
 India Greenhouse Horticulture Market | 2026-2036
India Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
India Greenhouse Horticulture Market Insights
Subscription-based climate management software is pivoting how Indian greenhouse operators procure technology, shifting capital expenditure into recurring operational contracts. Priva Holding BV leverages its sensor-to-cloud architecture to anchor premium positioning among large commercial growers in western India. Certhon competes through integrated project delivery that bundles Dutch engineering with local installation crews. Netafim Ltd. dominates precision irrigation retrofit sales, extending its drip legacy into fertigation automation for soil-based structures.
Greenhouse horticulture denotes the cultivation of vegetables, fruits, flowers, and herbs within enclosed structures where temperature, humidity, light, and CO2 levels are actively controlled, typically employing polyethylene or polycarbonate cladding over galvanized steel frames with pad-and-fan or natural ventilation systems. The primary purpose is to decouple agricultural output from monsoon dependency and extend growing seasons for high-value produce destined to urban wholesale markets and export channels. Vegetables command the largest product-type volume, though flowers generate superior per-square-meter margins through export rose and carnation shipments to West Asia and Europe. Hydroponics leads technology adoption among commercial growers seeking water-use efficiency in water-stressed districts of Gujarat and Telangana, while soil-based systems retain cost advantages for entry-level farmers transitioning from open-field cultivation.
BIS greenhouse structure standards and the Ministry of Agriculture's MIDH subsidy framework shape equipment eligibility and credit access for protected cultivation investments. State-level horticulture missions in Maharashtra, Karnataka, and Himachal Pradesh layer additional capital assistance atop central schemes, directing installation density toward their respective production clusters. The FSSAI residue monitoring protocol for greenhouse produce influences input choices, pushing growers toward biopesticide-integrated pest management to secure retailer offtake agreements. Stakeholders must weigh subsidy dependence against the operational flexibility required to serve contract buyers demanding traceability and year-round volume commitments.
Market Dynamics
Contracted sourcing from quick-service restaurant chains and organized retail is compressing procurement cycles for Indian greenhouse operators, forcing capital deployment toward climate-controlled infrastructure that can guarantee year-round volume commitments and residue-compliant traceability.
Growth Catalysts
- PLI scheme for horticulture:The Indian government's production-linked incentive framework channels capital into climate-controlled growing infrastructure, lowering effective equipment costs for commercial-scale entrants.
- Metro processor demand:Quick-service restaurant chains and organized retail are expanding contracted offtake agreements, pulling supply toward soilless cultivation facilities with documented input traceability.
- Hydroponics adoption:Water-stressed districts in Gujarat and Telangana are pivoting toward recirculating nutrient systems that slash irrigation requirements while lifting yield per hectare.
Market Restraints
- Capital intensity:Galvanized steel frames, polycarbonate cladding, and climate automation systems require substantial upfront investment that exceeds traditional open-field transition budgets.
- Subsidy dependence:MIDH framework eligibility criteria and disbursement timelines create cash-flow friction for growers awaiting central and state horticulture mission approvals.
- Skill scarcity:Integrated pest management and fertigation automation demand agronomy-engineering cross-training that remains scarce outside Nashik-Satara and Bengaluru-Mysuru production clusters.
Strategic Opportunities
- Himachal Pradesh expansion:State-level horticulture missions layer additional capital assistance atop central schemes, directing installation density toward underpenetrated mountain valleys with natural cooling advantages.
- Export rose corridors:West Asia and European carnation demand creates premium per-square-meter margins that justify controlled-atmosphere post-harvest infrastructure investment.
- Biopesticide integration:FSSAI residue monitoring protocols are pushing contract growers toward biocontrol-integrated systems that secure retailer offtake and price premiums.
Industry Challenges
- Certification timelines:FSSAI residue compliance and export phytosanitary clearance procedures create lag between harvest and market access that strains working capital.
- Integration complexity:Retrofitting drip-legacy soil-based structures with sensor-to-cloud fertigation automation requires field calibration expertise concentrated among Dutch-Indian project delivery teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Greenhouse Horticulture Market |
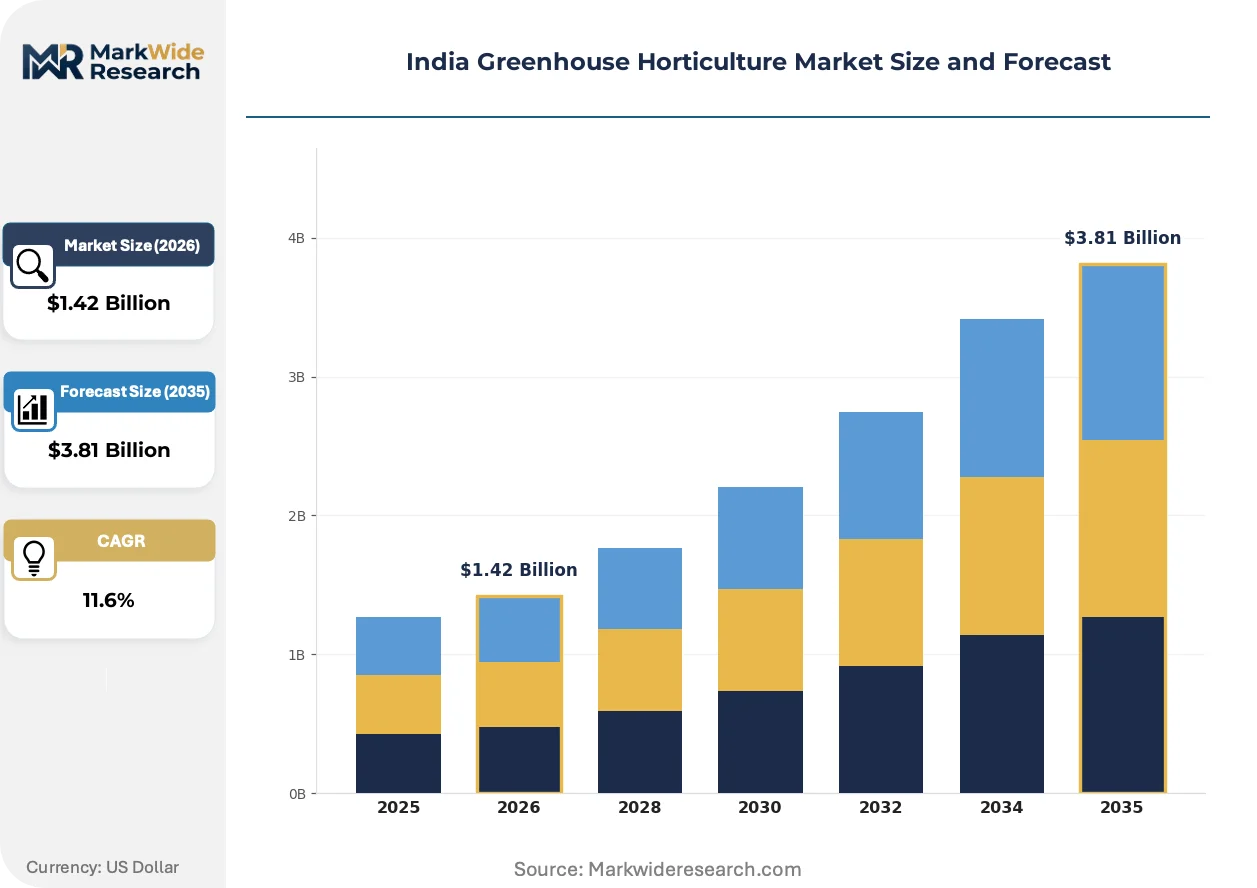
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Flowers, Herbs Technology: Hydroponics, Aeroponics, Soil-Based, Vertical Farming End User: Commercial Growers, Research Institutions, Retailers, Home Gardeners Distribution Channel: Wholesale, Direct Sales, Online, Retail Outlets |
| Companies Covered | Priva Holding BV, Certhon, Greentech Industries India Private Limited, Argus Control Systems, Dalsem B.V., Netafim Ltd., Richel Group, UrbanKisaan, Signify, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Greenhouse Horticulture Market Trends and Innovations
Sensor-to-cloud architecture is compressing the technology procurement model from capital expenditure toward recurring operational contracts, while regulatory pressure on residue limits and state-level capital assistance reshape competitive positioning.
LED supplemental lighting arrays with spectral tuning capabilities are electrifying year-round tomato and capsicum production in the Nashik-Satara belt. Large commercial growers in western India are deploying these systems to extend photoperiods beyond monsoon cloud cover, compressing the payback period for climate-controlled infrastructure through accelerated harvest cycles.
The Ministry of Agriculture's MIDH subsidy framework is tightening equipment eligibility criteria to favor domestic manufacturing content and BIS-certified greenhouse structures. This industrial consequence is redirecting procurement toward local fabricators of galvanized steel frames and pad-and-fan ventilation systems, particularly affecting Maharashtra and Karnataka growers who previously relied on imported Dutch engineering packages.
Quick-service restaurant chains are consolidating their vendor base toward a smaller cohort of greenhouse operators capable of delivering traceable, residue-compliant produce through twelve-month contracts. This buyer concentration is displacing spot-market wholesale transactions in the Bengaluru-Mysuru corridor, where organized retail now captures volume through direct sourcing agreements that specify input protocols and harvest scheduling.
India Greenhouse Horticulture Market Segmentation
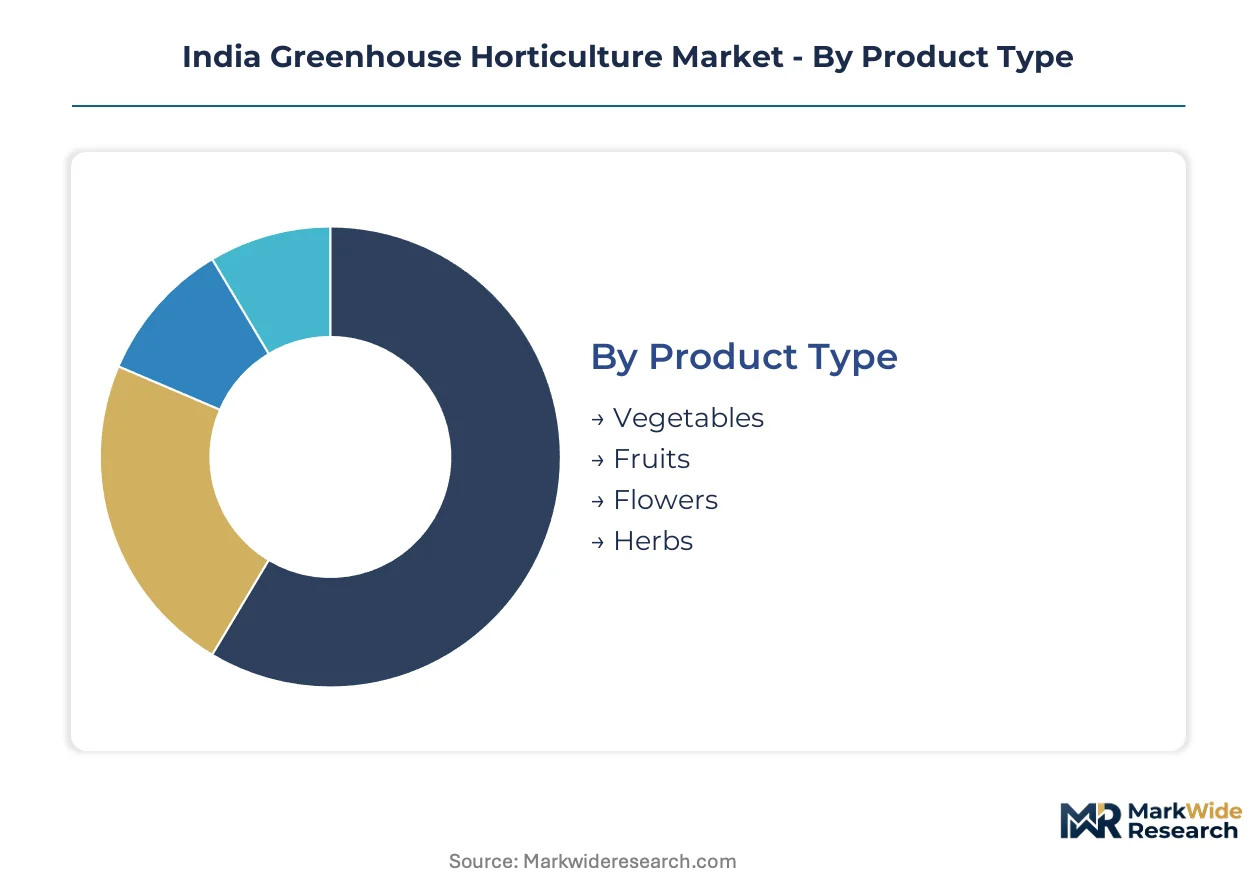
Greenhouse horticulture operators in India select product-technology combinations based on water availability, power reliability, and offtake contract terms. Segmentation choices directly determine capital recovery timelines and eligibility for MIDH subsidy tranches.
Product Type:
Capital intensity varies sharply across crop categories, with climate-controlled flower infrastructure requiring the highest per-square-meter investment due to post-harvest cold chain requirements.
- Vegetables:Tomato, capsicum, and cucumber dominate installed acreage under polyhouse structures. Nashik-Satara belt growers supply year-round to quick-service restaurant chains through contracted volume commitments.
- Flowers:Rose and carnation production commands premium per-square-meter margins through export shipments to West Asia and Europe. Controlled-atmosphere post-harvest infrastructure adds substantial capital burden.
- Fruits:Strawberry and exotic cultivars occupy niche greenhouse acreage in Himachal Pradesh and Karnataka. Limited domestic off-season supply supports price premiums over open-field harvests.
- Herbs:Basil, oregano, and exotic leafy greens serve organized retail and food processing contracts. Shorter crop cycles reduce working capital lock-up compared to woody perennials.
Most installed capacity flows through Vegetables. Expansion is steepest in Flowers as export corridors mature.
Technology:
Water-stressed districts in Gujarat and Telangana are pivoting toward recirculating systems that slash irrigation requirements while lifting yield density.
- Hydroponics:Nutrient film technique and deep water culture systems eliminate soil-borne pathogens while reducing water use by over sixty percent compared to flood irrigation. Commercial growers in water-scarce regions favor this technology for residue-compliant tomato and capsicum production.
- Soil-Based:Raised bed cultivation with drip-fertigation retains cost advantages for entry-level farmers transitioning from open-field methods. MIDH subsidies prioritize these structures for smallholder adoption targets.
- Aeroponics:Mist-based root delivery enables highest yield per cubic meter for leafy greens and herbs. Capital and technical complexity restrict deployment to research institutions and premium commercial operations.
- Vertical Farming:Stacked hydroponic layers with LED supplementation maximize production per land footprint. Urban peri-urban projects near Bengaluru and Hyderabad experiment with this model for hyperlocal retail supply.
Soil-Based structures retain the largest installed base. Hydroponics is gaining share fastest as water stress intensifies across western India.
End User:
Contract security and scale requirements segment the buyer base between integrated commercial operations and fragmented household cultivation.
- Commercial Growers:Large polyhouse operators with ten-plus acre deployments anchor supply to organized retail and quick-service restaurant chains. These entities capture MIDH subsidies and state horticulture mission capital assistance.
- Research Institutions:ICAR centers and state agricultural universities pilot climate-resilient cultivars and input protocols. Their procurement prioritizes sensor-to-cloud monitoring infrastructure over yield maximization.
- Retailers:Organized retail chains are backward-integrating into captive greenhouse production to secure traceable, residue-compliant produce. Direct sourcing agreements specify input protocols and harvest scheduling.
- Home Gardeners:Hobby-scale polyhouse kits serve urban consumers seeking pesticide-free vegetables. Online channels and horticulture extension centers drive penetration in metro peripheries.
Commercial Growers deploy the greatest capital stock. Retailers are expanding their greenhouse footprint most aggressively through vertical integration.
Distribution Channel:
Channel selection determines working capital cycles and traceability documentation requirements for residue compliance.
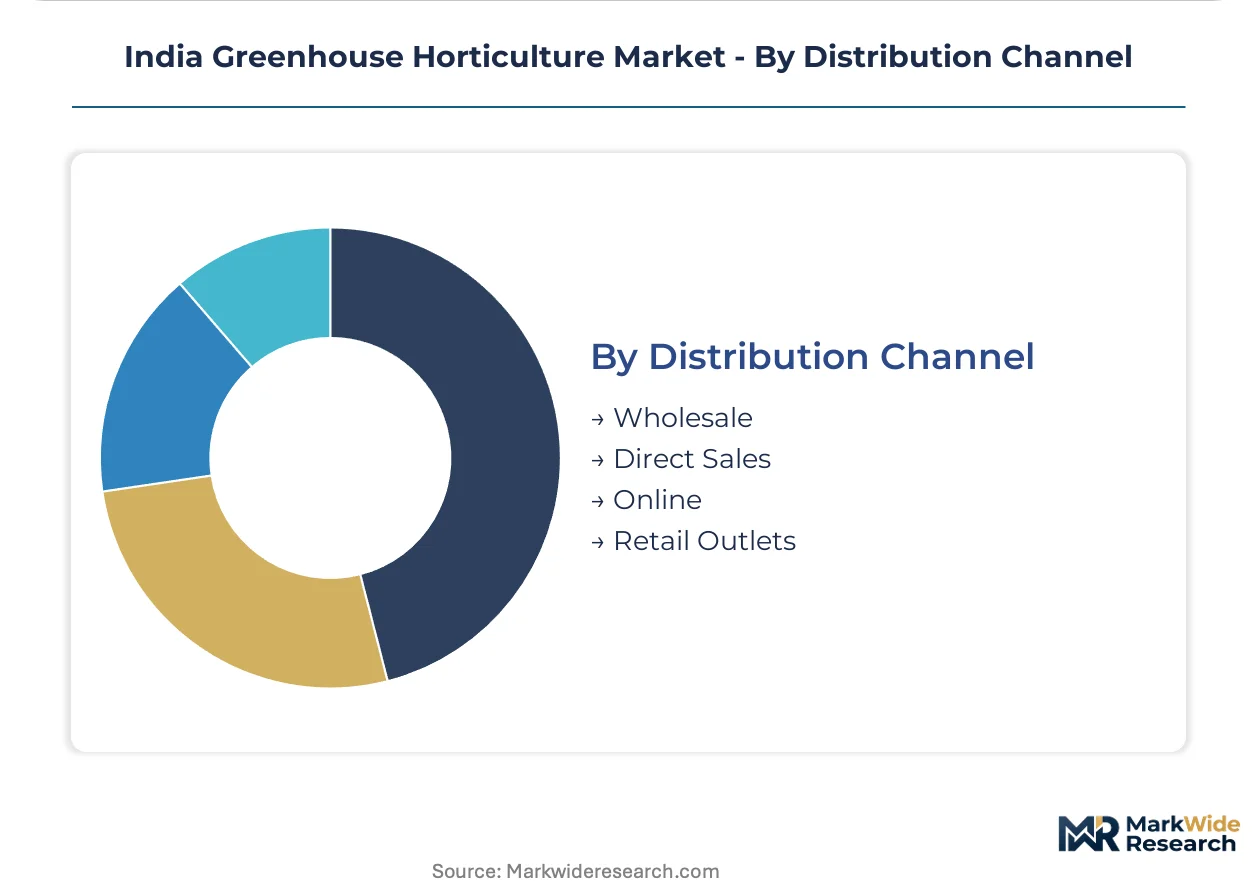
- Wholesale:Traditional commission agents and mandi intermediaries handle spot-market volume from small and mid-scale growers. Price volatility and payment delays characterize this channel.
- Direct Sales:Contracted offtake agreements with quick-service restaurant chains and organized retail specify volume, quality, and input protocols. These arrangements compress procurement cycles and reduce price risk.
- Online:Agritech platforms and B2B marketplaces connect greenhouse operators with institutional buyers. Digital traceability tools satisfy FSSAI residue monitoring requirements for premium segments.
- Retail Outlets:Branded greenhouse produce sections in modern trade formats command shelf-space premiums. Cold chain integrity from farm to store remains a constraint outside metro corridors.
Wholesale channels move the greatest volume. Direct Sales is expanding most quickly as buyer consolidation accelerates contracted sourcing arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's greenhouse horticulture infrastructure outpaces neighboring Bangladesh and Sri Lanka in installed polyhouse acreage, yet lags China's mechanized protected cultivation density by a significant margin. State-level subsidy layering and natural climate advantages create distinct regional competitive profiles across the subcontinent.
Maharashtra
Nashik-Satara belt tomato and capsicum growers supply year-round volumes to quick-service restaurant chains through contracted offtake agreements. The state's horticulture mission layers capital assistance atop MIDH subsidies, directing installation density toward the Western Ghats foothills where natural ventilation reduces cooling loads.
Karnataka
Bengaluru-Mysuru corridor rose and carnation producers anchor export shipments to West Asia through controlled-atmosphere post-harvest infrastructure. FSSAI residue monitoring protocols push contract growers toward biopesticide-integrated systems that secure retailer price premiums.
Gujarat
Water-stressed districts in Saurashtra and Kutch pivot toward hydroponic nutrient film technique systems that slash irrigation requirements by over sixty percent. State horticulture missions prioritize drip-legacy retrofits for smallholder transition from open-field cultivation.
Telangana
Hyderabad-Rangareddy peri-urban projects experiment with vertical farming stacked hydroponic layers for hyperlocal retail supply. The state's capital assistance framework targets recirculating systems in groundwater-depleted mandals where traditional flood irrigation faces regulatory pressure.
Himachal Pradesh
Mountain valleys around Solan and Shimla leverage natural cooling advantages for strawberry and exotic cultivar production. State-level horticulture missions channel subsidy density toward underpenetrated high-altitude clusters with limited monsoon dependency.
India Greenhouse Horticulture Market Competitive Landscape
Top-tier vendors anchor premium climate automation and integrated project delivery, while mid-scale fabricators compete on galvanized steel frame cost and local installation speed. The vendor base stratifies across three archetypes: Dutch engineering integrators bundling sensor-to-cloud architecture, Israeli precision irrigation specialists extending drip legacy into fertigation automation, and domestic fabricators capturing MIDH subsidy eligibility through BIS-certified structures. Competitive moves concentrate on backward integration into captive greenhouse production and technology licensing partnerships that transfer Dutch engineering protocols to Indian installation crews.
Within the Dutch engineering integrator tier, Priva Holding BV and Certhon occupy positions exemplifying sensor-to-cloud climate management and bundled project delivery archetypes respectively. Netafim Ltd. anchors the precision irrigation specialist segment, representing the drip-to-automation extension model that dominates retrofit sales in water-stressed western districts.
| Leading Market Players |
|---|
| Priva Holding BV |
| Certhon |
| Greentech Industries India Private Limited |
| Argus Control Systems |
| Dalsem B.V. |
| Netafim Ltd. |
| Richel Group |
| UrbanKisaan |
| Signify |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between FSSAI residue-compliant contract supply and mandi-distributed spot produce generates divergent margin structures across the Indian greenhouse horticulture value chain. Premium-tier operators serving quick-service restaurant chains and organized retail command price premiums through documented input traceability and year-round volume commitments, while commodity-grade output flows through traditional wholesale channels with volatile spot pricing and extended payment cycles.
Pricing Analysis
Capacity additions in Maharashtra and Karnataka are reshaping price floors for greenhouse-grown tomatoes and capsicums as commercial-scale deployments accelerate. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-certified contract supply from state-subsidized smallholder output and unorganized mandi trade. Cost compression in the standard tier is intensifying because domestic fabricators of BIS-certified galvanized steel frames are undercutting Dutch-engineered system costs. Smallholder transitions from open-field cultivation exhibit highest price sensitivity, while integrated commercial growers serving export rose corridors demonstrate lowest sensitivity due to West Asia and European carnation demand premiums.
Supply Chain Analysis
Climate automation hardware supply rests on Dutch engineering integrators and Israeli precision irrigation specialists, with domestic BIS-certified fabricators gaining share through MIDH subsidy eligibility. Galvanized steel frames, polycarbonate cladding, and sensor-to-cloud monitoring systems draw from Netherlands, Israel, and India respectively. Single-source vulnerability concentrates in Dutch climate control software licensing, where Priva Holding BV and Certhon anchor premium positioning. Distribution runs through direct sales contracts with quick-service restaurant chains and organized retail, displacing traditional mandi intermediaries in the Bengaluru-Mysuru and Nashik-Satara corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India greenhouse horticulture market functions as a stable compounder, with government PLI scheme capital flows and contracted offtake expansion from quick-service restaurant chains providing durable demand visibility across the projection horizon.
For Market Incumbents: Acquire sensor-to-cloud fertigation automation capabilities to defend against Israeli precision irrigation specialists extending drip legacy into climate-controlled infrastructure. Deepen backward integration into captive rose and carnation production for West Asia export corridors, securing controlled-atmosphere post-harvest infrastructure that locks in premium per-square-meter margins. MIDH subsidy disbursement timeline compression represents a critical operational lever for working capital optimization. For New Entrants and Emerging Players: Launch via state horticulture mission partnerships in underpenetrated Himachal Pradesh mountain valleys, where natural cooling advantages reduce climate control energy costs. Target hydroponic nutrient film technique deployment in groundwater-depleted Telangana mandals facing regulatory pressure on flood irrigation. Biopesticide-integrated pest management systems offer the most penetrable technology angle for securing retailer offtake agreements under FSSAI residue monitoring protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where state-level capital assistance programs concentrate installation density around production clusters lacking integrated project delivery capabilities. Mid-scale domestic fabricators with BIS certification and established installation crews in Maharashtra and Karnataka represent prime acquisition targets. Watch for PLI scheme disbursement acceleration as the inflection signal for commercial-scale capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Production | Organized retail chains secure traceable supply through direct greenhouse ownership in peri-urban Bengaluru corridors. |
| Technology Licensing Partnership | Dutch engineering protocols transfer to Indian installation crews through Certhon-style bundled project delivery models. |
| State Horticulture Mission Alignment | Capital assistance layering atop MIDH subsidies directs installation density toward Himachal Pradesh high-altitude clusters. |
| Biopesticide-Integrated System Deployment | FSSAI residue compliance secures quick-service restaurant chain offtake agreements with documented input traceability. |
| Export Cold Chain Infrastructure Investment | Controlled-atmosphere post-harvest systems enable West Asia and European carnation shipments from Karnataka growers. |
Research Methodology
Bottom-up commercial grower deployment modeling reconciled against top-down MIDH subsidy disbursement tracking forms the analytical core of this study. Primary interviews with greenhouse operators, state horticulture mission officers, quick-service restaurant chain procurement heads, and Dutch-Indian project delivery teams combined with secondary validation from BIS certification records, FSSAI residue monitoring protocols, and state agricultural department subsidy ledgers. Trade data on galvanized steel frame imports and polycarbonate cladding shipments supplemented domestic fabrication capacity estimates across Maharashtra and Karnataka production clusters.
Historical trendline analysis of installed polyhouse acreage by crop category and technology type established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, technology adoption, end-user archetype, and distribution channel dimensions with specific attention to hydroponics penetration rates in water-stressed districts. CAGRs derived from slope analysis of subsidy-driven capacity additions and contracted offtake expansion from organized retail backward-integration initiatives. Climate automation hardware procurement cycles and state-level capital assistance program rollout schedules served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including monsoon severity variability affecting open-field competitor supply, abrupt FSSAI residue limit tightening, and PLI scheme horticulture allocation modifications. Forecasts reflect assumptions on subsidy disbursement efficiency and Dutch-Indian technology transfer velocity. A small set of named triggers warrants ongoing watch: groundwater regulation enforcement in Gujarat and Telangana, quick-service restaurant chain vendor consolidation pace, and export phytosanitary clearance timeline compression for European rose shipments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Acorn Squash Market
Vegetables
Carrots and Turnips Market
Vegetables
Vegetable Grader Market
Vegetables
Hydroponic Vegetable Market
Vegetables
UAE Tomato Market
Vegetables
Sprouts Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Tomato Market
Vegetables
Fresh Mushroom Market
Vegetables
IQF Vegetables Market
Vegetables
Sweet Potatoes Market
Vegetables
Global Indoor Plant Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Asia-Pacific Peas Market