
 Turkey Greenhouse Horticulture Market | 2026-2036
Turkey Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Greenhouse Horticulture Market Insights
Good Agricultural Practice (GAP) certification is bifurcating the Turkey greenhouse horticulture competitive landscape into export-qualified and domestic-only tiers. NETAFIM leverages its precision irrigation technology to anchor premium vegetable contracts with European retailers. Dalsem B.V. sustains its position through integrated greenhouse engineering and climate control systems tailored to Mediterranean conditions. Hextech Green Machinery differentiates via automated transplanting and harvesting equipment designed for high-density tomato operations.
Turkey greenhouse horticulture encompasses controlled-environment agriculture using soil-based, hydroponic, aeroponic, and vertical farming systems to produce vegetables, fruits, flowers, and herbs under protective structures, typically employing polyethylene or glass coverings with active climate management to achieve yields per hectare three to five times above open-field cultivation. The primary commercial purpose centers on supplying consistent, quality-graded produce to supermarket chains, export markets, and foodservice distributors regardless of seasonal constraints. Vegetables dominate current output value, with tomatoes and peppers generating the deepest margin pools due to established cold-chain logistics and EU import familiarity. Hydroponics represents the fastest-expanding technology segment as water scarcity intensifies across the Aegean and Mediterranean basins, while soil-based systems retain volume leadership in older Antalya installations where capital retrofitting remains uneconomic.
Turkish Ministry of Agriculture and Forestry irrigation quotas, combined with BSI-equivalent quality standards for export eligibility, compel growers toward water-recycling hydroponics and traceable input documentation. The national agricultural bank's subsidized credit lines for modern greenhouse construction accelerate technology substitution in the Marmara and Mediterranean zones. Stakeholders must monitor evolving Russian phytosanitary border protocols and EU deforestation regulation traceability requirements, as these external compliance gates will determine which Turkish growing regions retain competitive access to premium offtake contracts.
Market Dynamics
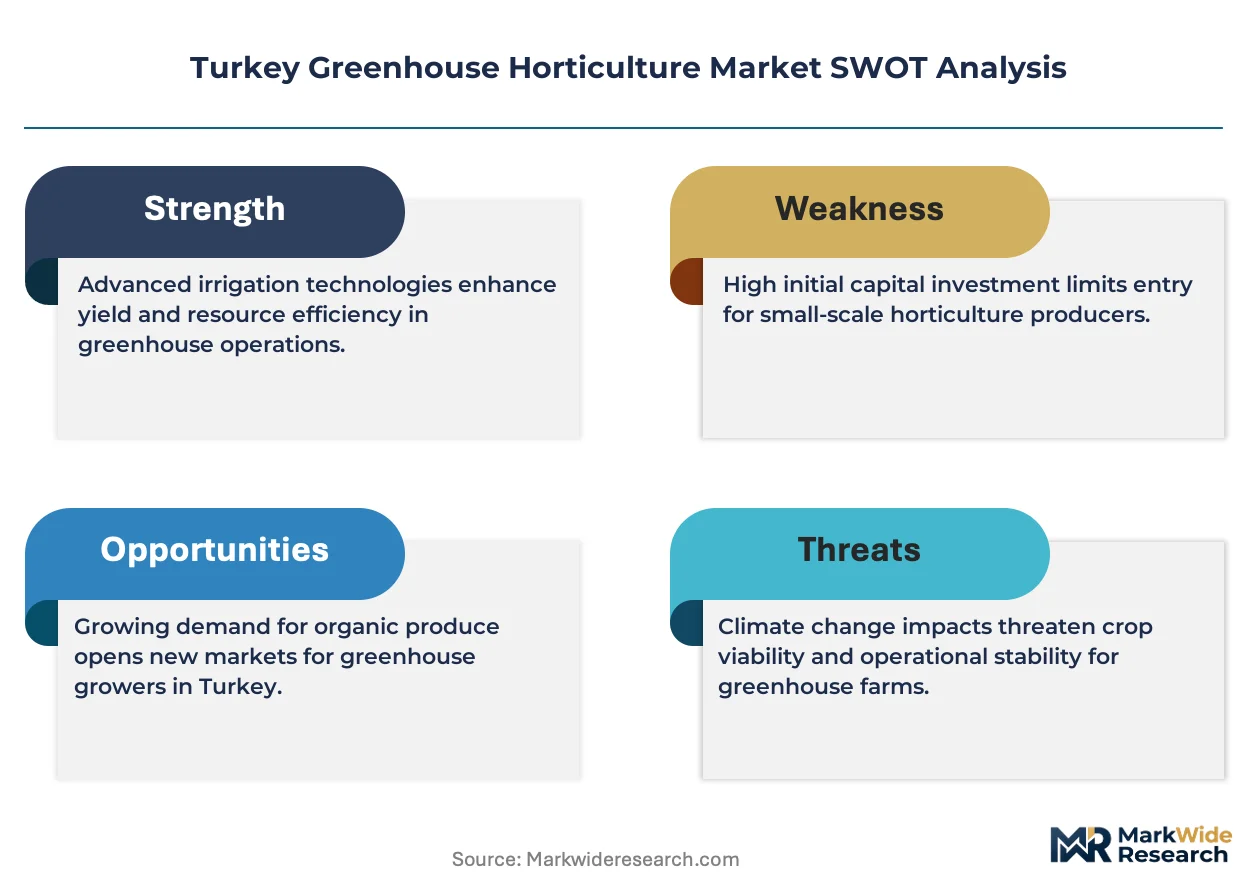
Water scarcity across Turkey's Aegean and Mediterranean basins is forcing accelerated conversion from soil-based cultivation to closed-loop hydroponic systems, reshaping capital allocation and technology vendor relationships throughout the Antalya-Alanya corridor.
Growth Catalysts
- Turkish Ministry of Agriculture and Forestry irrigation quotas:These restrictions on open-field water permits redirect investment toward soilless greenhouse systems with recycling capabilities.
- EU deforestation regulation traceability requirements:Compliance mandates are pushing Turkish exporters toward documented input chains that favor controlled-environment operations over open-field sourcing.
- Antalya-Alanya corridor cold-chain infrastructure:Established logistics networks for tomato and pepper exports to Russia enable year-round revenue capture that justifies greenhouse expansion.
Market Restraints
- Capital intensity of hydroponic retrofitting:Older polyethylene installations in coastal zones face prohibitive replacement costs for water-recycling infrastructure.
- Phytosanitary protocol uncertainty:Russian border inspection regimes create unpredictable shipment rejections that disrupt cash flow planning for export-oriented operators.
- Energy price volatility:Climate control and supplemental lighting systems expose growers to electricity cost swings that compress margins during winter production cycles.
Strategic Opportunities
- Eastern Anatolia high-altitude production:Cooler summer temperatures in Erzurum and Kars provinces enable natural ventilation greenhouses that reduce cooling energy for leafy greens.
- Good Agricultural Practice certification tiering:GAP-qualified growers capture premium supermarket contracts that domestic-only operators cannot access.
- Integrated pest management automation:Convergence of computer vision and robotic spraying systems reduces labor dependency while satisfying EU residue limits.
Industry Challenges
- Hydroponic nutrient management expertise:Shortage of technicians trained in closed-loop water chemistry creates operational risk during crop transitions.
- Legacy soil-based system integration:Mixed farms struggle to maintain parallel cultivation methods without cross-contamination of soil-borne pathogens into hydroponic zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Greenhouse Horticulture Market |
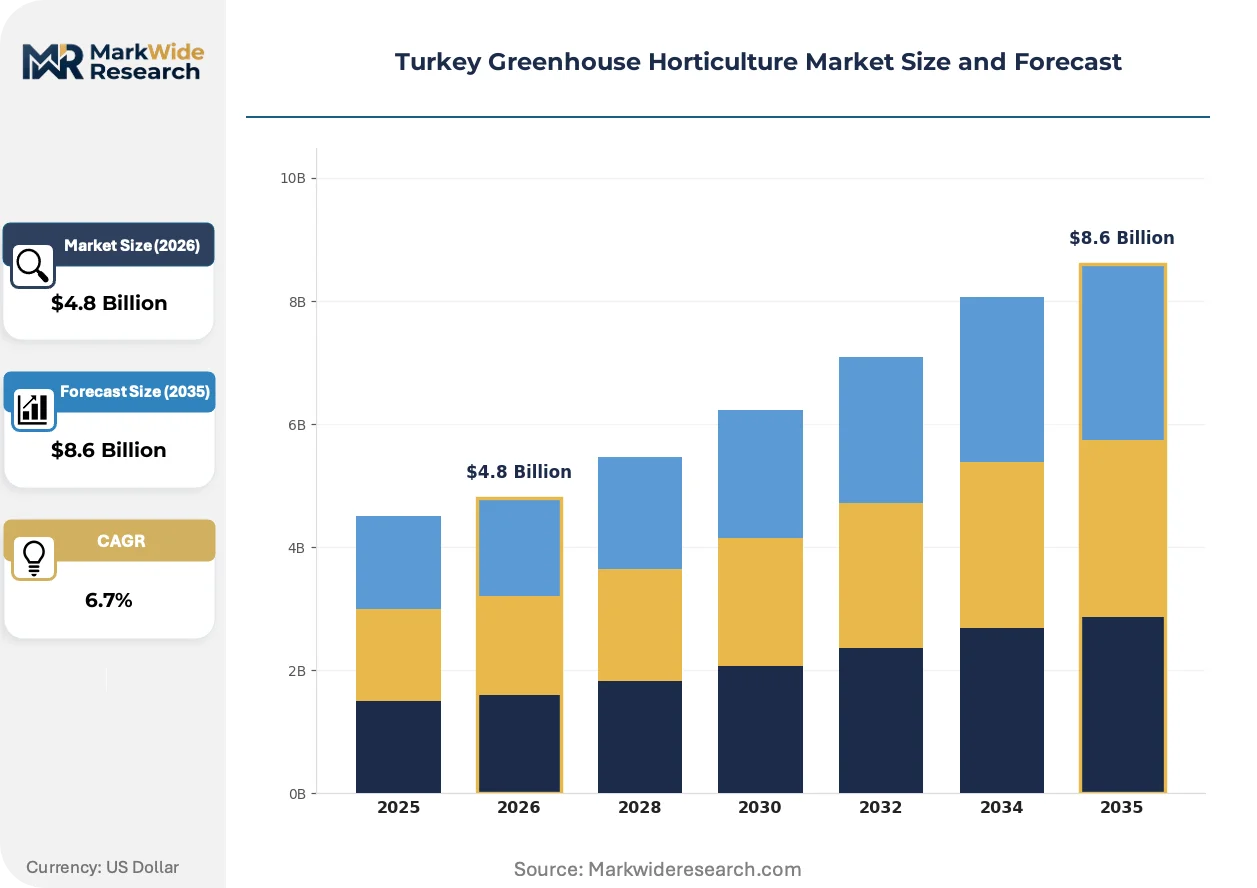
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Flowers, Herbs Technology: Hydroponics, Aeroponics, Soil-based, Vertical Farming End User: Commercial Growers, Retailers, Exporters, Research Institutions Distribution Channel: Direct Sales, Online Retail, Wholesale, Local Markets |
| Companies Covered | Hextech Green Machinery, Dalsem B.V., W Agro Park, NETAFIM, Certhon B.V., Batman Greenhouse OTB, Crop Genius Agriculture, Richel Group SA, Solis Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Greenhouse Horticulture Market Trends and Innovations
Technology substitution and compliance architecture are reconfiguring competitive advantage in Turkish greenhouse operations. Automation, regulatory alignment, and buyer consolidation are compressing traditional operational models.
Closed-loop nutrient film technique systems are displacing conventional drip-irrigation setups in Antalya tomato operations. Large export-oriented growers are adopting these configurations to meet EU water-efficiency audits. The technology is displacing older flood-and-drain methods that cannot demonstrate recycling ratios required by European retail procurement standards.
Turkish Ministry of Agriculture and Forestry has tightened documentation requirements for plant protection product applications in export-bound operations. This regulatory pressure forces growers toward integrated pest management and biological control agents. Soilless operations in the Mediterranean zone are most affected, responding with sensor-based monitoring systems that generate audit trails for EU deforestation regulation compliance.
Supermarket chain consolidation is compressing supplier counts and extending contract durations with traceability requirements. Migros and CarrefourSA are replacing spot-market purchasing with multi-year agreements that specify cultivation protocols. This pattern is most visible in pepper and tomato categories where three chains now control over sixty percent of domestic retail offtake.
Turkey Greenhouse Horticulture Market Segmentation
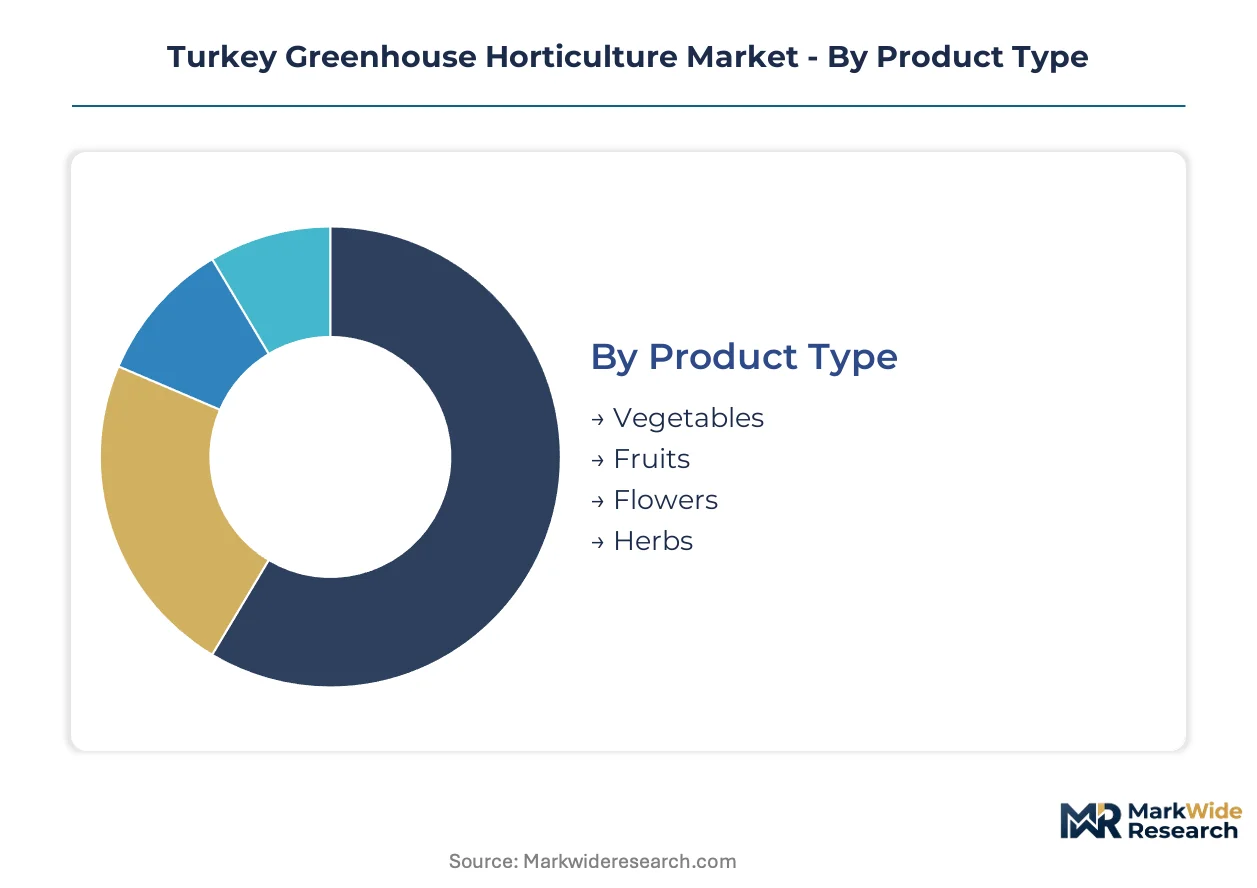
Segmentation in Turkey's greenhouse horticulture market reveals how regulatory pressure and export compliance are restructuring production decisions. Each dimension—product, technology, end user, and channel—carries distinct margin implications and capital requirements that determine competitive viability.
Product Type:
Channel flow varies sharply by crop: vegetables dominate supermarket contract volumes, while flowers and herbs concentrate in direct wholesale and export channels with stricter phytosanitary documentation.
- Vegetables:Tomatoes and peppers constitute the core revenue base, with standardized grading systems enabling seamless integration into Migros and CarrefourSA procurement networks. Antalya-Alanya corridor operations supply year-round volumes to Russian and EU markets through established cold-chain infrastructure.
- Fruits:Strawberries and melons command premium positioning in export channels, though shorter shelf lives restrict distribution to air-freight routes and high-turnover retail partnerships.
- Flowers:Ornamental production clusters near Istanbul and Izmir for domestic event markets, with limited export penetration due to perishability constraints and Dutch competition.
- Herbs:Basil, mint, and oregano serve foodservice distributors and ethnic grocery networks, with demand concentrating in urban centers and Middle Eastern export corridors.
By volume, vegetables lead. By growth pace, herbs are expanding most quickly as foodservice traceability requirements favor controlled-environment sourcing.
Technology:
Cost tier stratification separates capital-intensive hydroponic installations from legacy polyethylene operations, with technology choice directly determining water permit eligibility and export market access.
- Hydroponics:Closed-loop nutrient film technique systems dominate new Antalya investments, recycling ratios exceeding 90% satisfy Turkish Ministry of Agriculture and Forestry audits and EU water-efficiency standards. These configurations anchor premium vegetable contracts with European retailers.
- Soil-based:Older polyethylene installations in coastal zones retain volume leadership where retrofit capital is unavailable, though irrigation quota restrictions progressively constrain expansion permits.
- Aeroponics:High-density root-mist systems remain niche, deployed primarily for seedling propagation and research institution trials rather than commercial-scale production.
- Vertical Farming:Stacked-layer installations concentrate in Istanbul periphery for leafy greens, leveraging proximity to dense urban demand while avoiding land cost pressures of horizontal expansion.
By installed area, soil-based systems retain dominance. By investment flow, hydroponics is gaining share fastest as regulatory pressure accelerates technology substitution.
End User:
Customer type determines contract structure and compliance burden, with exporters and retailers imposing the most stringent cultivation protocol requirements.
- Commercial Growers:Large-scale Antalya operations supply standardized volumes to supermarket chains, absorbing GAP certification costs and multi-year contract obligations in exchange for price stability.
- Retailers:Migros and CarrefourSA consolidation is compressing supplier counts, with procurement teams specifying irrigation methods, residue limits, and traceability documentation that exclude smaller domestic-only operators.
- Exporters:Russian and EU-bound shipments require BSI-equivalent quality standards and deforestation regulation compliance, filtering supply toward hydroponic operations with documented input chains.
- Research Institutions:Universities and agricultural extension services pilot varietal development and IPM automation, though commercialization timelines limit near-term market impact.
By revenue concentration, commercial growers lead. By contract value growth, exporters are climbing the fastest as premium offtake agreements expand.
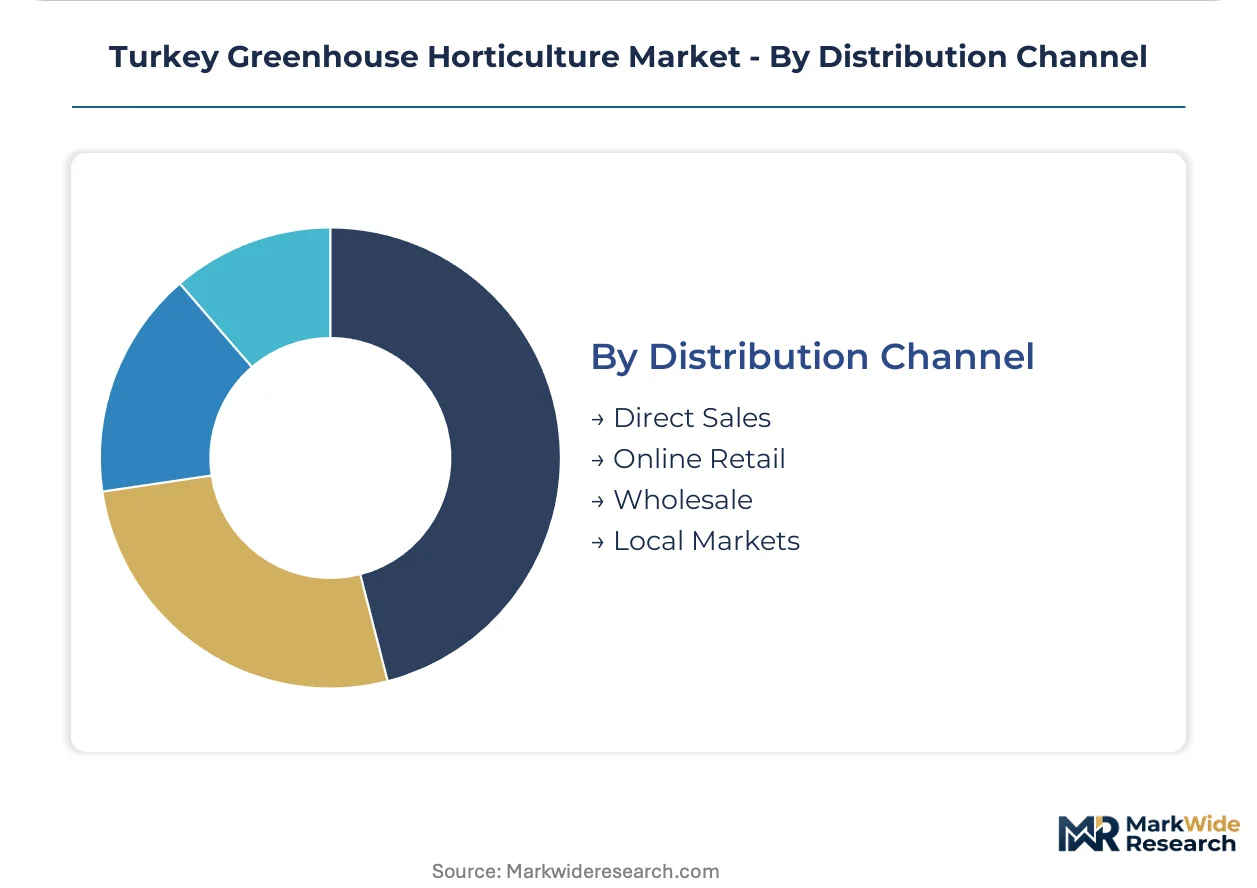
Distribution Channel:
Channel maturity reflects infrastructure investment patterns, with direct sales and wholesale retaining dominance while online retail builds share in urban fresh produce delivery.
- Direct Sales:Large growers bypass intermediaries for supermarket and foodservice contracts, capturing margin that wholesale networks previously absorbed while maintaining quality accountability.
- Wholesale:Antalya-based aggregators consolidate smallholder volumes for Russian export markets, though phytosanitary rejection risk concentrates financial exposure among these intermediaries.
- Online Retail:Istanbul-focused platforms deliver packaged herbs and specialty vegetables to urban consumers, growth constrained by last-mile cold-chain gaps outside major metropolitan zones.
- Local Markets:Municipal bazaars and neighborhood grocers handle non-certified domestic produce, serving price-sensitive consumers excluded from supermarket tiering.
By transaction volume, wholesale leads. By expansion trajectory, direct sales is gaining share fastest as buyer consolidation extends contract durations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mersin International Port anchors Turkey's greenhouse export corridor, handling refrigerated container volumes for Antalya-grown tomatoes and peppers bound for Russian and EU markets. Cold-chain rail links connect the Mediterranean production zone to Istanbul's air-freight hubs, enabling perishable distribution to Middle Eastern destinations.
Mediterranean Region
Antalya and Alanya concentrate year-round tomato and pepper cultivation for export markets. The Turkish Ministry of Agriculture and Forestry enforces irrigation quotas that redirect investment toward soilless greenhouse systems. Alanya-based operators are retrofitting polyethylene installations with closed-loop hydroponics to secure water-use permits.
Aegean Region
Izmir and Aydın provinces supply domestic supermarket chains with leafy greens and herbs. The national agricultural regulator's traceability documentation requirements favor controlled-environment operations over open-field sourcing. Torbalı district clusters automated transplanting facilities serving Migros procurement networks.
Marmara Region
Istanbul periphery vertical farms address urban demand for packaged herbs and specialty vegetables. The national agricultural bank's subsidized credit lines accelerate modern greenhouse construction in Tekirdağ and Kocaeli. Silivri sub-region hosts stacked-layer installations leveraging proximity to dense metropolitan offtake.
Central Anatolia Region
Konya and Ankara provinces develop soil-based greenhouse capacity for domestic winter vegetable supply. Turkish Ministry of Agriculture and Forestry GAP certification programs tier producers into export-eligible and domestic-only categories. Konya's Karatay district expands pepper cultivation for Ankara foodservice distributors.
Eastern Anatolia Region
Erzurum and Kars provinces exploit high-altitude cooler summers for natural ventilation greenhouse operations. The national agricultural bank extends preferential lending for energy-efficient structures in underserved zones. Erzurum's Aziziye district pilots leafy green production reducing cooling energy requirements.
Turkey Greenhouse Horticulture Market Competitive Landscape
Listed leaders compete with private specialists across irrigation technology and greenhouse engineering segments. The vendor base fragments across precision equipment suppliers, integrated system builders, and regional machinery fabricators. Two archetypes dominate: Israeli-Dutch irrigation technology licensors and Turkish-Benelux integrated greenhouse constructors. Competitive moves center on multi-year service contracts and technology licensing arrangements rather than asset-heavy consolidation.
Among precision irrigation specialists, NETAFIM anchors the technology-licensing tier for Mediterranean climate operations. Dalsem B.V. and Certhon B.V. occupy positions within the integrated greenhouse engineering segment, representing Benelux-origin system builders. Hextech Green Machinery exemplifies the automated equipment fabrication archetype. These three entities collectively span the critical technology vectors—irrigation, structural engineering, and mechanization—that determine competitive access to supermarket contract tiers.
| Leading Market Players |
|---|
| Hextech Green Machinery |
| Dalsem B.V. |
| W Agro Park |
| NETAFIM |
| Certhon B.V. |
| Batman Greenhouse OTB |
| Crop Genius Agriculture |
| Richel Group SA |
| Solis Technology |
| Others |
Pricing and Supply Chain Analysis
Closed-loop hydroponic nutrient film technique systems replacing conventional drip-irrigation setups in Antalya tomato operations simultaneously concentrate supply geography around Mediterranean basin technology vendors and compress pricing economics for legacy soil-based growers unable to meet EU water-efficiency audit standards.
Pricing Analysis
Volume-discount tiering structures dominate Turkish greenhouse horticulture procurement, with Migros and CarrefourSA extracting scaled rebates from large Antalya-Alanya corridor operators. Price differentiation hinges on Good Agricultural Practice certification status and cold-chain delivery radius to export ports. Pricing pressure intensifies in domestic-only tiers as supermarket consolidation compresses supplier margins. Export-qualified growers with EU deforestation regulation documentation command premium positioning, while uncertified smallholders face acute price sensitivity in municipal bazaar channels.
Supply Chain Analysis
Mersin International Port chokepoints govern Turkish greenhouse export velocity, with refrigerated container availability constraining peak-season tomato and pepper shipments to Russian markets. Supply geography centers on Netherlands-origin greenhouse engineering, Israeli precision irrigation technology, and domestic polyethylene fabrication. Raw material dependencies span specialty fertilizer formulations, climate control equipment, and phytosanitary-compliant packaging. Single-source vulnerability concentrates in European retailer certification audit services. Distribution runs through Antalya-based wholesale aggregators consolidating smallholder volumes for cross-border shipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in Turkish greenhouse horticulture as Migros, CarrefourSA, and BİM consolidate procurement teams, extending multi-year cultivation protocol contracts that exclude domestic-only operators from premium tier access.
For Market Incumbents: Secure multi-year service contracts with NETAFIM and Dalsem B.V. to lock in precision irrigation and integrated greenhouse engineering capabilities before technology licensing fees escalate. Invest in Good Agricultural Practice certification tiering to defend margin position against emerging hydroponic specialists in Eastern Anatolia. Channel control through direct supermarket relationships anchors pricing power as wholesale aggregators face phytosanitary rejection risk concentration. For New Entrants and Emerging Players: Post-harvest cold-chain service gaps in Eastern Anatolia present white-space targets where incumbent Antalya operators under-serve high-altitude natural ventilation greenhouse developers. The most penetrable segment sits with Erzurum and Kars province leafy green producers lacking established logistics partnerships. A go-to-market angle anchored in integrated pest management automation and sensor-based audit trail generation satisfies EU deforestation regulation compliance requirements that legacy operators struggle to document. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision agriculture technology licensors seeking Mediterranean climate application expansion. Long-term viability across the analysis window favors hydroponic infrastructure owners with water recycling ratios exceeding Turkish Ministry of Agriculture and Forestry audit thresholds. The signal to watch is Russian phytosanitary border protocol tightening, which would accelerate capital flight from export-dependent wholesale aggregators toward EU-certified direct contract growers.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Hydroponic Retrofit | Water recycling ratios above 90% satisfy Turkish Ministry of Agriculture and Forestry permits and EU retailer procurement standards. |
| Good Agricultural Practice Certification Investment | GAP-qualified growers access Migros and CarrefourSA multi-year contracts unavailable to domestic-only tier competitors. |
| Integrated Pest Management Automation Deployment | Computer vision and robotic spraying systems reduce labor dependency while meeting EU residue limit documentation requirements. |
| Eastern Anatolia High-Altitude Expansion | Natural ventilation greenhouses in Erzurum exploit cooler summers to reduce cooling energy costs for leafy green production. |
| Direct Retail Contract Structuring | Bypassing Antalya wholesale aggregators eliminates phytosanitary rejection risk concentration and captures intermediary margin. |
Research Methodology
The analysis maps hydroponic technology adoption, soil-based system retrofitting, and vertical farming deployment patterns, each validated through greenhouse operators, supermarket procurement managers, precision irrigation vendors, and agricultural bank lending officers. Primary interviews with Turkish Ministry of Agriculture and Forestry regional directors, NETAFIM technical specialists, and Migros category buyers combined with secondary validation against customs export records, national irrigation permit databases, and EU deforestation regulation compliance filings. Bottom-up installation capacity estimates triangulated against top-down supermarket procurement volume disclosures.
Consistency checks validated volume and value outputs against Turkish Ministry of Agriculture and Forestry greenhouse area statistics, Mersin International Port refrigerated container throughput, and EU import registration data for Turkish tomato and pepper shipments. Segmentation modeling spanned product type, technology configuration, end-user contract structure, and distribution channel maturity. CAGRs derived from weighted capacity expansion pipelines, regulatory permit issuance trajectories, and supermarket contract duration trends. Industry-specific forecast inputs incorporated water scarcity intensity indices and Russian phytosanitary inspection frequency patterns.
Forecasts assume regulatory continuity in Turkish Ministry of Agriculture and Forestry irrigation quota enforcement and EU deforestation regulation traceability requirements; material policy shifts in either regime would require re-modeling export market access assumptions. Practitioners should keep alternative scenarios live as Russian border inspection protocols and energy price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Sweet Potatoes Market
Vegetables
Global Mushroom Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Potato Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
North America Peas Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Fresh Mushroom Market
Vegetables
Qatar Greenhouse Market
Vegetables
North America Microgreens Market
Vegetables
Tomato Market
Vegetables
Europe Pea Market
Vegetables
Garlic Market
Vegetables
Dried Mushroom Market
Vegetables
Asparagus Market