
 Greenhouse Produce Market | 2026-2036
Greenhouse Produce Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse Produce Market Analysis
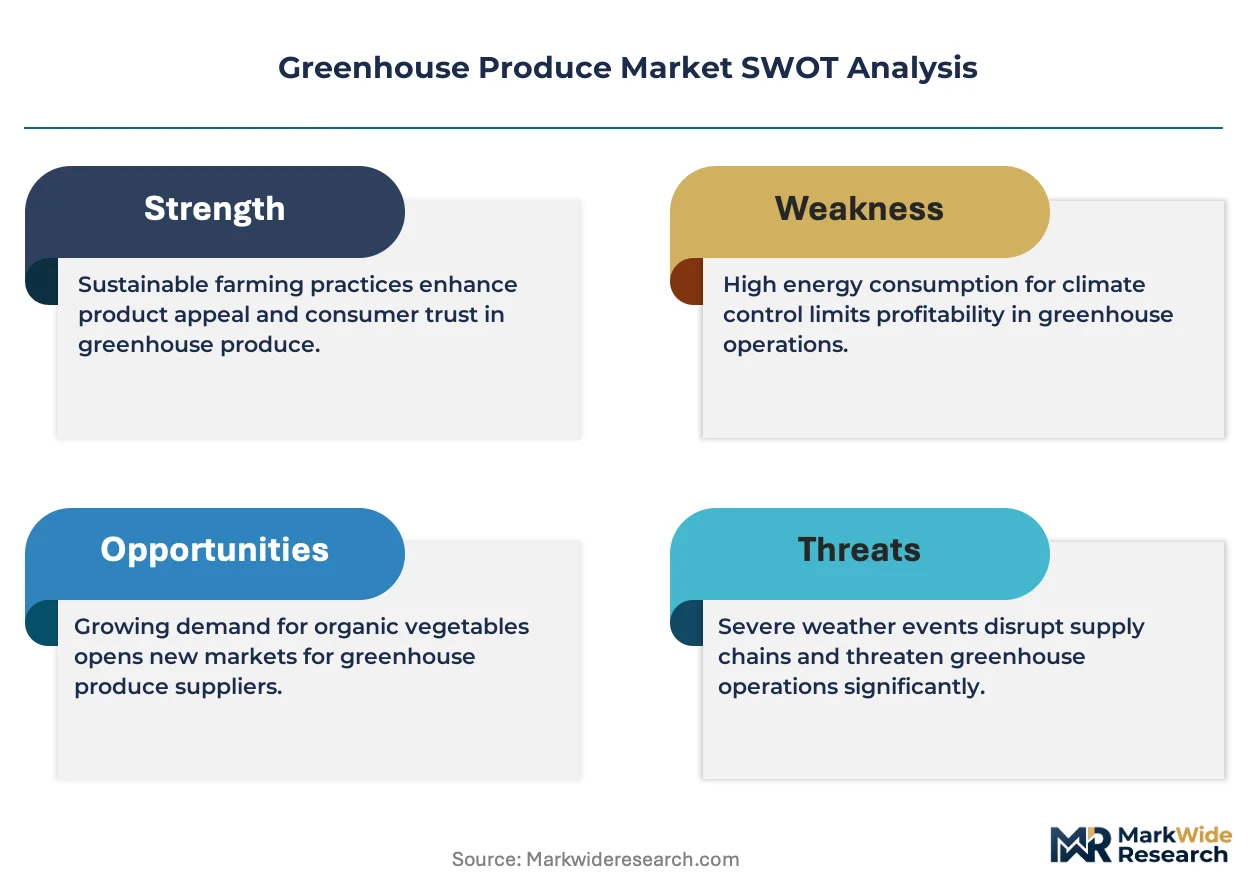
Greenhouse-as-a-service leasing and project finance structures is narrowing the capital barrier for new entrants across temperate-climate regions. Nature Fresh Farms leverages vertical integration from seed propagation through retail packing to control margin capture across the value chain. Mastronardi Produce anchors North American distribution through long-term supply agreements with major grocery banners. Houweling's Tomatoes specializes in large-scale glasshouse tomato production with combined heat and power systems that sustain energy cost advantages.
Greenhouse produce comprises vegetables and herbs cultivated within controlled-environment structures using transparent or semi-transparent cladding materials, typically maintaining interior temperatures between 18°C and 28°C through active climate management to enable year-round harvest cycles independent of external weather conditions. The primary commercial purpose is delivering consistent quality, predictable yield, and traceable origin to retail and foodservice buyers who require supply reliability. Tomatoes dominate product type revenue due to established consumer preference and longer shelf stability under controlled atmosphere, while lettuce categories compete fastest in direct-to-consumer channels where local-provenance messaging commands premium positioning. Hydroponics leads growing technique adoption for water-intensive crops, though soil-based systems sustain significant share in Mediterranean climates where natural light availability reduces supplemental energy requirements.
The EPA regulates agricultural runoff and pesticide application near greenhouse operations in the United States, while the EU Green Deal's Farm to Fork strategy imposes binding targets for chemical input reduction that reshape European cultivation protocols. BIS standards in India govern structural materials and cladding specifications for protected cultivation infrastructure, influencing import substitution patterns for domestic equipment suppliers. Stakeholders must monitor how evolving carbon border adjustment mechanisms and renewable energy certificate requirements alter the cost structure of heated versus unheated production systems across competing supply origins.
Market Dynamics
Foodservice operators from quick-service chains to institutional cafeterias are expanding contracted volume for year-round supply, concentrating purchasing power among buyers who prioritize traceability and climate-independent harvest cycles over spot-market sourcing.
Growth Catalysts
- EU F-Gas Regulation:The regulation accelerates the shift toward closed-loop hydroponic systems with lower refrigerant leakage, pushing growers toward energy-efficient climate control architectures.
- Foodservice contract expansion:Institutional cafeterias and quick-service chains are locking in multi-year supply agreements that guarantee volume and origin traceability.
- Dutch greenhouse clusters:Concentrated production around Rotterdam and Westland supplies Northern European retail through just-in-time logistics networks that compress delivery windows.
Market Restraints
- Natural gas price volatility:Combined heat and power systems depend on stable fuel input costs, and price spikes in European energy markets directly compress operating margins for heated glasshouse operations.
- Input concentration in propagation materials:Specialized seed genetics and young plant supply concentrate among a limited set of Dutch and Israeli breeders, creating supply vulnerability.
- Water access limitations:Hydroponic systems require consistent high-quality water inputs, and basin-level allocation restrictions in drought-prone regions constrain site selection.
Strategic Opportunities
- Greenhouse-as-a-service leasing:Project finance structures and operational leases are narrowing capital barriers for new entrants across temperate-climate regions where land and labor costs favor protected cultivation.
- Carbon border adjustment alignment:The EU carbon border adjustment mechanism creates competitive positioning for producers with verified renewable energy certificates and low-carbon heat sources.
- Direct-to-consumer channel expansion:Subscription box and farm-gate retail models capture premium positioning through local-provenance messaging that commands price separation from wholesale commodity channels.
Industry Challenges
- Climate engineering talent scarcity:The intersection of agronomy, HVAC engineering, and data analytics requires specialized skill sets that outpace vocational training program output in most producing regions.
- Integrated pest management certification timelines:Third-party audited protocols for residue-free production require 18-36 month conversion periods that delay market access for transitioning operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse Produce Market |
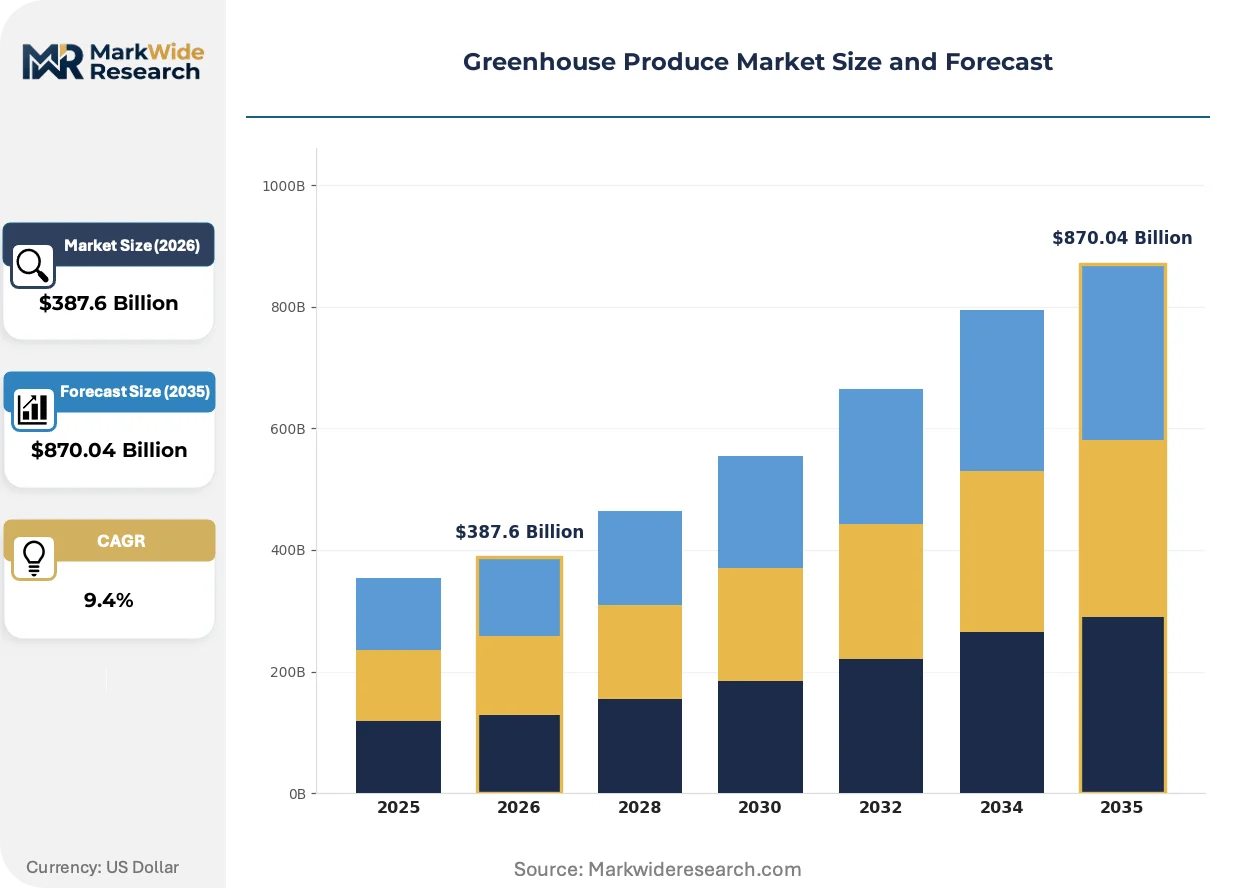
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $870.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomatoes, Lettuce, Peppers, Cucumbers Growing Technique: Hydroponics, Aeroponics, Soil-Based, Vertical Farming Distribution Channel: Wholesale, Retail, Direct-to-Consumer, Export Packaging Type: Clamshells, Bags, Boxes, Trays |
| Companies Covered | Nature Fresh Farms, Houweling's Tomatoes, Mastronardi Produce, Little Leaf Farms, BrightFarms, Windset Farms, Mucci Farms, Revol Greens, Village Farms International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse Produce Market Emerging Trajectories
Automation and environmental sensing technologies are compressing labor intensity while regulatory pressure on chemical inputs and carbon emissions is reshaping cultivation protocols across major producing regions.
Spectral imaging and computer vision systems for pest detection and yield forecasting are rendering obsolete manual scouting and experience-based harvest timing decisions. Large-scale glasshouse operators in the Netherlands and Canada are deploying these systems at commercial scale. The technology is compressing labor requirements per hectare while improving early intervention precision.
The EU Green Deal's Farm to Fork strategy imposes binding targets for chemical input reduction that reshape European cultivation protocols. Integrated biological control and precision dosing systems are replacing calendar-based spray schedules. Tomato and cucumber producers in Spain and Italy face the steepest compliance curves as they retrofit Mediterranean structures for closed-environment management.
Retail buyers are consolidating supplier lists and demanding unified data standards for origin, carbon footprint, and residue testing. Major grocery banners in Germany and the United Kingdom now require API-accessible traceability dashboards as a condition of listing. This supplier consolidation is most visible in Northern Europe, where three retail groups control over sixty percent of fresh produce shelf space.
Greenhouse Produce Market Segmentation
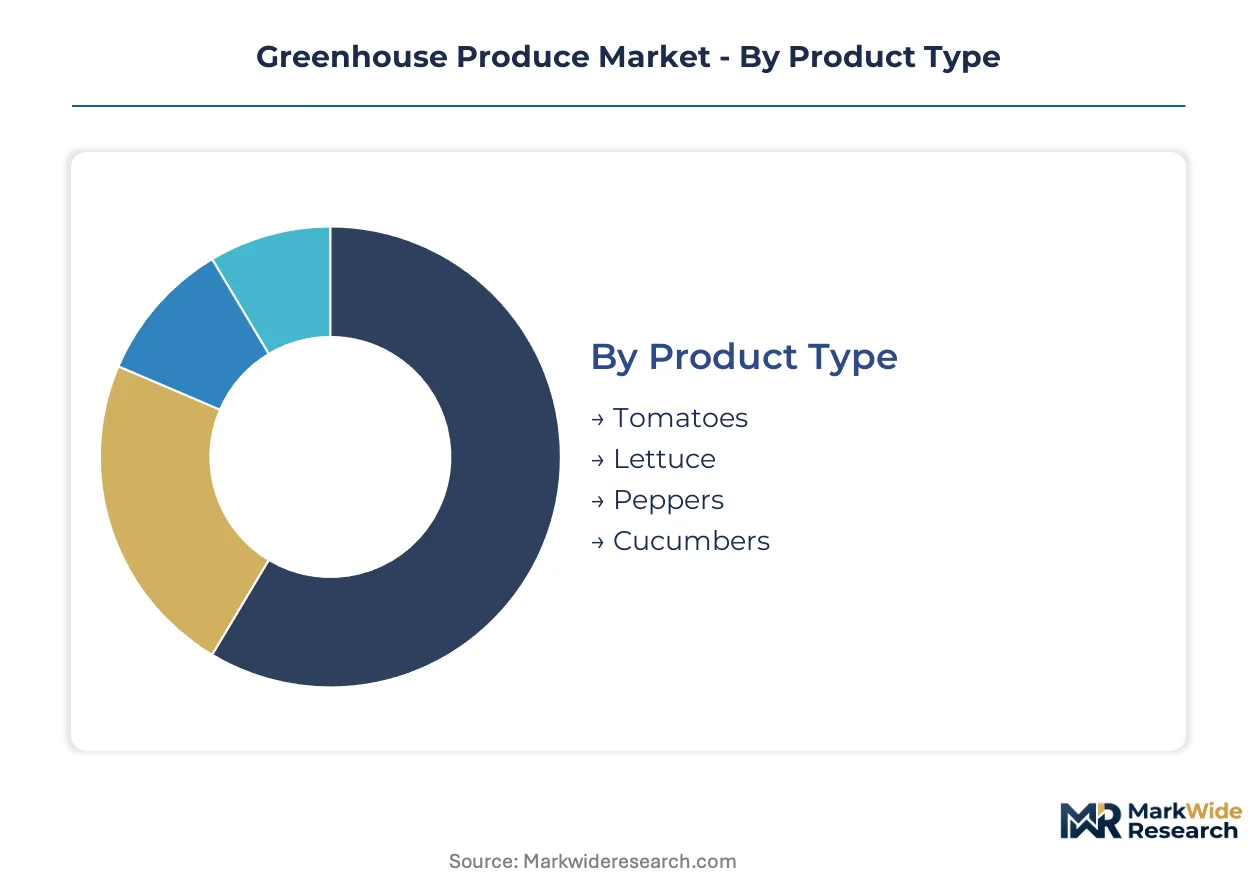
Segmentation in greenhouse produce reveals how cultivation methods, packaging formats, and channel strategies create distinct margin profiles. Each dimension carries different capital intensity, traceability requirements, and climate-control precision demands that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across crop categories, with vine crops requiring sustained technical support for climate optimization while leafy greens demand rapid response logistics.
- Tomatoes:Vine-ripened fruit with extended harvest cycles requires precise humidity calibration and integrated pest management protocols. Dutch glasshouse clusters and Canadian operators concentrate volume for year-round retail programs where shelf stability commands contract premiums.
- Lettuce:Rapid-turn leafy greens with 45-60 day cycles favor local-provenance messaging in direct-to-consumer channels. Urban and peri-urban installations across Germany and the United Kingdom are expanding fastest where last-mile compression justifies premium positioning.
- Peppers:Temperature-sensitive fruit with high supplemental lighting requirements during winter months.
- Cucumbers:Climbing vines demanding vertical trellis systems and precise pollination management in controlled environments.
By volume, tomatoes lead. By growth pace, lettuce is ahead.
Growing Technique:
Capital deployment patterns diverge dramatically across cultivation systems, with closed-loop architectures demanding upfront engineering investment that soil-based operations avoid.
- Hydroponics:Soilless nutrient film technique dominates water-intensive crops through recirculating systems with 90% consumption reduction versus open-field. Mediterranean retrofit projects in Spain and Italy face steepest compliance curves under EU Green Deal chemical reduction mandates.
- Vertical Farming:Stacked layer configurations maximize yield per square meter in urban logistics corridors. Singapore and UAE installations are expanding most quickly where land scarcity and import dependency justify energy-intensive artificial lighting.
- Aeroponics:Mist-based root delivery enables precise nutrient dosing with minimal water use.
- Soil-Based:Traditional substrate cultivation persists where natural light availability reduces supplemental energy requirements.
By installed base, hydroponics dominates. By expansion trajectory, vertical farming is climbing the fastest.
Distribution Channel:
Channel selection determines traceability investment levels and margin capture potential, with consolidated retail buyers imposing unified data standards that fragment wholesale channels ignore.
- Retail:Grocery banner supply agreements require API-accessible origin dashboards and residue certification. Northern European retail consolidation leaves three groups controlling shelf access, compressing supplier lists and standardizing packaging specifications.
- Direct-to-Consumer:Subscription boxes and farm-gate models capture price separation through local-provenance narratives. Netherlands and United Kingdom operators are gaining share fastest where consumer willingness-to-pay for traceability exceeds wholesale commodity spreads.
- Wholesale:Spot-market intermediation with limited origin documentation for foodservice processors.
- Export:Long-haul logistics demanding modified atmosphere packaging and phytosanitary certification.
By revenue concentration, retail leads. By margin expansion, direct-to-consumer is gaining share fastest.
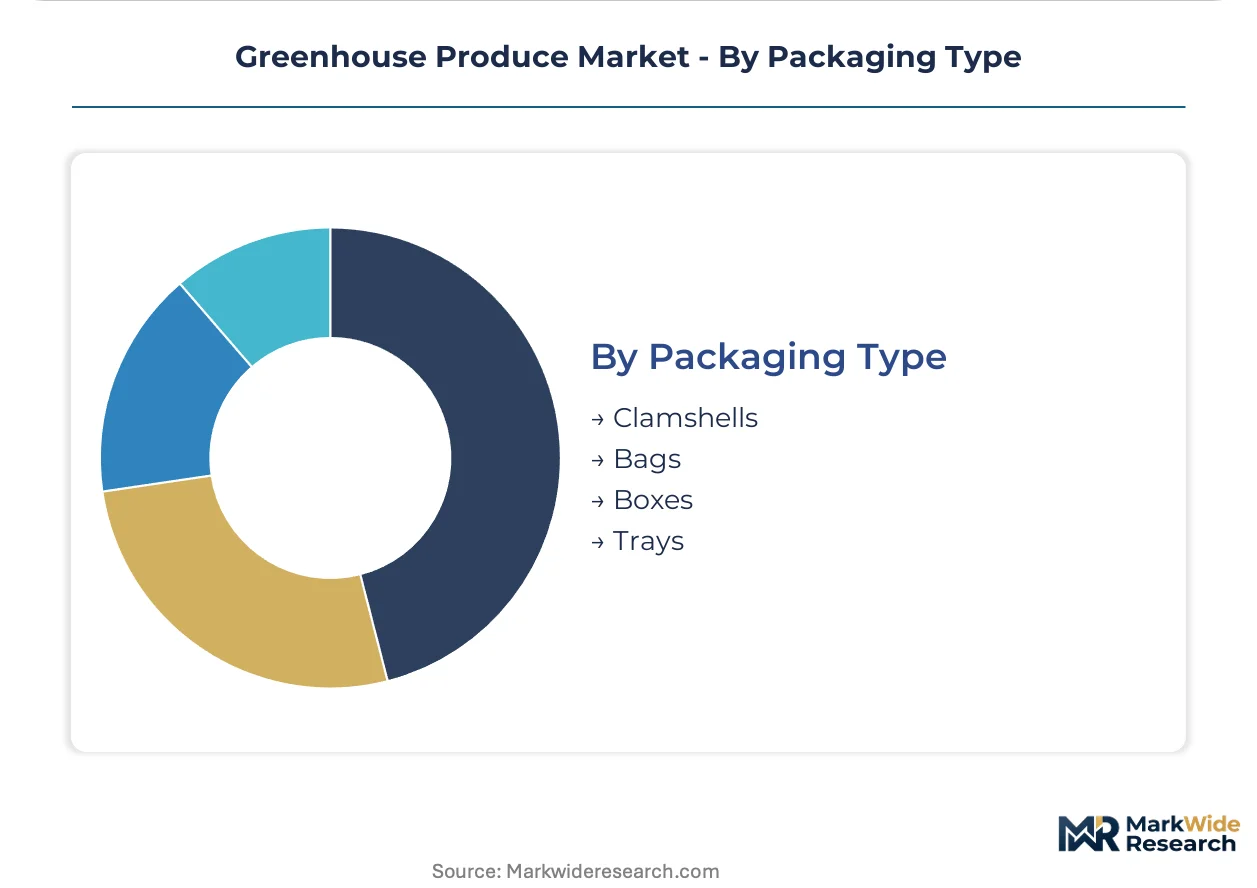
Packaging Type:
Packaging format selection intersects with automation compatibility and shelf-life extension requirements, with retail-facing formats demanding higher graphic investment than foodservice bulk.
- Clamshells:Rigid thermoformed containers with ventilation apertures protect delicate fruit through automated packing lines. North American tomato and berry shippers concentrate procurement where retail display readiness reduces in-store labor.
- Bags:Flexible film formats with micro-perforation enable modified atmosphere for leafy greens. European salad processors are expanding usage fastest where reduced plastic weight meets extended producer responsibility compliance.
- Boxes:Corrugated bulk containers for foodservice and wholesale volume shipment.
- Trays:Pulp or plastic platforms for institutional cafeteria presentation and portion control.
By unit volume, clamshells lead. By sustainability-driven substitution, bags are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium capture in the Netherlands exceeds commodity pricing in Spain by margins that reflect energy infrastructure quality and logistics density. Dutch clusters supply Northern European retail through compressed delivery windows. Spanish operators compete on volume under natural light advantages.
Netherlands
Westland and Aalsmeer clusters concentrate glasshouse tomato and pepper production for just-in-time distribution into German and British retail. The EU F-Gas Regulation accelerates retrofit investment toward closed-loop climate systems. Rotterdam port logistics enable 24-hour shelf delivery to London and Berlin distribution centers.
United States
Foodservice contract expansion from quick-service chains drives year-round tomato and lettuce demand across temperate states. EPA agricultural runoff rules shape site selection near watershed boundaries. California's Central Valley and southeastern Michigan host expanding protected cultivation clusters serving Chicago and New York metro retail.
Spain
Almería and Murcia provinces leverage Mediterranean solar exposure for winter tomato and pepper production with minimal supplemental heating. EU Green Deal Farm to Fork chemical reduction mandates force integrated pest management conversion. Coastal greenhouse belts face water basin allocation restrictions from drought management authorities.
Canada
Leamington, Ontario anchors North American greenhouse tomato supply through combined heat and power infrastructure. Provincial renewable energy certificate programs subsidize geothermal and biomass heat alternatives. The cluster ships volume through Detroit and Buffalo border crossings into Midwest US retail distribution.
United Kingdom
Direct-to-consumer subscription channels expand fastest in Kent and Sussex peri-urban zones where local-provenance messaging commands price separation. Defra agricultural policy supports protected cultivation grants for import substitution. Thanet Earth complex near Canterbury supplies major grocery banners with traceability-certified tomatoes and cucumbers.
Greenhouse Produce Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in propagation genetics and climate equipment. The vendor base organizes around three archetypes: vertically integrated growers controlling seed-to-retail margin capture, regional specialists anchoring supply agreements with single grocery banners, and technology-forward operators deploying automation and spectral imaging at scale. Competitive moves concentrate on long-term offtake contracting and geographic expansion through project finance structures.
Among North American vertically integrated growers, Nature Fresh Farms, Mastronardi Produce, and Houweling's Tomatoes occupy positions that exemplify divergent strategic emphases. Nature Fresh Farms represents the seed-to-retail control archetype through propagation and packing integration. Mastronardi Produce anchors distribution relationships with major grocery banners. Houweling's Tomatoes sits within the energy-efficient scale tier through combined heat and power infrastructure deployment.
| Leading Market Players |
|---|
| Nature Fresh Farms |
| Houweling's Tomatoes |
| Mastronardi Produce |
| Little Leaf Farms |
| BrightFarms |
| Windset Farms |
| Mucci Farms |
| Revol Greens |
| Village Farms International |
| Others |
Supply Flow & Price Mechanics
Westland glasshouse clusters concentrate tomato and pepper capacity within a 40-kilometer radius, compressing logistics costs and amplifying Dutch growers' negotiating leverage against Northern European retail buyers who require just-in-time delivery reliability.
Pricing Analysis
Configured-to-order pricing for traceability-certified vine crops commands spreads over standard wholesale commodity tiers. Three-tier pricing structure across premium, standard, and economy levels separates API-accessible origin dashboards from basic lot documentation. Cost compression in standard tiers is intensifying because natural gas price volatility erodes margins for heated glasshouse operators. Foodservice contract buyers exhibit lowest price sensitivity due to year-round supply guarantees, while spot-market wholesale intermediaries face acute margin pressure.
Supply Chain Analysis
Supplier-financing facilities extended by Dutch propagation genetics firms tighten working capital cycles for greenhouse operators retrofitting climate systems. Input concentration draws from the Netherlands, Israel, and Spain for specialized seed genetics and young plant supply. Supply chain risk centers on single-source vulnerability for combined heat and power equipment maintenance. Distribution runs through Rotterdam port logistics enabling 24-hour shelf delivery to London and Berlin distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as three retail groups in Northern Europe control shelf access and standardize supplier data requirements, fragmenting negotiating leverage among smaller greenhouse operators.
For Market Incumbents: Pre-empt margin erosion by securing long-term offtake agreements with quick-service chains before contract windows close to emerging entrants. Backward integration into seed propagation reduces vulnerability to Dutch and Israeli breeder concentration. Capacity addition in geothermal-enabled Canadian clusters hedges against European energy price volatility. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels where local-provenance messaging commands price separation from wholesale commodity spreads. Peri-urban installations across Kent and Sussex present the most penetrable geography given Defra protected cultivation grants. Lead with API-accessible traceability dashboards to meet grocery banner listing requirements. For Investors and Strategic Acquirers: Long-term, this sits as an infrastructure efficiency play because combined heat and power deployment and closed-loop hydroponic retrofits will separate economically viable operators from margin-compressed competitors. Target acquisition profile centers on mid-scale glasshouse operators with unrealized automation potential and renewable heat source access. The signal to watch is EU carbon border adjustment mechanism implementation pace affecting import substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Hydroponic Retrofit | EU F-Gas Regulation compliance reduces refrigerant leakage and operating cost exposure. |
| Combined Heat and Power Deployment | Geothermal and biomass alternatives under Canadian provincial programs sustain energy cost advantages. |
| Seed-to-Retail Vertical Integration | In-house propagation and packing control margin capture across the value chain. |
| API-Accessible Traceability Dashboard | German and British grocery banners now require unified data standards as a listing condition. |
| Direct-to-Consumer Channel Launch | Subscription box models in Netherlands and United Kingdom capture premium through local-provenance positioning. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with greenhouse operations managers, retail category buyers, foodservice procurement directors, and climate engineering specialists; and secondary validation against customs records, EU F-Gas regulatory filings, EPA agricultural runoff documentation, and renewable energy certificate registries. Bottom-up capacity modeling across Dutch Westland clusters, Spanish Almería belts, and Canadian Leamington operations was triangulated against top-down demand aggregation from grocery banner supply agreements.
Forecast inputs considered growing technique adoption curves, distribution channel shift velocities, and packaging format substitution patterns across the projection horizon. Segmentation dimensions modeled include product type, cultivation system, distribution channel, and regional production cluster. CAGRs were derived from installed base expansion rates and yield improvement trajectories rather than price inflation assumptions. Industry-specific inputs incorporated EU Green Deal Farm to Fork chemical reduction compliance timelines and carbon border adjustment mechanism implementation signals.
Stress conditions across natural gas price bands, water basin allocation restrictions, and integrated pest management certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding climate engineering talent pipeline development and automation technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Microgreens Market
Vegetables
Acorn Squash Market
Vegetables
IQF Vegetables Market
Vegetables
Roselle Market
Vegetables
Carrots and Turnips Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Artichokes Market
Vegetables
Dried Mushroom Market
Vegetables
Dried Vegetable Market
Vegetables
Dry Onion Market
Vegetables
Yarrow Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
Sprouts Market
Vegetables
Vegetable Chutney Market
Vegetables
Squash Market