
 United States Microgreens Market | 2026-2036
United States Microgreens Market Size, Share, and Industry Trends Forecast 2026-2036
United States Microgreens Market Analytics
Restaurant and hospitality procurement of microgreens is collapsing toward direct-from-farm contracts as buyers bypass traditional produce distributors. AeroFarms Inc. leverages controlled-environment agriculture at scale to supply northeastern urban corridors. Gotham Greens LLC anchors its position through rooftop greenhouse networks in Chicago, New York, and Denver. Fresh Origins LLC specializes in specialty varieties for chef-driven markets in California and Nevada.
Microgreens are young vegetable greens harvested 7-21 days after germination, typically 1-3 inches tall with concentrated nutrient profiles up to 40 times denser than mature leaves, produced through soilless hydroponic or substrate-based systems for fresh culinary application. Basil and arugula dominate volume through broad menu penetration across casual and fine-dining segments, while pea microgreens capture expanding share in health-conscious retail channels due to protein-forward positioning. Supermarkets and farmers markets represent contrasting margin architectures: the former demands standardized packaging and consistent supply, the latter rewards varietal novelty and harvest freshness.
The USDA enforces Good Agricultural Practices and Food Safety Modernization Act traceability rules that shape growing facility design and record-keeping burdens for domestic producers. FDA oversight of fresh produce safety, combined with state agricultural department inspections in California and New York, elevates compliance costs for new entrants while reinforcing incumbent quality credibility. Stakeholders must monitor evolving organic certification thresholds and municipal zoning shifts that determine where vertical farms can operate profitably.
Market Dynamics
Restaurant procurement teams are collapsing their microgreens supply chains toward direct-from-farm contracts, bypassing traditional produce distributors and forcing indoor agriculture operators to build captive sales capabilities.
Growth Catalysts
- Fine-dining procurement concentration:Premium restaurant groups in California and New York are consolidating vendor lists to single-source microgreens contracts, creating volume anchors for specialized growers.
- USDA National Organic Program certification:Certified organic microgreens command shelf space premiums in retail channels, pulling production investment toward compliant controlled-environment systems.
- LED horticultural lighting:Energy-efficient spectrum-tuned arrays are reducing per-unit production costs in vertical farms, expanding economically viable harvest cycles.
Market Restraints
- Input cost volatility:Specialized growing substrates and organic seed stock face price swings that compress margins for small-scale producers in Illinois and Colorado.
- Supply concentration risk:Northeast urban corridors depend heavily on a narrow base of controlled-environment operators, creating vulnerability to localized climate system failures.
- Perishability constraints:Seven-day harvest-to-plate windows limit geographic reach and prevent inventory buffering against demand spikes.
Strategic Opportunities
- Texas and Florida expansion:Underpenetrated Sun Belt metro areas lack local controlled-environment capacity, opening territory for greenhouse network replication.
- Pharmaceutical and nutraceutical applications:Concentrated sulforaphane and polyphenol extracts from broccoli and radish microgreens are attracting functional food R&D investment.
- Municipal zoning liberalization:Chicago and Denver adaptive reuse ordinances are permitting vertical farm operations in former industrial buildings, reducing real estate costs.
Industry Challenges
- Horticultural technician scarcity:Controlled-environment agriculture demands specialized expertise in climate system management and integrated pest management that outpaces training pipeline output.
- Food Safety Modernization Act compliance timelines:FDA traceability rule implementation requires facility retrofitting and record-keeping infrastructure that strains capital reserves of mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Microgreens Market |
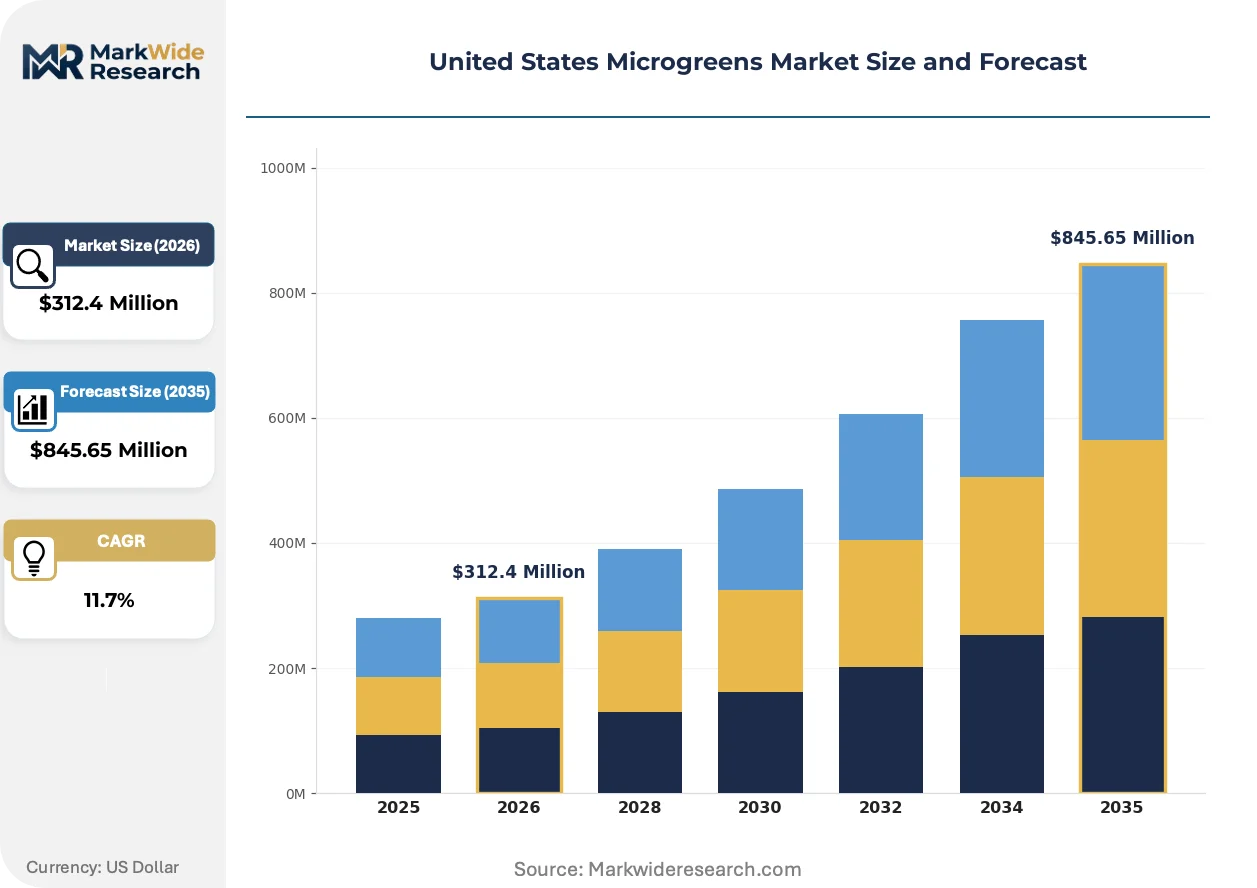
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basil, Radish, Arugula, Peas Distribution Channel: Supermarkets, Restaurants, Online Retail, Farmers Markets End User: Households, Chefs, Food Manufacturers, Health Enthusiasts Packaging Type: Plastic Containers, Bags, Eco-friendly Packs, Clamshells |
| Companies Covered | Bowery Farming Inc., BrightFarms Inc., AeroFarms Inc., The Chef's Garden Inc., Gotham Greens LLC, Little Leaf Farms LLC, Fresh Origins LLC, GoodLeaf Farms Inc., 80 Acres Farms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Microgreens Market Evolving Landscape
Automation and data-driven cultivation protocols are compressing the labor content of microgreens production while tightening variance in yield and quality metrics.
Automated seeding and harvesting robotics is supplanting manual labor in large-scale vertical farms. Northeast operators including AeroFarms are deploying vision-guided systems for tray handling and cut timing. This technology compression is enabling 24-hour production cycles and reducing per-unit labor costs by half.
FDA enforcement of the Food Safety Modernization Act's traceability rule is mandating lot-level digital record-keeping from seed to sale. Growing facilities must install environmental monitoring sensors and blockchain-linked inventory systems. California and New York state agriculture departments are conducting parallel inspections that elevate compliance documentation burdens.
Chef-driven procurement teams are consolidating vendor relationships around single-source contracts with guaranteed variety availability. Traditional produce distributors are losing microgreens category share to direct farm relationships in Chicago, Denver, and Las Vegas hospitality markets. This channel compression rewards growers with dedicated sales staff and flexible harvest scheduling.
United States Microgreens Market Segmentation
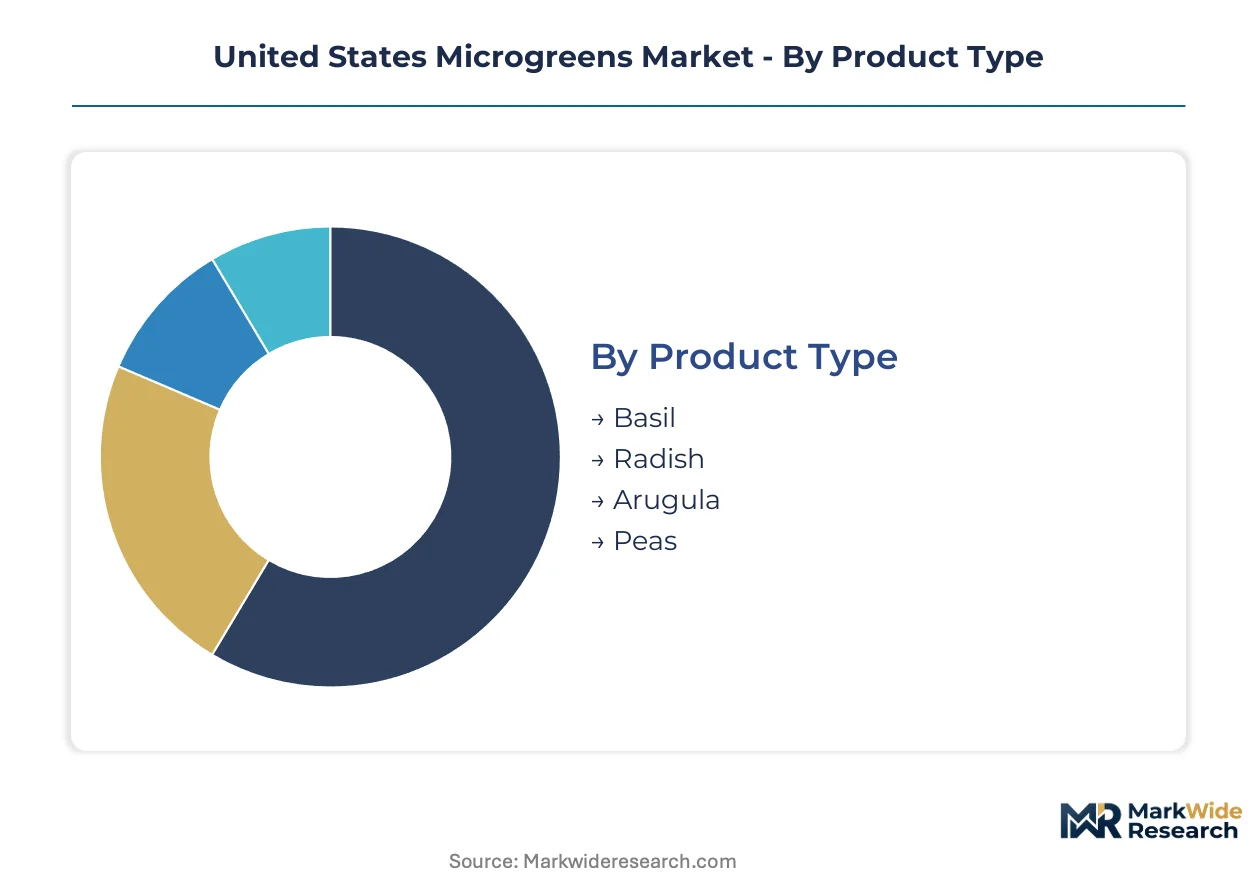
Microgreens segmentation reveals divergent margin architectures across procurement channels and end-use applications. Product variety selection and packaging format choices directly shape production economics and shelf-life performance for growers serving distinct customer tiers.
Product Type:
Basil and arugula anchor domestic foodservice procurement through broad menu penetration, while pea microgreens drive export-adjacent nutraceutical ingredient demand.
- Basil:Intensely aromatic with purple and green varietals, basil microgreens deliver concentrated volatile oils suited for finishing oils and cocktail garnishes. Fine-dining kitchens in New York and California specify living tray programs with 48-hour harvest-to-delivery guarantees. Basil holds the largest share; momentum sits with pea microgreens.
- Peas:Sweet, crisp tendrils with substantial protein content position pea shoots for health-conscious retail and functional food extraction. Illinois vertical farms supply Chicago-area meal kit operators seeking clean-label protein augmentation.
- Radish:Peppery flavor profiles from Daikon and Red Rambo cultivars target chef-driven garnish applications with visual contrast requirements.
- Arugula:Nutty, mustard-forward taste dominates casual dining salad builds through consistent year-round availability from controlled-environment systems.
Volume concentrates in basil and arugula; pea microgreens exhibit the steepest expansion trajectory.
Distribution Channel:
Channel selection determines pricing power through supply chain length and perishability exposure.
- Restaurants:Direct-from-farm contracting eliminates distributor margins and enables variety customization for tasting menus. Northeast chef cooperatives negotiate quarterly volume commitments with AeroFarms and Gotham Greens for guaranteed specialty access.
- Supermarkets:Standardized clamshell packaging and barcode traceability compliance dominate mass retail procurement. California chains demand organic certification and seven-day shelf-life minimums.
- Farmers Markets:Harvest-to-stall freshness commands 40-60% price premiums over retail in Denver and Austin metro areas.
- Online Retail:Subscription models aggregate microgreens with specialty produce for direct-to-consumer delivery in underserved Sun Belt markets.
Restaurants generate highest per-unit margins; online retail channels are climbing fastest.
End User:
User sophistication shapes variety breadth requirements and technical specification stringency.
- Chefs:Fine-dining and hotel culinary teams specify living trays, custom cuts, and varietal novelty for plating differentiation. Las Vegas and Miami hospitality markets drive demand for edible flower and microgreen combinations.
- Food Manufacturers:Frozen and freeze-dried ingredient procurement for soup, smoothie, and supplement applications requires HACCP documentation and consistent sulforaphane assays.
- Health Enthusiasts:Home juicing and raw food practitioners prioritize organic certification and soilless-growing transparency.
- Households:Occasional purchasers through conventional grocery seek recognizable varieties in single-use portions.
Chefs command premium positioning; food manufacturers are scaling procurement fastest.
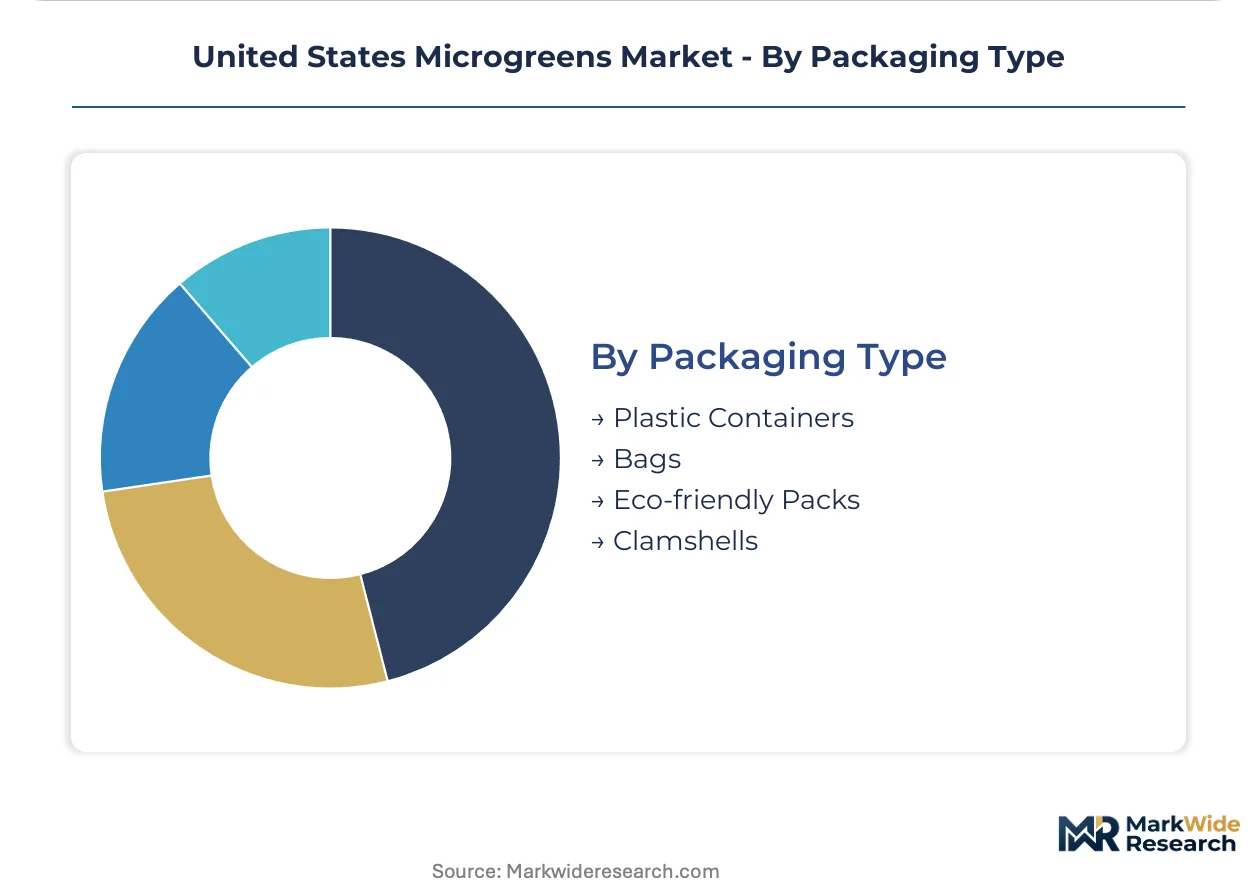
Packaging Type:
Material selection balances shelf-life extension against sustainability positioning and cost structure.
- Clamshells:Rigid PET containers dominate supermarket distribution with moisture control and stackability for automated fulfillment centers. California retailers mandate minimum recycled content thresholds.
- Eco-friendly Packs:Molded fiber and compostable films capture farmers market and specialty retail positioning in Colorado and Oregon regulatory environments.
- Plastic Containers:Deli-style tubs serve foodservice bulk procurement with portion flexibility.
- Bags:Modified atmosphere film extends retail shelf life for pre-cut blends in mass-market channels.
Clamshells maintain volume dominance; eco-friendly alternatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indoor agriculture capacity clusters along coastal urban corridors where restaurant density and premium retail overlap. State-level organic certification protocols and municipal zoning codes shape where controlled-environment operators can scale profitably.
California
San Diego and Los Angeles counties host the densest concentration of specialty microgreens growers serving chef-driven hospitality markets. The California Department of Food and Agriculture enforces stringent organic certification inspections that elevate compliance costs for new entrants. Fresh Origins LLC anchors the southern California cluster with supply contracts to Las Vegas and Phoenix hospitality corridors.
New York
Manhattan and Brooklyn restaurant procurement teams drive demand for living tray programs with 48-hour harvest guarantees. New York State Department of Agriculture and Markets conducts parallel inspections alongside FDA Food Safety Modernization Act enforcement. Gotham Greens LLC operates rooftop greenhouse networks across Brooklyn and Queens with direct distribution to independent chefs.
Illinois
Chicago's fine-dining and hotel sectors consolidate vendor relationships around single-source microgreens contracts. Chicago adaptive reuse ordinances permit vertical farm operations in former industrial buildings, reducing real estate costs for controlled-environment agriculture. Local growers supply meal kit operators and premium grocery chains throughout the Midwest corridor.
Colorado
Denver's farmers markets command 40-60% price premiums for harvest-to-stall freshness over conventional retail channels. Colorado Department of Agriculture organic certification requirements align with USDA National Organic Program standards for indoor producers. The Front Range urban corridor attracts greenhouse network expansion targeting underserved Mountain West markets.
Texas
Dallas and Houston metro areas present underpenetrated demand for local controlled-environment microgreens production. Texas Department of Agriculture inspection protocols for fresh produce safety apply to incoming shipments from out-of-state indoor farms. Sun Belt population growth and restaurant sector expansion outpace existing regional supply capacity.
United States Microgreens Market Competitive Landscape
Concentration sits with vertically integrated controlled-environment operators commanding direct-from-farm distribution channels. The competitive structure tiers between large-scale automated facilities and specialized variety growers serving chef-driven markets. Two archetypes dominate: scale-driven vertical farm networks and boutique specialty producers. Competitive moves center on geographic expansion into underpenetrated Sun Belt corridors and captive sales team development to bypass traditional produce distributors.
Among scale-driven vertical farm operators, AeroFarms Inc., Gotham Greens LLC, and Fresh Origins LLC exemplify contrasting geographic and channel strategies. AeroFarms represents the automated large-facility archetype with northeastern urban corridor concentration. Gotham Greens anchors the rooftop greenhouse network model across multiple metropolitan markets. Fresh Origins occupies the specialty variety position targeting premium hospitality procurement in California and adjacent states.
| Leading Market Players |
|---|
| Bowery Farming Inc. |
| BrightFarms Inc. |
| AeroFarms Inc. |
| The Chef's Garden Inc. |
| Gotham Greens LLC |
| Little Leaf Farms LLC |
| Fresh Origins LLC |
| GoodLeaf Farms Inc. |
| 80 Acres Farms |
| Others |
Value Network & Pricing Analysis
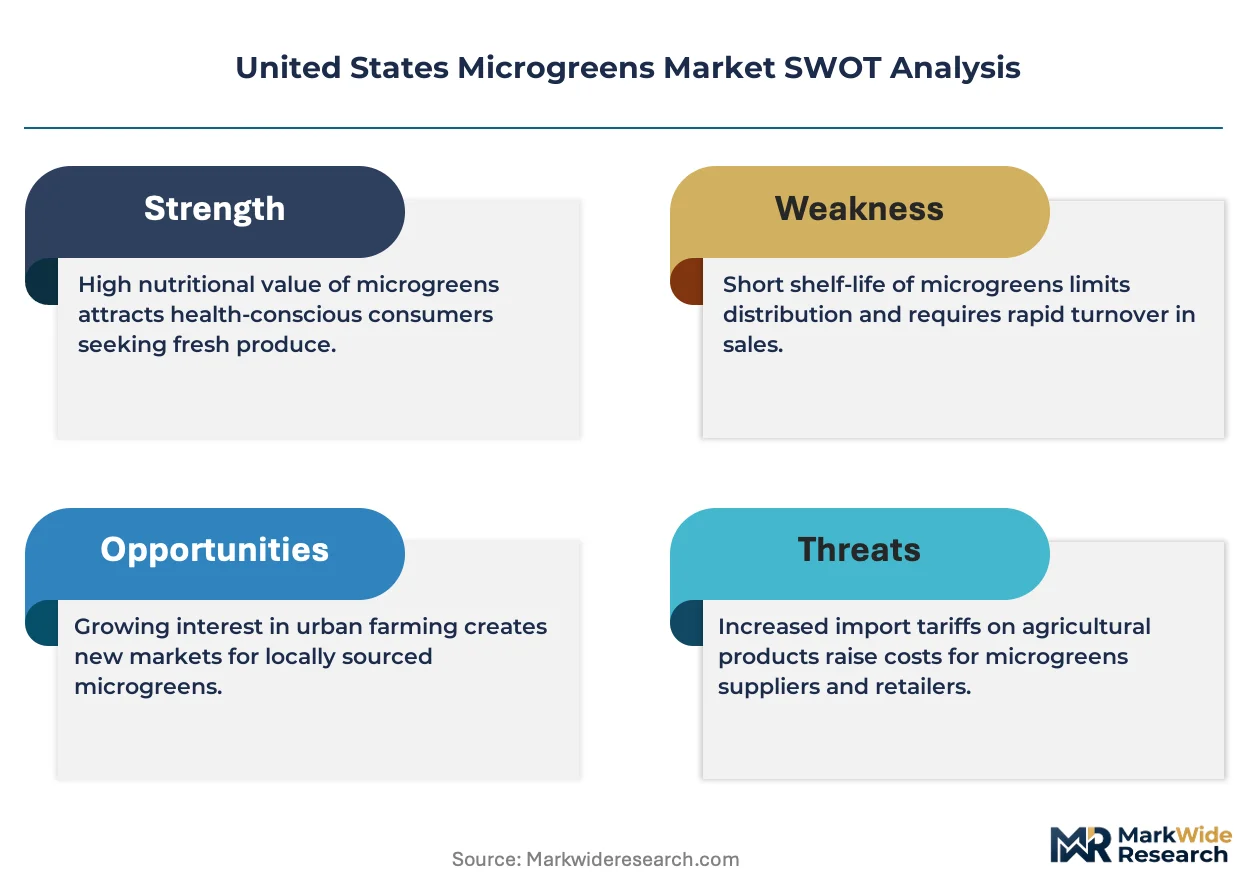
Controlled-environment facility scale economies in the United States compress per-unit growing costs below substrate-based operations, concentrating supply among automated vertical farm networks and establishing price floors that exclude small soil-based growers from mass retail procurement. This scale-driven supply consolidation enables premium positioning for certified organic output while forcing traditional greenhouse operators toward farmers market channels or specialty variety differentiation.
Pricing Analysis
Volume-discount tiering structures separate chef-driven direct contracts from supermarket wholesale and farmers market retail channels. Three-tier pricing stratifies across premium organic certification, standard controlled-environment conventional, and economy-grade open-field production, with USDA National Organic Program compliance commanding shelf-space premiums in California and New York retail. Cost compression in the standard tier intensifies as LED lighting efficiency gains propagate through northeastern vertical farms. Supermarket procurement teams exhibit highest price sensitivity through standardized clamshell specifications, while fine-dining chefs prioritize varietal novelty over per-unit cost.
Supply Chain Analysis
Just-in-time harvest scheduling dominates restaurant procurement, with 48-hour harvest-to-delivery windows eliminating inventory buffers and amplifying vulnerability to climate system failures. Geographic supply concentration centers on California, New York, and Illinois where urban vertical farming infrastructure overlaps with dense hospitality markets. Raw material dependencies draw from specialized growing substrates, organic seed stock, and spectrum-tuned LED arrays sourced through horticultural equipment distributors. Single-source vendor consolidation among chef cooperatives creates supply chain risk when localized growing facilities face contamination events or mechanical failures. Distribution runs through direct-from-farm relationships that bypass traditional produce distributors in Chicago, Denver, and Las Vegas markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as restaurant procurement teams disaggregate from produce distributors toward direct farm contracts, creating niche openings for specialized variety growers and regional greenhouse operators. Chef-driven demand for living tray programs and custom cuts rewards agile entrants over scale-driven incumbents.
For Market Incumbents: Secure single-source contract renewals through dedicated sales teams and flexible harvest scheduling that matches tasting menu rotations. Invest in USDA National Organic Program certification infrastructure to defend shelf-space positioning against emerging rooftop greenhouse networks. Threat substitution from automated seeding and harvesting robotics demands technician training pipelines that outpace competitor capability building. For New Entrants and Emerging Players: Anchor in underpenetrated Sun Belt metro corridors where Texas and Florida restaurant expansion outpaces local controlled-environment capacity. Target Dallas and Houston hospitality procurement teams with direct sales relationships and 48-hour delivery guarantees. Go-to-market leverage rests on adaptive reuse of former industrial buildings through municipal zoning liberalization in secondary cities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with captive distribution channels and automated facility footprints over asset-light variety specialists. Long-term viability over the projection horizon hinges on pharmaceutical and nutraceutical extraction partnerships for sulforaphane and polyphenol concentrates. Watch for FDA Food Safety Modernization Act traceability rule enforcement timelines as inflection indicators for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Farm Contracting | Bypasses distributor margins and enables variety customization for chef procurement teams. |
| Organic Certification Investment | USDA National Organic Program compliance commands retail shelf-space premiums in California. |
| Automated Seeding Robotics | Vision-guided systems at AeroFarms compress labor content and enable 24-hour production cycles. |
| Sun Belt Geographic Expansion | Texas and Florida metro areas lack local controlled-environment capacity for restaurant demand. |
| Pharmaceutical Extraction Partnerships | Broccoli and radish microgreens concentrate sulforaphane for functional food R&D investment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA National Organic Program certification databases, FDA Food Safety Modernization Act guidance documents, and state agricultural department inspection records across California, New York, and Illinois. Primary interviews engaged controlled-environment agriculture facility operators, chef procurement coordinators, supermarket category buyers, and horticultural equipment distributors. Secondary validation drew from SEC filings of publicly traded vertical farm operators, municipal zoning ordinance databases, and trade publications covering LED horticultural lighting efficiency trends. Bottom-up triangulation aggregated facility-level capacity estimates against top-down market sizing from produce distribution volume data.
Segmentation dimensions modeled include product variety, distribution channel, end-user sophistication, and packaging format across the analysis window. Analytical framework projections incorporate LED lighting cost curves, organic certification penetration rates, and restaurant procurement consolidation patterns. CAGRs derive from facility expansion announcements, equipment installation tracking, and chef cooperative contract disclosures. Industry-specific forecast inputs encompass municipal zoning liberalization timelines and FDA traceability rule implementation phases.
Decision-makers should treat outputs as directional under assumptions of continued LED efficiency gains and stable organic certification premiums; material deviation in energy cost trajectories or regulatory enforcement intensity would warrant model refresh. Specific risk factors include input cost volatility in specialized growing substrates, horticultural technician scarcity constraining facility scaling, and climate system failure rates in concentrated northeastern supply corridors. Revision becomes warranted when FDA Food Safety Modernization Act compliance timelines accelerate or municipal zoning shifts restrict vertical farm siting options.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dried Mushroom Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Sprouts Market
Vegetables
Canada Microgreens Market
Vegetables
Roselle Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Artichokes Market
Vegetables
Sweet Potatoes Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Yarrow Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Dry Onion Market
Vegetables
UAE Tomato Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Microgreens Market
Vegetables
Butternut Squash Market