
 IQF Vegetables Market | 2026-2036
IQF Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
IQF Vegetables Market Outlook
Food service procurement is recalibrating toward IQF formats as chain restaurants prioritize portion consistency and reduced kitchen labor. McCain Foods Limited leverages its North American processing network to dominate institutional supply contracts. Greenyard NV anchors European volume through specialized pea and spinach operations. J.R. Simplot Company differentiates via backward integration into potato and vegetable farming.
Individually quick frozen vegetables undergo rapid blast freezing at temperatures below minus forty degrees Celsius, producing discrete, non-clumped pieces that retain cellular structure, color, and nutritional content for twelve to twenty-four months. The technology serves food manufacturers requiring metered ingredient dosing without thaw cycles. Peas and spinach represent mature, high-volume categories where margin pools concentrate with processors achieving economies of scale in bag and bulk packaging. Carrots and broccoli segments exhibit faster structural growth in retail pouches and food processing channels, driven by clean-label ingredient demand from ready-meal producers.
The FDA enforces Hazard Analysis and Critical Control Points protocols alongside FSMA traceability mandates, compelling processors to upgrade digital lot-tracking systems. The USDA grades frozen vegetables for color defects and extraneous matter, shaping procurement specifications for institutional buyers. The EPA regulates refrigerant emissions from blast freezing equipment, accelerating capital replacement cycles. Stakeholders must weigh refrigerant transition timelines against capacity expansion decisions as regulatory compliance costs reshape processor economics.
Market Dynamics
Quick-service restaurant chains are consolidating procurement around IQF formats to lock in year-round supply consistency while compressing kitchen labor costs. This buyer concentration is forcing processors to reconfigure freezing capacity toward bulk institutional specifications rather than retail pack diversity.
Growth Catalysts
- FSMA Traceability Mandates:The FDA's updated Food Safety Modernization Act requirements are accelerating digital lot-tracking adoption among mid-tier processors, creating competitive separation between compliant and non-compliant suppliers.
- India Cold Chain Buildout:Urban retail expansion and refrigerated logistics investments across Indian metropolitan corridors are unlocking frozen vegetable penetration in previously unserved tier-two cities.
- Blast Freezing Automation:Continuous in-line freezing systems are reducing cryogen consumption per ton while improving individual piece integrity for high-value broccoli and cauliflower segments.
Market Restraints
- Refrigerant Transition Costs:The EPA's phasedown of hydrofluorocarbon refrigerants is forcing capital-intensive equipment replacement cycles at processors with aging blast freezing infrastructure.
- Pea Supply Concentration:European volume for mature pea and spinach categories concentrates with Greenyard NV and a handful of Dutch-Belgian processors, creating procurement vulnerability for buyers seeking supply diversification.
- Fresh Substitute Proximity:Local sourcing initiatives by restaurant groups in California and Mediterranean climates are displacing frozen formats in seasonal menu windows.
Strategic Opportunities
- Clean-Label Ready-Meal Integration:Carrot and broccoli processors can deepen penetration into European ready-meal manufacturing where ingredient transparency specifications are tightening.
- Carbon Accounting Differentiation:The EU Green Deal's embodied carbon disclosure requirements are creating first-mover advantage for processors with renewable-powered freezing operations and verified scope-three data.
- Direct Foodservice Platforms:Digital procurement portals are emerging as a channel to bypass traditional distributor markups for mid-size restaurant chains seeking transparent pricing.
Industry Challenges
- Cryogenic Technician Scarcity:Qualified maintenance personnel for minus-forty-degree blast freezing systems are concentrated in established processing regions, constraining greenfield expansion.
- Legacy ERP Integration:Lot-level traceability software deployment is clashing with decades-old inventory management systems at family-owned processing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IQF Vegetables Market |
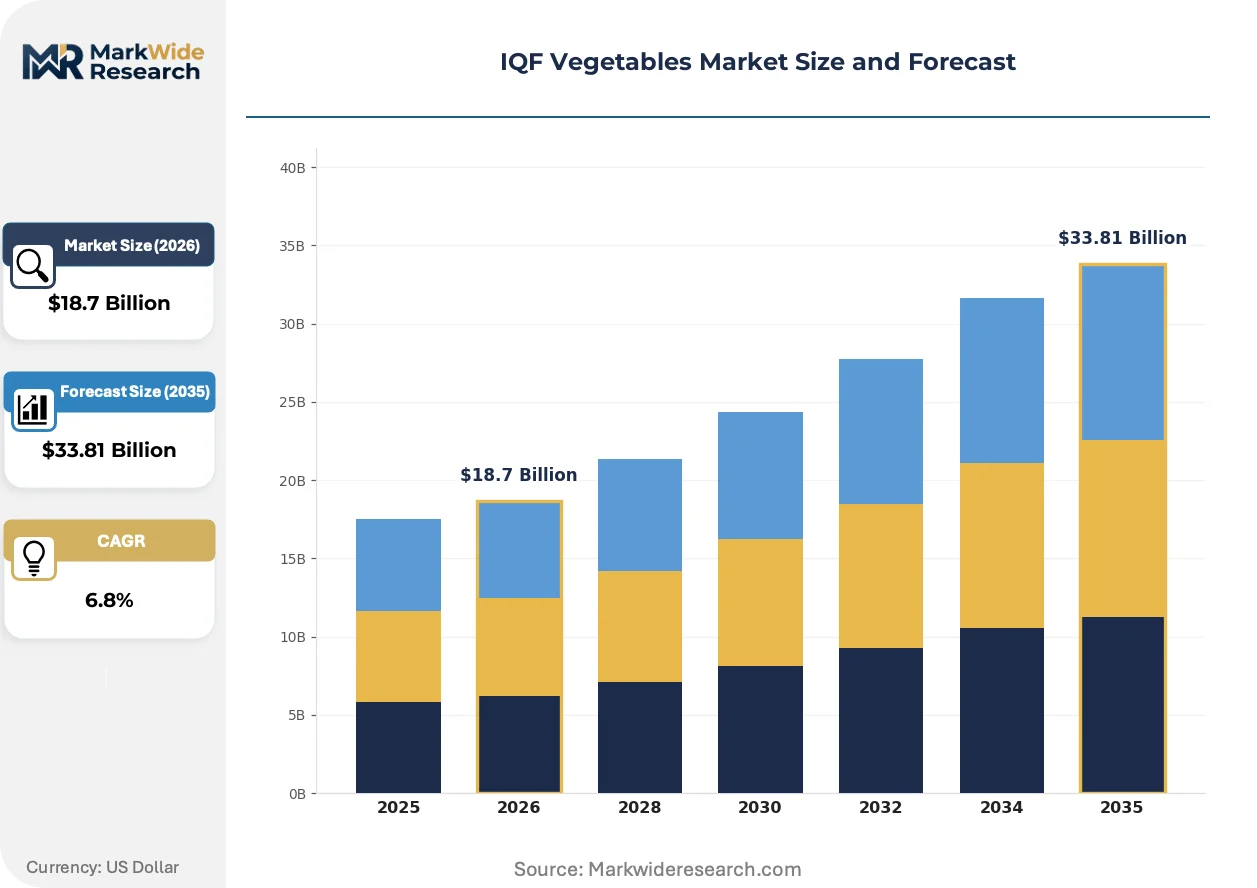
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broccoli, Carrots, Peas, Spinach End User: Food Service, Retail, Catering, Food Processing Packaging Type: Bags, Boxes, Pouches, Bulk Distribution Channel: Supermarkets, Online Retail, Wholesale, Distributors |
| Companies Covered | McCain Foods Limited, Conagra Brands, Inc., Dole Food Co., Greenyard NV, J.R. Simplot Company, SunOpta Inc., Ardo Group, Pinguin Foods N.V., Kerry Group Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IQF Vegetables Market Strategic Shifts
Thermal processing and digital traceability are converging to redefine competitive advantage in frozen vegetable supply. Equipment modularity and regulatory data architecture are becoming primary differentiation vectors alongside traditional scale economics.
Individual quick freezing technology is modularizing around containerized blast freezing units that processors can deploy incrementally rather than committing to centralized greenfield plants. Mid-size regional processors in Poland and Vietnam are adopting these scalable systems to serve quick-service restaurant contracts without the capital intensity of legacy infrastructure. This distributed freezing model is compressing the minimum efficient scale for viable IQF operations.
The F-Gas Regulation is accelerating refrigerant transition timelines across European processing facilities, compelling capital deployment into ammonia and carbon dioxide-based systems ahead of depreciation cycles. Processors in Belgium and the Netherlands are absorbing compliance costs through operational consolidation rather than price pass-through. Spinach and pea operations with the oldest hydrofluorocarbon infrastructure face the steepest replacement economics.
Chain restaurant procurement teams are consolidating supplier rosters around processors offering guaranteed twelve-month pricing with volume flexibility clauses. This contract structure is displacing spot-market purchasing for broccoli and carrot categories in North American foodservice. Quick-service operators in Texas and Florida are piloting these arrangements before national rollout.
IQF Vegetables Market Segmentation
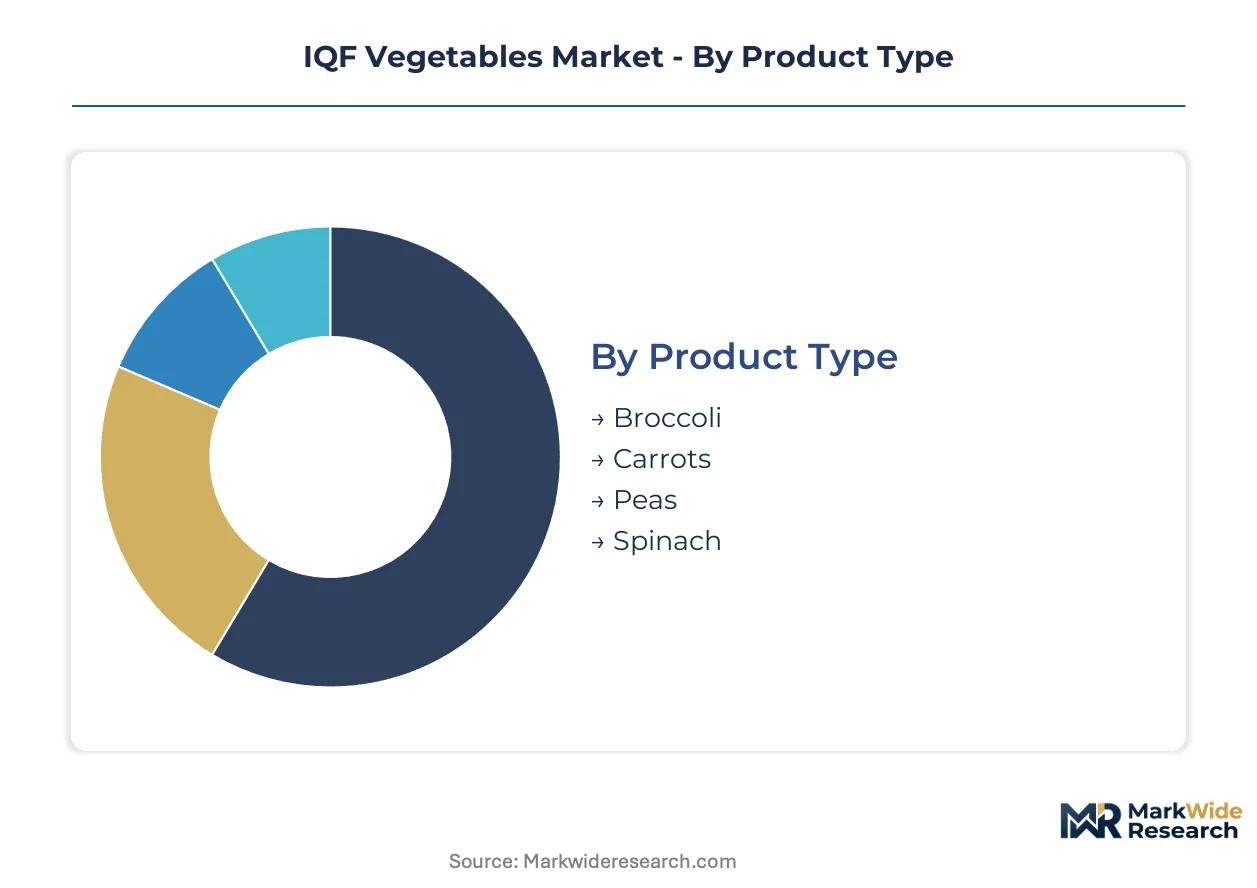
IQF vegetable processors configure production lines around discrete segment specifications that dictate freezing parameters, packaging formats, and distribution economics. Understanding how procurement patterns concentrate across product types, end users, and channel structures reveals where margin pools accumulate and where capacity investments face obsolescence risk.
Product Type:
Blast freezing equipment upgrades and refrigerant transitions are reshaping competitive positioning across vegetable categories with divergent processing economics and shelf-life requirements.
- Peas:Small, uniform spherical geometry enables high-throughput in-line freezing with minimal cryogen consumption per kilogram. Demand concentrates with institutional foodservice buyers in Belgium and the Netherlands who specify Brix levels and tenderometer readings for portion consistency.
- Spinach:High surface-area-to-volume ratio demands precise airflow control to prevent clumping and preserve chlorophyll integrity. European ready-meal manufacturers in Germany and France are tightening clean-label specifications, favoring processors with rapid post-harvest handling and verified pesticide residue protocols.
- Broccoli:Floret fragility requires gentler mechanical handling during washing and dicing stages. Retail pouch demand from North American supermarket chains is climbing fastest.
- Carrots:Dense cellular structure tolerates aggressive freezing rates but requires precise blanching to inactivate polyphenol oxidase. Food processing channels for prepared meals and soup bases absorb the largest volume.
Peas sit at the top of the volume ranking, with broccoli climbing the fastest.
End User:
Customer type determines contract structures, with institutional buyers consolidating procurement around long-term agreements while retail channels fragment across format diversity.
- Food Service:Quick-service restaurant chains mandate twelve-month pricing with volume flexibility clauses, compressing processor margins in exchange offtake certainty. McDonald's and Burger King procurement teams in Texas and Florida are piloting these arrangements before national rollout.
- Food Processing:Ready-meal manufacturers require metered ingredient dosing without thaw cycles, prioritizing discrete piece integrity over bag aesthetics. Clean-label transparency specifications from European manufacturers are tightening fastest.
- Retail:Supermarket private-label programs demand SKU proliferation across pouch sizes and organic variants, fragmenting production runs.
- Catering:Institutional feeding operations absorb bulk formats with lower packaging costs but irregular order timing.
Food service captures the largest revenue pool, with food processing gaining share fastest.
Packaging Type:
Packaging format selection directly determines distribution reach, with bulk configurations serving processor-to-processor supply and retail-facing formats demanding consumer-grade barrier properties.
- Bulk:Unpackaged product in totes or bins minimizes per-unit cost for high-volume food manufacturers with captive repacking capabilities. North American frozen vegetable processors supply industrial soup and sauce bases through this channel.
- Bags:Polyethylene or laminated structures dominate retail freezer cases, with zip-seal and steam-in-bag features commanding shelf space premiums.
- Pouches:Stand-up formats with high-definition printing support premium positioning in European and Asian retail.
- Boxes:Corrugated containment for foodservice distribution prioritizes stackability and moisture resistance over consumer appeal.
Bulk leads in tonnage throughput, with pouches expanding most quickly.
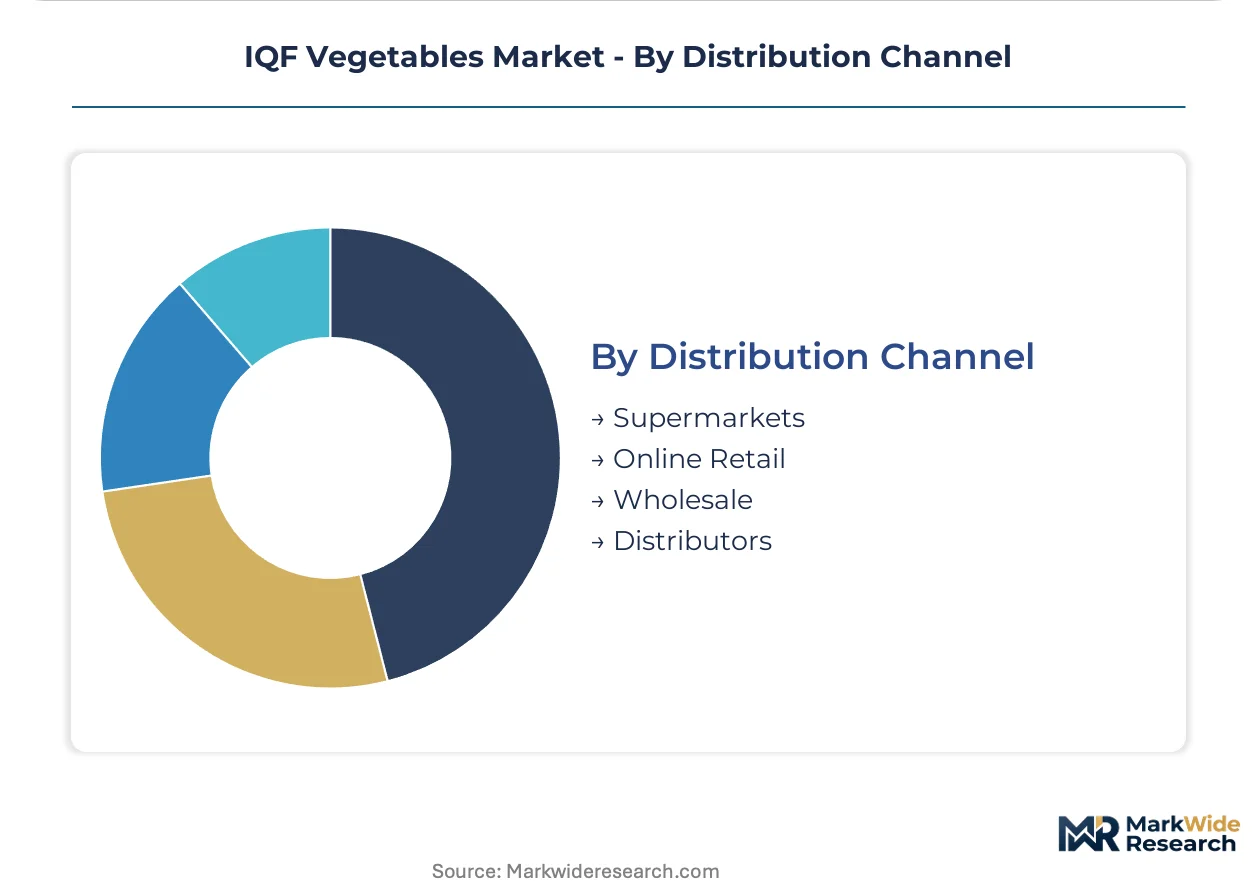
Distribution Channel:
Channel configuration dictates working capital intensity and traceability requirements, with direct-to-retail arrangements demanding ERP integration while wholesale routes buffer demand volatility.
- Distributors:Broadline foodservice distributors aggregate fragmented restaurant demand, absorbing inventory risk in exchange for markup capture. Sysco and US Foods route IQF vegetables through regional consolidation centers.
- Wholesale:Terminal market and cash-and-carry operations serve smaller food manufacturers with spot purchasing and minimal contract commitment.
- Supermarkets:Direct store delivery and distribution center arrangements require pallet-level traceability and promotional funding participation.
- Online Retail:E-commerce grocery platforms are emerging as a channel for premium organic SKUs with home delivery cold chain requirements.
Distributors handle the largest volume flows, with online retail showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium and the Netherlands host the densest concentration of pea and spinach processing infrastructure, with Greenyard NV and Dutch-Belgian processors commanding institutional supply contracts across European foodservice channels.
United States
Quick-service restaurant chains in Texas and Florida are piloting twelve-month pricing contracts with volume flexibility clauses, consolidating procurement around bulk IQF formats. The FDA enforces FSMA traceability mandates that accelerate digital lot-tracking adoption among mid-tier processors. McCain Foods Limited and J.R. Simplot Company anchor North American supply through regional freezing networks serving institutional buyers.
India
Urban retail expansion and refrigerated logistics investments across metropolitan corridors are accelerating frozen vegetable penetration in tier-two cities previously unserved by cold chain infrastructure. The FSSAI regulates frozen food safety standards while central government PLI scheme incentives support processing capacity buildout. Maharashtra and Gujarat host emerging processing clusters where domestic and multinational operators are establishing blast freezing operations.
Belgium
European ready-meal manufacturers source mature pea and spinach categories through specialized processors achieving economies of scale in bag and bulk packaging. The EU F-Gas Regulation accelerates refrigerant transition timelines, compelling capital deployment into ammonia and carbon dioxide-based freezing systems. The Flanders region concentrates spinach operations where clean-label specifications from German and French buyers are tightening fastest.
China
Food processing channels for prepared meals and soup bases absorb significant carrot and broccoli volume through bulk IQF supply arrangements. The country's national food safety regulator enforces Hazard Analysis and Critical Control Points protocols alongside traceability mandates for frozen vegetable exports. Shandong Province anchors domestic processing capacity with regional operators expanding blast freezing infrastructure to serve quick-service restaurant contracts.
Poland
Mid-size regional processors are adopting containerized blast freezing units to serve quick-service restaurant contracts without the capital intensity of legacy centralized plants. REACH compliance requirements shape export-oriented operations supplying European ready-meal manufacturers. The Mazovia region hosts emerging distributed freezing capacity where scalable systems compress minimum efficient scale for viable IQF operations.
IQF Vegetables Market Competitive Environment
Capacity expansion dominates the current landscape as processors reconfigure freezing infrastructure toward bulk institutional specifications rather than retail pack diversity. The vendor base clusters around three tiers: multinational scale operators with backward integration into farming, specialized European pea and spinach processors, and emerging regional players deploying modular containerized systems. Strategic archetypes include scale-driven institutional suppliers, clean-label specialists, and distributed freezing innovators. M&A activity and refrigerant transition investments represent the dominant competitive moves reshaping processor economics.
Among North American-based operators, McCain Foods Limited and J.R. Simplot Company occupy positions exemplifying scale-driven institutional supply archetypes, while Conagra Brands, Inc. represents diversified packaged food portfolio positioning. Within the European specialized tier, Greenyard NV anchors pea and spinach concentration, and Ardo Group exemplifies Belgian-Dutch processing specialization. Kerry Group Plc. sits within the ingredient solutions archetype serving food manufacturing channels with metered dosing requirements. SunOpta Inc. represents the organic and clean-label positioning vector, and Dole Food Co. occupies a position reflecting diversified produce portfolio structure. Pinguin Foods N.V. exemplifies the mid-scale European processor archetype navigating F-Gas compliance transitions.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Conagra Brands, Inc. |
| Dole Food Co. |
| Greenyard NV |
| J.R. Simplot Company |
| SunOpta Inc. |
| Ardo Group |
| Pinguin Foods N.V. |
| Kerry Group Plc. |
| Others |
Value Chain & Pricing Dynamics
Quick-service restaurant procurement consolidation around twelve-month fixed-price contracts with volume flexibility clauses is forcing processors to absorb input volatility rather than pass through cryogen and refrigerant cost swings. This buyer-imposed contract structure compresses margins for mid-tier operators lacking scale to hedge energy exposure or backward-integrate into farming.
Pricing Analysis
Input-cost pass-through mechanics in IQF vegetables hinge on cryogen consumption per ton and refrigerant transition timelines. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified spinach from conventional bag formats and bulk industrial supply. Price differentiation rests on clean-label certification and blast freezing automation levels. Cost compression in standard-tier bag formats is intensifying because European processors are absorbing F-Gas compliance costs without price adjustment. Foodservice buyers exhibit lowest price sensitivity due to menu-cost lock-in, while retail private-label programs drive hardest bargain.
Supply Chain Analysis
Dual-sourcing requirements from McDonald's and Burger King procurement teams mandate multi-supplier qualification across Belgium, the Netherlands, and Poland to mitigate pea supply concentration risk. Raw material dependencies center on field-grown vegetable supply, ammonia and carbon dioxide refrigerant systems, and laminated packaging films. Single-source vulnerability concentrates in European spinach processing where Greenyard NV and Dutch-Belgian operators control institutional volume. Distribution runs through broadline foodservice distributors including Sysco and US Foods regional consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
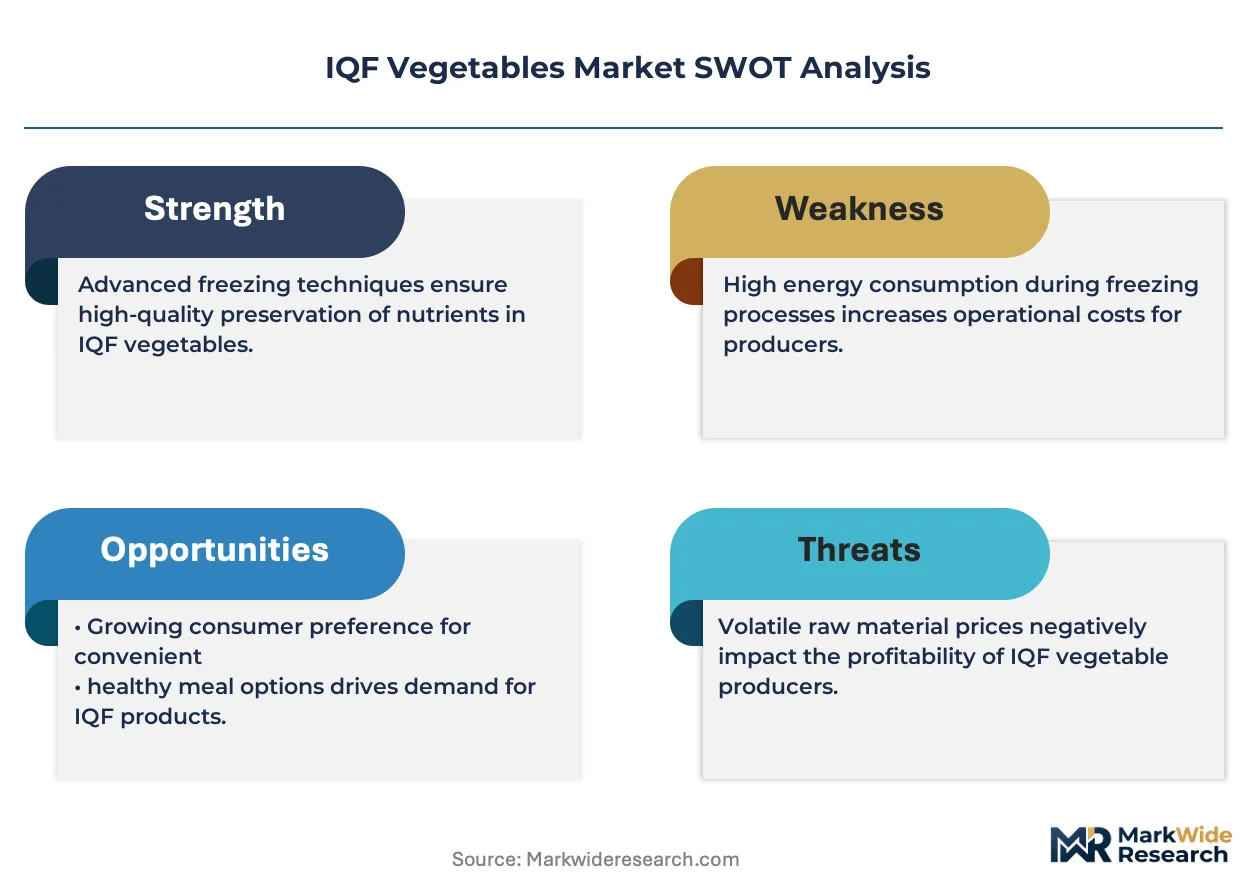
The IQF vegetables market functions as a geographic-arbitrage play where refrigerant transition cost differentials between European F-Gas regulated facilities and Indian PLI-subsidized greenfield capacity reshape competitive economics.
For Market Incumbents: Extend backward integration into potato and vegetable farming to lock in raw material cost predictability against climate volatility. Consolidate freezing capacity around bulk institutional specifications rather than fragmented retail SKU diversity. Refrigerant transition timelines in Belgium and the Netherlands threaten margin stability for operators with aging hydrofluorocarbon infrastructure. For New Entrants and Emerging Players: Digital procurement portals targeting mid-size restaurant chains in Texas and Florida offer a direct-channel route to bypass distributor markups and capture price-transparent volume. Tier-two Indian cities present the most penetrable geography where cold chain buildout outpaces local processing capacity. Containerized blast freezing units enable scalable entry without centralized plant capital intensity. For Investors and Strategic Acquirers: Asymmetric upside sits with modular freezing technology providers and regional Indian processors benefiting from PLI scheme incentives. Long-term viability across the analysis window favors operators with verified scope-three carbon data and renewable-powered freezing assets. Watch for EU Green Deal embodied carbon disclosure enforcement as inflection indicator separating compliant from stranded processing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant System Transition | F-Gas Regulation compliance in Belgium and Netherlands accelerates ammonia and CO2 adoption ahead of depreciation cycles. |
| Backward Integration into Farming | J.R. Simplot Company's captive potato supply anchors cost predictability against commodity price swings. |
| Digital Procurement Platform Launch | Direct foodservice channels bypass Sysco and US Foods markups for mid-size restaurant chain volume. |
| Containerized Freezing Deployment | Polish and Vietnamese regional processors compress minimum efficient scale for viable IQF operations. |
| Clean-Label Certification Investment | European ready-meal manufacturers in Germany and France tighten pesticide residue and transparency specifications. |
Study Parameters
Multiple input streams — processor production data, foodservice procurement records, and cold chain infrastructure investment filings — were reconciled against regulatory compliance databases and trade flow documentation. Primary interviews with blast freezing equipment engineers, quick-service restaurant supply chain directors, and European ready-meal manufacturer procurement leads were cross-validated with secondary sources including FDA FSMA guidance documents, EPA refrigerant phase-down schedules, EU F-Gas Regulation implementation reports, and FSSAI frozen food safety standards. Bottom-up capacity modeling and top-down demand segmentation were triangulated to produce volume and value estimates.
Data-stream reconciliation across the projection horizon applied segmentation by vegetable category, end-user channel, packaging format, and geographic production cluster. CAGRs were derived from fitted growth curves incorporating cold chain penetration rates, quick-service restaurant expansion plans, and refrigerant transition capital deployment timelines. Forecast inputs included blast freezing automation adoption curves, PLI scheme incentive disbursement patterns, and clean-label specification tightening trajectories from German and French buyers.
Refrigerant technology transition delays, FSSAI enforcement intensity variations, and quick-service restaurant contract structure shifts are the dominant revision risks to the outlook. Deviation in EU Green Deal carbon disclosure timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Europe Christmas Tree Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Dried Vegetable Market
Vegetables
Spain Avocado Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Sweet Potatoes Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Canada Microgreens Market
Vegetables
North America Christmas Tree Market
Vegetables
Butternut Squash Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Global Mushroom Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
North America Sweet Potatoes Market