
 Pre-Treater Laundry Products Market | 2026-2036
Pre-Treater Laundry Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Treater Laundry Products Market Analytics
Multi-source procurement for surfactant feedstocks is repositioning how pre-treater manufacturers secure alkylbenzene sulfonate supply chains. Henkel AG & Co. KGaA leverages captive European production facilities to sustain cost predictability. Procter & Gamble anchors North American distribution through club retail partnerships. Kao Corporation competes in Asian markets with concentrated gel formulations.
Pre-treater laundry products are surface-active formulations applied to textiles prior to washing to hydrolyze, oxidize, or emulsify stains before mechanical agitation; typical compositions incorporate protease enzymes, oxygen bleach precursors, or nonionic surfactants at pH ranges optimized for fiber compatibility. Spray treatments now lead household penetration due to dosing precision and spot-treatment convenience, while gel formulations capture premium shelf positioning through concentrated active loading and reduced water content. Oxygen bleach segments mature in developed markets where percarbonate stability issues have driven reformulation costs, whereas bio-based surfactant categories attract reformulation investment as alkyl polyglucoside supply scales.
The EPA Safer Choice program and EU Detergents Regulation shape permissible surfactant chemistries and biodegradability certification requirements for products entering US and European retail channels. The EU REACH framework restricts specific preservative actives, forcing manufacturers to validate alternative stabilizer systems for enzymatic pre-treaters. Stakeholders must monitor evolving state-level disclosure mandates in California and New York that extend beyond federal ingredient transparency thresholds.
Market Dynamics
Enzyme stabilization technology is compressing formulation cycles as manufacturers race to meet EU REACH preservative restrictions while maintaining protease activity in shelf-stable pre-treaters.
Growth Catalysts
- EU Detergents Regulation:Biodegradability mandates for surfactants are accelerating reformulation toward alkyl polyglucoside and other bio-based alternatives in European retail channels.
- Dual-income household expansion:Southeast Asian urban centers with rising washing machine penetration are generating concentrated demand for convenient spray-format pre-treaters.
- Enzyme engineering advances:Subtilisin variants with improved low-temperature activity are enabling cold-wash pre-treatment protocols that reduce energy consumption.
Market Restraints
- Percarbonate instability:Oxygen bleach precursor degradation during storage elevates reformulation costs and shortens effective shelf life in humid climates.
- Alkylbenzene sulfonate concentration:Feedstock supply tightness in Asian petrochemical corridors creates input cost volatility for conventional surfactant formulations.
- Preservative restrictions:EU REACH Annex XVII limitations on isothiazolinone biocides force manufacturers toward unproven stabilizer alternatives.
Strategic Opportunities
- India urbanization:Tier-2 city household formation and rising appliance ownership create white space for concentrated gel pre-treaters positioned above commodity detergents.
- EPA Safer Choice certification:Federal procurement preference and retail shelf placement incentives reward manufacturers achieving ingredient transparency compliance.
- Textile rental services:Commercial linen operators in hospitality are specifying enzyme-based protein removers as part of extended-fiber-lifecycle contracts.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in enzyme-surfactant compatibility and pH buffering across fiber types commands premium compensation.
- Legacy system integration:Existing spray-bottle manufacturing lines require capital retrofitting to handle higher-viscosity gel formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Treater Laundry Products Market |
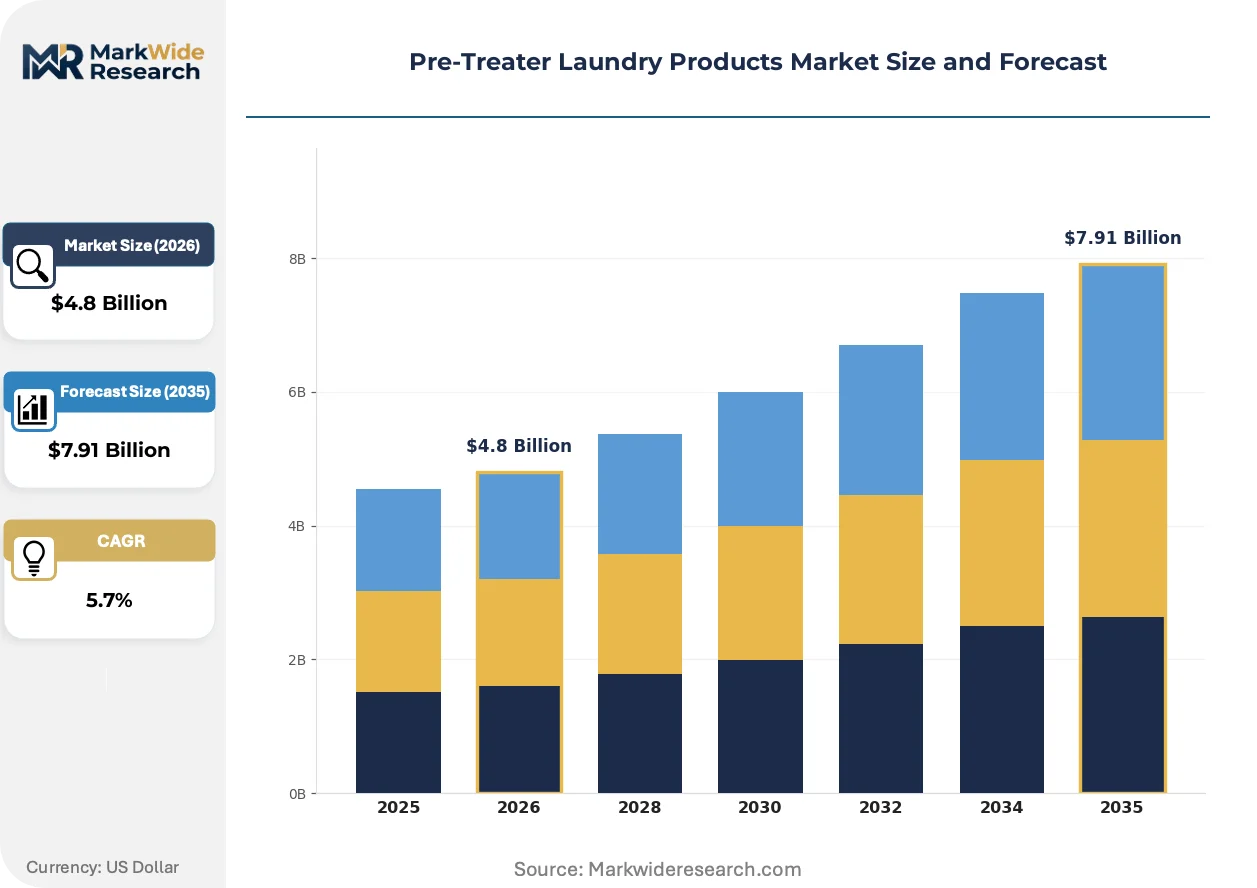
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stain Removers, Spray Treatments, Powder Formulas, Gel Formulations Application: Household, Commercial Laundry, Hospitality, Healthcare Formulation: Enzyme-Based, Oxygen Bleach, Bio-Based, Surfactant-Based Packaging Type: Bottles, Pouches, Tubes, Bulk Containers |
| Companies Covered | Church & Dwight Co., Inc., Reckitt Benckiser LLC, Unilever Ltd., S.C. Johnson & Son, Inc., Henkel AG & Co. KGaA, Procter & Gamble, Clorox Company, Kao Corporation, LG Household & Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Treater Laundry Products Market Evolving Landscape
Spray-to-gel format migration and cold-water enzyme activation are compressing traditional formulation paradigms while regulatory chemistry restrictions force active ingredient substitution.
Encapsulated enzyme technology is decentralizing pre-treater efficacy from temperature-dependent activation toward ambient-water performance. Hospitality linen services in Germany and Japan are adopting these systems to meet corporate carbon reduction targets. The shift is compressing energy-intensive hot-wash protocols while demanding new stabilizer chemistry.
REACH Annex XVII restrictions on methylisothiazolinone are forcing preservative system overhauls across European formulation facilities. Manufacturers are validating alternative stabilizers including benzoate derivatives and enzyme-compatible organic acids. Pre-treater segments with extended distribution chains face the steepest compliance timelines.
Spot-treatment precision is displacing whole-garment soaking as the dominant household application mode. Club retail channels in the United States are expanding trigger-spray SKU facings while supermarkets reduce pour-bottle allocations. Urban apartment dwellers with in-unit compact washers drive this behavioral shift.
Pre-Treater Laundry Products Market Segmentation
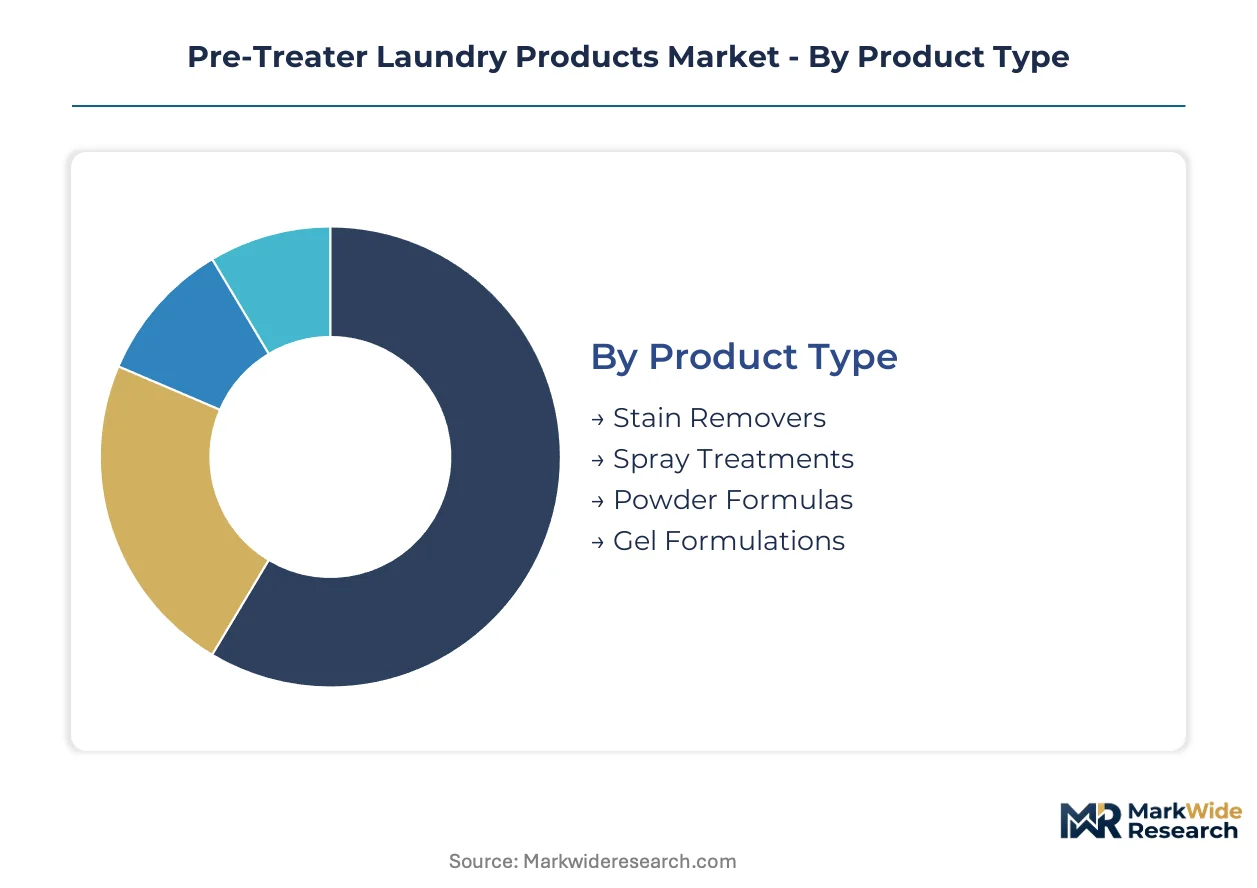
Pre-treater manufacturers calibrate formulation chemistry, packaging format, and channel strategy against distinct performance requirements across household and institutional end-uses. Segmentation discipline separates commodity surfactant formulations from premium enzyme systems with divergent margin profiles and regulatory compliance burdens.
Product Type:
Volume concentration tilts toward spray and powder formats in mass-market retail, while gel formulations command premium shelf positioning through concentrated active loading.
- Stain Removers:Liquid concentrates with protease or amylase enzymes target protein and carbohydrate soils. Hospitality linen services in Germany specify these for protein-heavy food service textiles under extended-fiber-lifecycle contracts.
- Spray Treatments:Trigger-dispensed aqueous solutions enable precise spot application. Urban apartment dwellers in Tokyo and Singapore with compact in-unit washers drive demand for dosing precision and convenience.
- Powder Formulas:Percarbonate-based systems deliver oxygen bleach activation. Storage instability in humid Southeast Asian climates elevates reformulation costs and shortens effective shelf life.
- Gel Formulations:High-viscosity matrices with reduced water content. Kao Corporation competes in Asian markets with concentrated gel positioning above commodity detergents.
Mature deployment sits with powder formulas in traditional retail channels. Newer deployment is concentrated in spray treatments through club retail partnerships.
Application:
Institutional buyers impose specification standards that diverge sharply from household purchasing patterns.
- Household:Individual consumers prioritizing convenience and spot-treatment precision. Spray format penetration rises alongside dual-income household expansion in Southeast Asian urban centers.
- Commercial Laundry:Centralized processing facilities with bulk procurement and standardized protocols. EPA Safer Choice certification influences federal procurement preferences in the United States.
- Hospitality:Linen rental services and hotel chains with extended-fiber-lifecycle contracts. Enzyme-based protein removers are now specified for food service and guest room textiles.
- Healthcare:Infection control protocols demanding validated efficacy against biological soils. EU REACH preservative restrictions complicate stabilizer selection for enzymatic systems in clinical settings.
Margin concentration favors hospitality and healthcare where specification lock-in reduces price sensitivity. Volume scale concentrates in household through mass-market retail distribution.
Formulation:
Regulatory chemistry restrictions in Europe and the United States are forcing active ingredient substitution across legacy surfactant systems.
- Enzyme-Based:Subtilisin variants with improved low-temperature activity enable cold-wash protocols. Encapsulated enzyme technology is decentralizing efficacy from temperature-dependent activation toward ambient-water performance in Germany and Japan.
- Oxygen Bleach:Percarbonate and perborate precursors delivering oxidative stain breakdown. Degradation during storage creates shelf-life constraints and elevated reformulation investment.
- Bio-Based:Alkyl polyglucoside and plant-derived surfactants meeting EU Detergents Regulation biodegradability thresholds. Supply scaling attracts reformulation investment as petrochemical feedstock volatility persists.
- Surfactant-Based:Conventional alkylbenzene sulfonate systems facing feedstock tightness in Asian petrochemical corridors. Multi-source procurement is repositioning manufacturer supply chain strategies.
Steepest expansion trajectory belongs to bio-based formulations as regulatory mandates harden and supply scales. Surfactant-based systems retain volume concentration in price-sensitive developing markets.
Packaging Type:
Format selection reflects channel economics, dosing precision requirements, and sustainability positioning.
- Bottles:Standard rigid containers for liquid and gel formulations. Club retail channels in the United States expand trigger-spray bottle facings while supermarkets reduce pour-bottle allocations.
- Pouches:Flexible film reducing shipping cube and plastic intensity. Concentrated refill formats gain traction in European markets with extended producer responsibility frameworks.
- Tubes:Collapsible packaging for gel and paste consistencies. Premium positioning in specialty retail and travel-size segments.
- Bulk Containers:Institutional formats for commercial laundry and hospitality procurement. Capital retrofitting requirements complicate manufacturer transitions from spray to gel viscosity ranges.
Packaging innovation concentrates in pouches and bulk formats as sustainability metrics and institutional procurement standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alkylbenzene sulfonate production corridors in Asian petrochemical clusters anchor supply-side positioning for pre-treater formulations. Southeast Asian urban demand centers and European regulatory laboratories drive divergent regional strategies. Dual-income household formation in emerging economies reshapes format preferences.
United States
Club retail channels expand trigger-spray SKU facings while supermarkets reduce pour-bottle allocations. EPA Safer Choice certification influences federal procurement preferences for institutional buyers. Urban apartment dwellers in New York and Chicago with compact in-unit washers drive spot-treatment precision demand.
Germany
Hospitality linen services specify enzyme-based protein removers under extended-fiber-lifecycle contracts. EU REACH Annex XVII restrictions on methylisothiazolinone force preservative system overhauls across formulation facilities. Encapsulated enzyme technology adoption concentrates in Frankfurt and Munich processing centers.
Japan
Concentrated gel formulations capture premium shelf positioning through reduced water content. METI guidelines on chemical substance management shape stabilizer selection for enzymatic systems. Kao Corporation competes from Tokyo and Osaka with high-viscosity matrices.
India
Tier-2 city household formation and rising appliance ownership create white space for gel pre-treaters above commodity detergents. BIS standards on surfactant biodegradability tighten compliance thresholds. Mumbai and Bangalore urban clusters concentrate dual-income demand for spray-format convenience.
Brazil
Percarbonate-based oxygen bleach systems face storage instability in humid coastal climates. ANVISA regulations on household chemical products govern preservative disclosure requirements. São Paulo and Rio de Janeiro metropolitan areas anchor mass-market distribution networks.
Pre-Treater Laundry Products Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance enzyme engineering investment against surfactant feedstock volatility. The vendor base spans multinational conglomerates with captive chemical divisions and regional specialists with format-specific expertise. Three archetypes prevail: integrated chemical giants with backward surfactant control, consumer goods multinationals with club retail anchoring, and Asian specialists in concentrated gel technology. M&A activity targets enzyme stabilization capabilities while geographic expansion concentrates on Indian tier-2 cities and Southeast Asian urban corridors.
Within the integrated chemical tier, Henkel AG & Co. KGaA and Procter & Gamble exemplify divergent supply chain strategies. Henkel leverages captive European production facilities for cost predictability. Procter & Gamble anchors North American distribution through club retail partnerships. Kao Corporation occupies a specialist position in Asian markets.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Reckitt Benckiser LLC |
| Unilever Ltd. |
| S.C. Johnson & Son, Inc. |
| Henkel AG & Co. KGaA |
| Procter & Gamble |
| Clorox Company |
| Kao Corporation |
| LG Household & Health Care |
| Others |
Value Network & Pricing Analysis
Alkylbenzene sulfonate spot indices in Asian petrochemical corridors cascade through pre-treater manufacturing into three distinct pricing tiers: enzyme-based premium formulations, mid-tier oxygen bleach systems, and commodity surfactant products. Contract manufacturers with captive surfactant production in Germany and Japan command pricing power over toll-dependent competitors facing feedstock volatility.
Pricing Analysis
Extended-fiber-lifecycle service bundling separates hospitality procurement contracts from unbundled household retail transactions. Three-tier pricing structure across premium enzyme systems, standard oxygen bleach formulations, and economy surfactant products reflects certification grade and active concentration differentials. Pricing pressure stems from percarbonate instability costs in humid climates forcing reformulation investment. Household consumers in Southeast Asian urban centers exhibit highest price sensitivity, while hospitality linen services with specification lock-in tolerate premium positioning.
Supply Chain Analysis
Dual-sourcing mandates from EU-based formulators require qualification of multiple alkylbenzene sulfonate suppliers across Germany, Belgium, and the Netherlands. Raw material dependencies center on linear alkylbenzene feedstocks, protease enzyme concentrates, and percarbonate precursors. Single-source vulnerability concentrates in encapsulated enzyme technology where Japanese and German suppliers dominate proprietary stabilization chemistry. Distribution runs through club retail partnerships in North America and specialized chemical distributors for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pre-treater market sits in a formulation-transition phase as encapsulated enzyme technology displaces temperature-dependent legacy systems requiring hot-wash activation.
For Market Incumbents: Lock in hospitality linen service contracts through extended-fiber-lifecycle bundling before bio-based surfactant scale erodes enzyme premium positioning. Secure captive alkyl polyglucoside supply through backward integration into European biorefinery partnerships. Counter preservative restriction threats by validating benzoate-derived stabilizer systems ahead of REACH Annex XVII enforcement timelines. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer lowest barrier entry for concentrated gel formulations targeting urban apartment dwellers with compact washers. White space concentrates in Indian tier-2 cities where appliance ownership rises ahead of branded pre-treater penetration. Partner with regional e-commerce platforms for spray-format trial-size distribution before retail shelf negotiation. For Investors and Strategic Acquirers: The window for entry favors enzyme stabilization specialists with proprietary encapsulation IP and existing REACH compliance documentation. Long-term viability hinges on cold-water activation technology as carbon reduction mandates compress hot-wash protocols across European and Japanese hospitality sectors. Watch for percarbonate supply exits as shelf-life constraints drive oxygen bleach segment consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Surfactants | Captive alkyl polyglucoside supply insulates margins from petrochemical volatility in Asian corridors. |
| Enzyme Stabilization R&D Partnership | Collaboration with German and Japanese encapsulation specialists accelerates cold-water formulation deployment. |
| Hospitality Linen Service Contract Expansion | Extended-fiber-lifecycle agreements with Frankfurt and Munich processing centers lock in specification-driven procurement. |
| Direct-to-Consumer Channel Launch | Subscription models bypass club retail gatekeepers for concentrated gel penetration in compact-washer households. |
| REACH Preservative System Validation | Alternative stabilizer qualification ahead of methylisothiazolinone restrictions preserves European market access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with formulation chemists, hospitality procurement managers, club retail category buyers, and surfactant plant managers combined with secondary validation from EPA Safer Choice certifications, EU REACH substance registrations, and import-export databases. Bottom-up volume modeling triangulated against top-down value estimates derived from channel revenue disclosures.
Granularity-level modeling operated at product type, application, formulation chemistry, and packaging format dimensions across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers including washing machine penetration curves and dual-income household formation. Industry-specific forecast inputs incorporated enzyme engineering advancement timelines and EU Detergents Regulation compliance cost trajectories.
The model holds under stable surfactant feedstock availability and incremental regulatory tightening; deviation in alkylbenzene sulfonate supply disruption or accelerated REACH preservative bans would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market