
 Antimicrobial Textile Additive Market | 2026-2036
Antimicrobial Textile Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Textile Additive Market Analysis
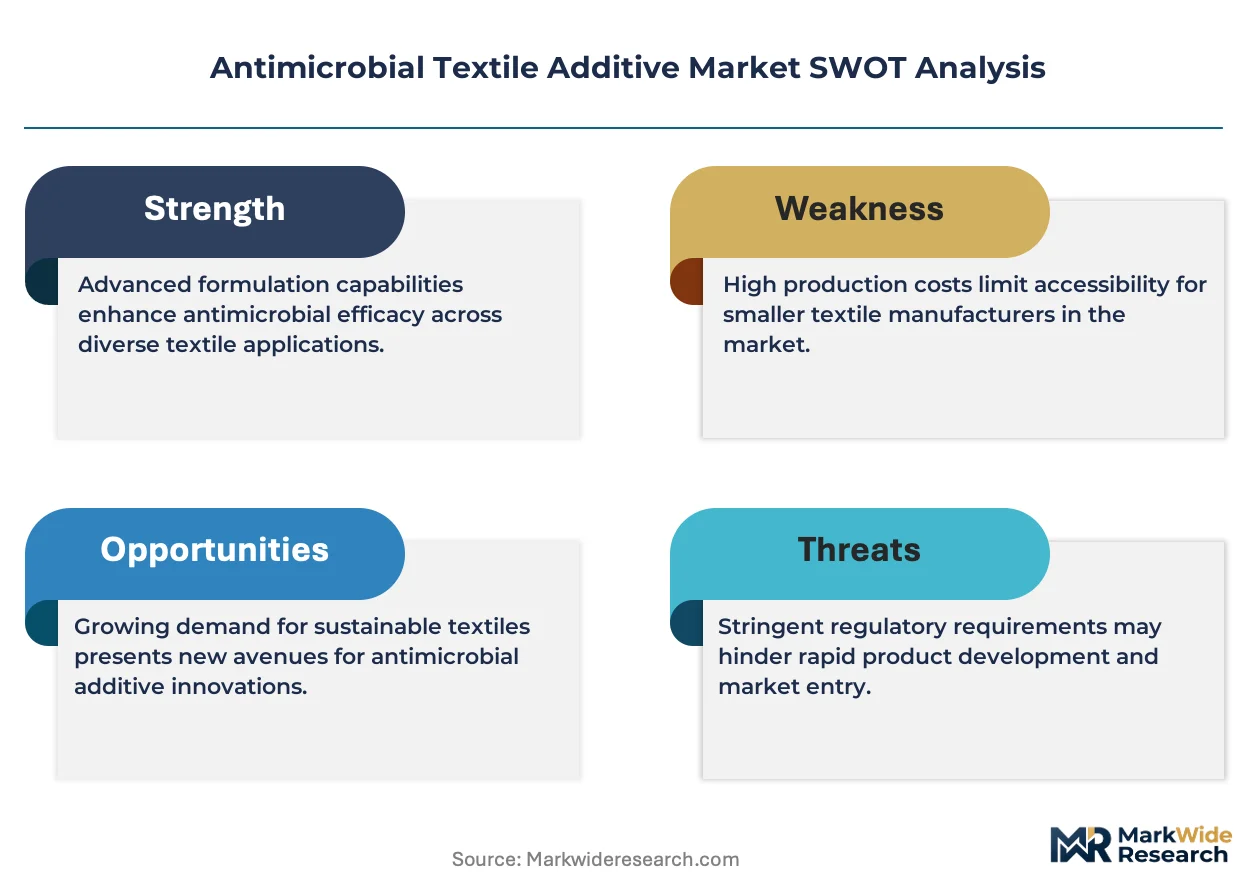
OEKO-TEX Standard 100 certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. BASF leverages its integrated chemical portfolio to supply silver-based active agents at scale. HeiQ Materials AG specializes in finishing technology platforms that anchor its position among European textile finishers. Dow competes through zinc oxide formulations that sustain broad-spectrum efficacy claims.
Antimicrobial textile additives are chemical or biological agents incorporated into fibers, coatings, or finishes to inhibit microbial growth on fabric surfaces, typically applied at 50–500 ppm active concentration depending on end-use requirements. The primary commercial purpose centers on odor control, hygiene preservation, and material longevity in high-contact applications. Silver-based product types dominate current volume owing to established efficacy documentation, while organic coatings represent the fastest-expanding category as brands seek alternatives to metal-based systems amid regulatory scrutiny. Medical textiles application commands the deepest margin pools due to stringent validation requirements and long-term supply contracts with healthcare providers.
The EPA regulates antimicrobial claims under the Federal Insecticide, Fungicide, and Rodenticide Act, requiring substantiated efficacy data before market entry, while the EU Biocidal Products Regulation mandates active-substance approval through ECHA, creating a dual compliance burden for cross-Atlantic suppliers. REACH restrictions on silver nanoparticles and emerging state-level chemical disclosure laws in California and New York are forcing reformulation investments ahead of anticipated tightening. Stakeholders must monitor biocidal authorization timelines and invest early in organic-active R&D pipelines to preserve market access across jurisdictions.
Market Dynamics
REACH restrictions on silver nanoparticles and emerging state-level chemical disclosure laws in California and New York are forcing reformulation investments ahead of anticipated tightening. Suppliers must now navigate dual compliance burdens across the Atlantic while preserving efficacy claims.
Growth Catalysts
- Healthcare procurement expansion:Medical-grade antimicrobial fabric orders from hospitals and long-term care facilities in Germany are accelerating as hygiene protocols tighten post-pandemic.
- EU Biocidal Products Regulation:Active-substance approval requirements are consolidating the supplier base and rewarding early movers with validated dossiers.
- Organic coating chemistry:Brands seeking metal-free alternatives are driving R&D investment into bio-based active agents with comparable durability profiles.
Market Restraints
- Silver price volatility:Precious metal input costs for silver-based formulations create margin compression during commodity spikes.
- German technical textile cluster concentration:Premium additive production concentrates in southern Germany, creating geographic supply risk.
- Efficacy validation timelines:EPA registration under FIFRA requires 12-24 month substantiation periods that delay commercialization.
Strategic Opportunities
- Athleisure and performance wear:Odor-control finishes for high-frequency-use apparel remain underpenetrated relative to medical and home textile saturation.
- California SB 1015 disclosure mandates:Early compliance with emerging state chemical transparency laws creates positioning advantage for US-market access.
- Chitosan-quaternary ammonium convergence:Hybrid bio-synthetic active systems are opening efficacy claims previously reserved for metal-based chemistries.
Industry Challenges
- Biocidal authorization pipeline management:ECHA review backlogs and data gap closures require dedicated regulatory affairs capacity that mid-tier suppliers struggle to fund.
- Legacy finishing equipment retrofitting:Textile mills face capital intensity in upgrading pad-dry-cure lines to handle next-generation aqueous additive formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Textile Additive Market |
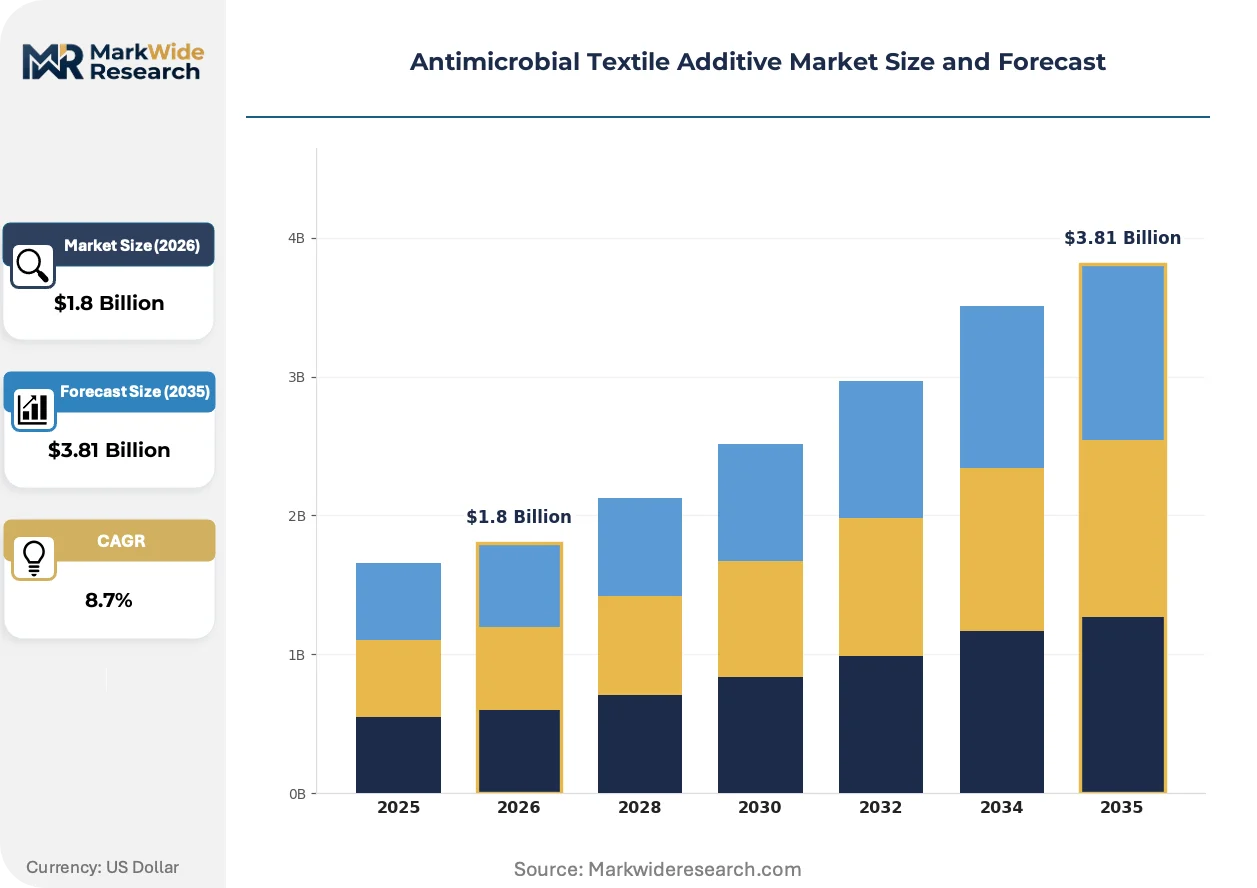
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver, Zinc, Copper, Organic Coatings Application: Apparel, Home Textiles, Medical Textiles, Industrial Fabrics End User: Healthcare Providers, Textile Manufacturers, Retail Brands, Consumers Technology: Spray Technology, Coating Technology, Fiber Modification, Finishing Technology |
| Companies Covered | BASF, Dow, Ashland, Solvay, Sanitized AG, Microban International, Milliken & Company, HeiQ Materials AG, Polygiene Group AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Textile Additive Market Emerging Trajectories
Reformulation chemistry is dominating supplier R&D agendas as metal-based systems face mounting regulatory headwinds. Three interconnected developments are restructuring how antimicrobial efficacy is engineered, validated, and commercialized across fiber and finishing applications.
Chitosan-derived bioactive coatings are supplanting silver-based finishes in consumer-facing apparel categories. Athletic wear brands in Germany and the United States are adopting these systems at pilot scale for 2025-2026 collections. The shift is compressing reliance on precious metal supply chains while opening new efficacy positioning around skin compatibility.
REACH authorization timelines for existing silver nanoparticle registrations are compressing grandfathering windows. ECHA's updated data requirements are forcing dossier resubmissions that favor integrated chemical conglomerates with existing toxicology databases. Medical textile suppliers with hospital contracts are accelerating organic-active qualification programs to preserve cross-border market access.
Hospital procurement departments are consolidating supplier rosters around OEKO-TEX Standard 100 certified finishers. German technical textile clusters are witnessing buyer concentration as group purchasing organizations standardize on pre-qualified additive platforms. This preference shift is most visible in surgical drape and gown contracts where validation documentation carries premium weight in vendor selection.
Antimicrobial Textile Additive Market Segmentation
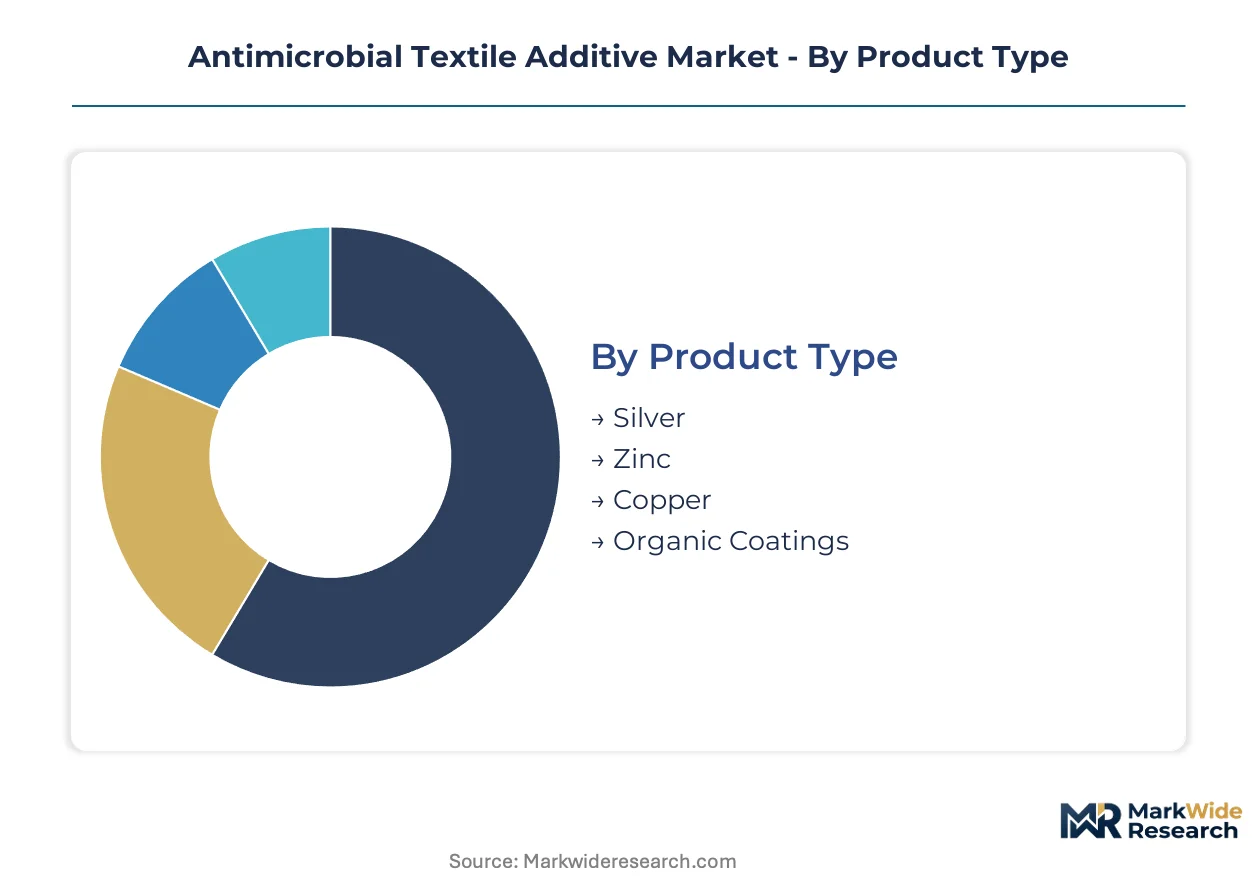
Antimicrobial textile additive purchasing patterns diverge sharply across end-use verticals, with medical-grade specifications commanding premium validation while consumer apparel prioritizes cost efficiency. The four segmentation dimensions reveal how suppliers must calibrate formulation chemistry, application technology, and regulatory dossiers to match distinct buyer requirements.
Product Type:
Silver-based systems dominate export-oriented supply chains serving regulated medical markets, while organic coatings concentrate in domestic consumer apparel production.
- Silver:Metallic ion-exchange systems deliver sustained release of antimicrobial ions at 50–200 ppm active loading. Hospital procurement in Germany and the United States concentrates demand here, driven by EPA FIFRA registration requirements and ECHA biocidal dossier precedents that favor established silver documentation.
- Organic Coatings:Chitosan-derived and quaternary ammonium formulations anchor metal-free efficacy claims for skin-contact applications. Athletic wear brands in Germany pilot these systems for 2025–2026 collections, compressing reliance on precious metal supply chains while opening positioning around dermatological compatibility.
- Zinc:Zinc oxide nanoparticles provide broad-spectrum efficacy with lower regulatory scrutiny than silver nanoparticles under REACH authorization timelines.
- Copper:Copper-based systems find niche uptake in industrial fabric applications where material longevity outweighs initial formulation cost.
Silver holds the largest share; momentum sits with organic coatings.
Application:
Cost tier stratification separates medical textiles with validation-intensive procurement from volume-driven home textile segments.
- Medical Textiles:Surgical drapes, gowns, and wound dressings require substantiated efficacy data under FDA 510(k) or MDR pathways. German hospital group purchasing organizations consolidate supplier rosters around OEKO-TEX Standard 100 certified finishers, embedding long-term contract structures that protect margin pools.
- Apparel:Odor-control finishes for athletic and performance wear remain underpenetrated relative to medical saturation. California SB 1015 disclosure mandates are reshaping procurement specifications for brands selling into the US West Coast market.
- Home Textiles:Bedding and upholstery applications prioritize cost efficiency over clinical validation, with zinc-based systems gaining traction.
- Industrial Fabrics:Filtration and protective equipment segments demand durability under mechanical stress, favoring fiber modification over surface coating approaches.
Medical textiles command the deepest margins; apparel is expanding most quickly.
End User:
Customer type determines whether procurement flows through centralized tender processes or dispersed brand-level formulation selection.
- Healthcare Providers:German technical textile clusters witness buyer concentration as hospital procurement departments standardize on pre-qualified additive platforms. Validation documentation carries premium weight in vendor selection for surgical textile contracts.
- Textile Manufacturers:Finishing mills face capital intensity in upgrading pad-dry-cure lines to handle next-generation aqueous additive formulations, concentrating demand among integrated chemical suppliers.
- Retail Brands:Consumer-facing apparel companies drive organic coating adoption through sustainability positioning and supply chain transparency requirements.
- Consumers:Direct purchasing of antimicrobial-treated textiles remains limited to premium niche channels, with most efficacy benefits embedded upstream in B2B supply chains.
Healthcare providers anchor volume commitment; retail brands are gaining share fastest.
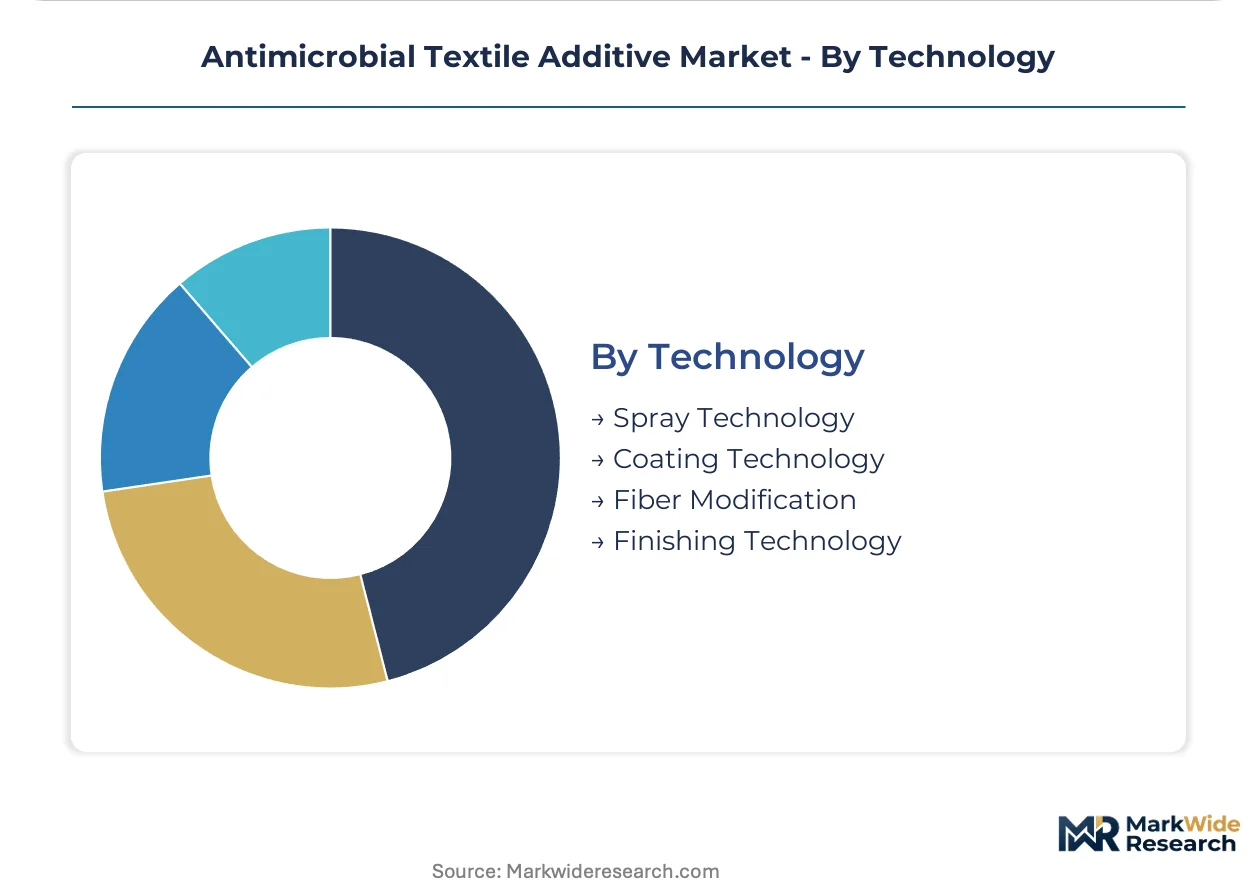
Technology:
Supply concentration in southern German technical textile clusters shapes which application methods achieve scale validation.
- Finishing Technology:Pad-dry-cure and exhaust application methods dominate current production infrastructure. HeiQ Materials AG anchors its European position through proprietary finishing platforms that textile mills license rather than develop in-house.
- Fiber Modification:Masterbatch incorporation during extrusion creates permanent antimicrobial protection that survives repeated laundering. Medical textile suppliers with hospital contracts are accelerating qualification programs to preserve cross-border market access amid REACH silver nanoparticle restrictions.
- Coating Technology:Surface-bound systems offer reformulation flexibility but face durability challenges in high-abrasion applications.
- Spray Technology:Post-manufacture application methods serve retrofit markets and small-batch production with lower capital barriers.
Finishing technology holds the largest share; fiber modification shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Biocidal Products Regulation enforcement is consolidating supplier access across European medical textile procurement, while EPA FIFRA registration timelines in the United States create parallel compliance bottlenecks that favor early dossier filers.
United States
Hospital group purchasing organizations are standardizing antimicrobial fabric specifications for surgical textiles and patient gowns. EPA registration requirements under FIFRA mandate 12-24 month efficacy substantiation periods that delay commercialization for new entrants. North Carolina's technical textile corridor hosts finishing operations serving domestic medical device manufacturers.
Germany
Technical textile clusters in southern Germany concentrate premium additive production for surgical drape and gown contracts. ECHA biocidal active-substance approval requirements reward suppliers with validated dossiers and documented toxicology databases. Baden-Württemberg finishing mills are upgrading pad-dry-cure infrastructure to handle next-generation aqueous formulations.
China
Domestic apparel brands are piloting organic coating systems for athletic wear collections targeting export markets. The country's national chemical regulator maintains evolving standards for antimicrobial claims in textile applications. Zhejiang and Jiangsu provinces host integrated fiber-to-finish operations supplying global home textile retailers.
Switzerland
Specialized finishing technology providers anchor European positions through licensed platform models rather than commodity chemical sales. Swissmedic oversight of medical device textiles creates validation-intensive procurement for surgical applications. Basel's chemical industry corridor connects additive innovation with downstream textile engineering.
India
Technical textile manufacturers are expanding antimicrobial finishing capacity for domestic healthcare infrastructure and export home textile segments. Bureau of Indian Standards certification requirements are tightening quality benchmarks for hospital-grade fabrics. Tamil Nadu's textile belt is attracting investment in medical textile conversion facilities.
Antimicrobial Textile Additive Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates and specialized finishing technology providers. Market structure concentrates around suppliers with validated ECHA dossiers and EPA registrations, creating tiered access based on regulatory compliance capacity rather than manufacturing scale alone. Two dominant competitive moves are reshaping positioning: strategic partnerships between additive suppliers and textile finishing mills to secure qualification pipelines, and geographic expansion through local registration filings in priority export markets.
Within the integrated chemical tier, BASF and Dow exemplify scale-driven archetypes with cross-portfolio active agent supply capabilities. Among specialized European finishers, HeiQ Materials AG occupies a position representing technology licensing models that textile mills adopt rather than develop internally. Sanitized AG anchors the Swiss-based specialist segment where regulatory dossier depth determines medical textile contract access.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Ashland |
| Solvay |
| Sanitized AG |
| Microban International |
| Milliken & Company |
| HeiQ Materials AG |
| Polygiene Group AB |
| Others |
Supply Flow & Price Mechanics
OEKO-TEX Standard 100 certification gates both supplier qualification and price differentiation simultaneously, separating qualified finishers from marginal participants while embedding premium positioning for hospital-grade antimicrobial textiles. Medical procurement departments in Germany concentrate purchasing power around certified platforms, compressing margins for non-compliant suppliers and amplifying returns for dossier-validated additive providers.
Pricing Analysis
Certification level (OEKO-TEX Standard 100 versus uncertified) creates the primary spread between premium medical-grade additives and commodity home textile formulations. Three-tier pricing structure across premium, standard, and economy levels reflects validation intensity, with surgical drape contracts commanding multiples over bedding applications. Pricing pressure stems from silver price volatility and REACH-driven reformulation costs. Healthcare providers show lowest price sensitivity due to long-term contract structures, while apparel brands negotiate aggressively on volume.
Supply Chain Analysis
Baden-Württemberg technical textile clusters in Germany anchor the chokepoint for premium additive finishing capacity serving European medical markets. Active agent supply draws from China and Switzerland, with silver ion precursors sourced from precious metal refiners and chitosan derivatives from biopolymer specialists. Single-source vulnerability concentrates in southern German finishing infrastructure. Distribution runs through textile mill licensing agreements and direct hospital group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated regulatory dossiers represent the scarcest capability in this market, with ECHA biocidal authorization timelines and EPA FIFRA registrations creating multi-year barriers that only integrated chemical conglomerates and specialized Swiss finishers can surmount.
For Market Incumbents: Consolidate supplier rosters around OEKO-TEX certified finishing platforms to deepen hospital contract penetration. Accelerate organic-active R&D pipelines ahead of REACH silver nanoparticle restrictions. Vertical integration into chitosan-derived bioactive chemistry preserves cross-border market access as metal-based systems face authorization compression. For New Entrants and Emerging Players: Anchor in California SB 1015 compliance services for apparel brands seeking chemical transparency advantage. Target athleisure odor-control finishes where medical-grade validation requirements are absent and brand sustainability positioning drives premium uptake. License finishing technology from established European platform providers rather than building proprietary application infrastructure. For Investors and Strategic Acquirers: ECHA biocidal active-substance approval deadlines reshape the acquisition landscape toward dossier-rich specialists with documented toxicology databases. Long-term viability centers on suppliers with dual US-European regulatory capacity and hospital contract backlogs. Watch ECHA authorization backlogs as the signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| ECHA Dossier Expansion | Biocidal active-substance approvals protect German medical textile contract access against REACH silver restrictions. |
| Organic Coating R&D Partnership | Chitosan-quaternary ammonium convergence opens efficacy claims previously reserved for metal-based chemistries. |
| California Compliance Pre-Positioning | SB 1015 disclosure mandates create first-mover advantage for US West Coast apparel brand procurement. |
| Finishing Platform Licensing | HeiQ Materials AG model demonstrates scale without capital intensity in pad-dry-cure infrastructure. |
| Hospital GPO Contract Consolidation | German group purchasing organization standardization embeds long-term supply relationships with margin protection. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in documented compliance trajectories. Conversations with textile mill technical directors, hospital procurement managers, ECHA regulatory affairs specialists, and athletic wear brand sustainability officers combined with EPA FIFRA registration databases, ECHA biocidal product dossiers, and OEKO-TEX certification records. Bottom-up additive volume estimates triangulated against top-down medical textile production data.
Sensitivity analysis across silver price volatility scenarios and REACH authorization delay assumptions stress-tested projection robustness. Segmentation modeling spanned product type chemistry, application end-use, technology platform, and regional regulatory cluster. CAGRs derived from hospital procurement expansion rates and apparel brand pilot adoption curves. Fiber modification versus finishing technology penetration served as the critical industry-specific demand split.
Material uncertainties — ECHA review backlogs, silver commodity spikes, and state-level chemical disclosure law expansion — sit outside the modeled envelope. Forecasts reflect assumptions about biocidal authorization timelines and organic coating efficacy parity achievement. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and precious metal supply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market