
 Functional Textile Finishing Chemicals Market | 2026-2036
Functional Textile Finishing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Textile Finishing Chemicals Market Analytics
The gap between premium fluorine-free formulations and commodity perfluorinated chemistries is hardening as brands face divergent compliance timelines. BASF SE leverages its polymer R&D pipeline to sustain leadership in durable water-repellent alternatives. Huntsman International LLC anchors its position through integrated finishing auxiliaries that span pretreatment through final coating. Dow Inc. competes via silicone-based softeners that occupy the technical fabrics channel with consistent batch performance.
Functional textile finishing chemicals encompass surface-active formulations applied to woven, knitted, or nonwoven substrates to impart durable properties such as hydrophobicity measured by spray ratings or limited flame spread per ASTM D6413. These treatments enable textiles to meet end-use specifications in sectors where performance failure carries safety or liability consequences. Anti-microbial finishes lead product type demand as healthcare and athletic applications tighten hygiene protocols. Technical fabrics represent the fastest-growing application segment, driven by industrial filtration and geotextile specifications. Coating technologies command margin concentration due to capital intensity and formulation know-how barriers that filter out commodity competitors.
EPA scrutiny of long-chain perfluoroalkyl substances under TSCA Section 6 shapes product registration requirements for US-market suppliers. ECHA REACH restrictions on C8-based fluorotelomers force European formulators to validate short-chain or fluorine-free alternatives through notified body assessment. China's MEE enforcement of dual carbon goals tightens emissions thresholds at finishing mills, redirecting procurement toward low-temperature cure systems. Stakeholders must monitor regulatory divergence across these jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
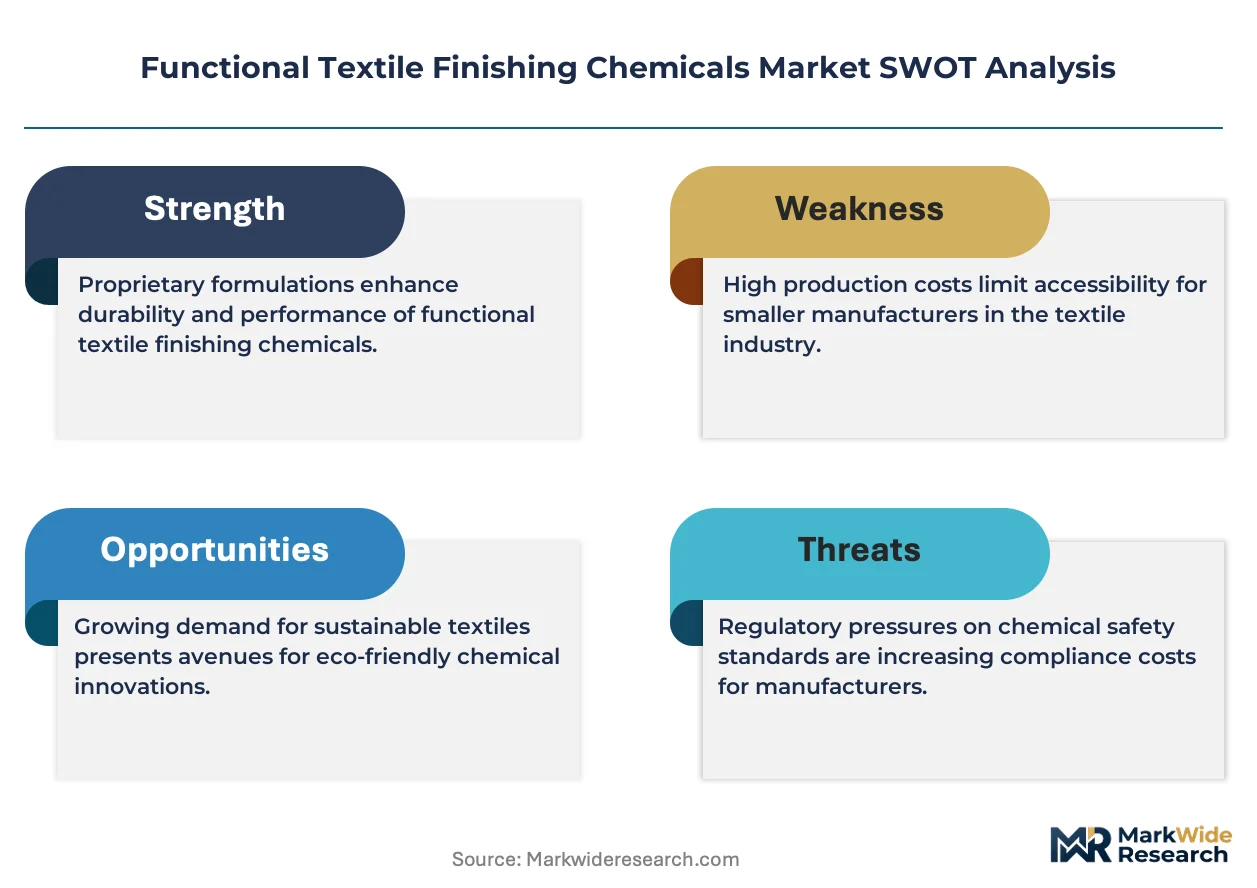
REACH restrictions on perfluorinated compounds are forcing European formulators to rebuild product portfolios around fluorine-free chemistries, compressing reformulation timelines and widening the performance gap against legacy C8-based systems.
Growth Catalysts
- Healthcare hygiene protocols:Hospitals and medical textile laundries are mandating anti-microbial finishes with validated efficacy against hospital-acquired pathogens, pulling demand from commodity softeners into certified biocidal treatments.
- China's dual carbon enforcement:MEE emissions thresholds at finishing mills are redirecting procurement toward low-temperature cure systems that reduce energy intensity per linear meter processed.
- Technical fabric specifications:Industrial filtration and geotextile applications are tightening performance benchmarks for hydrophobicity and UV stability, requiring durable finishes that survive mechanical stress and chemical cleaning cycles.
Market Restraints
- Fluorine-free performance gap:Short-chain and fluorine-free water-repellent chemistries still fail to match C8-based systems on oil repellency and wash durability, limiting substitution in premium outdoor apparel.
- Raw material concentration:Silicone softener precursors and specialized polymer backbones concentrate among Asian petrochemical suppliers, exposing finishers to freight cost volatility and allocation risk.
- Capital intensity of coating lines:Slot-die and rotary screen coating equipment requires seven-figure investments with long depreciation cycles, filtering out mid-scale entrants from margin-rich technical fabric segments.
Strategic Opportunities
- India technical textile expansion:PLI scheme incentives for domestic technical fabric manufacturing are creating demand for finishing chemicals that meet export-market certification requirements.
- Smart textile convergence:Integration of conductive inks with traditional finishing chemistries is enabling sensor-embedded athletic wear that monitors biometric data through launderable conductive pathways.
- EU Green Deal procurement rules:Public sector textile purchasing mandates are favoring finishes with verified biodegradability and renewable feedstock content, creating premium positioning for compliant formulators.
Industry Challenges
- Reformulation talent scarcity:Polymer chemists with expertise in hydrophobic surface engineering and notified body dossier preparation command premium compensation, constraining R&D throughput at mid-tier suppliers.
- Multi-jurisdiction registration complexity:Divergent EPA TSCA Section 6, ECHA REACH, and China MEE notification requirements force parallel toxicology studies and extended timeline-to-market for new active substances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Textile Finishing Chemicals Market |
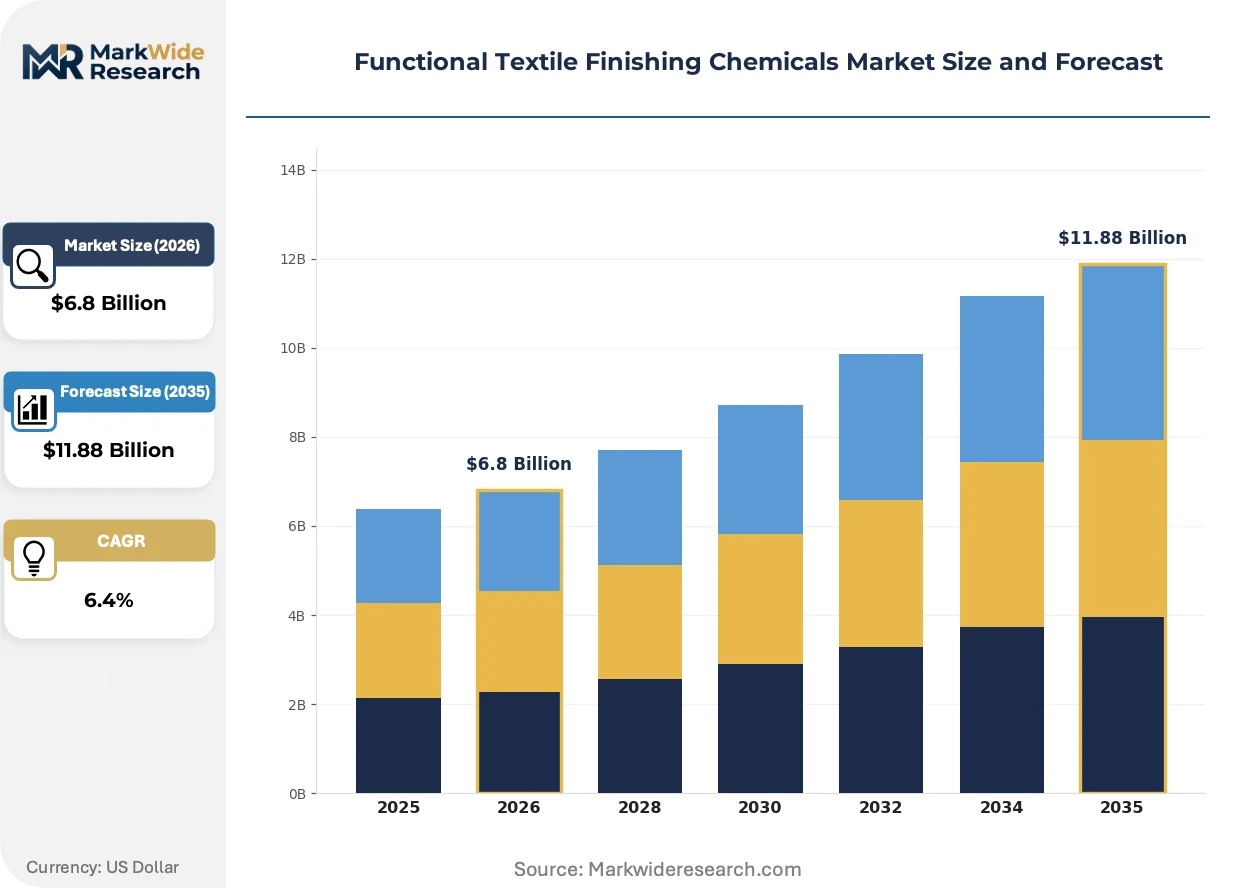
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Repellent, Flame Retardant, Anti-microbial, Soil Release Application: Athletic Wear, Home Textiles, Technical Fabrics, Protective Clothing End User: Textile Manufacturers, Apparel Brands, Home Furnishing Companies, Industrial Textile Providers Technology: Coating Technologies, Printing Technologies, Finishing Technologies, Chemical Treatments |
| Companies Covered | BASF SE, Huntsman International LLC, Dow Inc., Evonik Industries AG, Sumitomo Chemical Co., Ltd., Archroma, OMNOVA Solutions Inc., Wacker Chemie AG, NICCA Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Textile Finishing Chemicals Market Evolving Landscape
Digital process control and closed-loop chemistry management are compressing batch variability and enabling mass customization of finish recipes at industrial scale.
Plasma surface treatment is automating the activation of synthetic fiber surfaces prior to chemical finishing, eliminating wet pretreatment stages and reducing water consumption by textile mills in Germany and Japan. Automotive interior suppliers are adopting this technology to achieve consistent adhesion of anti-soil finishes on recycled polyester substrates. The capital cost per treatment line is automating the displacement of manual spray booths in tier-one seating plants.
ECHA REACH restrictions on C8-based fluorotelomers are forcing European finishers to validate short-chain alternatives through notified body assessment, extending product registration timelines by 18-24 months. German and Italian formulators are absorbing these costs to maintain access to outdoor apparel brands with EU manufacturing footprints. The regulatory friction is compressing margins on commodity water-repellent chemistries while concentrating premium positioning among dossier-ready suppliers.
Athletic wear brands are consolidating finish suppliers around vertically integrated partners who control polymer synthesis through to application testing, displacing fragmented distributor networks. This procurement consolidation is visible most acutely in Vietnam and Bangladesh, where cut-make-trim factories now specify approved chemical lists from parent brand headquarters. The shift is compressing switching flexibility and locking in volume commitments with BASF, Huntsman, and Dow formulation portfolios.
Functional Textile Finishing Chemicals Market Segmentation
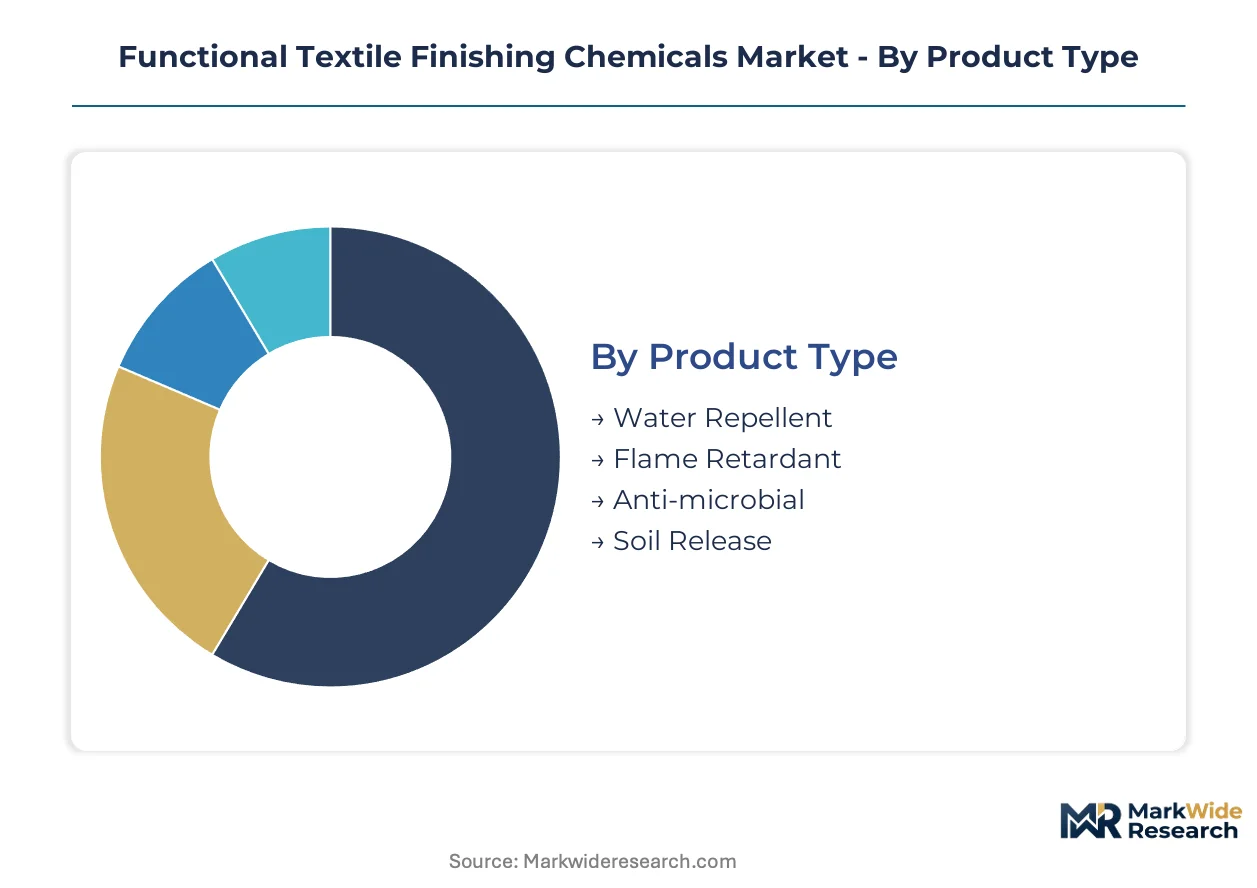
Segmentation in functional textile finishing chemicals reveals how formulation chemistry, application method, and end-use specifications create distinct margin tiers. Suppliers must align R&D pipelines with the technical validation requirements of each segment to avoid stranded capacity.
Product Type:
Volume concentrates in commodity softeners, while premium pricing attaches to certified biocidal and high-durability formulations.
- Anti-microbial:Biocidal formulations incorporating silver-ion or quaternary ammonium compounds deliver validated efficacy against hospital-acquired pathogens. Demand concentrates in healthcare laundries and athletic wear supply chains where hygiene protocols mandate certified treatments.
- Water Repellent:Fluorine-free polymer backbones and short-chain fluorotelomer alternatives now dominate new product registrations, though performance gaps persist against legacy C8 systems in oil repellency. European outdoor apparel brands are absorbing reformulation costs to maintain EU market access.
- Flame Retardant:Halogen-free phosphorus-nitrogen systems meeting ASTM D6413 specifications for limited flame spread.
- Soil Release:Hydrophilic finish systems that facilitate stain removal during industrial laundering cycles.
Today's leader: Anti-microbial. Tomorrow's challenger: Water repellent.
Application:
Technical specifications separate industrial-grade durability requirements from consumer-facing comfort and aesthetics.
- Technical Fabrics:Industrial filtration media and geotextile applications demand hydrophobic finishes surviving mechanical stress and chemical cleaning. Specifications tightening on UV stability and wash durability are pulling formulation innovation toward cross-linked polymer architectures.
- Athletic Wear:Moisture-wicking and anti-odor finishes with launderable durability dominate procurement from Vietnam and Bangladesh cut-make-trim factories. Brand headquarters now specify approved chemical lists, consolidating supplier relationships around vertically integrated partners.
- Protective Clothing:Multi-hazard finishes combining flame resistance with chemical splash protection for industrial safety compliance.
- Home Textiles:Stain-resistant and easy-care finishes for upholstery and bedding applications.
Technical fabrics command the steepest expansion trajectory as infrastructure investment scales. Athletic wear retains the largest absolute volume.
End User:
Procurement authority separates formulation-specifying brands from toll-finishing textile manufacturers.
- Apparel Brands:Headquarters-controlled chemical approval lists now govern finishing chemical selection at third-party mills. This procurement consolidation locks volume commitments with dossier-ready suppliers who control polymer synthesis through application testing.
- Textile Manufacturers:Toll finishers in China and India face MEE emissions thresholds and PLI scheme incentives respectively, redirecting capital toward low-temperature cure systems.
- Industrial Textile Providers:Specification-driven procurement for filtration, geosynthetic, and automotive interior applications.
- Home Furnishing Companies:Volume contracting for stain-resistant upholstery and bedding finishes.
Apparel brands dictate formulation choices. Textile manufacturers execute under transferred specifications.
Technology:
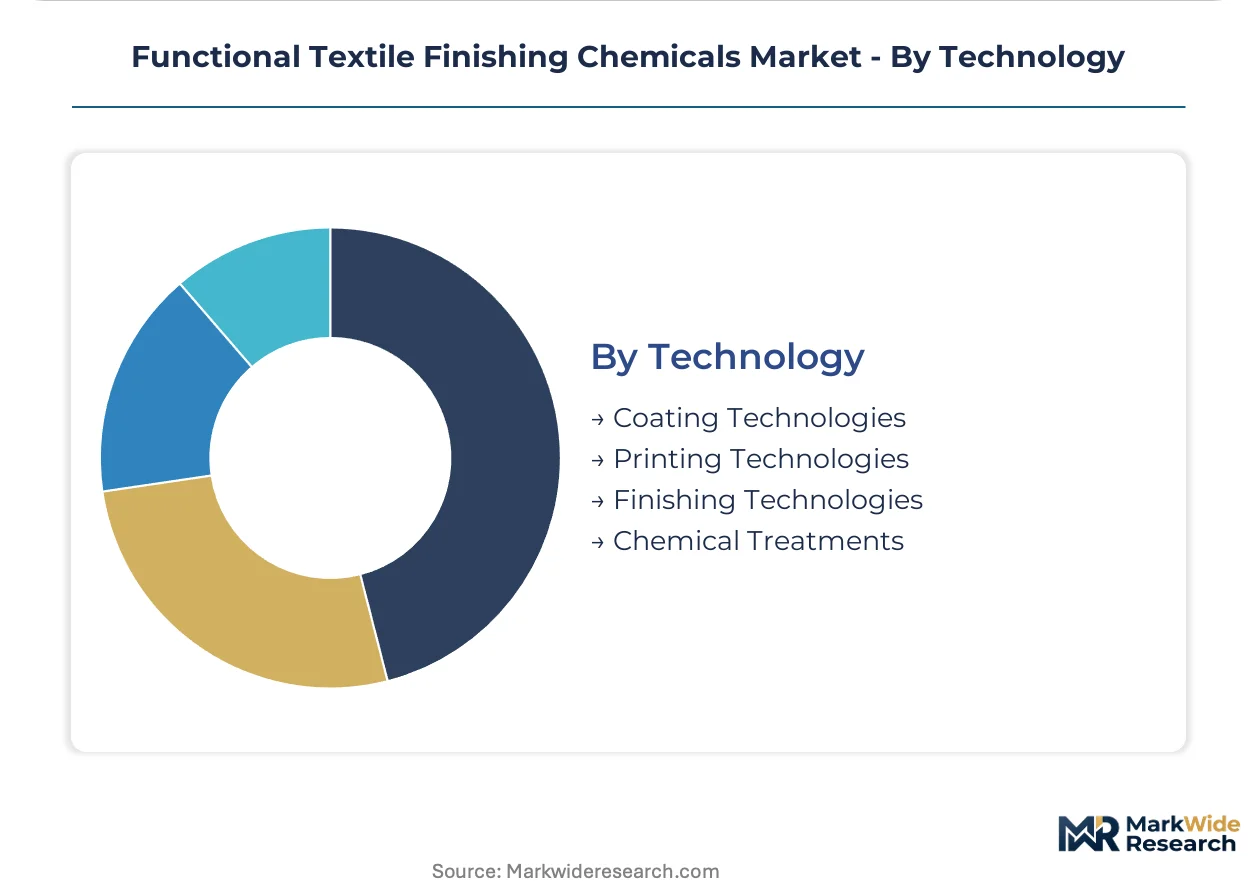
Capital intensity and formulation know-how barriers concentrate margin in coating and advanced finishing systems.
- Coating Technologies:Slot-die and rotary screen application equipment requires seven-figure investments with long depreciation cycles. This capital threshold filters out mid-scale entrants from technical fabric segments where precise add-on rates determine performance compliance.
- Finishing Technologies:Pad-dry-cure and exhaust application methods dominate cotton and synthetic substrate processing. Low-temperature cure variants are gaining procurement preference in China as MEE enforcement tightens emissions thresholds at finishing mills.
- Chemical Treatments:Plasma surface activation prior to chemical finishing eliminates wet pretreatment stages, reducing water consumption in German and Japanese textile operations.
- Printing Technologies:Digital and rotary screen methods for localized functional finishing on garment panels.
Coating technologies defend margin concentration. Finishing technologies capture volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemists with expertise in hydrophobic surface engineering cluster in Germany, Japan, and the United States, anchoring formulation innovation for water-repellent alternatives. Technical fabric mills in China and Vietnam absorb the largest volumes of finishing chemicals for export-market compliance. Regulatory divergence across EPA, ECHA, and China MEE jurisdictions forces parallel registration strategies that extend time-to-market.
China
Domestic technical fabric output for industrial filtration and geotextile exports scales rapidly, pulling demand for durable hydrophobic finishes. MEE enforcement of dual carbon goals tightens emissions thresholds at finishing mills in Zhejiang and Jiangsu provinces, redirecting procurement toward low-temperature cure systems. The Yangtze River Delta concentration of textile manufacturers faces rising compliance costs that filter smaller finishers from contract eligibility.
Germany
Automotive interior suppliers and industrial filtration specialists drive specification-grade demand for plasma-activated finishes with consistent adhesion properties. ECHA REACH restrictions on C8-based fluorotelomers force notified body assessment of short-chain alternatives, extending registration timelines by 18-24 months. The textile chemistry cluster around Leverkusen and Ludwigshafen absorbs these compliance costs to maintain access to outdoor apparel brands with EU manufacturing footprints.
United States
Athletic wear headquarters in Portland and Boston specify approved chemical lists that govern finishing selection at third-party mills in Vietnam and Bangladesh. EPA scrutiny of long-chain perfluoroalkyl substances under TSCA Section 6 shapes product registration requirements for suppliers targeting the US market. The Southeast textile corridor faces reformulation pressure as brand compliance timelines diverge from legacy chemistry deprecation schedules.
Vietnam
Cut-make-trim factories process the largest volumes of moisture-wicking and anti-odor finishes for export to North American and European athletic wear brands. Procurement consolidation around vertically integrated chemical suppliers locks volume commitments and compresses switching flexibility. The Ho Chi Minh City industrial zone concentrates finishing operations that execute specifications transferred from brand headquarters.
India
PLI scheme incentives for domestic technical fabric manufacturing create demand for finishing chemicals meeting export-market certification requirements. Toll finishers in Tamil Nadu and Gujarat redirect capital toward low-temperature cure systems to align with emerging emissions norms. The technical textile expansion concentrates procurement authority with integrated suppliers controlling polymer synthesis through application testing.
Functional Textile Finishing Chemicals Market Competitive Landscape
Top-tier vendors anchor premium formulation tiers, while mid-scale distributors face compression from procurement consolidation at brand headquarters. The supplier base stratifies across integrated polymer producers, specialized finishing auxiliaries manufacturers, and regional toll compounders. Strategic archetypes include dossier-ready multinationals with notified body capabilities, vertically integrated partners spanning synthesis to application testing, and technology licensors monetizing proprietary cure systems. Competitive moves concentrate on backward integration into polymer backbones and geographic co-location with technical fabric clusters.
Within the integrated multinational tier, BASF SE, Huntsman International LLC, and Dow Inc. occupy positions that exemplify divergent technology bets. BASF SE leverages polymer R&D pipelines for durable water-repellent alternatives. Huntsman International LLC anchors market presence through integrated finishing auxiliaries spanning pretreatment through final coating. Dow Inc. competes via silicone-based softeners that occupy technical fabric channels with consistent batch performance. These three represent the procurement consolidation pattern visible in Vietnam and Bangladesh, where brand headquarters now specify approved chemical lists that lock volume commitments.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman International LLC |
| Dow Inc. |
| Evonik Industries AG |
| Sumitomo Chemical Co., Ltd. |
| Archroma |
| OMNOVA Solutions Inc. |
| Wacker Chemie AG |
| NICCA Chemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
The fluorine-free versus C8-based performance gap bifurcates formulation tiers into premium dossier-ready suppliers and commodity finishers, concentrating pricing power with BASF, Huntsman, and Dow while compressing margins among distributors lacking polymer synthesis capabilities. This tier divergence manifests in supply chain configurations where brand headquarters in Portland and Boston specify approved chemical lists that lock volume commitments with integrated partners, displacing fragmented sourcing networks in Vietnam and Bangladesh.
Pricing Analysis
Bundle-unbundle service splits separate formulation-only supply from integrated application-testing packages, with premium suppliers commanding higher attach rates for technical support and notified body dossier preparation. Price differentiation rests on REACH compliance certification and low-temperature cure system performance, with European outdoor apparel brands absorbing reformulation premiums to maintain EU market access. Pricing pressure stems from MEE emissions enforcement in China redirecting procurement toward energy-efficient cure systems at margin sacrifice. Toll finishers in Zhejiang and Jiangsu provinces exhibit acute price sensitivity, while apparel brand headquarters prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Shanghai anchor hub-and-spoke patterns for finishing chemical logistics, with German and Italian formulators maintaining EU market access through notified body-certified inventory positioning. Raw material dependencies draw from Asian petrochemical suppliers for silicone softener precursors and specialized polymer backbones, creating single-source vulnerability during freight allocation disruptions. Distribution runs through vertically integrated partners who control synthesis through application testing, compressing switching flexibility at cut-make-trim factories. The capital intensity of slot-die and rotary screen coating equipment filters mid-scale entrants from technical fabric segments where precise add-on rates determine performance compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional textile finishing chemicals market represents a late-cycle quality story as healthcare hygiene protocols and athletic wear performance specifications shift procurement toward certified biocidal and durable water-repellent formulations with validated efficacy data.
For Market Incumbents: To counter procurement consolidation at brand headquarters, BASF and Huntsman should deepen backward integration into fluorine-free polymer backbones while expanding notified body dossier capabilities to defend premium positioning. Capacity co-location with Yangtze River Delta technical fabric clusters reduces logistics exposure and tightens specification control with apparel brand procurement teams. For New Entrants and Emerging Players: Launch via toll-finishing partnerships in Tamil Nadu and Gujarat to capture PLI scheme-driven technical textile expansion without seven-figure coating line investments. White-space targets include low-temperature cure system distribution for MEE-compliant mills and plasma-activated finishing services for automotive interior suppliers in Germany seeking water consumption reductions. For Investors and Strategic Acquirers: Asymmetric upside sits with dossier-ready mid-scale formulators possessing ECHA REACH short-chain validation and established brand-approved chemical list positioning. Long-term viability hinges on regulatory compliance moats rather than commodity volume scale. Watch for EPA TSCA Section 6 enforcement acceleration as an inflection signal for US-market reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Backbones | Captures margin concentration in fluorine-free water-repellent formulations as REACH restrictions accelerate. |
| Notified Body Dossier Investment | Secures 18-24 month registration timelines for short-chain alternatives in EU outdoor apparel supply chains. |
| Low-Temperature Cure System Development | Aligns with MEE dual carbon enforcement redirecting procurement at Zhejiang and Jiangsu finishing mills. |
| Plasma Surface Treatment Deployment | Eliminates wet pretreatment stages for German automotive interior suppliers targeting water consumption reductions. |
| Technical Fabric Cluster Co-location | Reduces freight cost volatility exposure while tightening specification control with Vietnam and Bangladesh CMT factories. |
Research Methodology
Multiple input streams — technical R&D directors at integrated chemical suppliers, procurement leads at Vietnam cut-make-trim factories, plant managers at Zhejiang finishing mills, and regulatory affairs specialists at notified bodies — were reconciled against secondary validation from ECHA REACH registration databases, SEC 10-K chemical segment disclosures, China MEE emissions compliance filings, and ACC/Cefic specialty chemical trade data. Bottom-up volume estimates from application-specific consumption rates were triangulated with top-down market sizing derived from technical fabric production statistics and finish add-on rate benchmarks.
Data-stream reconciliation across product type, application method, end-use industry, and regional regulatory cluster dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis calibrated to infrastructure investment trajectories in industrial filtration and geotextile specifications, with athletic wear hygiene protocol tightening and automotive interior plasma treatment adoption serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA TSCA Section 6 enforcement acceleration or China MEE emissions threshold recalibration. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that reformulation timelines and notified body assessment durations may compress or extend competitive positioning windows for specific supplier archetypes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market