
 Tarpaulin Sheets Market | 2026-2036
Tarpaulin Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Tarpaulin Sheets Market Outlook
Buyer concentration in the transportation logistics sector is pivoting toward large fleet operators and third-party logistics providers that negotiate multi-year supply contracts. SRF Limited leverages its integrated polymer film operations to secure bulk orders from these consolidated buyers. Heytex Brandenburger GmbH anchors its position through specialized PVC-coated fabrics engineered for extreme weather endurance. Shur-Co LLC competes by controlling the North American automated tarping systems channel, bundling hardware with consumable sheet replacements.
Tarpaulin sheets are woven or extruded polymer fabrics, typically polyethylene or PVC, treated with UV stabilizers and laminated to achieve tear strengths exceeding 300 N/5cm for industrial grades; they function primarily as protective barriers against moisture, abrasion, and solar degradation in outdoor storage and transit applications. Polyethylene dominates volume across the product type dimension due to its cost position in agricultural ground cover and temporary shelter applications, while PVC commands margin pools in heavy-duty cargo protection where flame-retardant certification commands price premiums. The thickness dimension shows extra heavy-duty grades recording the fastest trajectory as mining and military end users specify reinforced weave constructions for extended field deployment cycles.
EPA regulations on volatile organic compound emissions from PVC coating facilities are reshaping domestic manufacturing compliance costs in the United States, while REACH restrictions on phthalate plasticizers in Europe are accelerating reformulation investments across the supply base. China's MEE enforcement of dual carbon goals is pressuring energy-intensive calendering operations to adopt cleaner thermal processes or relocate capacity. Stakeholders must monitor how divergent regional chemical safety frameworks fragment material specifications and determine whether to maintain multiple product variants or consolidate around universally compliant base formulations.
Market Dynamics
Construction procurement is pivoting toward reinforced polyethylene grades as infrastructure spending accelerates replacement cycles for heavy-duty covers, tightening material certification requirements across multiple jurisdictions simultaneously.
Growth Catalysts
- REACH compliance mandates:European ECHA restrictions on phthalate plasticizers are accelerating reformulation investments toward bio-based stabilizers, pulling demand for certified-compliant sheet grades.
- Agricultural mechanization:India's tractor-mounted implement covers and grain storage bunkers are driving procurement of UV-stabilized woven PE at volumes exceeding traditional hand-laid alternatives.
- Dual carbon enforcement:China's MEE pressure on energy-intensive calendering operations is consolidating capacity around cleaner thermal processes, advantaging suppliers with captive renewable power.
Market Restraints
- Ethylene feedstock volatility:Crude-linked polyethylene resin costs swing tarpaulin sheet margins unpredictably, squeezing converters without long-term offtake agreements with integrated petrochemical suppliers.
- Calendering concentration:Heavy-duty PVC-coated fabric production clusters in Shandong and Zhejiang provinces, creating geographic single-point vulnerability for flame-retardant certified grades.
- Woven PP substitution:Polypropylene ground covers compete on price in temporary shelter applications, compressing PE tarpaulin volumes in price-sensitive agricultural segments.
Strategic Opportunities
- Rural electrification corridors:India's transmission infrastructure expansion creates demand for equipment weatherization covers in Maharashtra and Gujarat, where local fabricators lack certified supply.
- Automated tarping convergence:Integration of RFID-tagged sheets with fleet management systems enables usage-based replacement contracts, opening recurring revenue streams for integrated hardware-software vendors.
- EU Green Deal procurement rules:Public infrastructure tenders now mandate recycled content thresholds, rewarding converters with verified post-industrial PE feedstock streams.
Industry Challenges
- Multijurisdictional certification timelines:Simultaneous EPA VOC compliance, REACH SVHC screening, and GB standard testing extends product launch cycles by 8-14 months for cross-border suppliers.
- Lamination technician scarcity:Skilled operators for hot-melt adhesive bonding of multi-layer constructions are retiring faster than vocational programs replace them, constraining quality-consistency at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tarpaulin Sheets Market |
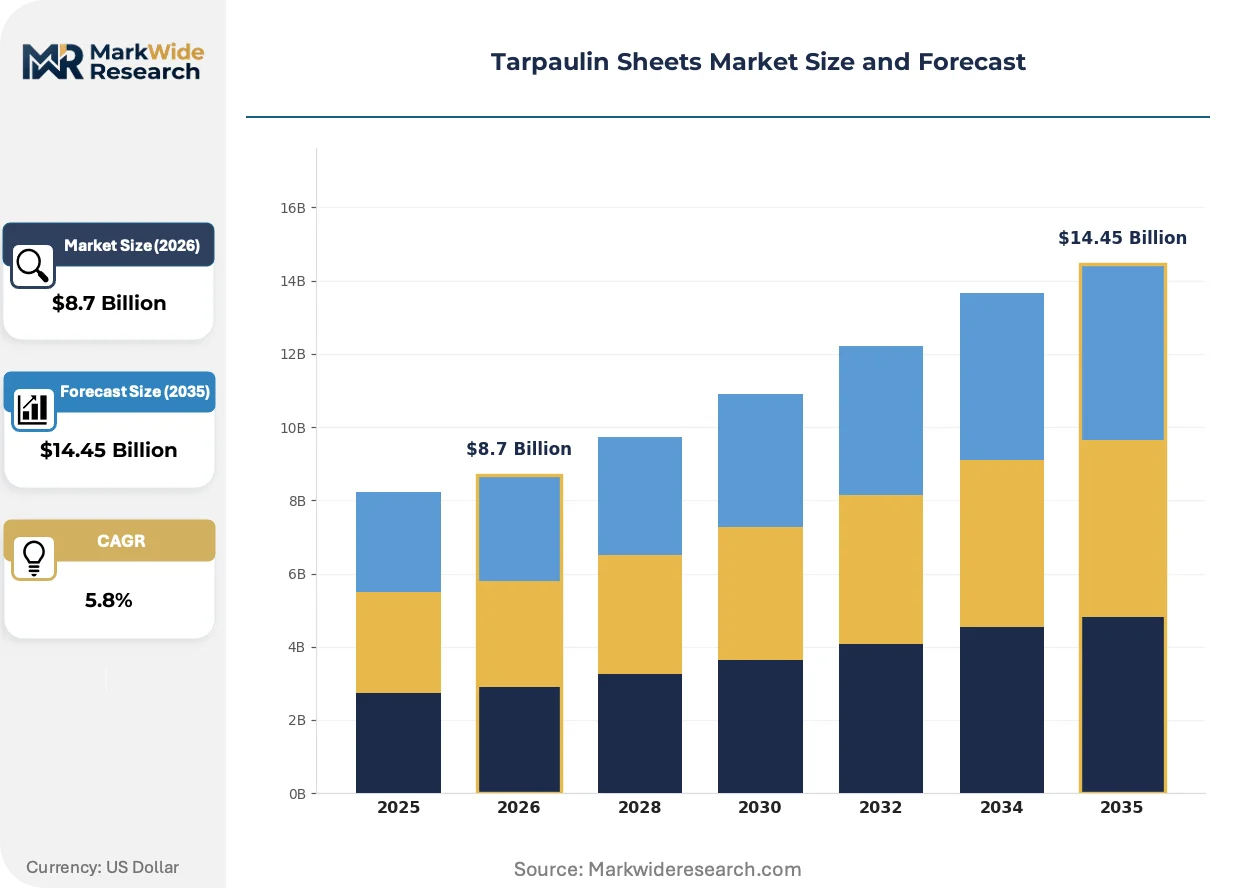
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, PVC, Canvas, Canvas-composite End User: Agriculture, Construction, Transportation, Outdoor Events Thickness: Lightweight, Medium, Heavy-duty, Extra Heavy-duty Application: Covering, Cargo Protection, Temporary Shelters, Ground Cover |
| Companies Covered | SRF Limited, Heytex Brandenburger GmbH, Sioen Industries, Shur-Co LLC, Puyoung Industrial Corporation, DERFLEX, Cunningham Covers, Canadian Tarpaulin Manufacturers, Seaman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tarpaulin Sheets Market Strategic Shifts
Material science advances and regulatory fragmentation are compressing product lifecycles while opening premium tiers for certified-performance grades. Three developments merit close attention.
Co-extruded multilayer polyethylene constructions with embedded scrim reinforcement are overtaking traditional single-ply laminates in mining and military shelter applications. Australian and Chilean mining contractors specify these grades for 36-month field deployment cycles. The technology is overtaking conventional woven alternatives by eliminating delamination failure modes in high-solar-load environments.
EPA regulations on volatile organic compound emissions from PVC coating facilities are reshaping domestic manufacturing compliance costs in the United States. Facility upgrades for thermal oxidizer installation or solvent recovery systems absorb capital that smaller converters cannot access. California and Texas-based producers are responding by consolidating coating operations or exiting the heavy-duty cargo protection segment entirely.
Third-party logistics providers now negotiate multi-year supply contracts bundling hardware systems with consumable sheet replacements, displacing spot-market purchasing. This consolidation concentrates procurement power among fleet operators with 500+ vehicle counts. The shift is most visible in North American flatbed trucking, where automated tarping system penetration exceeds 40 percent among top-20 carriers.
Tarpaulin Sheets Market Segmentation
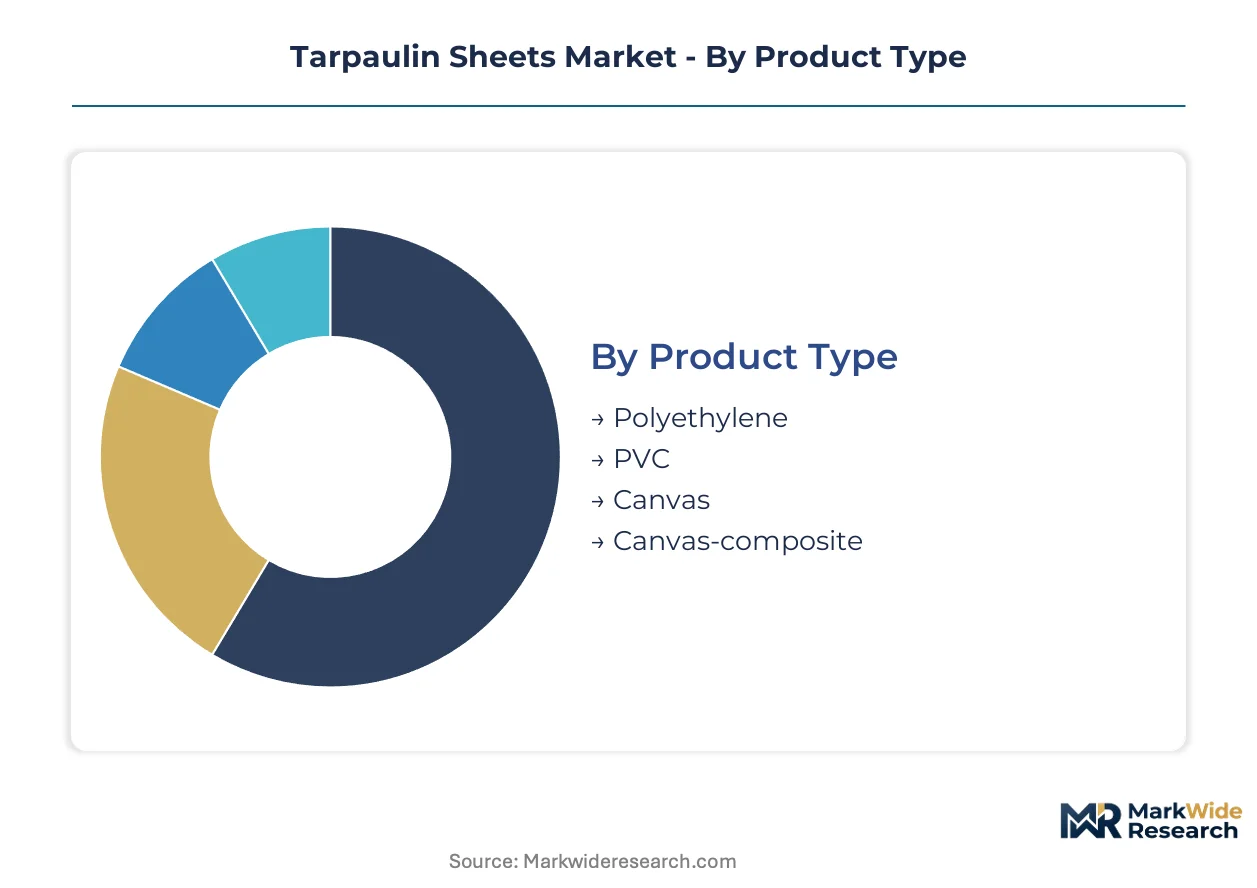
Material specifications and duty ratings determine replacement cycles across tarpaulin applications. Procurement patterns diverge sharply between cost-driven agricultural buyers and certification-focused industrial users.
Product Type:
Upgrade cycles vary by polymer chemistry, with UV stabilization requirements and weave density dictating field service life in exposed deployments.
- Polyethylene:Woven or extruded HDPE substrates laminated with LDPE coatings achieve tear strengths of 150-400 N/5cm depending on scrim count. India's agricultural mechanization programs are accelerating procurement of UV-stabilized PE grades for tractor-mounted implement covers and grain storage bunkers, displacing traditional hand-laid alternatives.
- PVC:Calendered vinyl-coated polyester fabrics with flame-retardant certification command premium positioning in heavy-duty cargo protection. REACH restrictions on phthalate plasticizers are forcing reformulation investments toward bio-based stabilizers, pulling demand for certified-compliant sheet grades in European transportation logistics.
- Canvas:Cotton or hemp-based woven substrates treated with wax or synthetic resins persist in heritage marine and military applications requiring breathability.
- Canvas-composite:Hybrid constructions bonding natural fiber faces to synthetic scrim cores balance biodegradability concerns with dimensional stability.
Volume placements concentrate in Polyethylene; the faster expansion belongs to PVC.
End User:
Customer procurement sophistication separates spot-market purchasers from integrated supply contract negotiators.
- Agriculture:India's infrastructure spending and rural electrification corridors in Maharashtra and Gujarat are driving equipment weatherization cover demand where local fabricators lack certified supply.
- Construction:Reinforced polyethylene grades dominate infrastructure spending acceleration for heavy-duty covers, with multijurisdictional certification timelines extending product launch cycles.
- Transportation:Third-party logistics providers negotiate multi-year supply contracts bundling hardware systems with consumable sheet replacements, displacing spot-market purchasing among fleet operators.
- Outdoor Events:Temporary shelter specifications prioritize rapid deployment and compact storage over extended durability.
Procurement scale peaks in Transportation; margin expansion is steepest in Construction.
Thickness:
Duty ratings correlate directly with weave density, coating weight, and reinforcement scrim configuration.
- Lightweight:Single-ply laminates below 120 gsm serve short-duration covering needs with minimal capital outlay.
- Medium:Dual-layer constructions with embedded scrim reinforcement balance cost against 12-18 month service intervals.
- Heavy-duty:Mining contractors in Australia and Chile specify these grades for 24-month field deployment cycles with co-extruded multilayer polyethylene constructions.
- Extra Heavy-duty:Reinforced weave constructions with tear strengths exceeding 500 N/5cm support military shelter applications requiring 36-month continuous exposure tolerance.
Unit economics favor Medium grades; specification intensity climbs fastest in Extra Heavy-duty.
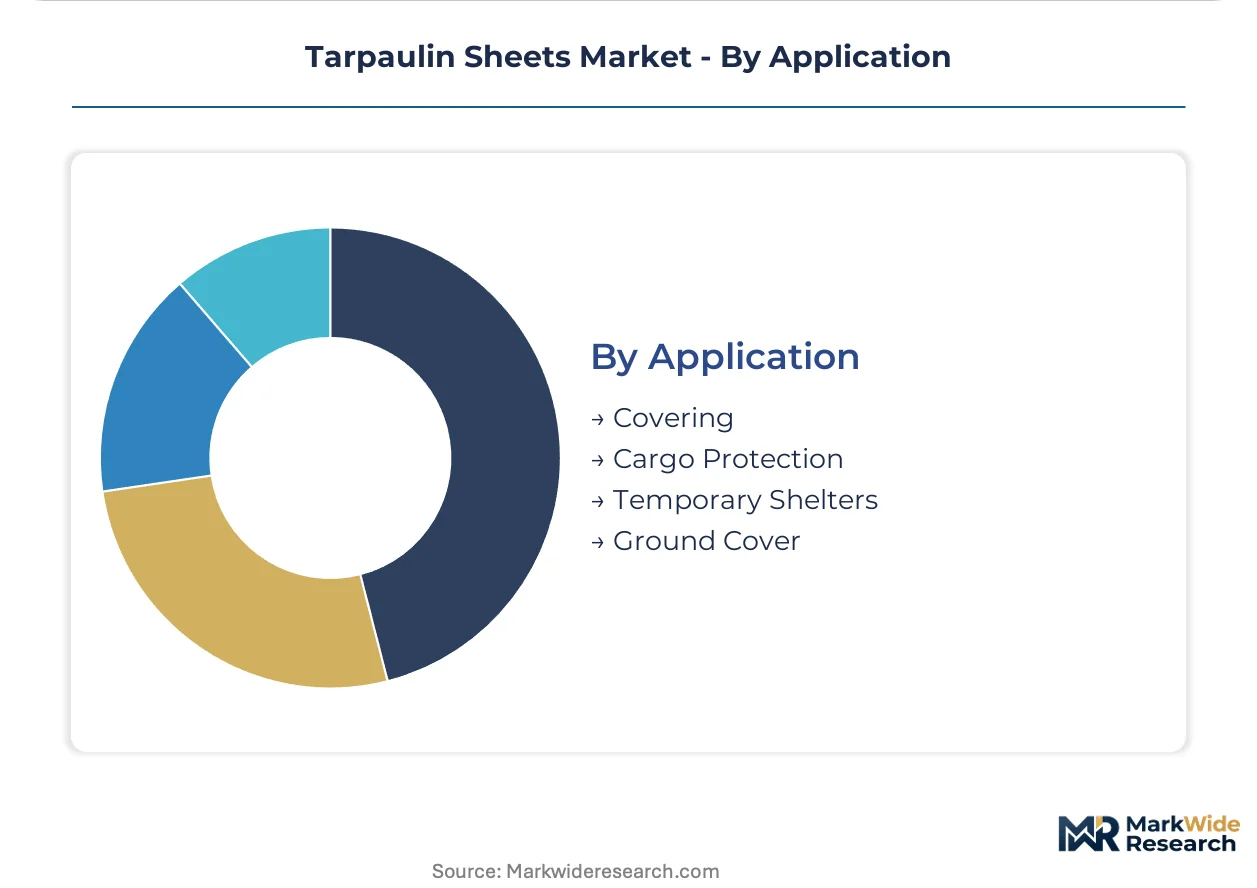
Application:
Functional requirements determine material selection more than price sensitivity in industrial segments.
- Covering:General protective deployment against moisture and solar degradation spans all polymer grades.
- Cargo Protection:Flame-retardant certification and automated tarping system compatibility dominate North American flatbed trucking procurement.
- Temporary Shelters:Rapid assembly protocols favor lightweight polyethylene with grommet reinforcement patterns.
- Ground Cover:Woven polypropylene competes aggressively on price, compressing polyethylene volumes in price-sensitive agricultural segments.
Shipment volumes anchor in Covering; technology integration proceeds fastest in Cargo Protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand acceleration through infrastructure spending and agricultural mechanization programs, while regulatory fragmentation across the United States, Germany, and China forces suppliers to maintain multiple certification pathways simultaneously.
United States
Transportation logistics consolidation drives multi-year supply contracts among fleet operators with automated tarping systems. EPA regulations on volatile organic compound emissions from PVC coating facilities reshape domestic manufacturing compliance costs. California and Texas-based producers respond by consolidating coating operations or exiting heavy-duty cargo protection segments.
Germany
REACH restrictions on phthalate plasticizers accelerate reformulation investments toward bio-based stabilizers in European transportation logistics. Heytex Brandenburger GmbH anchors positioning through specialized PVC-coated fabrics engineered for extreme weather endurance. The country's central European location enables distribution coverage across EU Green Deal procurement corridors.
China
MEE enforcement of dual carbon goals pressures energy-intensive calendering operations to adopt cleaner thermal processes or relocate capacity. Shandong and Zhejiang provinces cluster heavy-duty PVC-coated fabric production, creating geographic single-point vulnerability for flame-retardant certified grades. GB standards evolution tightens material certification requirements for domestic infrastructure procurement.
India
Rural electrification corridors in Maharashtra and Gujarat create demand for equipment weatherization covers where local fabricators lack certified supply. BIS certification requirements and PLI scheme incentives accelerate formalization of previously informal tarpaulin fabrication. SRF Limited leverages integrated polymer film operations to secure bulk orders from consolidated agricultural and logistics buyers.
Australia
Mining contractors specify co-extruded multilayer polyethylene constructions for 36-month field deployment cycles in high-solar-load environments. The country's national environmental regulator maintains strict VOC emission standards for industrial coating operations. Perth and Queensland mining clusters drive specification intensity for extra heavy-duty grades with tear strengths exceeding 500 N/5cm.
Tarpaulin Sheets Market Competitive Environment
Indian producers anchor one tier through integrated polymer operations; German and Belgian specialists hold premium positioning in certified-performance grades. The vendor base separates into three strategic archetypes: petrochemical-integrated converters with captive resin supply, regional fabricators serving spot agricultural demand, and hardware-software bundlers controlling automated tarping channels. Competitive moves concentrate on backward integration into resin supply and geographic expansion through distribution partnerships.
Among Asia-Pacific-based fabricators, SRF Limited represents the integrated-converter archetype with captive polymer film operations. Heytex Brandenburger GmbH and Shur-Co LLC occupy positions on the premium-hardware vector, with the German GmbH exemplifying specialized coating expertise and the LLC anchoring North American automated system penetration. These three names illustrate how competitive positioning fragments across supply chain control points rather than product specifications alone.
| Leading Market Players |
|---|
| SRF Limited |
| Heytex Brandenburger GmbH |
| Sioen Industries |
| Shur-Co LLC |
| Puyoung Industrial Corporation |
| DERFLEX |
| Cunningham Covers |
| Canadian Tarpaulin Manufacturers |
| Seaman Corporation |
| Others |
Value Chain & Pricing Dynamics
Co-extruded multilayer polyethylene constructions are displacing conventional single-ply laminates across mining and military procurement, simultaneously elevating material cost structures and consolidating production among converters with captive scrim-weaving capabilities. This technology transition concentrates pricing power with integrated manufacturers while spot-market buyers face compressed margins on legacy grades.
Pricing Analysis
Volume placements concentrate in economy-grade polyethylene for agricultural ground cover, while margin pools concentrate in flame-retardant PVC certified for European transportation logistics. Price differentiation hinges on REACH-compliant stabilizer formulations and automated tarping system compatibility. Cost compression in standard-grade PE is intensifying because woven polypropylene substitutes compete aggressively on price in temporary shelter applications. Agricultural buyers exhibit highest price sensitivity, while mining contractors in Australia and Chile demonstrate lowest sensitivity due to 36-month replacement cycle specifications.
Supply Chain Analysis
Direct-to-fleet channels handle consolidated third-party logistics demand, while spot-market distributors serve fragmented agricultural procurement. Raw material supply draws from ethylene production clusters in the United States, Saudi Arabia, and China, with PVC resin sourcing tethered to Shandong and Zhejiang calendering operations. Lamination adhesives and UV stabilizer masterbatches rest on specialized chemical intermediate supply. Geographic concentration in Chinese coastal provinces creates single-point vulnerability for flame-retardant certified grades. Distribution runs through regional fabricator networks in India and integrated polymer film operations for bulk industrial contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tarpaulin sheets market functions as a cost-of-compliance arena where REACH phthalate restrictions and EPA VOC regulations erect certification barriers that favor incumbents with reformulation capital and multi-jurisdictional testing infrastructure.
For Market Incumbents: Cement market position by acquiring distressed PVC coating capacity in Texas and California as smaller converters exit under EPA compliance cost pressure. Prioritize backward integration into UV stabilizer masterbatch production to secure formulation flexibility against REACH-driven raw material substitution cycles.
For New Entrants and Emerging Players: Launch via certified supply partnerships with Indian state electricity boards in Maharashtra and Gujarat rural electrification corridors, where local fabricators lack BIS-compliant production. Target equipment weatherization cover procurement through PLI scheme-linked tenders as the most penetrable entry vector.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by petrochemical-integrated converters seeking geographic expansion. Long-term viability favors targets with verified post-industrial PE feedstock streams aligned to EU Green Deal procurement thresholds. Monitor ECHA SVHC candidate list expansion as the critical signal for reformulation investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Masterbatch Production | Captive UV stabilizer supply insulates margins from REACH-driven raw material substitution cycles. |
| Automated Tarping System Partnership | Hardware-software bundling locks in recurring sheet replacement revenue from fleet operators. |
| Post-Industrial PE Feedstock Certification | Verified recycling streams unlock EU Green Deal public infrastructure tender eligibility. |
| Multi-Jurisdictional Testing Infrastructure | Simultaneous EPA, REACH, and GB standard capability compresses product launch timelines. |
| Geographic Expansion via Distribution Partnership | Local fabricator alliances in Indian certification-deficient corridors capture infrastructure spending flows. |
Study Parameters
Document review covered customs and trade data, SEC filings from petrochemical-integrated converters, and BIS certification registries, complemented by interviews with plant managers at coating facilities, procurement leads at third-party logistics providers, distribution channel partners in Indian agricultural supply networks, and technical R&D directors at polymer film operations. Secondary validation drew from EPA enforcement actions, ECHA restriction proposals, and MEE dual carbon policy circulars. Bottom-up shipment estimates and top-down petrochemical consumption patterns were triangulated to establish market sizing.
Segment-level projections across material type, duty rating, end-use industry, and regional regulatory cluster were generated through the analysis window. CAGRs were derived from replacement cycle analysis by application intensity and infrastructure spending correlation models. Key inputs included tractor-mounted implement cover procurement data from Indian agricultural mechanization programs and mining shelter deployment specifications from Australian and Chilean contractors.
Ethylene feedstock volatility, phthalate restriction list expansion, and woven polypropylene substitution acceleration are the dominant revision risks to installed base forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Global Industrial Fabric Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Industrial Laundry Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Textile Printer Market