
 Tarpaulin Market | 2026-2036
Tarpaulin Market Size, Share, and Industry Trends Forecast 2026-2036
Tarpaulin Market Analysis
Recurring maintenance and repair service contracts for industrial-grade tarpaulin installations is shifting how manufacturers monetize long-term customer relationships. Sioen Industries leverages captive coating technology to anchor premium positioning in European marine and defense applications. Heytex Brandenburger GmbH sustains R&D intensity in textile-laminate composites, while Naizil Canada Inc. dominates North American transportation cover segments through controlled distribution networks.
Tarpaulin denotes a heavy-duty flexible sheet engineered from woven polyethylene, PVC-coated polyester, or canvas duck cloth, typically rated by denier count and tensile strength for load-bearing and weatherproofing functions. Polyethylene grades lead volume due to cost efficiency in disposable agricultural and construction applications, while vinyl commands margin pools in military and transportation sectors requiring UV stabilization and weld-seam integrity. Mesh variants compete in wind-permeable scaffolding and event signage where custom printing capabilities differentiate suppliers.
EPA guidelines on vinyl chloride emissions and REACH restrictions on phthalate plasticizers constrain formulation choices for PVC-based products in North America and Europe, while India's BIS certification mandates GSM thresholds for agricultural tarpaulin distributed through government subsidy programs. China's GB standards enforce flame-retardant ratings for construction-site deployments. Stakeholders must monitor evolving chemical compliance calendars and regional subsidy eligibility to align capacity investments with accessible demand pools.
Market Dynamics
REACH restrictions on phthalate plasticizers and EPA vinyl chloride emission limits are forcing PVC-coated polyester producers to reformulate entire product lines, while monsoon-driven agricultural demand in India strains regional supply chains and compresses lead times for heavy-duty polyethylene grades.
Growth Catalysts
- Flame-retardant mandates:China's GB standards for construction-site deployments are accelerating procurement of certified vinyl grades by scaffolding and temporary shelter contractors across Guangdong and Jiangsu provinces.
- India:BIS certification requirements for GSM thresholds in agricultural tarpaulin distributed through government subsidy programs are formalizing quality tiers and consolidating procurement toward certified domestic mills.
- Weld-seam automation:Radio-frequency welding systems are displacing sewn seams in transportation cover manufacturing, improving load-bearing integrity for flatbed and container applications.
Market Restraints
- Crude-linked resin volatility:Polyethylene and PVC resin prices track naphtha and ethylene feedstock swings, compressing margin visibility for converters on quarterly contract resets.
- Coating concentration:Captive coating capacity clusters among three European integrated textile producers, creating supply bottleneck risk for independent cut-and-sew operations.
- Canvas substitution:Natural fiber duck cloth retains niche demand in heritage marine and military specifications, limiting volume expansion for synthetic alternatives in premium segments.
Strategic Opportunities
- Repair and refurbishment services:Industrial installation maintenance contracts are creating recurring revenue streams for manufacturers with field service networks in North American transportation and logistics sectors.
- UV-stabilized vinyl:Extended-warranty offerings on UV-resistant grades for Middle East construction and event infrastructure are differentiating suppliers in high-insolation climates.
- Digital printing compatibility:Mesh substrate formulations compatible with solvent and UV-cure wide-format printers are opening event signage and temporary branding applications.
Industry Challenges
- Formulation chemistry expertise:Replacement of legacy phthalate plasticizers with bio-based or non-phthalate alternatives requires polymer science capabilities scarce among mid-tier converters.
- Certification timeline compression:BIS and REACH compliance testing cycles extend 14-22 weeks, delaying market entry for reformulated products during peak agricultural procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tarpaulin Market |
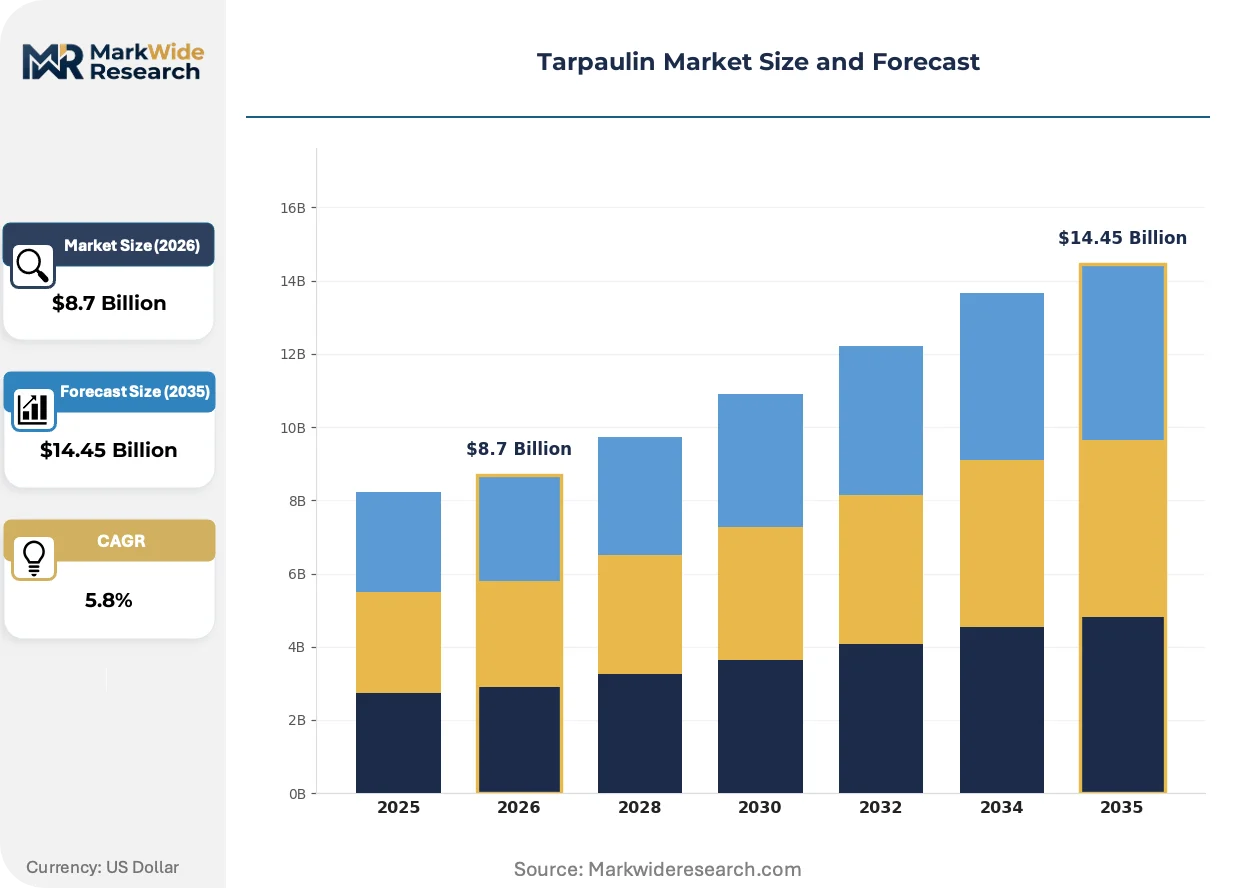
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Canvas, Vinyl, Mesh End User: Agriculture, Construction, Transportation, Events Application: Covering, Protection, Custom Printing, Camping Distribution Channel: Online Retail, Wholesale, Direct Sales, Others |
| Companies Covered | Sioen Industries, Naizil Canada Inc., Tarp Supply, Inc., Puyoung Industrial Corporation, Ltd., HDT Global, Canadian Tarpaulin Manufacturers LTD., Heytex Brandenburger GmbH, Karnawat Tarpaulin, Fastrack Dealcomm Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tarpaulin Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to reshape competitive positioning across woven polyethylene, PVC-coated polyester, and mesh substrate categories.
Co-extruded multilayer polyethylene films with embedded carbon-black UV stabilizers are rewriting durability benchmarks for disposable agricultural covers. Indian and Brazilian farming cooperatives are specifying 200-250 GSM grades with 36-month degradation resistance, compressing replacement cycles for traditional woven alternatives and enabling longer-term procurement contracts.
REACH Annex XVII restrictions on short-chain chlorinated paraffins and phthalate plasticizers are eliminating legacy formulation pathways for European PVC tarpaulin producers. ECHA compliance deadlines through 2025-2027 are forcing accelerated R&D spend on bio-based plasticizers and alternative stabilizer packages, with marine and defense applications facing the steepest certification burdens.
Long-term service agreements bundling installation, inspection, and scheduled replacement are displacing transactional spot purchasing in North American trucking and logistics fleets. Asset-light operators in the US Midwest and Southeast are outsourcing cover lifecycle management to specialized suppliers, compressing working capital requirements while locking in multi-year volume commitments.
Tarpaulin Market Segmentation
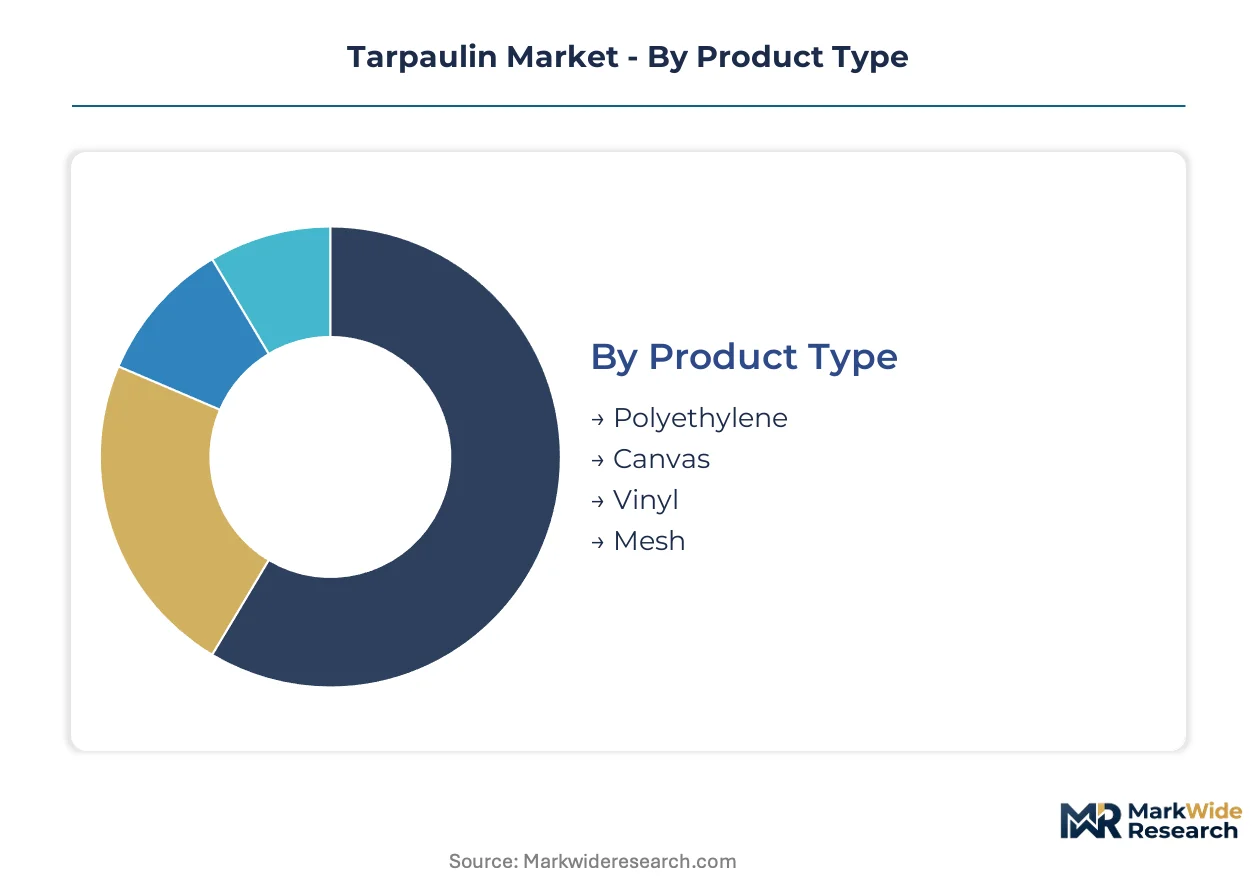
Material composition and end-use durability requirements create distinct procurement behaviors across the tarpaulin market. Buyers segment by weather exposure severity, load-bearing specifications, and regulatory compliance tiers rather than price alone.
Product Type:
Cost tier and replacement frequency drive buyer selection between commodity polyethylene and engineered vinyl grades.
- Polyethylene:Woven HDPE and LDPE films dominate disposable agricultural and construction site applications. Indian farming cooperatives specify 200-250 GSM grades with embedded carbon-black UV stabilizers for monsoon crop protection, compressing replacement cycles and enabling longer procurement contracts.
- Vinyl:PVC-coated polyester fabrics command premium positioning in military transportation covers and marine applications requiring weld-seam integrity. REACH Annex XVII restrictions on phthalate plasticizers are forcing European producers toward bio-based formulation pathways, extending certification timelines.
- Canvas:Natural fiber duck cloth retains heritage demand in specialty marine and military specifications where breathability and repairability outweigh synthetic durability.
- Mesh:Wind-permeable substrates compete in scaffolding enclosures and event signage where digital printing compatibility differentiates suppliers.
Volume sits with polyethylene; growth tilts toward vinyl as flame-retardant mandates expand.
End User:
Application environment severity determines material specification and margin capture potential.
- Construction:China's GB standards for flame-retardant site deployments accelerate certified vinyl procurement across Guangdong and Jiangsu provinces. Scaffolding contractors specify mesh variants for wind-load compliance on high-rise projects.
- Transportation:North American flatbed and container operators are shifting from transactional purchasing to long-term service agreements bundling installation, inspection, and scheduled replacement.
- Agriculture:India's BIS certification mandates for GSM thresholds in government-subsidized tarpaulin are consolidating procurement toward certified domestic mills.
- Events:Temporary infrastructure contractors in the Middle East specify UV-stabilized vinyl grades with extended warranty offerings for high-insolation climates.
Construction commands the largest installed base; transportation exhibits the steepest expansion trajectory for recurring-revenue service models.
Application:
Functional performance requirements separate commodity covering from value-added protection and branding solutions.
- Covering:Standard weatherproofing applications in agriculture and construction represent baseline demand with thin margins and high volume throughput.
- Protection:Heavy-duty load-bearing specifications for transportation and industrial equipment sheltering require tensile strength certification and seam-weld testing.
- Custom Printing:Mesh substrates compatible with solvent and UV-cure wide-format printers enable temporary branding and event signage applications with differentiated margin pools.
- Camping:Recreational outdoor applications favor lightweight polyethylene and coated nylon alternatives with portable deployment characteristics.
Protection applications anchor revenue stability; custom printing climbs fastest as event marketing budgets recover.
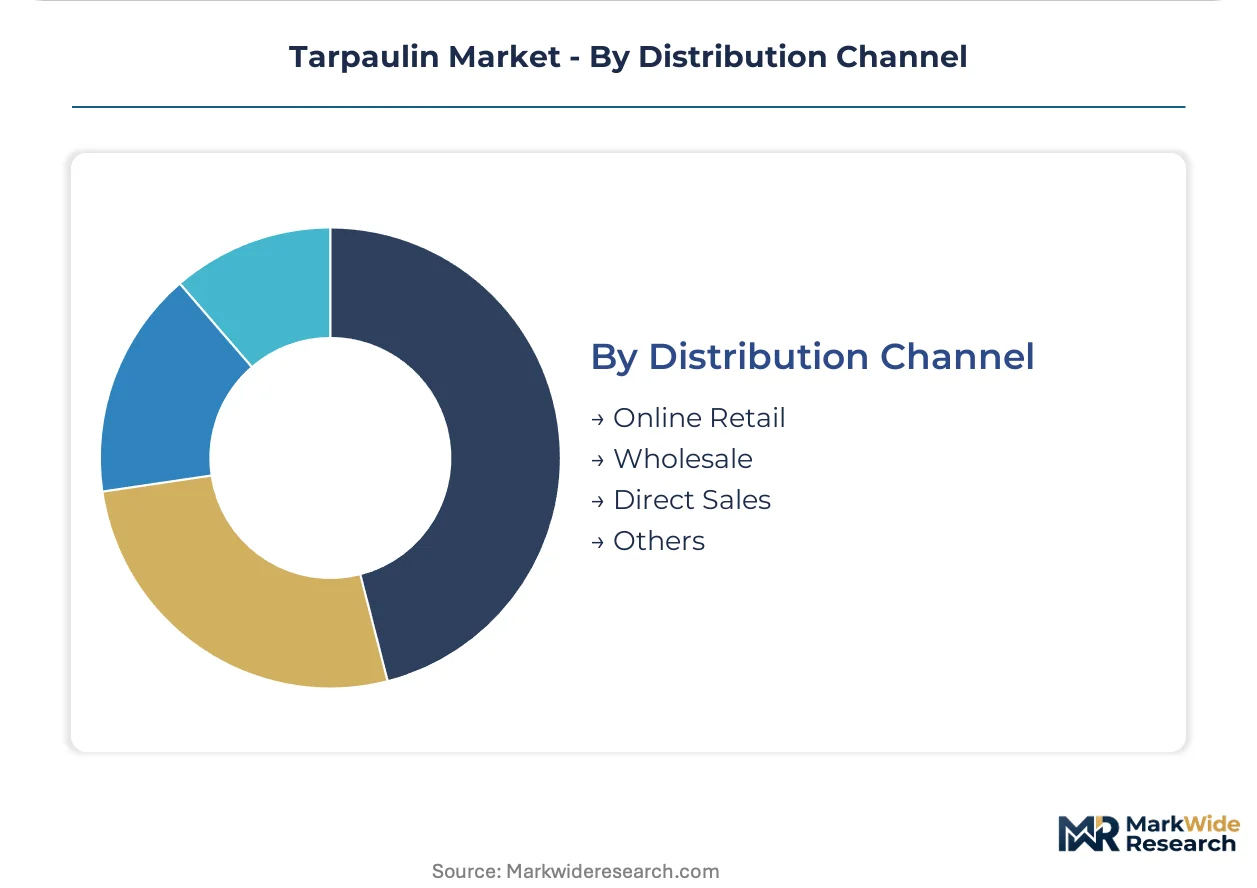
Distribution Channel:
Customer scale and technical specification complexity determine channel selection and service bundling potential.
- Wholesale:Industrial distributors serve construction contractors and agricultural cooperatives with volume pricing and regional inventory positioning.
- Direct Sales:Manufacturers with field service networks capture transportation fleet maintenance contracts through multi-year agreements covering installation and replacement scheduling.
- Online Retail:E-commerce platforms address consumer camping and small-scale agricultural demand with standardized specifications and rapid fulfillment.
- Others:Government procurement programs and cooperative buying arrangements channel subsidized agricultural tarpaulin through designated domestic mills in India.
Wholesale retains volume leadership; direct sales gain share fastest through service-integrated contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of coated textile substrates while India and the United States absorb the highest volumes of finished tarpaulin for agricultural and transportation end-uses. This production-consumption divide shapes regional trade flows and regulatory compliance priorities.
China
Guangdong and Jiangsu provinces drive certified vinyl procurement for scaffolding contractors responding to GB standards for flame-retardant construction-site deployments. The Ministry of Ecology and Environment enforces dual carbon goals that constrain petrochemical feedstock expansion. The Yangtze River Delta hosts integrated coating facilities supplying marine-grade specifications to domestic shipyards.
India
Maharashtra and Gujarat agricultural cooperatives specify 200-250 GSM polyethylene grades with carbon-black UV stabilizers for monsoon crop protection. The Bureau of Indian Standards mandates GSM thresholds for subsidized tarpaulin distributed through government procurement channels. Tamil Nadu's domestic mills are consolidating certification capacity to capture formalized quality-tier contracts.
United States
Midwest and Southeast transportation fleets are outsourcing cover lifecycle management to specialized suppliers under multi-year service agreements. The EPA maintains vinyl chloride emission limits that constrain PVC formulation choices for domestic converters. The Dallas-Fort Worth metroplex anchors distribution networks serving flatbed operators across the Interstate 35 corridor.
Germany
REACH Annex XVII restrictions on phthalate plasticizers and short-chain chlorinated paraffins are eliminating legacy formulation pathways for European PVC producers. The European Chemicals Agency compliance deadlines through 2025-2027 force accelerated R&D spend on bio-based alternatives. The North Rhine-Westphalia industrial cluster concentrates captive coating technology for defense and marine applications.
Brazil
São Paulo and Minas Gerais farming cooperatives are specifying co-extruded multilayer films with extended degradation resistance for soybean and corn storage covers. The national agricultural regulator monitors import quality standards for subsidized equipment programs. The Campinas industrial corridor hosts cut-and-sew operations serving South American transportation logistics demand.
Tarpaulin Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the tarpaulin value chain. Integrated textile-coating operations in Europe and Asia hold captive advantages in vinyl formulation, while independent converters in North America specialize in cut-and-sew logistics and field service bundling. Three archetypes dominate: integrated coating specialists, regional cut-and-sew assemblers, and service-integrated logistics contractors. Competitive moves concentrate on M&A for coating capacity access and geographic expansion through distribution partnerships.
Among European integrated producers, Sioen Industries and Heytex Brandenburger GmbH exemplify the coating-specialist archetype with captive technology positioning. Naizil Canada Inc. represents the North American service-integrated model, while Puyoung Industrial Corporation, Ltd. occupies a position within Asian manufacturing scale tiers. These anchors illustrate how geographic origin and corporate structure map to strategic positioning across formulation-heavy versus service-heavy market segments.
| Leading Market Players |
|---|
| Sioen Industries |
| Naizil Canada Inc. |
| Tarp Supply, Inc. |
| Puyoung Industrial Corporation, Ltd. |
| HDT Global |
| Canadian Tarpaulin Manufacturers LTD. |
| Heytex Brandenburger GmbH |
| Karnawat Tarpaulin |
| Fastrack Dealcomm Pvt Ltd |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII restrictions on phthalate plasticizers gate qualified supply for European vinyl tarpaulin producers, compressing accessible capacity to certified mills and enabling premium-tier pricing for compliant grades. This regulatory filter concentrates formulation expertise among integrated coating specialists while independent converters face margin compression from extended certification timelines.
Pricing Analysis
Margin tightening in standard polyethylene grades reflects naphtha-linked resin volatility and compressed contract-reset windows. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified vinyl for marine applications from BIS-mandated agricultural grades and disposable construction covers. Certification level and volume scale drive differentiation, with government-subsidized Indian procurement exhibiting highest price sensitivity and Middle East UV-stabilized vinyl commands lowest.
Supply Chain Analysis
Resin supply rests on integrated petrochemical complexes in China, Saudi Arabia, and the United States. Woven substrate production draws from polyester fiber mills in China and India, while specialty coating chemicals feed from European and Japanese additive suppliers. Single-source vulnerability concentrates in European captive coating capacity for defense-grade specifications. Distribution runs through industrial distributors, direct manufacturer field-service networks, and government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH and BIS certification requirements create barrier-to-entry moats for players with in-house polymer science capabilities and testing infrastructure.
For Market Incumbents: Anchor premium positioning through captive coating technology investments in European marine and defense segments. Accelerate backward integration into UV-stabilizer and bio-based plasticizer supply chains to offset REACH-driven formulation cost inflation. Defend against Asian volume competition by locking multi-year service contracts with North American transportation fleets. For New Entrants and Emerging Players: E-commerce platforms offer the most penetrable route for standardized agricultural polyethylene in underserved Brazilian and Southeast Asian cooperatives. Target cut-and-sew assembly partnerships with Indian domestic mills seeking BIS certification capacity expansion. Deploy digital sampling and rapid fulfillment to bypass wholesale distributor markups in consumer camping segments. For Investors and Strategic Acquirers: Consolidation of European coating specialists is the leading indicator that formulation scarcity is translating to acquisition premiums. Five-to-ten year viability favors integrated producers with regulatory compliance infrastructure over asset-light distributors. Watch for BIS certification backlog clearance in Indian state tenders as the signal for formalized quality-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemicals | Captive supply of REACH-compliant plasticizers secures margin against ECHA deadline compression. |
| Long-term Service Agreement Expansion | Multi-year transportation fleet contracts lock volume commitments and compress customer switching. |
| Joint Venture with Indian Domestic Mills | BIS certification capacity partnerships capture formalized agricultural subsidy procurement channels. |
| Green Manufacturing Transition | Bio-based formulation pathways differentiate European producers in marine and defense specifications. |
| Digital Printing Compatibility Investment | Mesh substrate R&D opens event signage applications with solvent and UV-cure printer integration. |
Methodological Framework
Multi-period observation of resin price indices, certification timeline data, and subsidy program disbursements anchored the trend analysis, supplemented by interviews with plant managers at integrated coating facilities, procurement leads at North American flatbed operators, technical R&D directors at European textile-laminate producers, and distribution channel partners serving Indian agricultural cooperatives. Secondary validation drew from customs and trade data, ECHA regulatory filings, BIS certification registries, and SEC 10-K disclosures from listed materials companies. Bottom-up volume estimates triangulated against top-down macroeconomic drivers across material grades and end-use segments.
Input-output matrices mapped polyethylene and PVC resin throughput to finished tarpaulin production capacity across major manufacturing clusters, with segmentation dimensions spanning material composition, end-use durability requirements, application functional performance, and distribution channel structure. CAGRs derived from regression analysis of historical procurement patterns and forward-projected regulatory compliance timelines. Industry-specific forecast inputs included monsoon intensity projections for Indian agricultural demand and GB standards enforcement schedules for Chinese construction procurement.
The model holds under stable petrochemical feedstock pricing and consistent regulatory enforcement schedules; deviation in resin volatility spikes or accelerated ECHA restriction timelines would shift volume and value projections. A small set of named triggers warrants ongoing watch: BIS certification backlog rates, REACH alternative formulation cost curves, and Middle East infrastructure spending announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Fabric Reversing Machines Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Webbing Cutting Machine Market