
 Fabric Stain Remover Market | 2026-2036
Fabric Stain Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Stain Remover Market Analysis
Subscription-based replenishment programs is rebalancing how households purchase fabric stain removers, shifting volume from episodic retail trips to predictable direct-to-home deliveries. Procter & Gamble leverages its logistics network to sustain recurring revenue streams in this channel. Henkel anchors European market share through specialized enzyme portfolios. Church & Dwight competes aggressively on powder-form value positioning.
A fabric stain remover is a surface-active cleaning formulation engineered to disrupt hydrogen bonding between textile fibers and organic or synthetic discolorants, typically operating within pH ranges of 7.5 to 10.5 for alkaline oxy-based systems. Its primary commercial purpose is to restore garment appearance without fiber degradation in both consumer and industrial washing protocols. Enzyme-based variants now lead product-type growth due to superior cold-water efficacy and biodegradability profiles. Liquid formulations dominate volume but gel concentrates capture expanding margin pools through dosing precision. Commercial laundry end users represent the fastest-expanding demand segment as on-premise cleaning operations upgrade from legacy solvent systems.
The EPA regulates volatile organic compound emissions from solvent-based formulations under Clean Air Act provisions, compelling manufacturers toward aqueous and enzyme alternatives. REACH restrictions on perchloroethylene and NMPA oversight of antimicrobial claims in China further constrain formulation freedom across major supply corridors. Stakeholders must monitor tightening state-level disclosure mandates in California and New York that will soon require full ingredient transparency on household cleaning labels.
Market Dynamics
Enzyme-based cold-water formulations are compressing energy costs for commercial laundries while forcing legacy solvent suppliers to reformulate entire product lines. This technology pivot reconfigures supplier power toward biotechnology feedstock providers and away from petrochemical intermediaries.
Growth Catalysts
- EPA discharge standards:Tightening effluent limits on phosphorus and surfactant loads compel North American commercial operators to adopt biodegradable enzyme systems that degrade below detection thresholds in wastewater treatment.
- Cold-water washing protocols:Industrial laundries in Germany and the Netherlands are retrofitting tunnel washers for 30°C cycles, creating pull-through demand for protease and lipase concentrates that activate at reduced thermal input.
- Textile rental service expansion:Hospitality and healthcare linen leasing programs require extended garment lifecycles, driving specification of pH-neutral stain removers that minimize fiber damage across repeated cleaning cycles.
Market Restraints
- Surfactant feedstock volatility:Linear alkylbenzene sulfonate and fatty alcohol ethoxylate prices track palm kernel oil and ethylene oxide markets, compressing margins for aqueous formulation producers when oleochemical supply tightens.
- Enzyme supplier concentration:Novozymes and DuPont Industrial Biosciences control approximately three-quarters of global protease and amylase capacity, creating single-source risk for mid-tier formulators lacking backward integration into fermentation assets.
- Perchloroethylene legacy infrastructure:Dry cleaning operators in France and Italy face stranded asset risk as REACH phase-out deadlines approach, delaying capital redeployment into aqueous alternatives despite regulatory pressure.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-home dosing systems with IoT-enabled refill triggers capture recurring revenue streams while disintermediating traditional retail shelf space competition.
- Antimicrobial stain hybrid formulations:Post-pandemic healthcare textile protocols create specification openings for peracetic acid and quat-combined products that satisfy both aesthetic and hygiene mandates in single-application workflows.
- India PLI scheme for specialty chemicals:Domestic fermentation capacity expansion incentives position local manufacturers to supply enzyme concentrates for South Asian and Middle Eastern laundry markets at reduced import duty exposure.
Industry Challenges
- Enzyme stability formulation expertise:Protease inclusion in liquid matrices requires boron-free stabilizer chemistry that few regional compounders have mastered, creating quality variance across private-label supply.
- Multi-jurisdiction label compliance:Simultaneous satisfaction of California SB-312 ingredient disclosure, EU CLP hazard classification, and China GB/T 26396 standards demands dedicated regulatory affairs headcount that fragments smaller competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Stain Remover Market |
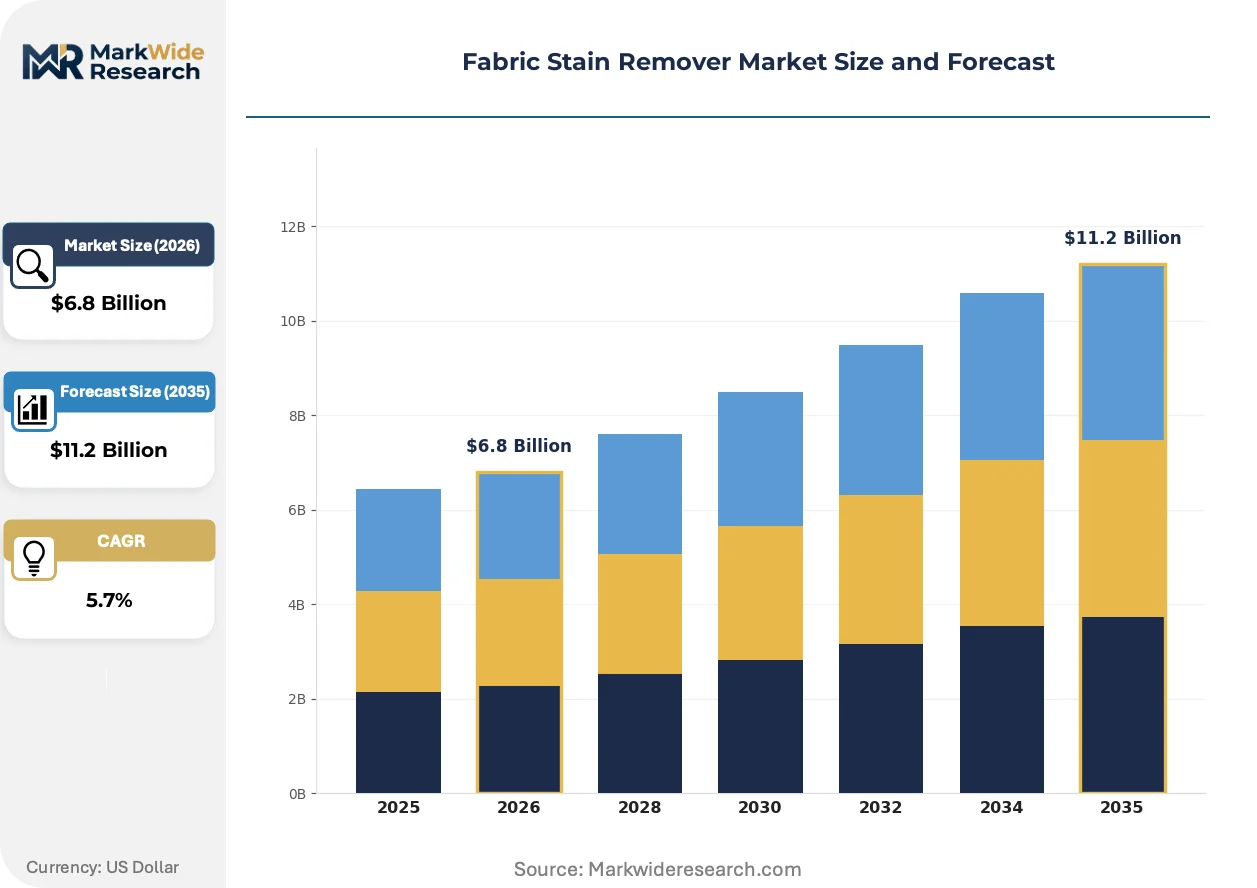
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxy-Based, Enzyme-Based, Solvent-Based, Spray Formulation: Liquid, Powder, Gel, Wipe End User: Households, Commercial Laundry, Retail, Hospitality Distribution Channel: Online Retail, Supermarkets, Drugstores, Specialty Stores |
| Companies Covered | Unilever, S.C. Johnson & Son, Procter & Gamble, Colgate-Palmolive, Church & Dwight, Reckitt Benckiser, Henkel, Kao Corporation, The Clorox Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Stain Remover Market Emerging Trajectories
Formulation science is converging with digital dosing systems to eliminate over-application waste while meeting intensifying biodegradability mandates. These parallel developments compress the viable product lifecycle for legacy petrochemical surfactants.
Enzyme encapsulation via spray-dried granulation is automating controlled-release delivery in front-loading washers. Commercial laundries in Scandinavia are retrofitting dispensing equipment to handle these concentrated formats. The technology is automating reduction in both water consumption and rewash rates that previously required manual pre-treatment intervention.
REACH restrictions on perchloroethylene and N-methyl-2-pyrrolidone are accelerating aqueous system adoption across European dry cleaning networks. Formulators must now certify biodegradability under OECD 301B protocols to maintain distribution access. Italy and Spain show the most visible equipment replacement activity as solvent-based machine depreciation schedules compress.
Healthcare procurement departments are consolidating vendor lists around suppliers offering combined chemical and equipment service contracts. This bundling displaces standalone product purchasing in hospital and aged-care textile operations. The shift is most advanced in Germany's Klinikum networks, where total-cost-per-cleaned-kilogram metrics now dominate supplier selection criteria.
Fabric Stain Remover Market Segmentation
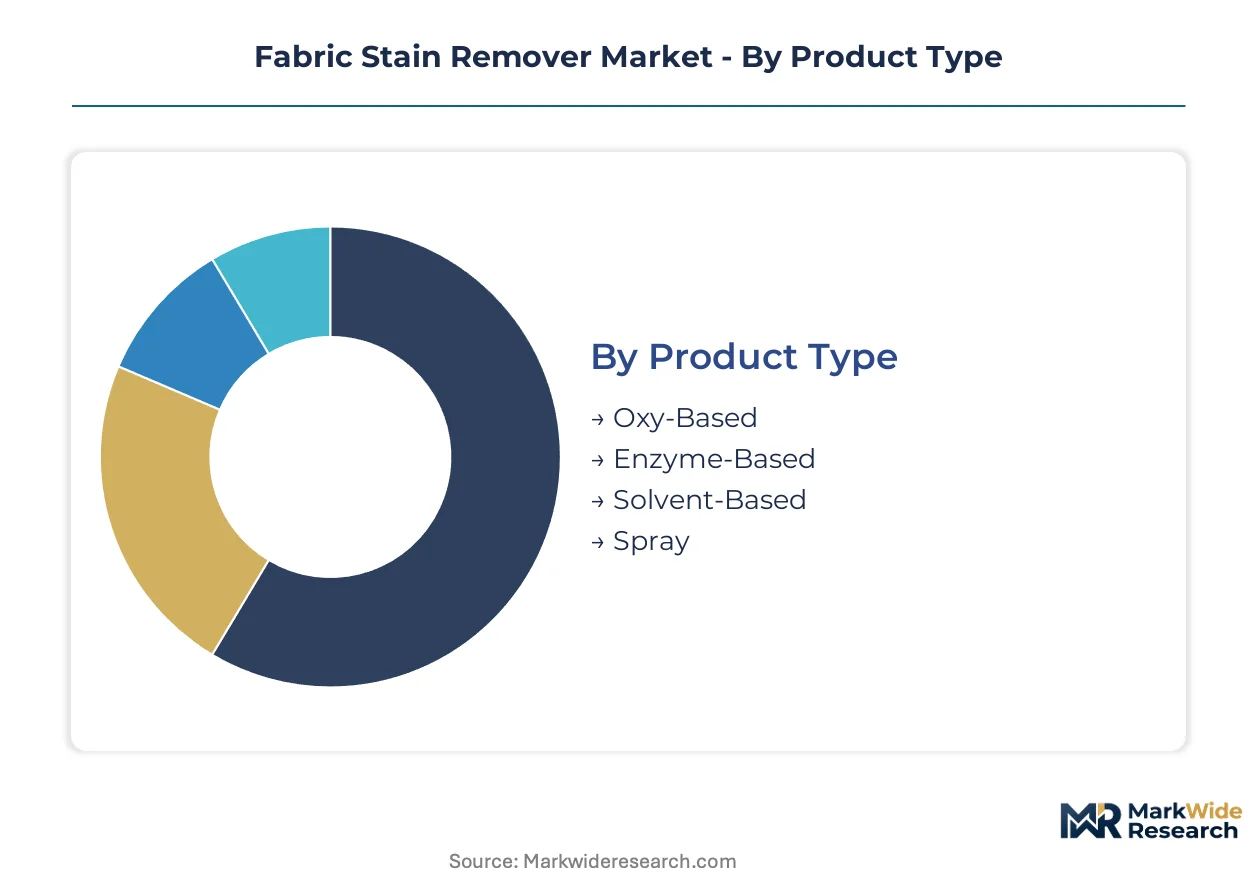
Fabric stain removers fragment across four critical dimensions that determine formulation chemistry, packaging economics, and channel strategy. Product type and formulation choices cascade through manufacturing asset requirements, while end-user concentration and distribution access shape margin capture and brand positioning.
Product Type:
Buyers differentiate primarily by washing temperature capability and biodegradability compliance obligations rather than stain removal efficacy alone.
- Enzyme-Based:Protease and lipase concentrates engineered for activation at 30°C enable cold-water protocols that cut energy expenditure for commercial tunnel washer operations. German and Dutch industrial laundries are retrofitting equipment specifically to exploit these formulations, driven by REACH-aligned discharge standards that penalize petrochemical surfactant persistence.
- Oxy-Based:Alkaline hydrogen peroxide systems operating at pH 7.5-10.5 dominate household pre-treatment applications where thermal input is unrestricted. North American consumers favor these formulations for color-safe brightening, though California's forthcoming ingredient disclosure mandates will force reformulation of stabilizer packages.
- Solvent-Based:Perchloroethylene formulations face stranded asset risk in France and Italy as ECHA phase-out deadlines approach, compressing viable service life for existing dry cleaning infrastructure.
- Spray:Aerosol and trigger-dispensed formats target on-the-go spot treatment with rapid evaporation carriers; portability constraints limit active ingredient loading versus liquid concentrates.
Oxy-based systems lead volumes today; enzyme-based formats are gaining share fastest.
Formulation:
Physical state determines dosing precision, shipping economics, and stability engineering requirements across supply chains.
- Liquid:Aqueous solutions with dissolved surfactants and suspended enzymes require boron-free stabilizer chemistry that few regional compounders have mastered; quality variance fragments private-label supply. Concentrated variants reduce plastic intensity and capture margin expansion through precision dosing systems.
- Gel:Thickened matrices enable controlled dispensing in front-loading washers and IoT-enabled refill triggers for subscription replenishment channels. Scandinavian commercial laundries are retrofitting dispensing equipment to handle these concentrated formats.
- Powder:Spray-dried granules with encapsulated enzymes offer shelf stability without liquid-phase stabilizer complexity; Church & Dwight competes aggressively on value positioning in this format.
- Wipe:Pre-saturated substrates target travel and emergency spot treatment with limited active loading; single-use waste profiles face mounting scrutiny under EU packaging regulations.
Liquid formulations anchor current volume; gel concentrates show the steepest expansion trajectory.
End User:
Volume concentration and specification authority diverge sharply between fragmented household purchasers and consolidated commercial procurement.
- Commercial Laundry:On-premise cleaning operations in North American hospitality and healthcare sectors drive fastest-expanding demand as EPA discharge standards tighten. Total-cost-per-cleaned-kilogram metrics now dominate supplier selection in Germany's Klinikum networks.
- Households:Subscription-based replenishment programs are rebalancing purchase patterns from episodic retail trips to predictable direct-to-home deliveries; Procter & Gamble leverages logistics infrastructure to sustain recurring revenue.
- Hospitality:Textile rental service expansion requires extended garment lifecycles, driving pH-neutral formulation specifications that minimize fiber damage across repeated cleaning cycles.
- Retail:Dry cleaning operators face capital redeployment delays into aqueous alternatives despite regulatory pressure, particularly in France and Italy where perchloroethylene legacy infrastructure creates stranded asset risk.
Households dominate absolute volume; commercial laundry is climbing the fastest.
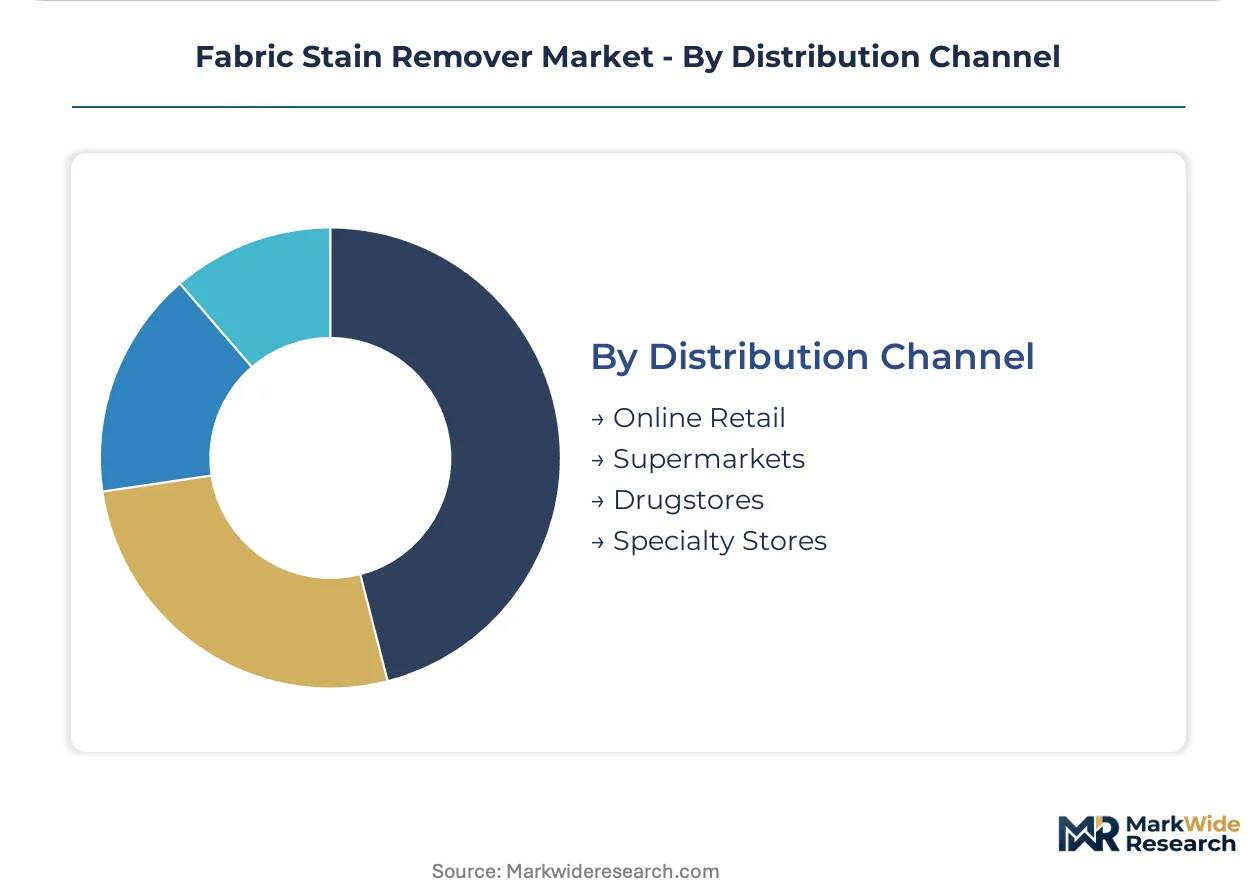
Distribution Channel:
Channel selection determines margin retention, customer data access, and exposure to retail shelf space competition.
- Online Retail:Direct-to-home platforms enable subscription mechanics and IoT-enabled auto-replenishment triggers that disintermediate traditional retail competition; logistics network scale separates viable competitors.
- Supermarkets:Mass merchandisers capture impulse and planned replenishment purchases with broad SKU availability; shelf space fees compress margins for mid-tier brands.
- Drugstores:Pharmacy chains emphasize specialty stain treatment and travel-size formats with higher unit margins; limited shelf depth favors established brand recognition.
- Specialty Stores:Fabric care boutiques and dry cleaning supply distributors serve professional formulators with bulk concentrate access and technical service relationships.
Supermarkets maintain volume leadership; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial laundries operate at lower wash temperatures than their United States counterparts, yet both markets face tightening discharge standards that favor enzyme-based formulations over legacy petrochemical systems.
United States
Commercial laundry operators in California and New York drive specification of biodegradable enzyme systems as EPA effluent limits on phosphorus tighten. The agency's Clean Air Act provisions on volatile organic compound emissions compel reformulation away from solvent-based pre-treatments. Chicago's hospitality linen services are retrofitting tunnel washers for cold-water protocols to capture utility rebates.
Germany
Industrial laundries in North Rhine-Westphalia and Bavaria retrofit equipment for 30°C cycles, creating concentrated demand for protease concentrates. REACH restrictions on perchloroethylene accelerate aqueous system adoption across dry cleaning networks. Munich's Klinikum hospital networks now select suppliers using total-cost-per-cleaned-kilogram metrics rather than unit pricing.
India
Domestic fermentation capacity expansion under the PLI scheme for specialty chemicals positions local manufacturers to supply enzyme concentrates for South Asian markets. Central Pollution Control Board discharge monitoring tightens compliance costs for legacy surfactant formulators. Maharashtra's textile processing clusters in Mumbai and Pune are upgrading effluent treatment to meet zero-liquid-discharge mandates.
China
NMPA oversight of antimicrobial claims constrains hybrid stain-remover development for healthcare textile applications. GB/T 26396 standards on household cleaning products mandate ingredient disclosure that parallels tightening state-level requirements elsewhere. Shanghai's commercial laundry sector leads equipment upgrades for aqueous systems as environmental enforcement intensifies in the Yangtze River Delta.
Netherlands
Tunnel washer operators in the Randstad region pioneer 30°C industrial protocols that pull through demand for cold-water enzyme activation. National wastewater discharge permits now incorporate biodegradability thresholds that exclude legacy petrochemical surfactants. Eindhoven's equipment manufacturers supply precision dosing systems that optimize concentrate consumption for hospitality textile rental programs.
Fabric Stain Remover Market Vendor Landscape
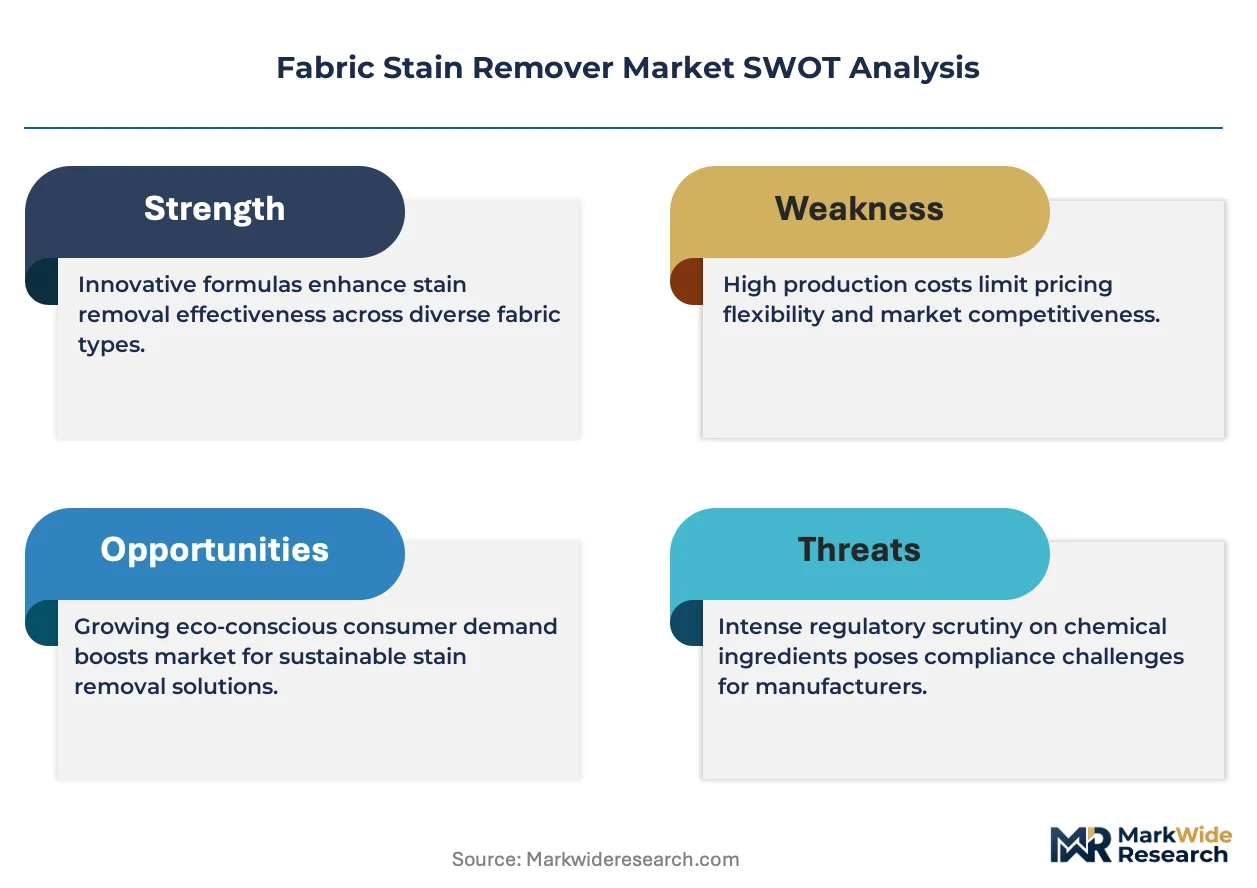
Top-tier vendors anchor premium enzyme and concentrated gel segments, while mid-tier formulators compete on powder-format value positioning and private-label supply. The vendor base spans multinational consumer goods conglomerates with logistics-scale advantages, regional specialty chemical houses with fermentation assets, and contract manufacturers serving retail channel exclusives. Three strategic archetypes dominate: biotechnology-forward innovators, scale-driven mass-market suppliers, and regulatory-compliance specialists. Competitive moves concentrate on subscription channel infrastructure buildout and boron-free stabilizer chemistry licensing for liquid enzyme matrices.
Among diversified consumer goods conglomerates, Procter & Gamble, Henkel, and Church & Dwight occupy positions that exemplify distinct strategic vectors. Procter & Gamble represents the logistics-integrated subscription model, leveraging distribution infrastructure to sustain recurring revenue streams. Henkel anchors European market share through specialized enzyme portfolio depth and REACH compliance leadership. Church & Dwight exemplifies value-tier positioning in powder-format segments, competing on unit economics rather than formulation sophistication. These three archetypes structure competitive intensity across retail shelf space, direct-to-home channels, and commercial laundry procurement.
| Leading Market Players |
|---|
| Unilever |
| S.C. Johnson & Son |
| Procter & Gamble |
| Colgate-Palmolive |
| Church & Dwight |
| Reckitt Benckiser |
| Henkel |
| Kao Corporation |
| The Clorox Company |
| Others |
Supply Flow & Price Mechanics
Commercial laundry procurement departments in Germany and the Netherlands concentrate purchasing power around total-cost-per-cleaned-kilogram metrics, anchoring contract pricing to enzyme concentrate performance rather than unit volume. This buyer consolidation rewards formulators with fermentation assets and REACH-compliant documentation while squeezing mid-tier suppliers dependent on spot surfactant purchases.
Pricing Analysis
Capacity additions in India's fermentation corridors are reshaping price floors for protease and lipase concentrates, compressing margins for European suppliers still amortizing REACH compliance investments. Three-tier pricing structure across premium enzyme concentrates, standard aqueous formulations, and economy powder segments stratifies according to cold-water activation thresholds and boron-free stabilizer certification. Cost compression in the standard tier intensifies as palm kernel oil volatility transmits through fatty alcohol ethoxylate markets. Small-scale dry cleaning operators in Southern Europe exhibit highest price sensitivity, while Germany's Klinikum networks prioritize performance guarantees over unit cost.
Supply Chain Analysis
Specialized fermentation technician availability in Denmark and the Netherlands constrains rapid capacity scaling for enzyme feedstock producers. Manufacturing gravity centers on Germany for formulation compounding, India for fermentation capacity expansion under PLI incentives, and China for surfactant intermediate production. Supply chains draw from palm kernel oil plantations in Southeast Asia, ethylene oxide derivatives from Gulf Coast petrochemical complexes, and proprietary bacterial strains from Copenhagen-based biotechnology repositories. Single-source vulnerability concentrates in Novozymes and DuPont Industrial Biosciences protease capacity. Distribution runs through specialty chemical distributors serving commercial laundries, with direct-to-home subscription channels bypassing traditional retail markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on cold-water formulation premiums capturing energy-cost savings for commercial end users, while enzyme stability expertise creates defendable differentiation against commodity surfactant competitors.
For Market Incumbents: Deepen backward integration into fermentation assets to secure protease supply against Novozymes concentration risk, while licensing boron-free stabilizer chemistry to regional compounders seeking private-label quality parity. Channel control through IoT-enabled dosing system deployments locks in recurring revenue and raises switching costs for hospitality textile rental programs. For New Entrants and Emerging Players: Mid-sized hospital systems in India's Maharashtra and Karnataka clusters represent underserved buyers seeking aqueous alternatives to perchloroethylene with localized technical service support. White-space exists in antimicrobial-hybrid formulations for healthcare linen protocols, with go-to-market traction through equipment-plus-chemical bundled contracts mimicking Germany's Klinikum procurement model. For Investors and Strategic Acquirers: Consumer goods conglomerates with underutilized logistics networks are the most active acquirer in this space, seeking subscription-channel infrastructure to offset retail shelf space erosion. Fermentation-capable specialty chemical houses in India and Denmark present acquisition profiles with durable moats around enzyme stability expertise. Watch for EPA state-level disclosure mandate acceleration in California and New York as signal for reformulation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Boron-Free Stabilizer Licensing | Unlocks private-label enzyme liquid quality parity for regional compounders lacking in-house R&D. |
| IoT-Enabled Dosing System Deployment | Captures recurring revenue streams while disintermediating traditional retail shelf competition. |
| Fermentation Capacity Expansion | Reduces import duty exposure for South Asian markets under India's PLI incentive scheme. |
| Antimicrobial-Hybrid Formulation Launch | Addresses post-pandemic healthcare textile protocols combining aesthetic and hygiene mandates. |
| REACH-Compliant Documentation Investment | Maintains distribution access across European dry cleaning networks facing perchloroethylene phase-out. |
Methodological Framework
Coverage spans North America, Western Europe, South Asia, and East Asia, with primary inputs from each region combined with secondary validation across trade and regulatory databases. Interviews with commercial laundry operations managers, specialty chemical procurement leads, fermentation plant engineers, and regulatory affairs directors at formulators informed demand-side and supply-side assessments. Secondary sources include EPA discharge monitoring reports, ECHA REACH registration databases, India PLI scheme disclosure filings, and customs trade data on surfactant intermediate flows. Bottom-up volume builds from end-use segment consumption patterns triangulate against top-down market sizing from producer shipment disclosures.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type, formulation state, end-user concentration, and distribution channel access, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derive from fitted trend extrapolation adjusted for technology substitution curves and policy inflection points. Forecast inputs incorporate tunnel washer retrofit timelines in Germany and the Netherlands, EPA effluent limit implementation schedules, and PLI scheme capacity commissioning milestones.
Underlying measurement precision varies by segment; commercial laundry procurement data carries tighter precision than fragmented household consumption estimates. Forecasts reflect assumptions on regulatory enforcement intensity, enzyme stability formulation diffusion rates, and surfactant feedstock price normalization. Material deviation in EPA state-level disclosure mandates, REACH amendment timelines, or fermentation capacity commissioning delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market