
 Public Transportation Software Market | 2026-2036
Public Transportation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Public Transportation Software Market Intelligence
The EU Green Deal is expanding requirements for emissions monitoring and reporting across municipal transit fleets, compelling agencies to replace legacy dispatch systems with integrated software platforms. Optibus leverages algorithmic optimization to anchor large-scale European deployments. Swiftly competes through real-time data infrastructure that sustains operational visibility for mid-sized transit authorities. Ecolane Evolution specializes in paratransit scheduling, occupying a niche with specialized compliance workflows.
Public transportation software comprises digital platforms that coordinate vehicle dispatch, passenger information, fare collection, and service planning through centralized data architectures operating on sub-second latency thresholds. These systems primarily enable transit operators to match supply with passenger demand while minimizing deadhead mileage and schedule deviations. Scheduling software dominates enterprise procurement budgets due to its integration complexity and long replacement cycles, while rider apps represent the fastest-expanding segment as agencies prioritize channel shift toward mobile-first engagement. Cloud-based deployment captures growing share from on-premises installations, though hybrid configurations retain relevance where legacy hardware constraints persist.
The Federal Transit Administration, EPA, and state-level Departments of Transportation collectively shape compliance mandates for emissions tracking, accessibility standards, and cybersecurity protocols across US transit networks. The EU AI Act and GDPR impose additional algorithmic transparency and data governance requirements on automated routing and passenger analytics platforms deployed in European markets. Stakeholders must monitor evolving interoperability standards between proprietary fleet systems and emerging municipal data exchanges to preserve platform relevance.
Market Dynamics
Cloud migration is compressing replacement cycles for legacy dispatch systems as municipal transit authorities confront EU Green Deal mandates for real-time emissions transparency.
Growth Catalysts
- EU Green Deal mandates:Transit authorities across Germany, France, and the Netherlands must deploy integrated monitoring platforms to satisfy emissions reporting requirements for municipal fleets.
- Edge computing architectures:Sub-second latency for vehicle-to-infrastructure communication enables dynamic rerouting that cuts deadhead mileage for bus operators.
- Federal subsidies:Germany's digital infrastructure program is accelerating procurement timelines for mid-sized transit agencies previously constrained by capital budgets.
Market Restraints
- Legacy hardware lock-in:On-premises SCADA systems in older rail networks create technical debt that extends replacement timelines beyond typical software depreciation.
- GDPR compliance costs:Algorithmic transparency requirements under the EU AI Act impose documentation burdens that inflate implementation budgets for automated routing platforms.
- Specialized talent scarcity:Transit agencies compete with logistics and ride-hail platforms for operations research specialists capable of configuring optimization engines.
Strategic Opportunities
- Paratransit digitization:Demand-responsive transit services for elderly and disabled riders remain underpenetrated by specialized scheduling software in Spain and Italy.
- Mobility-as-a-Service integration:Convergence of transit software with bike-share and micro-mobility platforms creates unified payment and routing propositions for urban commuters.
- CSRD reporting tools:Corporate sustainability disclosure requirements are generating demand for emissions analytics modules that transit vendors can white-label to enterprise clients.
Industry Challenges
- API standardization gaps:Proprietary fleet management protocols resist interoperability with municipal open data exchanges, forcing costly middleware development.
- Cybersecurity certification delays:Common Criteria evaluation timelines for safety-critical transit systems stretch 18-24 months, blocking deployment of security patches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Transportation Software Market |
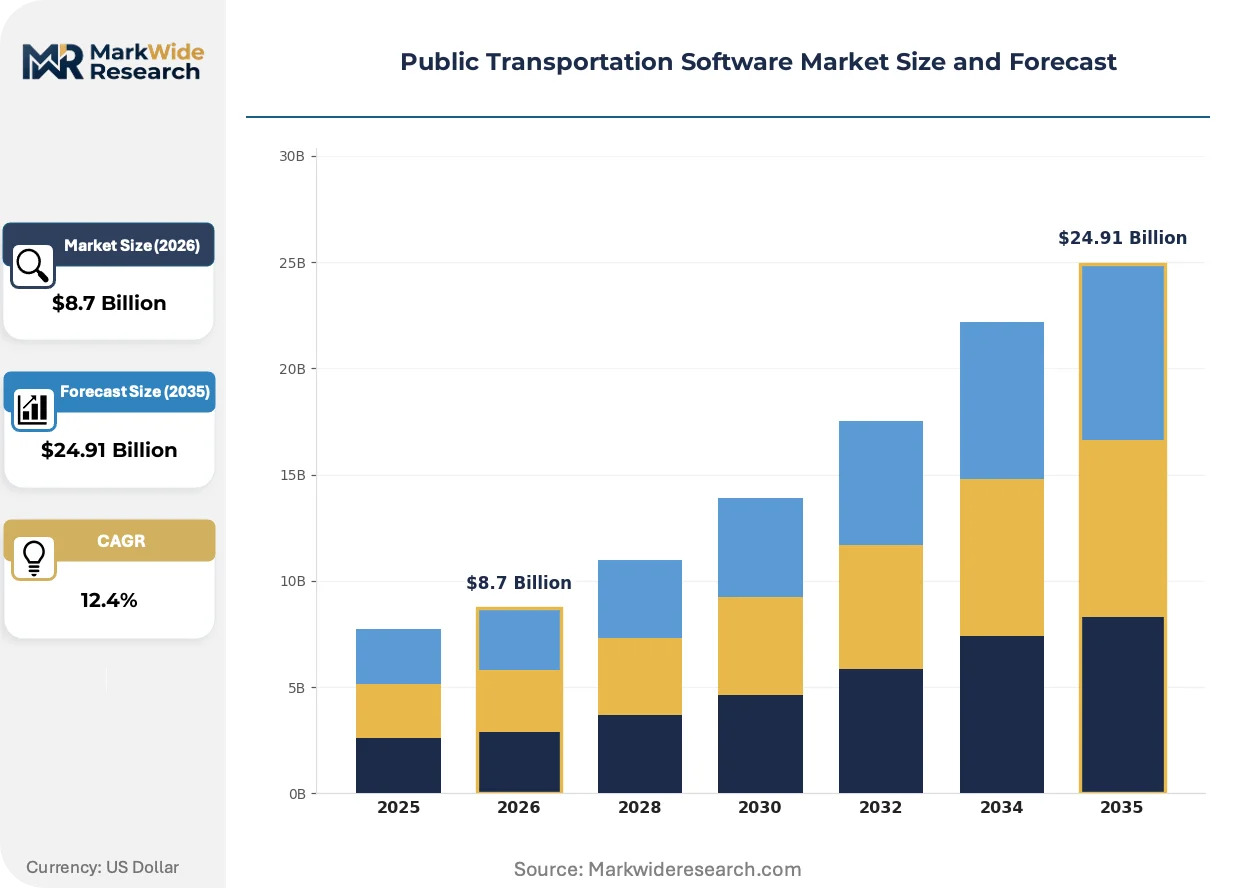
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Ticketing Systems, Fleet Management Solutions, Rider Apps End User: Transit Authorities, Government Agencies, Private Operators, Commuters Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Platforms Application: Real-Time Tracking, Route Optimization, Fare Management, Customer Engagement |
| Companies Covered | Swiftly, PtMS, TripSpark Fixed Route & Paratransit, Spare, Pantonium, Optibus, Ecolane Evolution, Trackit, RideCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Transportation Software Market Strategic Shifts & Innovations
Algorithmic optimization is migrating from back-office planning to real-time operational control, while regulatory pressure fuses emissions compliance with core platform functionality.
Microservices architectures are modularizing monolithic transit management suites into discrete components for dispatch, fare collection, and passenger information. Large operators in Germany and the Netherlands are adopting containerized deployments that allow independent scaling of high-frequency modules. This decomposition is modularizing vendor competitive dynamics, enabling point-solution specialists to displace integrated suite providers in specific functional domains.
The EU AI Act's risk classification framework is imposing documentation and human-oversight requirements on automated vehicle routing systems. Transit software vendors must now maintain algorithmic audit trails and explainability interfaces for safety-critical decisions. European deployments face the steepest compliance ramps, with France's national rail operator already restructuring procurement specifications to mandate conformity assessment.
Subscription pricing for cloud-native platforms is displacing perpetual license models among municipal buyers with constrained capital budgets. Annual recurring revenue structures align vendor incentives with ongoing operational performance rather than upfront implementation. This shift is most pronounced in Germany, where federal digital infrastructure subsidies explicitly favor operational expenditure treatment over capital procurement.
Public Transportation Software Market Segmentation
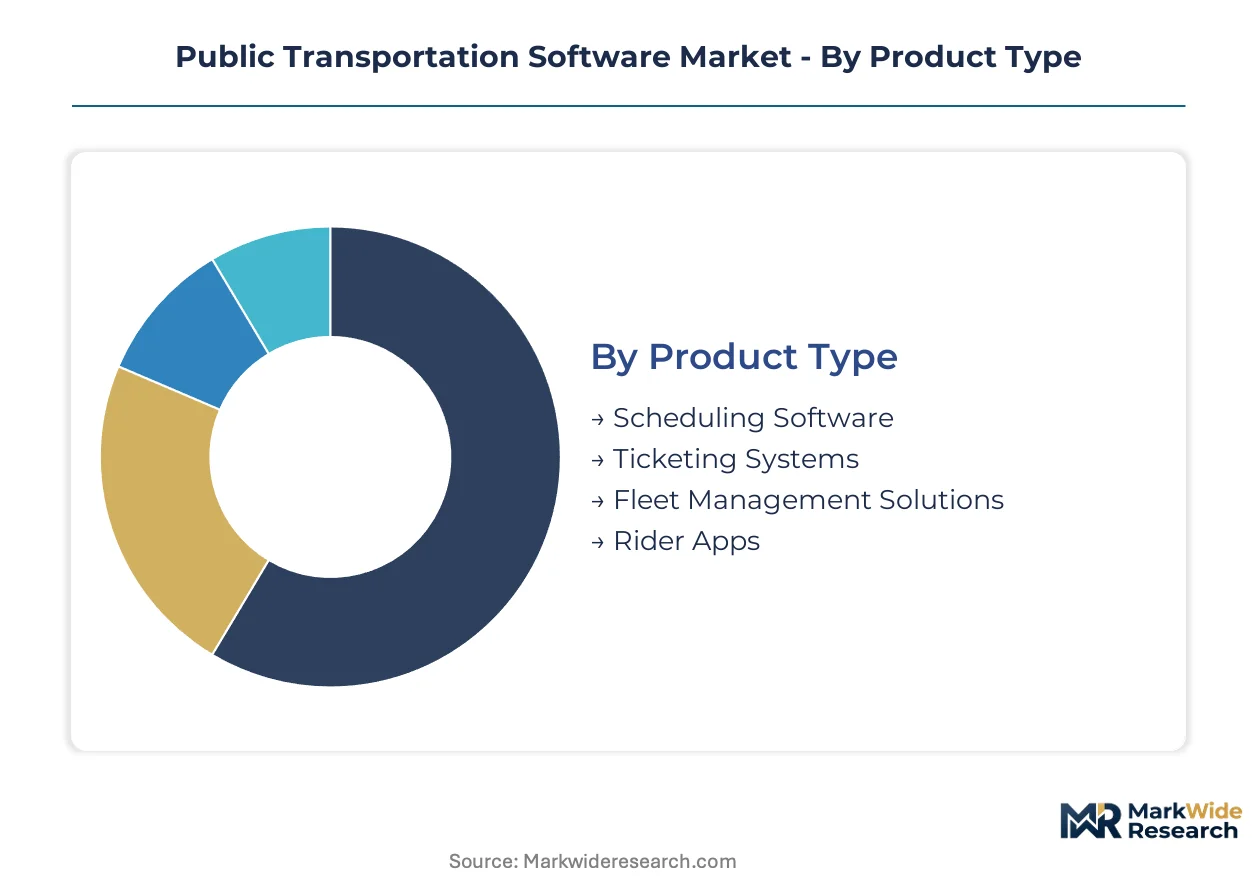
Segmentation reveals how procurement priorities diverge across buyer archetypes in public transportation software. Municipal transit authorities prioritize integration depth over feature breadth, while private operators weight scalability metrics more heavily. Understanding these splits enables vendors to align R&D investment with revenue concentration.
Product Type:
Procurement budgets concentrate where integration complexity creates the highest switching costs for transit operators.
- Scheduling Software:Algorithmic platforms coordinate vehicle dispatch, driver rostering, and service planning through constraint-based optimization engines. German and Dutch transit authorities allocate the largest capital shares here due to EU Green Deal mandates for emissions-transparent operations. Legacy system replacement cycles extend 7-10 years, locking in vendor relationships.
- Ticketing Systems:These platforms process fare collection across contactless cards, mobile wallets, and account-based architectures. Demand is concentrating in France and Spain where open-loop payment convergence with banking infrastructure accelerates procurement. Interoperability with national transit pass schemes drives technical specifications.
- Fleet Management Solutions:Real-time vehicle monitoring combines GPS telemetry, fuel consumption analytics, and predictive maintenance alerts.
- Rider Apps:Mobile-first passenger interfaces deliver trip planning, real-time arrival predictions, and service disruption notifications.
Scheduling software leads on scale; rider apps lead on momentum.
End User:
Buyer sophistication determines platform complexity requirements and sales cycle duration.
- Transit Authorities:Municipal operators manage multi-modal networks requiring centralized command-and-control architectures. Procurement in Germany dominates this segment as federal digital infrastructure subsidies compress evaluation timelines. Compliance with accessibility mandates and emissions reporting shapes RFP specifications.
- Government Agencies:State and national bodies oversee regulatory compliance, subsidy distribution, and cross-jurisdictional coordination. French national rail restructuring under EU AI Act conformity assessment is redirecting specifications toward algorithmic audit capabilities. Budget approval hierarchies extend procurement cycles.
- Private Operators:Contracted bus and shuttle services prioritize operational efficiency metrics over political visibility.
- Commuters:Individual riders influence demand indirectly through app store ratings and service complaints channeled to elected officials.
Transit authorities anchor procurement volume; government agencies are expanding most quickly.
Deployment:
Capital budget constraints versus data sovereignty requirements shape infrastructure decisions.
- Cloud-Based:Subscription models deliver elastic compute for real-time optimization without upfront hardware investment. German federal subsidies explicitly favor operational expenditure treatment, accelerating municipal adoption. Latency requirements below 100 milliseconds for vehicle-to-infrastructure communication demand edge node distribution.
- On-Premises:Legacy installations persist where rail networks maintain decades-old SCADA hardware with proprietary protocols. Older networks in France and Belgium face technical debt extending replacement timelines. Cybersecurity air-gapping for safety-critical systems preserves relevance despite higher total cost of ownership.
- Hybrid Solutions:Split architectures process sensitive dispatch data locally while offloading analytics to cloud tiers.
- Mobile Platforms:Native iOS and Android deployments extend functionality to field personnel and passengers without fixed terminal dependency.
Cloud-based deployments gain share fastest; on-premises retains position in rail-heavy networks.
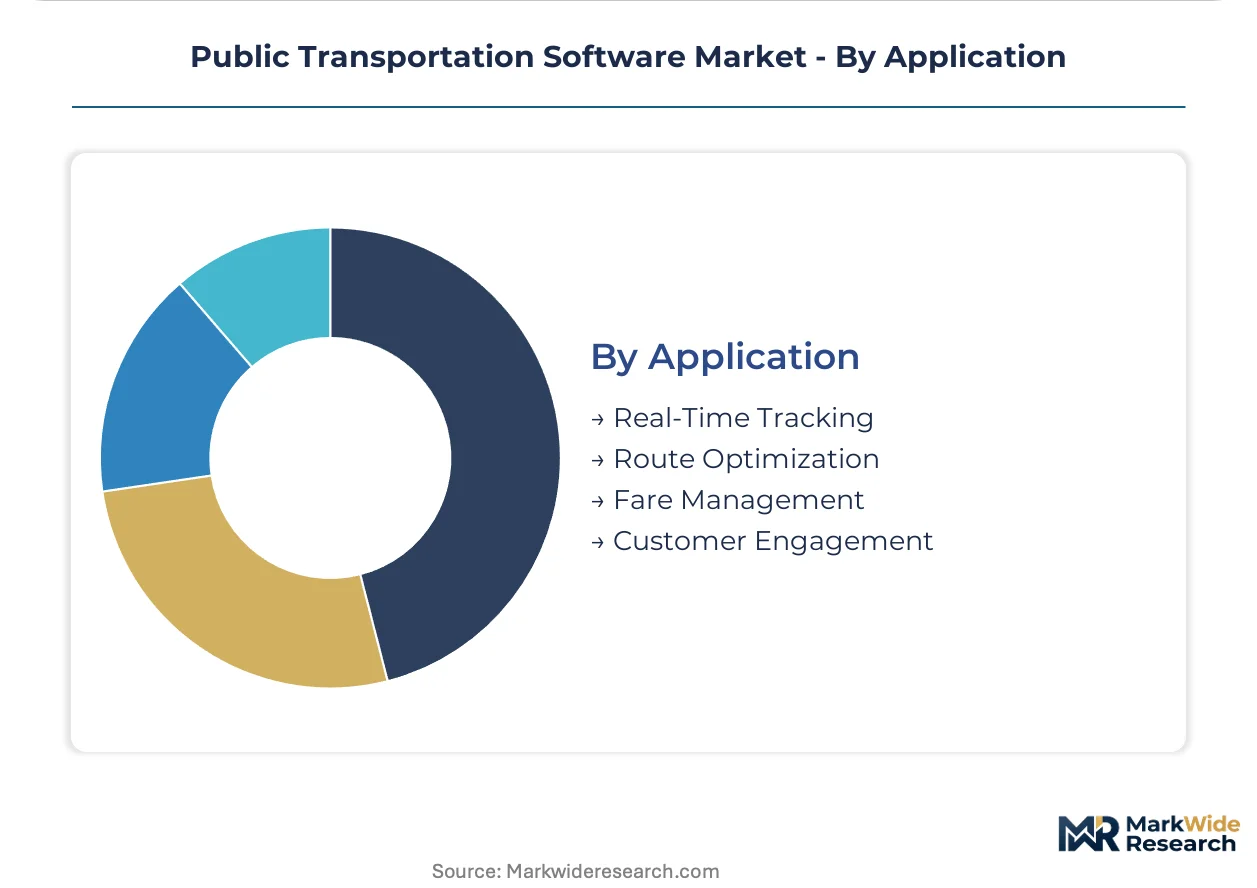
Application:
Functional modules compete for integration priority within unified platform architectures.
- Real-Time Tracking:GPS and cellular positioning systems deliver sub-minute location accuracy to control centers and passenger interfaces. Dutch operators lead deployment density where open data mandates require standardized API publication. Predictive arrival algorithms reduce perceived wait times and improve satisfaction scores.
- Route Optimization:Dynamic rerouting engines adjust service patterns based on traffic conditions, demand surges, and vehicle availability. Edge computing architectures in Germany enable sub-second latency for bus priority signal preemption. EU AI Act documentation requirements impose algorithmic audit trail obligations.
- Fare Management:Revenue protection and pricing engines balance accessibility mandates with operational sustainability.
- Customer Engagement:Personalized notifications and service alerts reduce call center burden while improving rider retention.
Real-time tracking dominates installed base; route optimization shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public transportation software originated in North American and European transit authorities during the 1970s mainframe era, with municipal operators in the United States and Germany pioneering early computerized scheduling systems for bus and rail networks.
Germany
Federal digital infrastructure subsidies are compressing procurement timelines for mid-sized transit agencies previously constrained by capital budgets. The EU Green Deal mandates emissions transparency requirements that favor integrated cloud-native platforms over legacy on-premises installations. Bavaria's Munich transit authority is restructuring specifications to prioritize algorithmic audit capabilities under EU AI Act conformity assessment.
United States
Municipal transit authorities confront Federal Transit Administration mandates for accessibility compliance and cybersecurity protocols across legacy fleet systems. The EPA's emissions tracking requirements for municipal bus fleets are accelerating replacement of decades-old dispatch hardware. Chicago's Regional Transportation Authority exemplifies procurement concentration where cloud migration contracts now favor operational expenditure treatment.
France
SNCF restructuring under EU AI Act risk classification frameworks is redirecting national rail specifications toward algorithmic explainability interfaces. The country's national pharmaceutical regulator ANSM and data protection authority CNIL impose overlapping documentation burdens on automated passenger analytics. Paris-Île-de-France Mobilités is consolidating multi-modal platform procurement around real-time data infrastructure vendors.
Netherlands
Open data mandates requiring standardized API publication for vehicle positioning are driving deployment density for real-time tracking modules. Dutch operators lead European adoption of edge computing architectures for sub-second vehicle-to-infrastructure communication. Amsterdam's GVB is integrating predictive arrival algorithms with national transit pass schemes to reduce perceived wait times.
United Kingdom
Transport for London's account-based fare collection system is influencing procurement specifications across regional bus operators transitioning from contactless card architectures. The Information Commissioner's Office enforces GDPR compliance costs on passenger data analytics platforms. Greater Manchester's Bee Network is consolidating demand-responsive transit services under unified scheduling software for paratransit digitization.
Public Transportation Software Market Key Industry Players
Capital-heavy integrated suite providers compete with asset-light point-solution specialists across functional domains. The vendor landscape fragments across three tiers: algorithmic optimization engines anchoring large-scale deployments, real-time data infrastructure sustaining mid-sized authorities, and specialized paratransit schedulers occupying compliance-driven niches. Dominant competitive moves include modular microservices decomposition that enables discrete component replacement, and subscription pricing structures displacing perpetual licenses among municipal buyers with constrained capital budgets.
Within the optimization-engine tier, Optibus and Swiftly exemplify divergent architectural approaches to municipal procurement. Optibus leverages constraint-based planning algorithms that anchor enterprise deployments across European transit authorities confronting EU Green Deal mandates. Swiftly competes through real-time data infrastructure sustaining operational visibility for mid-sized agencies prioritizing channel shift toward mobile-first engagement. Ecolane Evolution occupies the specialized paratransit position where compliance workflows for elderly and disabled rider services create defensible niche positioning against generalized platforms.
| Leading Market Players |
|---|
| Swiftly |
| PtMS |
| TripSpark Fixed Route & Paratransit |
| Spare |
| Pantonium |
| Optibus |
| Ecolane Evolution |
| Trackit |
| RideCo |
| Others |
Cost & Logistics Intelligence
Cloud compute pricing indices cascade through public transportation software supply chains, compressing margins for on-premises legacy providers while amplifying subscription revenue multiples for cloud-native vendors serving German and Dutch transit authorities.
Pricing Analysis
Annual recurring revenue structures now dominate municipal procurement, with three-tier pricing separating enterprise optimization engines from mid-market data infrastructure and entry-level dispatch modules. Price differentiation centers on integration depth and EU AI Act compliance certification levels. Cost compression in the mid-tier is intensifying because federal subsidies in Germany explicitly favor operational expenditure treatment, forcing perpetual-license incumbents to restructure. Small transit authorities exhibit highest price sensitivity, while national rail operators prioritize algorithmic audit capabilities over cost.
Supply Chain Analysis
Freight costs for edge computing hardware shipments from Taiwan and South Korea into European transit depots have elevated total deployment costs for vehicle-to-infrastructure communication modules. Software development concentrates in Israel, the United States, and Germany, drawing from specialized operations research talent pools and proximity to municipal buyer clusters. Single-source vulnerability in GPS telemetry chipsets sourced from semiconductor foundries presents structural risk. Distribution runs through systems integrators and direct municipal sales teams, with cloud marketplaces gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Public transportation software offers margin expansion through cloud migration tailwinds and premium-tier algorithmic compliance modules that command pricing premiums from EU transit authorities confronting AI Act mandates.
For Market Incumbents: To counter modular microservices specialists displacing integrated suite providers, anchor procurement relationships through long-term subscription contracts with embedded emissions analytics. Deepen upstream control over constraint-based optimization engines through captive development centers in Tel Aviv and Berlin, securing talent scarcity advantages against logistics and ride-hail platform competition. For New Entrants and Emerging Players: EU Green Deal mandates in Germany open a window for paratransit digitization specialists targeting Spain and Italy where demand-responsive transit services remain underpenetrated. Prioritize white-label CSRD reporting modules for enterprise clients as the fastest path to revenue, leveraging algorithmic transparency documentation as a differentiated go-to-market angle against generalized platform competition. For Investors and Strategic Acquirers: Consolidation pressure builds where point-solution specialists in real-time data infrastructure command valuation multiples disconnected from their standalone profitability. Frame long-term viability around recurring revenue concentration and EU regulatory compliance moats. Target acquisition profiles emphasizing cloud-native architectures with existing algorithmic audit capabilities. Monitor Common Criteria cybersecurity certification timelines as the critical inflection signal—delays beyond standard evaluation windows indicate vendor execution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microservices decomposition enables discrete component replacement, reshaping competitive dynamics against monolithic suite providers. |
| Strategic Partnership | Mobility-as-a-Service convergence with bike-share platforms creates unified payment propositions for Amsterdam and Munich commuters. |
| Acquisition of Specialist Firm | Paratransit scheduling expertise in Spain and Italy offers defensible niche positioning against generalized optimization engines. |
| Geographic Expansion | Federal digital infrastructure subsidies in Germany compress procurement timelines previously constrained by municipal capital budgets. |
| Product Launch | Algorithmic explainability interfaces satisfy SNCF restructuring requirements under EU AI Act risk classification frameworks. |
Research Approach
Direct dialogue with transit authority CTOs, municipal procurement officers, platform integration specialists, and operations research directors grounded qualitative findings, validated against secondary sources including Federal Transit Administration filings, EU Green Deal implementation reports, SEC disclosures from listed software vendors, and municipal RFP documentation. Bottom-up and top-down triangulation cross-checked vendor revenue concentration against transit agency expenditure patterns.
Bottom-up modeling segmented the market across deployment models, organization size tiers, vertical integration complexity, and regional adoption patterns, while top-down approaches validated aggregate figures against macroeconomic transit infrastructure investment flows. CAGRs were derived from slope analysis across the projection horizon, incorporating edge computing latency requirements and EU AI Act compliance timeline assumptions as industry-specific inputs.
Revisions become necessary when federal subsidy program modifications, cybersecurity certification delays, or algorithmic transparency regulatory clarifications materialize unexpectedly. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Transit Ticketing Market