
 Taxi and Limousine Software Market | 2026-2036
Taxi and Limousine Software Market Size, Share, and Industry Trends Forecast 2026-2036
Taxi and Limousine Software Market Analysis
Driver-algorithm interface expertise is redrawing competitive boundaries as platforms race to reduce onboarding friction. Limo Anywhere leverages its specialization in luxury fleet workflows to sustain premium pricing power. TaxiMobility anchors its position through deep integration with legacy dispatch hardware across multiple continents. Onde competes aggressively on white-label flexibility, allowing regional operators to launch branded apps without engineering overhead.
Taxi and limousine software encompasses cloud-native and on-premises platforms that automate dispatch, route optimization, payment settlement, and driver-passenger matching through GPS telemetry and real-time data pipelines. These systems process location streams at sub-second latency to synchronize mobile applications with fleet movements across urban environments. Deployment models reveal a structural tilt toward cloud-based architectures as small operators abandon server maintenance burdens, while on-premises installations retain footholds among large fleet owners with strict data sovereignty requirements. Technology segmentation shows GPS tracking and payment processing emerging as the highest-margin modules, with vendors bundling these capabilities into tiered subscription structures.
The Federal Communications Commission governs spectrum allocation for vehicle-to-infrastructure communications affecting real-time dispatch reliability in the United States. The European Commission's Digital Services Act imposes algorithmic transparency mandates on ride-matching platforms operating across member states. India's Ministry of Electronics and Information Technology enforces data localization standards that influence hosting decisions for vendors serving South Asian operators. Stakeholders must weigh regulatory fragmentation against standardization pressure when architecting multi-territory platform roadmaps.
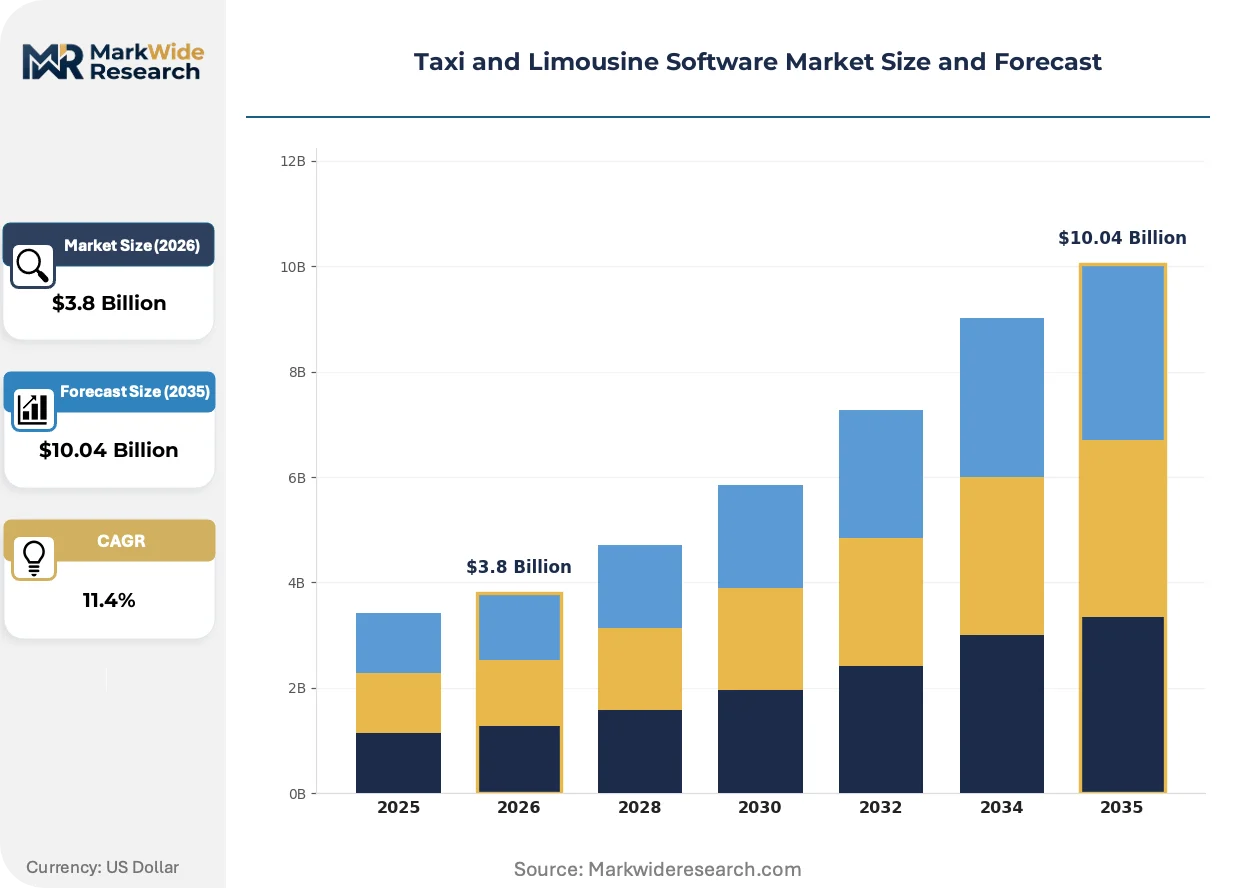
Market Dynamics
Fleet operators are abandoning on-premises dispatch infrastructure for cloud-native architectures, driven by zero-downtime requirements and the collapse of in-house server maintenance economics across urban ground transportation networks.
Growth Catalysts
- GDPR and Digital Services Act compliance mandates:European operators face algorithmic transparency requirements that accelerate replacement of legacy black-box dispatch systems with auditable platforms.
- Real-time payment settlement:GPS-telemetry integration with instant driver compensation is eliminating cash-handling friction and reducing fleet turnover in high-churn markets.
- India's data localization standards:MEITY enforcement is compelling vendors to establish sovereign hosting infrastructure, expanding addressable market for compliant platform providers.
Market Restraints
- Cloud infrastructure concentration:Dependence on hyperscale providers in US West Coast regions creates latency vulnerability and geopolitical exposure for mission-critical dispatch operations.
- Legacy hardware lock-in:Radio-frequency dispatch terminals with 15-20 year depreciation cycles obstruct software-only upgrades in municipally regulated taxi fleets.
- Driver smartphone fragmentation:Android OS version heterogeneity across emerging-market driver pools degrades real-time location pipeline reliability.
Strategic Opportunities
- White-label platform proliferation:Regional operators in Southeast Asia and Latin America seek branded application deployment without engineering overhead, opening reseller channel expansion.
- Vehicle-to-infrastructure integration:FCC spectrum allocation for C-V2X communications enables predictive dispatch based on traffic signal phase timing.
- Corporate ground transportation unbundling:Enterprise travel managers are disaggregating limousine services from bundled travel management company contracts, creating direct B2B platform procurement.
Industry Challenges
- API standardization gaps:Absence of unified protocols between dispatch platforms and municipal regulatory reporting systems forces redundant integration engineering.
- Algorithmic bias litigation exposure:Driver-ranking and trip-allocation models face scrutiny under emerging AI accountability frameworks, requiring explainability infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taxi and Limousine Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Scheduling, Dispatching, Fleet Management Technology: Mobile App, Web Portal, GPS Tracking, Payment Processing End User: Small Operators, Large Fleet Owners, Taxi Companies, Limousine Services Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Cloud |
| Companies Covered | Limo Anywhere, TaxiMobility, Yelowsoft, Autocab, Moovs, Onde, iCabbi, Gazoop, Jungleworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taxi and Limousine Software Market Emerging Trajectories
Edge-computing architectures are redistributing processing load from centralized clouds to vehicle-mounted hardware, compressing dispatch latency while complicating software update orchestration across dispersed fleet assets.
Embedded telematics units with local inference capability are displacing smartphone-dependent driver applications for location streaming and route optimization. Large fleet operators in Germany and the United States are piloting these systems to eliminate cellular dead-zone dispatch failures. This hardware shift is displacing the BYOD (bring-your-own-device) model that dominated the 2015-2022 period.
The EU AI Act's risk-classification framework for automated decision systems is imposing documentation burdens on ride-matching algorithm operators. Vendors serving European markets must now maintain technical files and conformity assessments for dispatch optimization engines. Large platform operators are responding by segregating EU-specific algorithm versions from global codebases.
Corporate procurement departments are consolidating ground transportation spend under centralized software procurement rather than reimbursing employee ride-hailing expenses. This purchasing centralization is compressing vendor sales cycles and elevating API integration capabilities above user-interface differentiation in RFP evaluations. The shift is most advanced in financial services and professional services verticals across London and New York.
Taxi and Limousine Software Market Segmentation
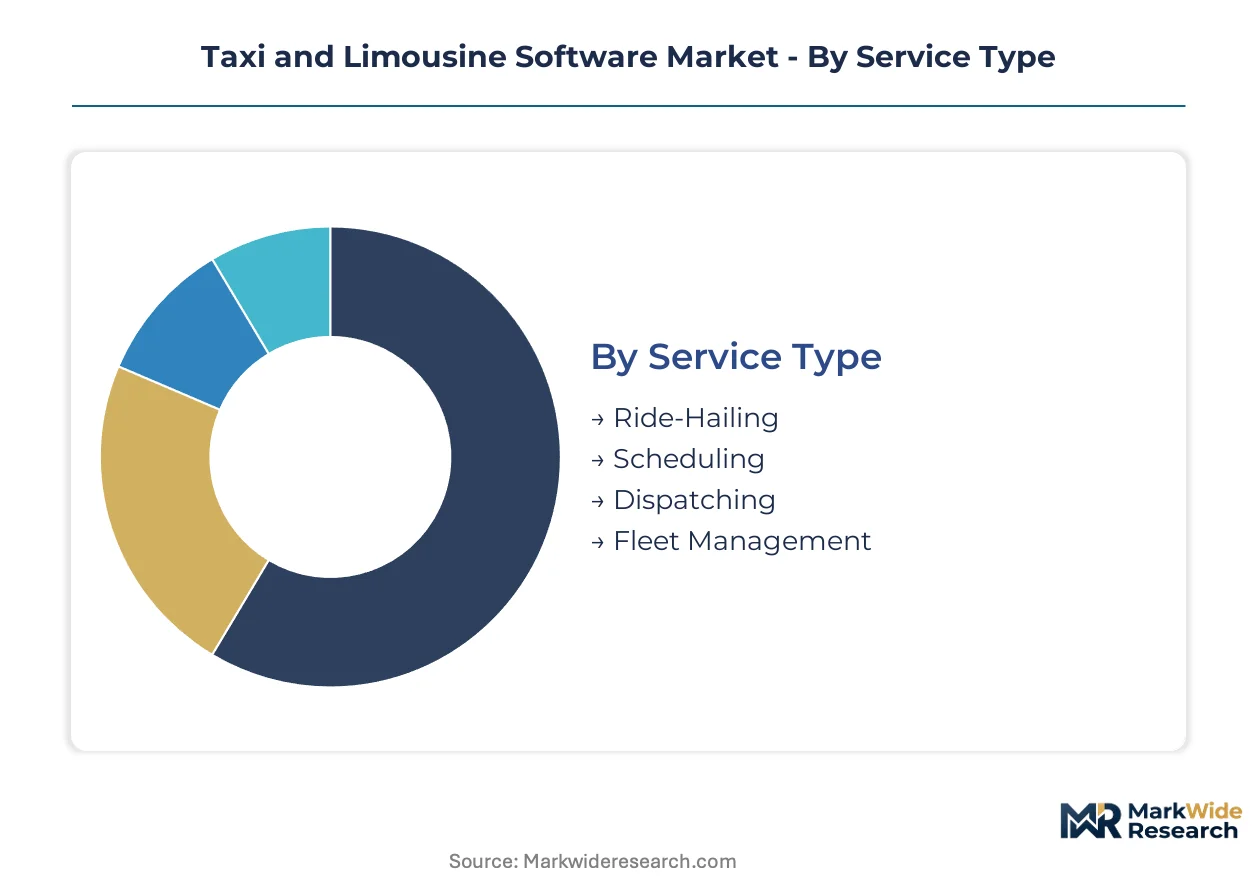
Segmentation in taxi and limousine software reveals how regulatory pressure, infrastructure maturity, and fleet scale reshape purchasing patterns. Vendors must architect modular platforms that span divergent compliance obligations and technical capabilities across operator tiers.
Service Type:
GDPR algorithmic transparency mandates and India's MEITY data localization standards create divergent functional requirements across service modules, with European operators prioritizing auditable dispatch logic and South Asian markets demanding sovereign-hosted scheduling infrastructure.
- Ride-Hailing:Real-time passenger-driver matching engines process GPS telemetry at sub-second latency to synchronize mobile applications with fleet movements. Demand concentrates in India's urban corridors where MEITY-compliant hosting infrastructure supports rapid platform deployment, though driver smartphone fragmentation across Android OS versions degrades location pipeline reliability in emerging-market pools.
- Dispatching:Automated route optimization and trip-allocation algorithms coordinate fleet movements through centralized command interfaces. Germany's KBA vehicle registration standards and municipal taxi regulations in the United States shape integration requirements with legacy radio-frequency terminals, obstructing software-only upgrades where 15-20 year hardware depreciation cycles persist.
- Scheduling:Advance booking platforms manage reservation pipelines and capacity allocation for pre-arranged transportation services.
- Fleet Management:Asset tracking and maintenance coordination systems monitor vehicle utilization across distributed operator networks.
Established volume favors Dispatching; emerging adoption favors Ride-Hailing.
Technology:
Margin concentration follows data intensity, with payment processing and GPS tracking commanding premium subscription tiers while web portals compete on cost efficiency.
- Payment Processing:Instant driver compensation engines eliminate cash-handling friction through GPS-telemetry integration with real-time settlement rails. Large fleet owners in the United States prioritize FCC-governed spectrum reliability for transaction continuity, while European operators face additional PSD2 strong customer authentication requirements for in-app payments.
- GPS Tracking:Location streaming infrastructure processes vehicle telemetry across cellular and satellite networks with sub-meter accuracy demands. India's Ministry of Electronics and Information Technology data localization enforcement compels sovereign hosting for location archives, expanding addressable market for compliant platform providers serving South Asian operators.
- Mobile App:Passenger-facing interfaces handle booking, tracking, and payment workflows across iOS and Android ecosystems.
- Web Portal:Browser-based administrative dashboards provide fleet oversight without native application deployment overhead.
Payment Processing captures the steepest expansion trajectory as real-time settlement becomes standard; Web Portal growth flattens amid mobile-first operator preferences.
End User:
Procurement centralization in corporate travel departments elevates API integration capabilities above user-interface differentiation for limousine services, while small operators prioritize white-label flexibility.
- Large Fleet Owners:Enterprise-grade platforms require strict data sovereignty compliance and edge-computing architectures to compress dispatch latency. Financial services verticals in London and New York drive demand for centralized ground transportation procurement with direct B2B platform integration.
- Small Operators:White-label solutions enable branded application deployment without engineering overhead, opening reseller channel expansion across Southeast Asia and Latin America.
- Taxi Companies:Municipally regulated fleets face legacy hardware lock-in from radio-frequency dispatch terminals with extended depreciation cycles.
- Limousine Services:Luxury workflow specialization sustains premium pricing power through specialized dispatch logic for high-value passenger segments.
Large Fleet Owners dominate current procurement volume; Small Operators are gaining share fastest through white-label platform proliferation.
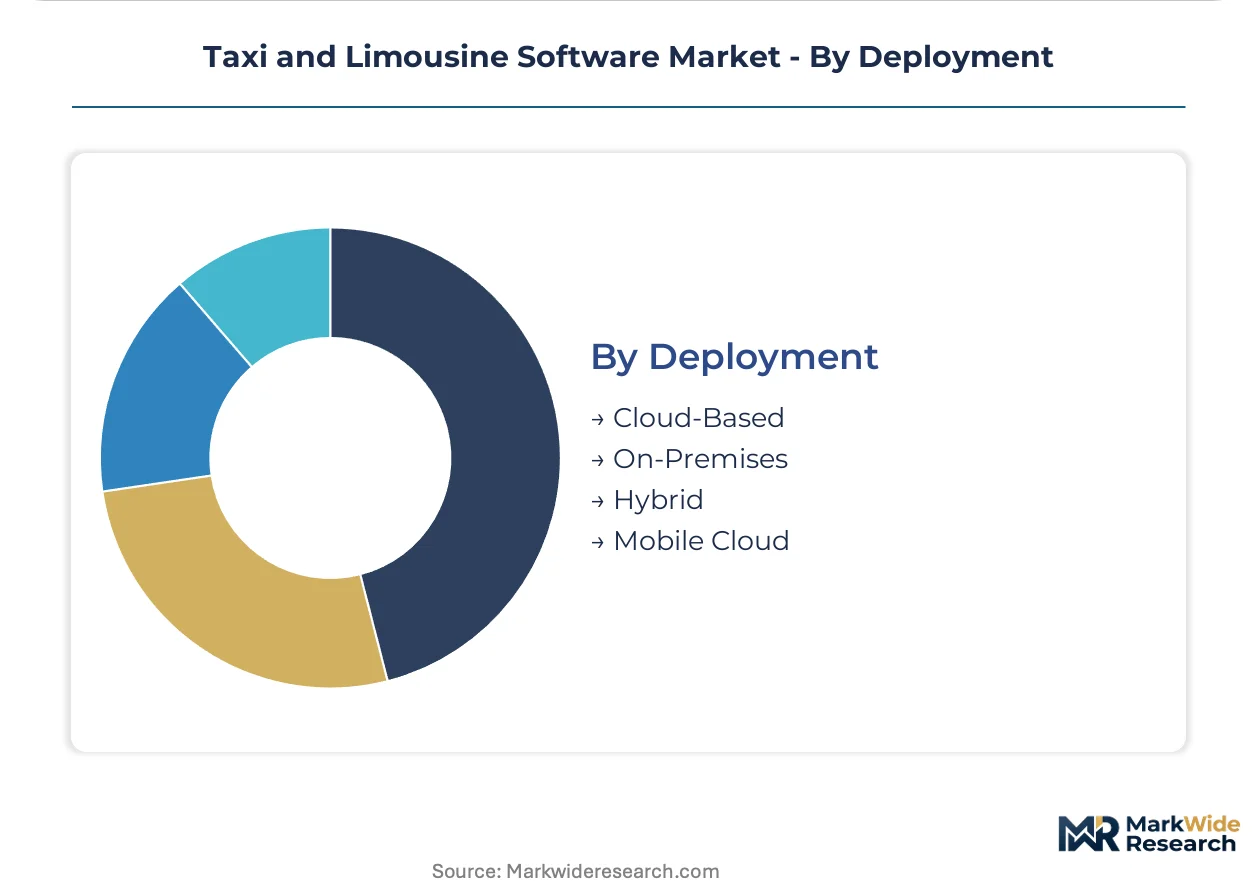
Deployment:
Cloud infrastructure concentration on US West Coast hyperscale regions creates latency vulnerability and geopolitical exposure, driving hybrid architectures among risk-conscious operators.
- Cloud-Based:Fully managed SaaS platforms eliminate server maintenance burdens as small operators abandon on-premises economics. Zero-downtime requirements across urban ground transportation networks accelerate migration from legacy dispatch infrastructure.
- Hybrid:Split architectures retain sensitive dispatch logic on-premises while offloading passenger-facing applications to cloud edge nodes. Germany's Federal Office for Information Security (BSI) baseline protection standards influence hosting decisions for operators serving public-sector contracts.
- On-Premises:Self-hosted installations persist among large fleet owners with strict data sovereignty requirements and legacy system integration obligations.
- Mobile Cloud:Vehicle-mounted edge computing redistributes processing load from centralized infrastructure to distributed fleet assets.
Cloud-Based deployment holds established volume; Hybrid architectures are climbing the fastest as regulatory fragmentation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Indian operators prioritize white-label deployment speed while German fleets demand algorithmic auditability. US buyers split between corporate procurement centralization and municipal legacy-system constraints.
United States
Fleet operators in New York and San Francisco drive corporate ground transportation unbundling, with financial services verticals procuring platforms directly. The FCC governs C-V2X spectrum allocation affecting real-time dispatch reliability. Chicago's municipally regulated taxi fleets retain radio-frequency terminals with 15-20 year depreciation cycles, obstructing software-only upgrades.
Germany
Luxury limousine workflows sustain premium pricing power through specialized dispatch logic for high-value passenger segments. The KBA vehicle registration standards and BSI baseline protection standards shape hosting decisions for operators serving public-sector contracts. Munich and Frankfurt clusters pilot embedded telematics units with local inference capability to eliminate cellular dead-zone failures.
India
Urban corridors in Mumbai and Bangalore generate rapid platform deployment demand through MEITY-compliant hosting infrastructure. The Ministry of Electronics and Information Technology enforces data localization standards compelling sovereign hosting for location archives. Driver smartphone fragmentation across Android OS versions degrades location pipeline reliability in emerging-market pools.
United Kingdom
Corporate travel managers in London consolidate ground transportation spend under centralized software procurement. The Digital Services Act imposes algorithmic transparency mandates on ride-matching platforms. The city's financial services verticals drive advanced API integration requirements above user-interface differentiation in RFP evaluations.
Canada
Toronto and Vancouver operators balance zero-downtime cloud migration against data sovereignty requirements for cross-border fleet movements. Health Canada influences telematics safety standards for vehicle-mounted hardware. Ontario's large fleet owners retain hybrid architectures with sensitive dispatch logic on-premises while offloading passenger-facing applications to cloud edge nodes.
Taxi and Limousine Software Market Vendor Landscape
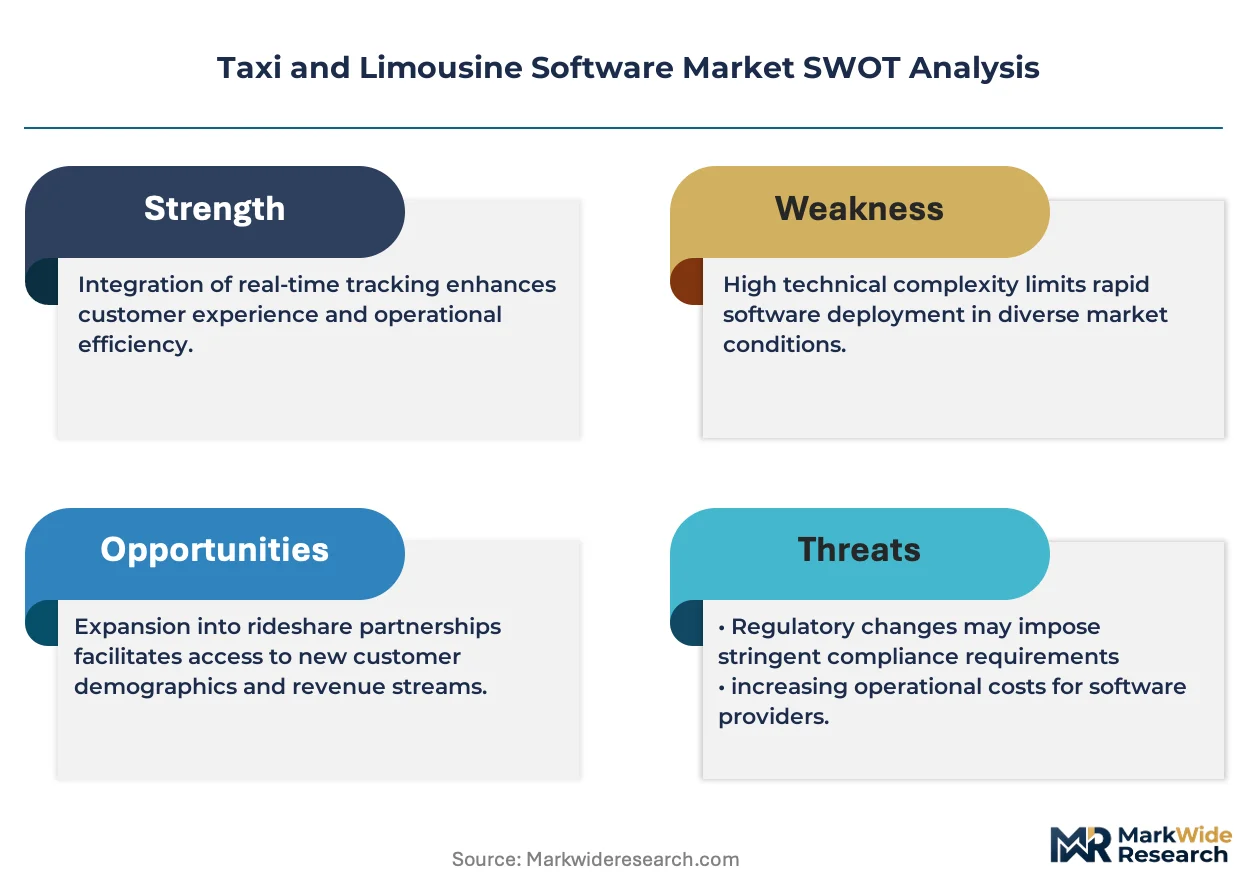
A small set of integrated leaders sits above a broader specialist tier, with vertical differentiation across luxury workflow depth, white-label flexibility, and legacy hardware integration. The market structure favors vendors bundling GPS-telemetry with payment processing into tiered subscription structures. Two strategic archetypes dominate: platform specialists optimizing driver-algorithm interfaces and infrastructure generalists spanning dispatch-to-payment stacks. Competitive moves concentrate on geographic reseller channel expansion and compliance-segregated algorithm versioning for EU markets.
Within the luxury specialization tier, Limo Anywhere anchors premium positioning through workflow depth for high-value passenger segments. TaxiMobility exemplifies legacy integration specialists, occupying a position across multiple continents through deep dispatch hardware connectivity. Onde represents white-label flexibility archetypes, enabling regional operators to launch branded applications without engineering overhead.
| Leading Market Players |
|---|
| Limo Anywhere |
| TaxiMobility |
| Yelowsoft |
| Autocab |
| Moovs |
| Onde |
| iCabbi |
| Gazoop |
| Jungleworks |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud capacity utilization in US West Coast regions anchors cost structures for SaaS vendors, concentrating supply-side leverage among AWS, Azure, and Google Cloud while compressing margins for white-label platform providers dependent on these infrastructure layers.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, with annual SaaS tiers replacing month-to-month arrangements as large fleet owners seek price predictability. Price differentiation rests on API integration depth and GDPR auditability certification, with European operators paying premiums for algorithmic transparency documentation. Cost compression in mid-market tiers is intensifying because Onde and similar white-label providers are commoditizing entry-level deployments. Small operators in Southeast Asia exhibit highest price sensitivity, while financial services verticals in London and New York prioritize integration capabilities over unit cost.
Supply Chain Analysis
Cellular modem chipset supply from Qualcomm and MediaTek facilities in Taiwan and China underwrites real-time GPS telemetry hardware, creating single-source vulnerability for embedded telematics units. Software vendors draw from Indian engineering talent pools for white-label customization, German automotive hardware suppliers for vehicle integration modules, and US hyperscale cloud infrastructure for hosting. Tariff exposure on Chinese-manufactured telematics components threatens cost structures for fleet hardware bundles. Distribution runs through direct enterprise sales teams for large fleet owners and reseller networks for regional operator segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ride-hailing super-apps threaten to subsume standalone dispatch platforms through vertical integration of driver supply and passenger demand, forcing incumbents to articulate defensible specialization.
For Market Incumbents: Compound algorithmic transparency investments to preempt EU AI Act enforcement actions and harden switching costs among European operators. Deepen vertical integration into embedded telematics hardware to displace smartphone-dependent location pipelines and eliminate cellular dead-zone failures that degrade dispatch reliability. For New Entrants and Emerging Players: Differentiate on sovereign-hosted deployment architectures to capture Indian operators facing MEITY data localization mandates. Target Latin American regional fleets with white-label solutions that bypass engineering overhead. Pursue municipal taxi fleet modernization contracts where legacy radio-frequency terminal depreciation cycles create software-only upgrade resistance. For Investors and Strategic Acquirers: Legacy hardware integration specialists with deep dispatch terminal connectivity across multiple continents present acquisition targets with durable moats against SaaS-only competitors. Long-term viability hinges on regulatory fragmentation persisting as EU algorithmic auditability, Indian data sovereignty, and US spectrum allocation regimes diverge rather than converge. Watch FCC C-V2X spectrum auction outcomes as inflection indicator for predictive dispatch technology adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| EU Algorithm Segregation | Isolates GDPR-compliant dispatch logic from global codebases to preempt Digital Services Act penalties. |
| Embedded Telematics Deployment | Displaces BYOD location streaming with vehicle-mounted edge computing to compress dispatch latency. |
| Corporate Procurement Integration | Captures financial services verticals in London and New York through direct B2B platform relationships. |
| White-Label Reseller Expansion | Opens Southeast Asian and Latin American markets without direct sales infrastructure investment. |
| Hybrid Sovereign-Cloud Architecture | Retains sensitive dispatch logic on-premises per BSI standards while offloading passenger apps to edge nodes. |
Methodological Framework
A spread of perspectives from fleet operations directors, platform engineering leads, municipal taxi regulators, and corporate travel procurement managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC spectrum allocation records, MEITY compliance circulars, EU Digital Services Act implementation guidance, and hyperscaler capex disclosures. Bottom-up triangulation across operator deployment scales and top-down segmentation by regulatory jurisdiction anchored volume estimates.
Segmentation dimensions modeled include deployment architecture, fleet size tier, service module type, and regional regulatory cluster across the analysis window. CAGRs were derived from elasticity estimates between cloud infrastructure cost curves and operator migration propensities. Forecast inputs incorporated edge-computing hardware adoption trajectories and algorithmic transparency compliance investment schedules.
Material uncertainties — MEITY enforcement intensity variations, EU AI Act risk-classification boundary shifts, and C-V2X spectrum allocation delays — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory fragmentation trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Transit Oriented Development Market