
 Electric Public Transport System Market | 2026-2036
Electric Public Transport System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Public Transport System Market Insights
The EU Green Deal is repositioning municipal procurement criteria across European transit agencies. BYD Company Ltd. leverages integrated battery manufacturing to undercut European rivals on total cost of ownership. Yutong Bus Co., Ltd. dominates domestic volume in China while extending export footprints into Latin America and Southeast Asia. Volvo Group AB anchors Nordic markets with cold-climate operational expertise.
An electric public transport system comprises zero-emission or low-emission vehicles—battery-electric buses, hydrogen fuel cell trams, hybrid shuttles, and trolleybuses—powered by onboard energy storage or catenary infrastructure, designed to move passengers along fixed or flexible routes within urban and interurban corridors. Battery electric technology leads absolute deployment volumes while fuel cell systems compete for long-haul intercity routes where charging downtime proves operationally prohibitive. Urban transit applications capture the deepest municipal subsidy pools, whereas campus circulation segments attract private operators seeking predictable ridership density.
The European Commission's F-Gas Regulation and the EPA's greenhouse gas standards for heavy-duty vehicles jointly tighten propulsion system compliance thresholds, forcing manufacturers toward full electrification or hydrogen pathways. China's MIIT enforces dual carbon goals through GB standards that mandate progressive fleet replacement timelines for state-owned transport operators. Stakeholders must monitor how subsidy phase-out schedules in Beijing and Brussels reshape total cost of ownership calculations against diesel baselines.
Market Dynamics
The EU Green Deal's 90% transport emission reduction target for 2050 is forcing municipal transit agencies to accelerate fleet electrification timelines and restructure procurement criteria around total cost of ownership rather than upfront capital expenditure.
Growth Catalysts
- EU Green Deal fleet mandates:The European Commission's binding emission targets compel transit authorities in Berlin, Paris, and Amsterdam to replace diesel buses with battery-electric alternatives on compressed schedules.
- China's MIIT dual carbon enforcement:GB standards mandate progressive fleet replacement timelines for state-owned transport operators in tier-one cities, concentrating procurement volume in Shenzhen, Beijing, and Shanghai.
- Catenary infrastructure expansion:Trolleybus and tram networks in Eastern European cities leverage existing overhead line investments to deploy zero-emission vehicles without onboard battery weight penalties.
Market Restraints
- Lithium-ion supply concentration:Cathode material processing and cell manufacturing cluster in China's Jiangsu and Fujian provinces, exposing European and North American fleet operators to geopolitical supply disruption risks.
- F-Gas Regulation compliance friction:The European Commission's phasedown of hydrofluorocarbons in thermal management systems forces manufacturers to redesign battery cooling architectures mid-product cycle.
- Grid interconnection bottlenecks:Depot charging infrastructure for 200-plus vehicle fleets requires utility-scale transformer upgrades that municipal power distributors in aging European grid zones cannot prioritize.
Strategic Opportunities
- India's urban bus electrification gap:State transport undertakings in Delhi, Mumbai, and Bengaluru operate legacy diesel fleets with minimal battery-electric penetration, creating first-mover advantage for infrastructure-financing consortia.
- Hydrogen fuel cell corridor development:Intercity express routes exceeding 400 kilometers between German metropolitan clusters favor fuel cell trams and coaches where en-route charging downtime violates service-level agreements.
- Vehicle-to-grid revenue stacking:Bi-directional charging protocols enable transit agencies to sell stored energy back to utilities during peak demand windows, offsetting capital recovery periods for battery assets.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance depots lack certified personnel capable of servicing 600-volt battery packs and integrated power electronics, forcing reliance on manufacturer service contracts.
- Multi-supplier integration complexity:Transit agencies procuring batteries from CATL, drivetrains from Siemens, and bodies from local coachbuilders face warranty attribution disputes when system-level failures occur.
- EPA heavy-duty certification timelines:New powertrain variants require 18-to-24-month validation cycles that delay revenue service entry and compress operational data feedback loops for iterative improvement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Public Transport System Market |
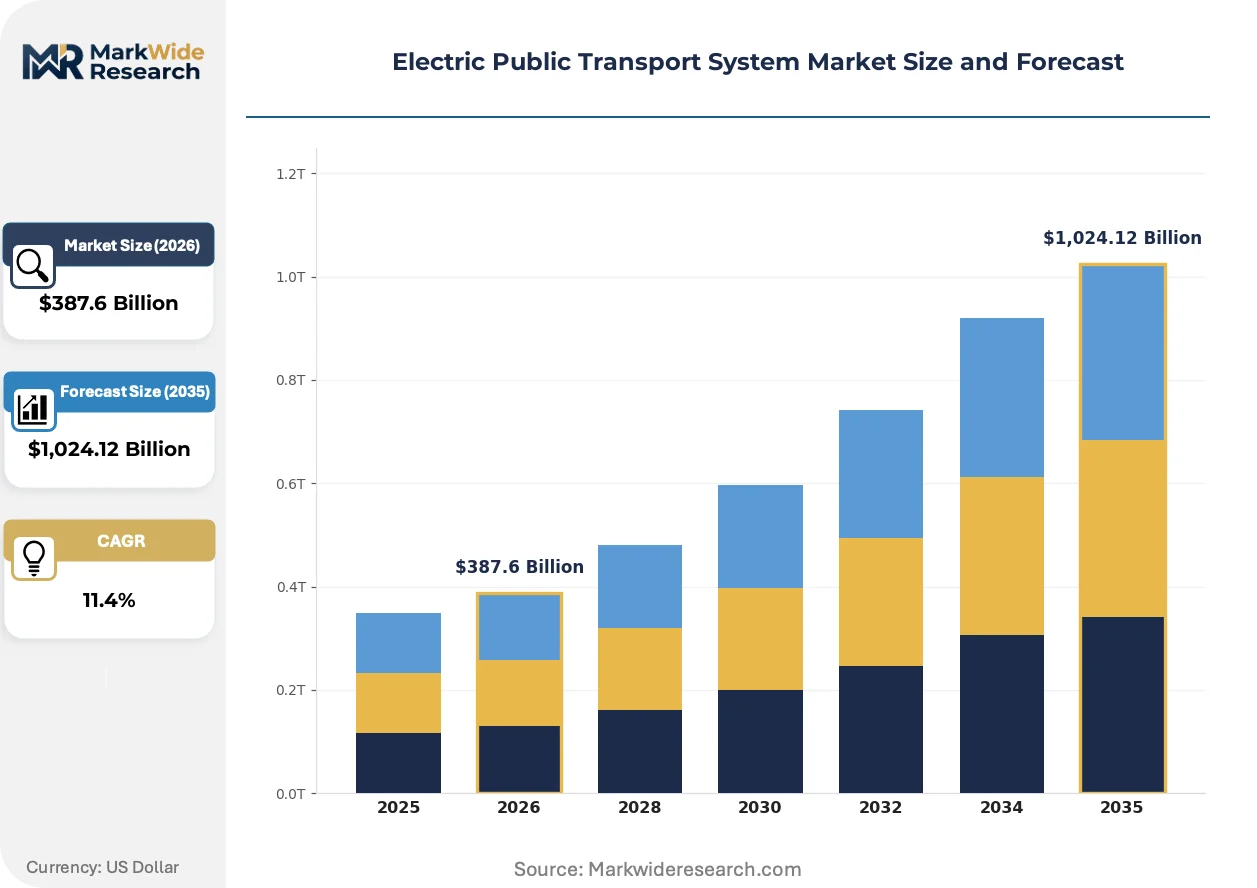
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trams, Buses, Taxis, Shuttles Technology: Battery Electric, Hybrid Electric, Fuel Cell, Trolleybus End User: Municipalities, Transportation Agencies, Private Operators, Corporate Sponsors Application: Urban Transit, Intercity Travel, Campus Circulation, Tourist Services |
| Companies Covered | BYD Company Ltd., Yutong Bus Co., Ltd., CRRC Corporation Limited, NFI Group, Volvo Group AB, Daimler Buses, Proterra, Iveco Bus, MAN Truck & Bus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Public Transport System Market Trends and Innovations
Solid-state battery chemistry and autonomous depot management software are converging to reshape how transit agencies calculate fleet availability, energy costs, and labor deployment across 24-hour operations.
Solid-state electrolyte technology is integrating lithium-metal anodes with ceramic separators to achieve energy densities exceeding 400 watt-hours per kilogram. BYD and Toyota are piloting these cells in double-decker bus prototypes for London and Tokyo routes where weight-constrained battery capacity limits daily range. This chemistry is compressing the total cost of ownership gap against diesel baselines by extending battery cycle life beyond 3,000 full discharge equivalents.
The EPA's greenhouse gas standards for heavy-duty vehicles are tightening propulsion system compliance thresholds through model year 2027 and beyond. Manufacturers must achieve fleet-average CO2 reductions or face credit trading penalties that erode margin structures. California's Advanced Clean Transit regulation is accelerating zero-emission bus deployment timelines faster than federal mandates, forcing national fleet strategies to bifurcate around CARB-compliant and federal-minimum product variants.
Municipal procurement offices are consolidating vehicle purchases into 10-to-15-year service contracts that bundle charging infrastructure, energy supply, and maintenance under single-vendor accountability. This displaces traditional capital-acquisition models where transit agencies owned assets and managed multi-supplier relationships. The Netherlands' Transdev and Germany's DB Regio are piloting these contracts in Rotterdam and Stuttgart, transferring operational risk to private operators while retaining route-level public control.
Electric Public Transport System Market Segmentation
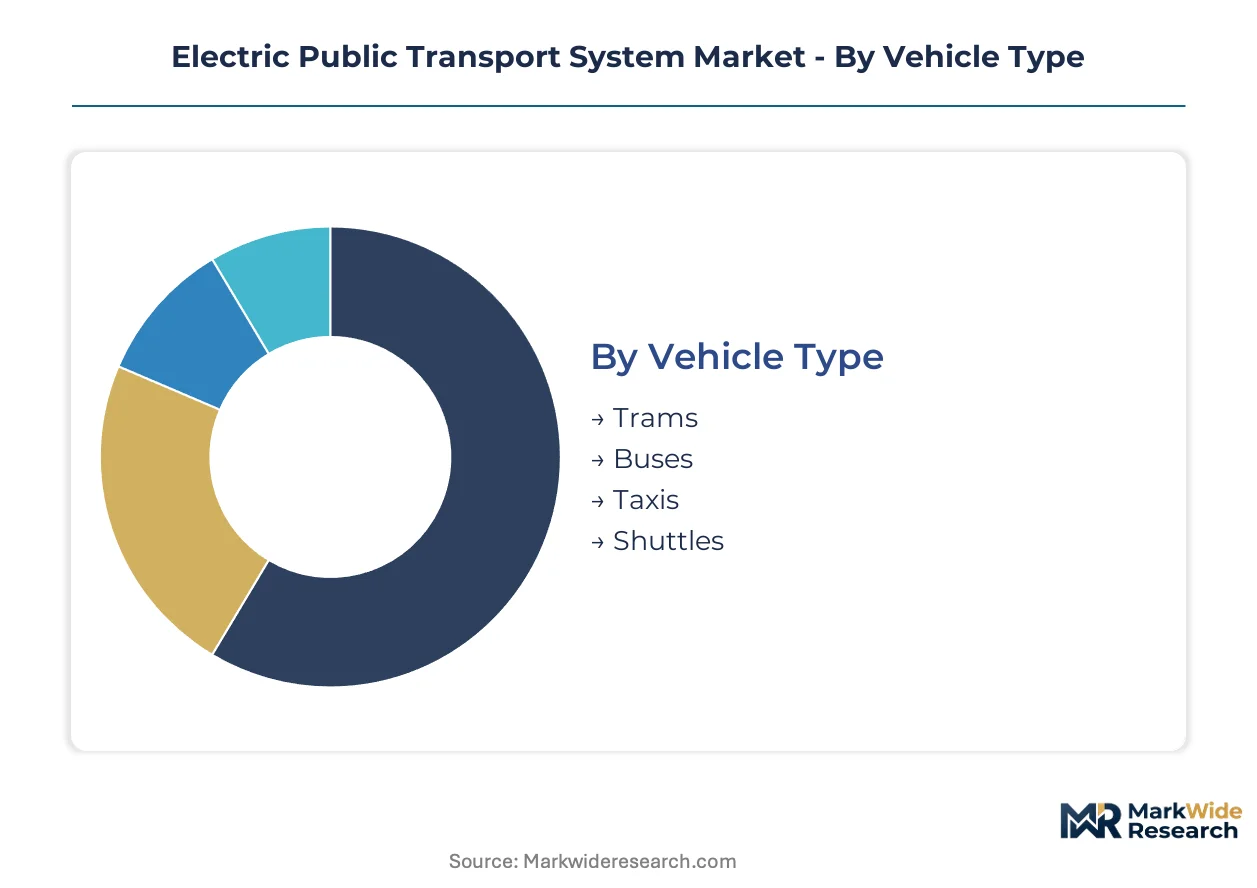
Segmentation in electric public transport reveals how procurement criteria diverge between subsidy-dependent municipal fleets and margin-driven private operators. Each dimension exposes distinct total cost of ownership calculations, infrastructure dependencies, and regulatory compliance pathways.
Vehicle Type:
Standardization dominates high-volume categories where manufacturing scale compresses unit costs, while customization persists in specialized formats serving constrained geographies.
- Buses:Articulated and single-deck configurations with battery capacities from 250 to 500 kilowatt-hours dominate absolute deployment volumes. Municipalities in Shenzhen and Berlin concentrate procurement here, driven by EU Green Deal fleet mandates and China's MIIT dual carbon enforcement timelines.
- Trams:Rail-guided vehicles drawing power from overhead catenary infrastructure eliminate onboard battery weight penalties. Eastern European cities including Prague and Warsaw leverage legacy track networks to expand zero-emission corridors without depot charging infrastructure.
- Taxis:Compact passenger vehicles operating on flexible routes require rapid-charging compatibility with urban fast-charging networks. Fleet operators in Singapore and Seoul prioritize swappable battery configurations to minimize downtime.
- Shuttles:Low-floor minibuses serving fixed-loop circuits at airports and business parks. California's Advanced Clean Transit regulation accelerates adoption at corporate campuses seeking CARB compliance credits.
Leading the category by volume: Buses. Expanding most quickly: Shuttles.
Technology:
Cost tier stratification separates mature battery platforms from emerging hydrogen systems competing on operational uptime rather than capital efficiency.
- Battery Electric:Lithium-ion phosphate and nickel-manganese-cobalt chemistries power the majority of deployed vehicles. Transit agencies in China's tier-one cities favor this technology for routes under 300 kilometers where overnight depot charging satisfies duty cycles.
- Fuel Cell:Hydrogen proton-exchange-membrane systems deliver rapid refueling for long-haul intercity routes. German metropolitan clusters including Hamburg and Cologne pilot fuel cell coaches on 400-plus kilometer express corridors where charging downtime violates service agreements.
- Hybrid Electric:Parallel and series-hybrid architectures combining downsized combustion engines with electric traction motors. Operators in grid-constrained Indian cities deploy these as transitional compliance solutions pending charging infrastructure buildout.
- Trolleybus:Rubber-tired vehicles drawing continuous power from overhead dual-wire catenary systems. Russian and Belarusian manufacturers maintain production lines serving legacy networks in Minsk and Saint Petersburg.
Dominating procurement value: Battery Electric. Gaining share fastest: Fuel Cell.
End User:
Customer type determines financing structure, with public entities accessing sovereign green bonds and private operators relying on project finance.
- Municipalities:City governments operating directly owned fleets under political accountability for emission reductions. Paris and Amsterdam structure 15-year service contracts bundling vehicles, charging infrastructure, and energy supply.
- Transportation Agencies:Regional or national public bodies managing multi-city networks. Germany's DB Regio and Netherlands' Transdev consolidate procurement across Rotterdam and Stuttgart to achieve vendor scale discounts.
- Private Operators:Commercial entities bidding for route concessions under gross-cost or net-cost contracts. Latin American operators in Santiago and Mexico City expand battery-electric penetration where subsidy mechanisms offset diesel price advantages.
- Corporate Sponsors:Employers funding campus circulation or employee shuttle services as ESG compliance instruments. Technology campuses in Bengaluru and Austin deploy electric shuttles to satisfy Scope 3 emission reduction commitments.
Capturing majority fleet volume: Municipalities. Steepest expansion trajectory: Corporate Sponsors.
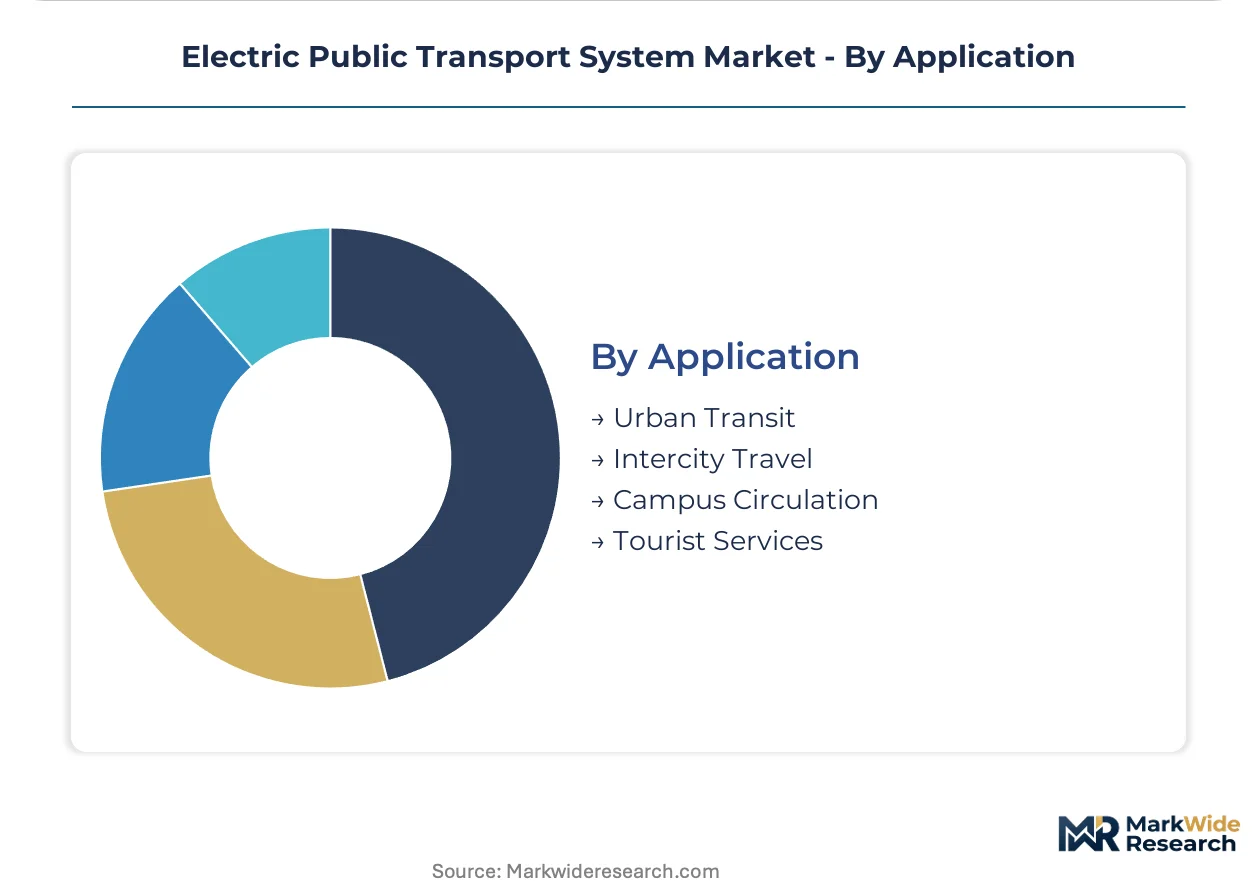
Application:
Geography and ridership density dictate vehicle sizing, with high-frequency urban corridors justifying heavy infrastructure investment that tourist circuits cannot amortize.
- Urban Transit:High-capacity trunk routes serving dense metropolitan cores with 5-minute headways. Battery-electric buses in London and Stockholm achieve 18-hour daily utilization through opportunity charging at terminal loops.
- Intercity Travel:Scheduled services connecting metropolitan areas with predictable load factors. Fuel cell and battery-electric coaches in France's Ouibus and Germany's FlixBus networks compete on total trip time including refueling stops.
- Campus Circulation:Closed-loop circuits serving universities, hospitals, and corporate headquarters with captive ridership. Private operators favor this segment for revenue predictability and simplified right-of-way negotiations.
- Tourist Services:Seasonal operations including hop-on hop-off circuits and heritage tram routes. Open-top double-decker electrics in Barcelona and San Francisco prioritize passenger experience over energy efficiency optimization.
Commanding capital deployment: Urban Transit. Climbing the fastest: Campus Circulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the world's largest battery-electric bus deployment, with municipal operators managing over 16,000 zero-emission vehicles across dense urban corridors. Procurement concentration in this southern Chinese metropolis shapes supplier production schedules and battery supply chain flows across Asia-Pacific manufacturing zones.
China
State-owned transit operators in Beijing and Shanghai execute MIIT-mandated fleet replacement timelines under dual carbon enforcement protocols. GB standards progressively tighten emission thresholds for municipal bus procurement. The Yangtze River Delta cluster around Shanghai concentrates tram and trolleybus manufacturing capacity serving domestic and export markets.
Germany
Berlin's BVG transit authority accelerates battery-electric bus procurement to meet EU Green Deal emission reduction trajectories. The F-Gas Regulation phases down hydrofluorocarbon use in thermal management systems, forcing cooling architecture redesigns. Industrial concentration in North Rhine-Westphalia hosts Daimler Buses and MAN Truck & Bus production facilities serving European fleet operators.
United States
California's Advanced Clean Transit regulation drives zero-emission bus deployment faster than federal EPA heavy-duty standards. Transit agencies in Los Angeles and San Francisco structure 10-to-15-year service contracts bundling vehicles with charging infrastructure. Proterra and NFI Group anchor domestic manufacturing capacity serving CARB-compliant procurement pools.
India
State transport undertakings in Delhi and Mumbai operate legacy diesel fleets with minimal battery-electric penetration, creating infrastructure financing gaps. The national PLI scheme for advanced chemistry cell manufacturing targets supply chain localization. Bengaluru's technology campuses pilot electric shuttle services as ESG compliance instruments for corporate sponsors.
France
Paris structures 15-year service contracts with Transdev and RATP bundling vehicles, energy supply, and maintenance under single-vendor accountability. The EU Green Deal's binding emission targets compel Île-de-France Mobilités to compress diesel replacement schedules. Iveco Bus maintains manufacturing presence serving municipal procurement across Western European markets.
Electric Public Transport System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across battery chemistry integration and cold-climate operational expertise. The vendor base stratifies between integrated battery manufacturers and vehicle assemblers sourcing powertrains from tier-one suppliers. Three archetypes dominate: state-backed Chinese conglomerates with captive cell production, European incumbents leveraging service network density, and North American specialists targeting subsidy-rich transit agency procurement. Competitive moves concentrate on long-term service contract bundling and geographic expansion into underpenetrated municipal markets.
Within the integrated-manufacturer tier, BYD Company Ltd. and Yutong Bus Co., Ltd. exemplify state-backed scale advantages in battery-electric bus deployment. CRRC Corporation Limited occupies a position bridging rail-guided vehicle manufacturing with urban transit system integration. These Chinese entities represent archetypes of vertical control over cell chemistry and vehicle assembly that European and North American competitors struggle to replicate without subsidy-backed capital structures.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| Yutong Bus Co., Ltd. |
| CRRC Corporation Limited |
| NFI Group |
| Volvo Group AB |
| Daimler Buses |
| Proterra |
| Iveco Bus |
| MAN Truck & Bus |
| Others |
Pricing and Supply Chain Analysis
Captive battery manufacturing within Chinese state-owned conglomerates anchors supply security and compresses procurement pricing for municipal fleet operators. This integration pattern forces European and North American assemblers to absorb margin compression or pursue joint-venture structures with cell suppliers.
Pricing Analysis
Outcome-based service contracts now anchor municipal procurement decisions across tier-one cities. Three-tier pricing structure across premium, standard, and economy levels separates cold-climate certified vehicles from temperate-zone configurations and basic compliance-grade alternatives. Cost compression in the economy tier is intensifying because Chinese integrated manufacturers leverage in-house cell production. Private campus operators exhibit the highest price sensitivity, whereas Nordic municipal agencies prioritize total cost of ownership over capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with cathode precursor processing concentrated in China's Jiangsu and Fujian provinces. The electric public transport ecosystem draws from lithium carbonate extraction in Australia, Chile, and Argentina, plus separator membrane production in Japan and South Korea. Geopolitical trade restriction risk looms over European fleet operators dependent on Chinese cell imports. Distribution runs through state-owned procurement consortia in domestic markets and EPC-financing bundles in export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where cell chemistry control determines margin survival. Players are pursuing backward integration into lithium refining and separator manufacturing to secure supply positions.
For Market Incumbents: To counter subsidy-dependent procurement volatility in European markets, Daimler Buses and Volvo Group should consolidate charging infrastructure partnerships with municipal utilities while accelerating in-house solid-state battery pilot programs. Certification investment in EU F-Gas Regulation compliance creates defensive moats against Chinese cost advantages. For New Entrants and Emerging Players: Solid-state battery chemistry breakthroughs offer the most penetrable wedge for specialized manufacturers targeting London and Tokyo double-decker replacement cycles. India's state transport undertakings in Delhi and Mumbai present white-space opportunities for infrastructure-financing consortia bundling vehicles with depot charging. A technology-licensing go-to-market angle bypasses capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-technology acquisitions by automotive Tier 1 suppliers seeking electrification capabilities. Long-term viability hinges on securing offtake agreements with state-owned operators in China's tier-one cities. The signal to watch is MIIT subsidy phase-out announcements that would compress margin structures for non-integrated assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD cell offtakes secure capacity for European OEM electrification timelines. |
| Charging Infrastructure Partnership | Utility joint ventures in Berlin and Rotterdam resolve grid interconnection bottlenecks for fleet operators. |
| Platform Standardization | Common bus chassis architectures reduce part complexity across municipal and intercity variants. |
| Geographic Manufacturing Footprint | North American assembly plants satisfy Buy America provisions for federal transit grants. |
| Software-Defined Vehicle Investment | Autonomous depot management systems optimize fleet availability and labor deployment. |
Research Methodology
Independent corroboration across fleet procurement officers, battery supply chain managers, and municipal finance directors underwrites the qualitative findings. Primary fieldwork with transit agency CTOs, OEM platform engineers, and charging infrastructure EPC contractors combined with secondary validation from EPA heavy-duty certification databases, EU F-Gas Regulation filings, and MIIT GB standard disclosures. Bottom-up vehicle deployment tallies triangulate against top-down municipal budget allocation estimates.
Rate-of-change decomposition across vehicle type, technology architecture, end-user financing structure, and regional regulatory cluster shapes the analytical framework. Segmentation modeling incorporates propulsion system, fleet ownership model, application corridor density, and climate-zone operational requirements. CAGRs derive from installed base replacement schedules and subsidy phase-out trajectories. Forecast inputs include lithium carbonate price volatility bands and grid interconnection approval timelines.
Several conditions sit outside the modeled scope, including hydrogen fuel cell infrastructure buildout pace and autonomous vehicle regulatory approval pathways. Forecasts reflect documented assumptions about subsidy continuity and battery chemistry cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Transit Ticketing Market