
 Qatar Taxi Market | 2026-2036
Qatar Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Taxi Market Insights
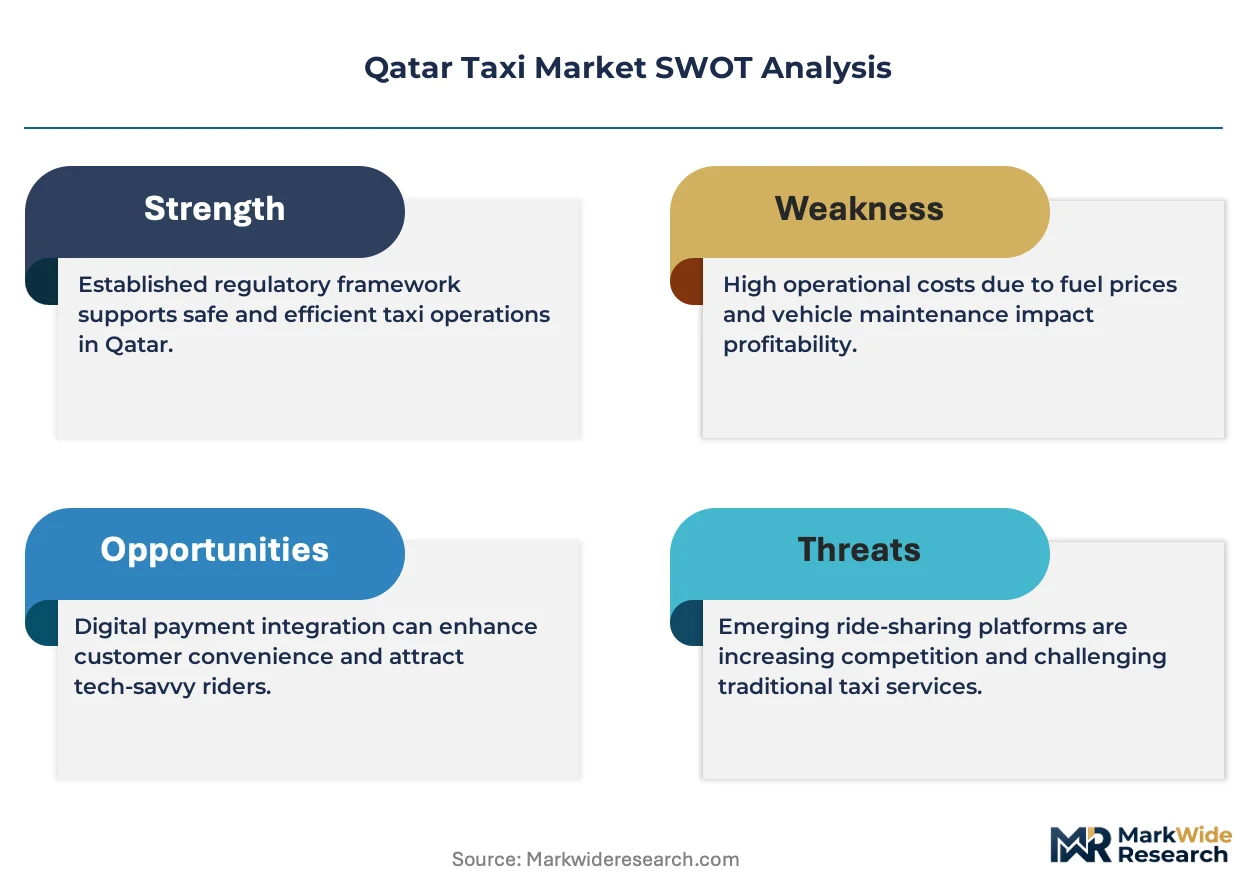
Asset-light fleet leasing is rewriting competitive dynamics in Qatar's taxi sector. Mowasalat Taxis anchors its position through state-backed fleet scale and exclusive airport access. Uber leverages its global technology stack to compete on app-based booking convenience. BadrGo specializes in localized Arabic-language service, differentiating through cultural customization that larger platforms rarely match.
Qatar taxi services comprise licensed passenger transport vehicles operating on fixed or dispatched routes, typically governed by metered fare systems and real-time GPS compliance. These vehicles serve commercial mobility needs across urban corridors, airports, and event venues, with sedans and SUVs forming the operational backbone due to passenger volume and road infrastructure demands. Luxury taxi and ride-hailing segments capture premium margin pools as business travelers and tourists prioritize comfort and predictability. Electric vehicle deployment within fleets remains nascent but draws policy support from Qatar's national sustainability framework.
Qatar's Ministry of Transport and Communications regulates licensing, fare structures, and digital platform compliance, while the Qatar Central Bank governs mobile payment interoperability that ride-hailing operators must integrate. These frameworks shape market access by mandating local partnership requirements and data sovereignty provisions for foreign platforms. Stakeholders must monitor how emission standards and driver classification rules evolve as the state advances its smart city agenda.
Market Dynamics
Qatar's Ministry of Transport mandates GPS tracking and digital meter integration for all licensed operators, forcing fleet-wide technology retrofits that reshape capital allocation and vendor selection across the sector.
Growth Catalysts
- Qatar National Vision 2030:Sustainability targets drive electric vehicle pilot programs and charging infrastructure deployment, creating fleet modernization incentives for operators.
- Corporate managed travel:Multinational firms centralize ground transport under service contracts, consolidating demand toward platforms with enterprise-grade booking and reporting capabilities.
- Real-time dispatch algorithms:Dynamic routing optimization reduces passenger wait times and vehicle deadheading, improving asset utilization rates for digital-first operators.
Market Restraints
- Driver supply constraints:Qatar's kafala sponsorship system limits labor mobility and increases recruitment costs for fleet operators expanding vehicle counts.
- Airport access concentration:Exclusive concession agreements at Hamad International Airport restrict market entry for new competitors seeking high-yield passenger segments.
- Petroleum price volatility:Fuel costs constitute a major operating expense line, compressing margins when global oil markets spike without corresponding fare adjustment mechanisms.
Strategic Opportunities
- Lusail City expansion:The new smart city's entertainment and residential districts lack mature transport networks, opening first-mover positioning for operators establishing local presence.
- Interoperable mobile payments:Qatar Central Bank's framework for digital wallet integration enables seamless fare settlement, reducing friction for cashless-first tourists and business travelers.
- Event-driven surge capacity:FIFA World Cup legacy infrastructure and recurring international sporting calendars create predictable demand spikes that reward flexible fleet scaling.
Industry Challenges
- Legacy dispatch system migration:Traditional radio-based taxi cooperatives face complex integration timelines when retrofitting digital booking platforms without disrupting daily operations.
- Data sovereignty compliance:Foreign ride-hailing platforms must localize passenger data storage and processing, adding infrastructure costs and architectural complexity to market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Taxi Market |
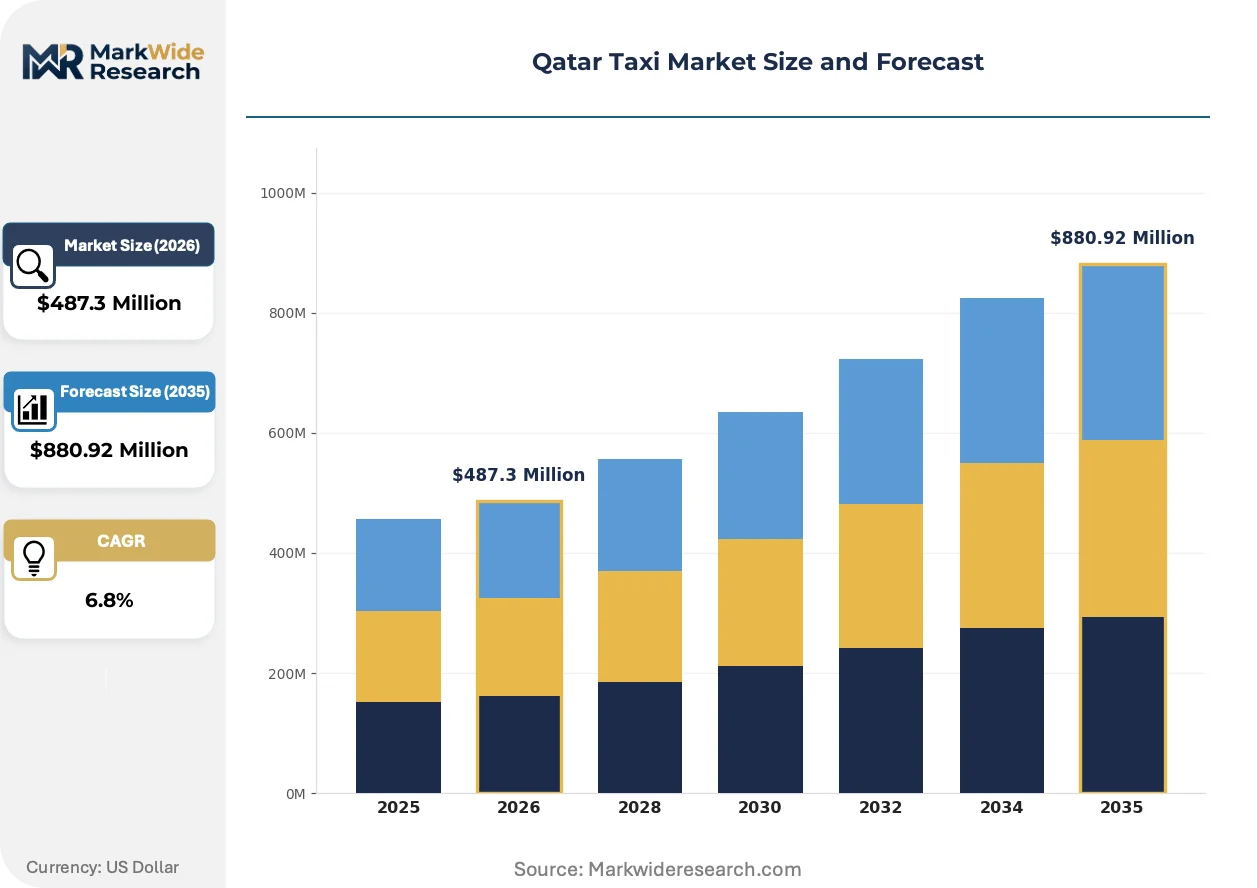
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Taxi, Luxury Taxi, Ride-Hailing, Airport Transfer Vehicle Type: Sedan, SUV, Minivan, Electric Vehicle Payment Method: Cash, Credit Card, Mobile Payment, Prepaid Customer Type: Business Traveler, Tourist, Local Resident, Corporate Client |
| Companies Covered | BadrGo, SIXT ride, Mowasalat Taxis (Karwa Taxis), Fox Transport, Doha Cabs, Uber, Zoom Ride, Discover Doha, Ryde, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Taxi Market Trends and Innovations
Digital infrastructure is displacing analog dispatch methods across Qatar's taxi sector, with platform economics and regulatory digitization converging to redefine how operators compete for passenger acquisition and driver retention.
Artificial intelligence-powered demand forecasting is digitizing fleet deployment decisions. Mowasalat and private operators deploy predictive models that anticipate stadium event dispersals and flight arrival clusters. The technology compresses passenger wait times from minutes to seconds during peak demand windows.
Qatar's Ministry of Transport and Communications enforces mandatory telematics integration for all licensed vehicles. The policy creates compliance costs for smaller operators while rewarding scale players with integrated technology stacks. Fleet owners are responding by consolidating through operational partnerships to share platform development burdens.
Corporate procurement departments now mandate consolidated ground transport reporting with carbon accounting attachments. This behavioral shift favors operators offering API-connected booking tools and emissions tracking over traditional street-hail or phone-dispatch services. Doha's central business district exhibits the strongest concentration of this specification-driven selection pattern.
Qatar Taxi Market Segmentation
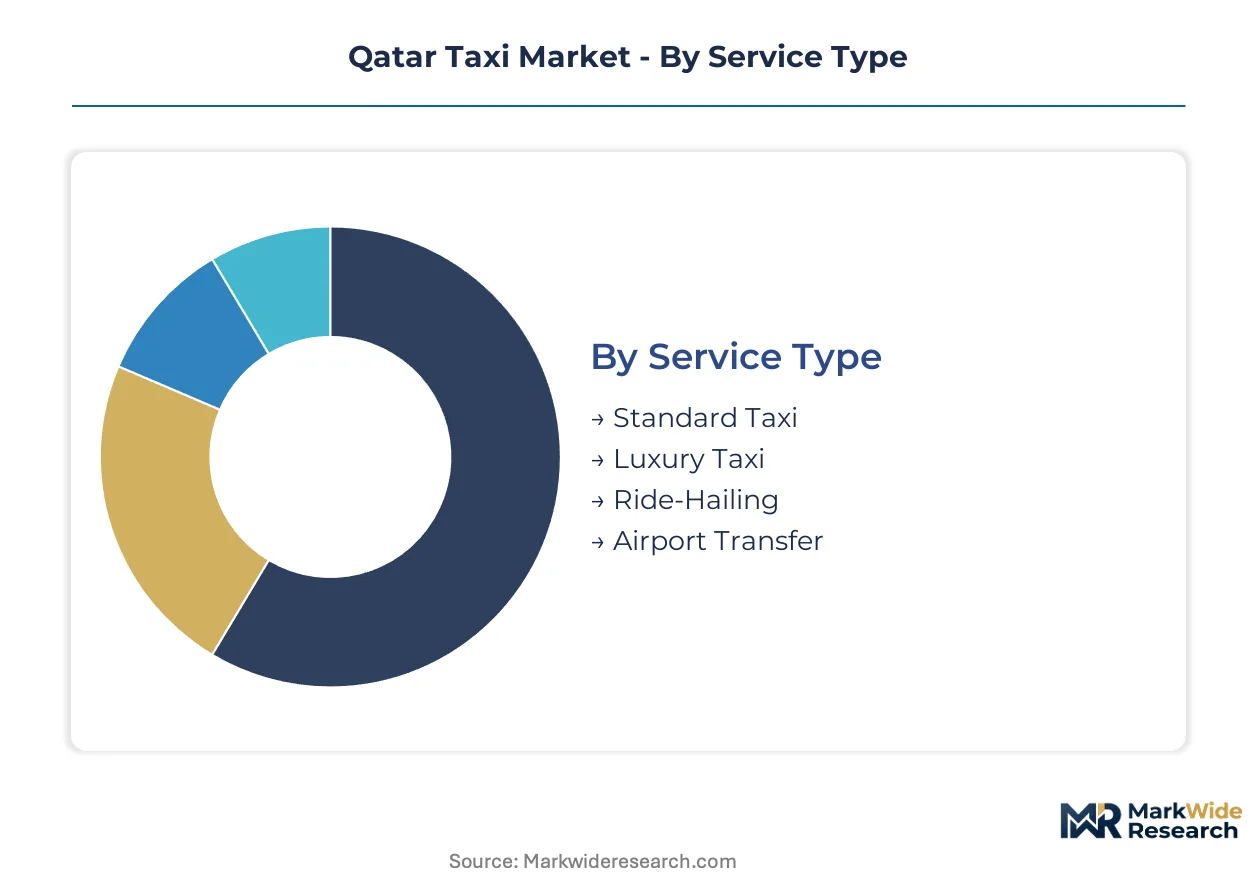
Segmentation in Qatar's taxi market reveals distinct operational economics and customer acquisition patterns. Service tiers separate by margin structure, while vehicle and payment configurations reflect infrastructure maturity and regulatory compliance requirements across Doha, Lusail, and airport corridors.
Service Type:
Cycle times vary dramatically across service tiers, with airport transfers and luxury bookings extending utilization windows while ride-hailing compresses turnaround through algorithmic matching.
- Standard Taxi:Metered sedans operating under Karwa and Mowasalat licensing dominate street-hail and dispatch volume. Fleet operators in Doha's central business district prioritize this segment for baseline capacity coverage during peak commuting windows.
- Luxury Taxi:Premium sedans and SUVs command fare multiples through enhanced comfort specifications and guaranteed vehicle age limits. Business travelers arriving at Hamad International Airport drive concentration here, particularly for government and diplomatic protocol requirements.
- Ride-Hailing:App-based platforms leverage dynamic pricing and real-time driver positioning to capture spontaneous demand. Qatar Central Bank's mobile payment interoperability mandates shape platform technical architecture.
- Airport Transfer:Pre-booked fixed-route services operate under exclusive concession frameworks at Hamad International. Mowasalat maintains anchor positioning through state-backed fleet scale and terminal access rights.
Standard Taxi anchors the volume base while Ride-Hailing gains share at the steepest rate.
Vehicle Type:
Cost tiers separate clearly across vehicle configurations, with acquisition price and fuel efficiency creating divergent margin profiles for fleet operators.
- Sedan:Toyota Camry and Honda Accord variants constitute the operational backbone for metered services. Sedan depreciation schedules and parts availability favor high-mileage operators serving Doha-Lusail commuter corridors.
- SUV:Seven-seat configurations capture family and group transport demand with luggage capacity premiums. Airport transfer operators and luxury service tiers concentrate SUV deployment for passenger volume flexibility.
- Minivan:High-capacity vehicles serve event-driven surge requirements and corporate shuttle contracts. FIFA World Cup legacy infrastructure continues generating intermittent demand spikes for this configuration.
- Electric Vehicle:Nissan Leaf and Tesla Model 3 pilot programs operate under Qatar National Vision 2030 sustainability incentives. Charging infrastructure gaps in Lusail and peripheral districts constrain deployment scale.
Sedan configurations dominate fleet composition while Electric Vehicle procurement climbs fastest amid policy-driven modernization mandates.
Payment Method:
Customer type and transaction value shape payment method selection, with corporate accounts and tourist segments driving divergence from cash-dominant legacy patterns.
- Cash:Remains prevalent among local residents and short-haul trips in traditional taxi services. Qatar Central Bank's interoperability framework gradually displaces cash handling costs for fleet operators.
- Credit Card:Terminal infrastructure investments concentrate in airport and hotel pickup zones. Business traveler preference for expense reconciliation drives adoption in premium service tiers.
- Mobile Payment:Apple Pay, Google Pay, and local wallet integration accelerate through regulatory mandates. Ride-hailing platforms and younger demographic segments exhibit highest penetration rates.
- Prepaid:Corporate managed travel accounts and event transport contracts utilize bulk purchase arrangements. Mowasalat enterprise solutions anchor this segment through consolidated billing capabilities.
Cash transactions retain volume leadership while Mobile Payment expands most quickly among digital-native customer cohorts.
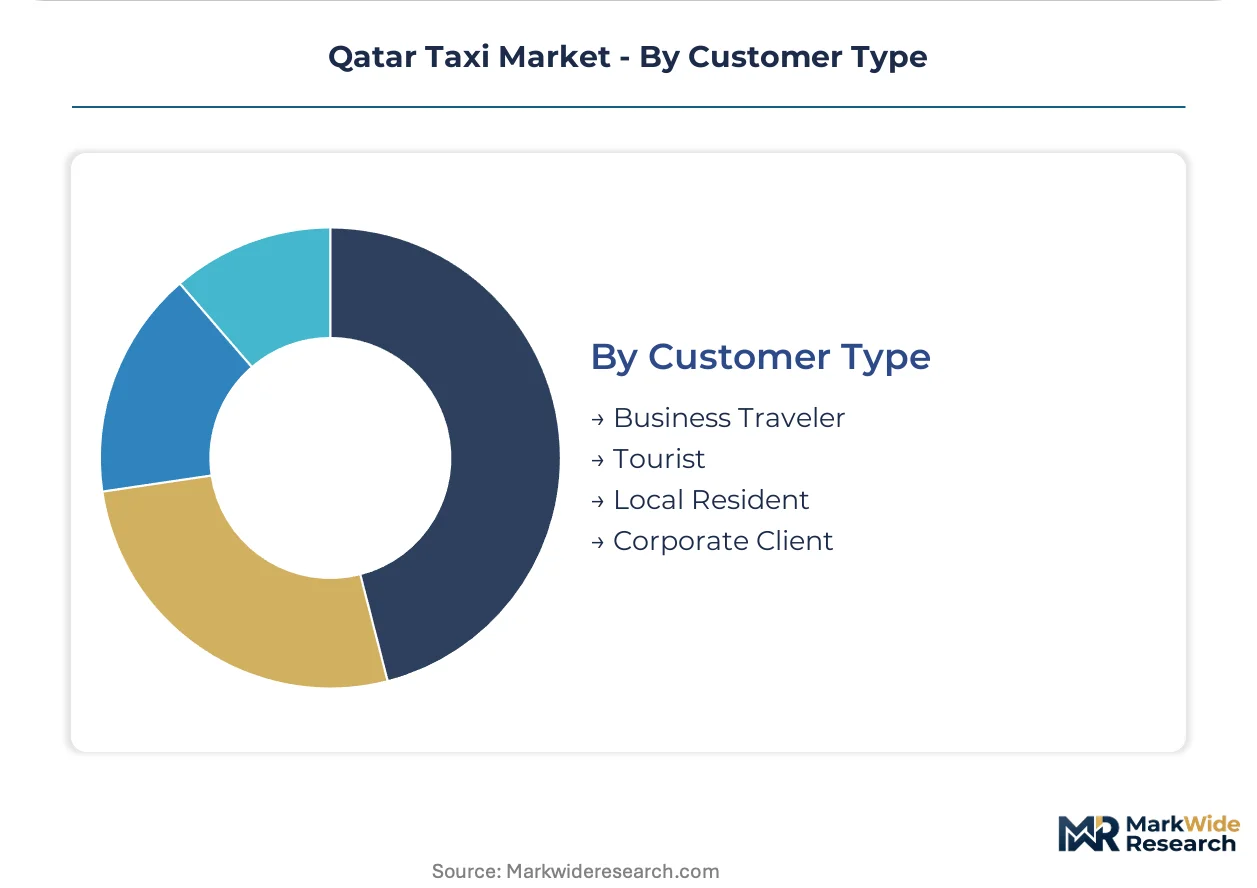
Customer Type:
Application context determines service specification, with journey purpose and expense treatment creating distinct procurement behaviors across segments.
- Business Traveler:Expense-account transport demands reliability guarantees and digital receipt integration. Doha's West Bay financial district concentrates this segment during weekday peak periods.
- Tourist:Cruise ship and hotel concierge bookings prioritize English-language service and fixed-rate certainty. Museum and souq circuits generate predictable demand clustering in historic districts.
- Local Resident:Price-sensitive routine mobility favors street-hail availability and familiar driver relationships. Residential density in Al Wakrah and Al Khor shapes geographic service priorities.
- Corporate Client:Multinational firms centralize ground transport under managed service contracts with carbon reporting attachments. API-connected booking tools and consolidated invoicing separate winning bids from commodity providers.
Local Resident demand provides the volume foundation while Corporate Client procurement expands at the steepest trajectory through centralized travel management adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's Ministry of Transport mandates GPS tracking and digital meter integration for all licensed operators, forcing fleet-wide technology retrofits that reshape capital allocation across the emirate's transport corridors.
Doha
Corporate managed travel contracts and West Bay financial district commuting dominate demand generation. Qatar Central Bank's mobile payment interoperability mandates accelerate cashless adoption in the capital's premium service tiers. Hamad International Airport and the central business district concentrate fleet deployment for high-yield passenger segments.
Lusail
The new smart city's entertainment districts and residential towers lack mature transport networks, opening first-mover positioning for operators. Qatar National Vision 2030 sustainability targets drive electric vehicle pilot programs in this planned development zone. Stadium infrastructure and waterfront retail clusters generate intermittent surge demand requiring flexible fleet scaling.
Al Wakrah
Price-sensitive local resident mobility favors street-hail availability and familiar driver relationships in this densely populated southern municipality. The Ministry of Transport's telematics integration requirements apply uniformly across all operational zones. Industrial zones and port facilities create distinct commuter patterns separate from tourist-oriented corridors.
Al Khor
Energy sector employment and northern industrial facilities sustain baseline demand for scheduled transport services. Regulatory compliance costs for smaller operators pressure consolidation through operational partnerships. Residential expansion along the northern highway corridor extends service radius requirements for fleet operators.
Al Rayyan
Educational institutions and sports complex traffic generate predictable demand clustering distinct from central Doha patterns. The kafala sponsorship system constrains driver supply expansion for fleet operators seeking to match vehicle counts to passenger volume. Mall of Qatar and surrounding retail infrastructure anchor suburban mobility patterns.
Qatar Taxi Market Competitive Landscape
On the supply side, the industry is bifurcated between state-backed incumbents with exclusive infrastructure access and global technology platforms competing on digital convenience. Mowasalat Taxis holds anchor positioning through fleet scale and airport concession rights. Uber and BadrGo represent divergent competitive archetypes: global technology stack deployment versus localized cultural customization. Dominant competitive moves center on strategic partnerships for payment interoperability and portfolio diversification into corporate managed travel contracts.
Within the state-backed tier, Mowasalat Taxis (Karwa Taxis) exemplifies incumbent positioning through exclusive terminal access and enterprise billing capabilities. Among global platforms, Uber occupies the technology-first archetype leveraging algorithmic dispatch and brand recognition. BadrGo represents the localization specialist archetype, differentiating through Arabic-language service customization that larger platforms rarely match.
| Leading Market Players |
|---|
| BadrGo |
| SIXT ride |
| Mowasalat Taxis (Karwa Taxis) |
| Fox Transport |
| Doha Cabs |
| Uber |
| Zoom Ride |
| Discover Doha |
| Ryde |
| Others |
Pricing and Supply Chain Analysis
Vehicle procurement from Japanese and Korean OEMs concentrates upstream supply for Qatar's taxi operators, directing margin pools toward fleet scale players with volume purchasing power and integrated maintenance capabilities. Fare regulation by Qatar's Ministry of Transport caps street-hail pricing while permitting dynamic surge algorithms for app-based platforms, creating divergent margin structures across service tiers.
Pricing Analysis
Service tier certification creates the primary spread between economy street-hail fares and premium luxury bookings. Metered base rates for Karwa-licensed sedans operate under Ministry-mandated ceilings, while ride-hailing platforms deploy algorithmic surge multipliers during stadium events and flight arrival clusters. Corporate managed travel contracts command fixed-rate premiums for guaranteed availability and carbon reporting integration. Local residents in Al Wakrah and Al Khor exhibit highest price sensitivity, whereas diplomatic and energy sector clients in West Bay demonstrate lowest elasticity.
Supply Chain Analysis
Fleet procurement concentrates through authorized distributors of Toyota, Honda, and Hyundai in Qatar, with vehicle assembly anchored in Japan, South Korea, and Thailand. Parts inventory for high-mileage Camry and Accord fleets draws from regional hubs in the UAE and Saudi Arabia. Single-source vulnerability runs through exclusive airport concession agreements that restrict terminal access for new market entrants. Distribution flows through Mowasalat's state-backed service centers and independent garage networks across Doha, Lusail, and Al Wakrah.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's taxi sector faces high-growth disruption from mandatory telematics integration and electric vehicle pilot mandates under Qatar National Vision 2030, creating technology-driven competitive separation between digital-first platforms and legacy cooperatives.
For Market Incumbents: Insulate core airport and corporate contract revenue by accelerating API-connected booking tool deployment before competitor platform consolidation. Vertical integration into captive maintenance facilities in Lusail and Al Rayyan reduces third-party service dependency. Exclusive terminal access rights at Hamad International Airport remain the critical defensive moat against global ride-hailing expansion. For New Entrants and Emerging Players: Lusail City's entertainment districts and unfinished residential towers represent the most penetrable entry point for establishing local fleet presence before infrastructure maturation. Electric vehicle pilot programs under Ministry sustainability mandates offer regulatory-aligned positioning with policy support. Arabic-language service customization and localized payment wallet integration provide differentiation angles against global platform standardization. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale operators with existing fleet scale but underdeveloped digital infrastructure, where technology retrofit creates acquisition value. Long-term viability hinges on compliance adaptability as emission standards and driver classification rules evolve. Monitor Qatar Central Bank mobile payment interoperability enforcement as the signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Mandatory GPS and digital meter compliance by Qatar's Ministry of Transport forces fleet-wide technology retrofits. |
| Electric Vehicle Fleet Pilot | Qatar National Vision 2030 sustainability targets create first-mover positioning in Lusail smart city deployment. |
| Corporate Managed Travel Contract | Multinational firms in Doha's West Bay district consolidate ground transport under API-connected booking requirements. |
| Airport Concession Extension | Exclusive terminal access rights at Hamad International anchor high-yield passenger segment capture. |
| Mobile Payment Interoperability | Qatar Central Bank framework mandates digital wallet integration, reducing cash handling friction for tourists. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet managers at Mowasalat and independent taxi cooperatives, regulatory affairs leads at Qatar's Ministry of Transport, corporate travel procurement officers at multinational energy and financial firms, and platform engineering directors at ride-hailing operators. Secondary validation drew from Qatar Central Bank payment system disclosures, Ministry of Transport telematics compliance filings, Hamad International Airport passenger traffic statistics, and corporate sustainability reporting frameworks. Bottom-up fleet deployment modeling triangulated against top-down addressable demand estimates across service tiers.
Calibration anchored volume and value outputs to documented fleet counts, vehicle replacement cycles, and fare structure regulations across the analysis window. Segmentation dimensions modeled included service type, vehicle configuration, payment method, and customer archetype, with geographic clustering across Doha, Lusail, Al Wakrah, Al Khor, and Al Rayyan. CAGRs were derived from trend extrapolation of corporate contract adoption, tourist arrival patterns, and electric vehicle policy implementation timelines. Forecast inputs incorporated kafala sponsorship system constraints on driver supply expansion and petroleum price volatility assumptions.
Macroeconomic conditions sit as an overlay; deviation in energy sector employment levels, FIFA legacy event scheduling, or global oil price spikes would shift the trajectory of fleet utilization and fare adjustment negotiations. Forecasts reflect documented assumptions regarding regulatory enforcement timing and infrastructure buildout pace. Quarterly review of Ministry telematics compliance deadlines, Central Bank payment interoperability milestones, and Lusail residential occupancy rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Public Transportation Dispatch Software Market