
 Public Transport Smart Card Market | 2026-2036
Public Transport Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
Public Transport Smart Card Market Analytics
Market Context
South Korea's transit infrastructure is fragmenting as multiple city-level procurement frameworks create parallel ecosystems for smart card deployment. Thales Group leverages its embedded security expertise to dominate rail system tenders across Seoul and Busan. NXP Semiconductors N.V. anchors the semiconductor layer with NFC controller chips purpose-built for transit form factors. Cubic Corporation competes through integrated account-based ticketing platforms that bridge agency legacy systems with mobile wallets.
Technical Definition and Segment Structure
Public transport smart cards are credential-bearing payment instruments that store fare value or identity tokens on embedded microcontrollers, typically operating at 13.56 MHz via ISO/IEC 14443 protocols for contactless transaction completion within 300 milliseconds. These devices enable automated fare collection while reducing cash handling costs for transit operators and shortening passenger boarding dwell times. Contactless card types now command the dominant volume position due to their compatibility with both closed-loop transit schemes and open-loop bank card acceptance, though dual-interface variants are gaining traction where agencies seek migration paths from legacy magnetic stripe systems. RFID technology underpins the majority of deployed infrastructure, while NFC-enabled mobile credentialing is capturing the fastest-growing use case segment as smartphone penetration reshapes commuter behavior.
Regulatory Environment
The EU AI Act and GDPR impose data governance requirements on transit operators processing commuter movement patterns through smart card back-office systems, while EMVCo specifications govern open-loop payment security standards that banks and transit agencies must jointly satisfy. India's BIS certification mandates and the country's PLI scheme for electronics manufacturing are reshaping domestic card production economics and import substitution trajectories. Stakeholders must monitor how interoperability standards evolve as metropolitan agencies weigh closed-loop control against open-loop convenience in procurement decisions.
Market Dynamics
The transition from card-based credentials to smartphone-embedded transit wallets is compressing hardware procurement cycles while expanding software and cloud infrastructure spending across municipal transit agencies.
Growth Catalysts
- EU Green Deal Interoperability Mandates:The European Commission's push for seamless cross-border transit payment integration is forcing member states to upgrade legacy closed-loop systems toward open-loop EMV acceptance, creating replacement demand for dual-interface card infrastructure.
- Contactless NFC Controllers:Semiconductor manufacturers are shipping purpose-built transit-grade NFC chips that operate reliably in high-density electromagnetic environments, enabling sub-300 millisecond transaction speeds that meet rail operator dwell-time requirements.
- India's PLI Scheme:The country's production-linked incentive framework for electronics manufacturing is attracting smart card assembly capacity away from traditional East Asian supply bases, lowering landed costs for domestic transit procurement.
Market Restraints
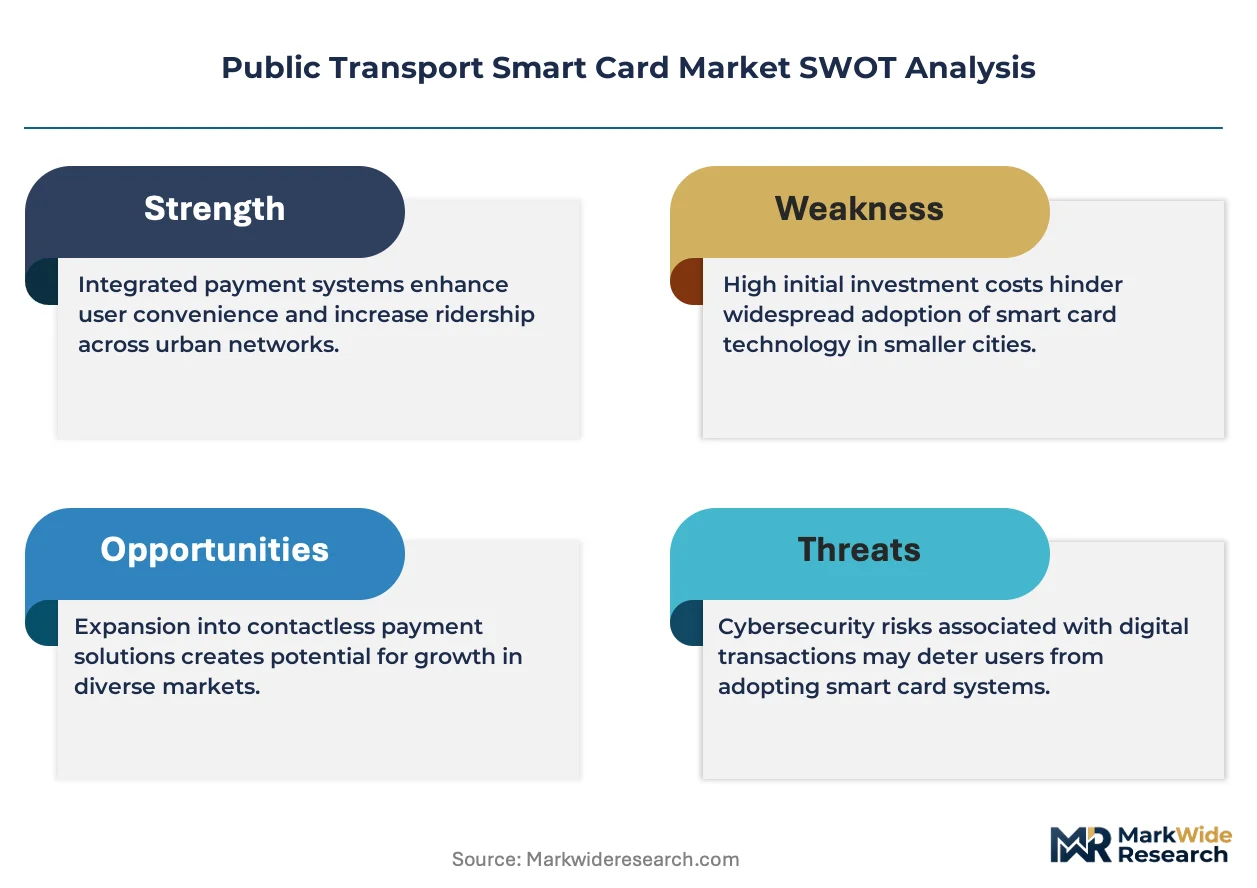
- Semiconductor Supply Concentration:NFC controller fabrication concentrates among a handful of foundry operators in Taiwan and South Korea, exposing transit card issuers to allocation risk during capacity crunches.
- GDPR Compliance Burden:The EU's data protection framework imposes strict governance requirements on back-office systems processing commuter movement patterns, extending deployment timelines and raising system integration costs for European operators.
- Mobile Wallet Substitution:Apple Pay and Google Pay credentialing is displacing physical card issuance in premium commuter segments, compressing hardware volume in mature urban markets.
Strategic Opportunities
- Brazilian Municipal Modernization:Legacy magnetic stripe systems in São Paulo and Rio de Janeiro transit networks present white-space demand for contactless migration, with federal infrastructure financing unlocking procurement budgets.
- Account-Based Ticketing Convergence:The integration of transit fare engines with banking core systems enables real-time fare capping and concession management, opening recurring software revenue streams for system integrators.
- India's BIS Certification Pathway:Domestic certification mandates for electronic payment devices are creating captive demand for locally manufactured card bodies and embedded modules, favoring regional production investments.
Industry Challenges
- Legacy System Integration Complexity:Decades-old fare collection infrastructure in established metro systems requires expensive middleware development to bridge proprietary protocols with modern open-loop standards.
- EMV Certification Timelines:Bank-card interoperability testing cycles routinely extend 18-24 months, delaying revenue recognition for transit agencies and straining vendor working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Transport Smart Card Market |
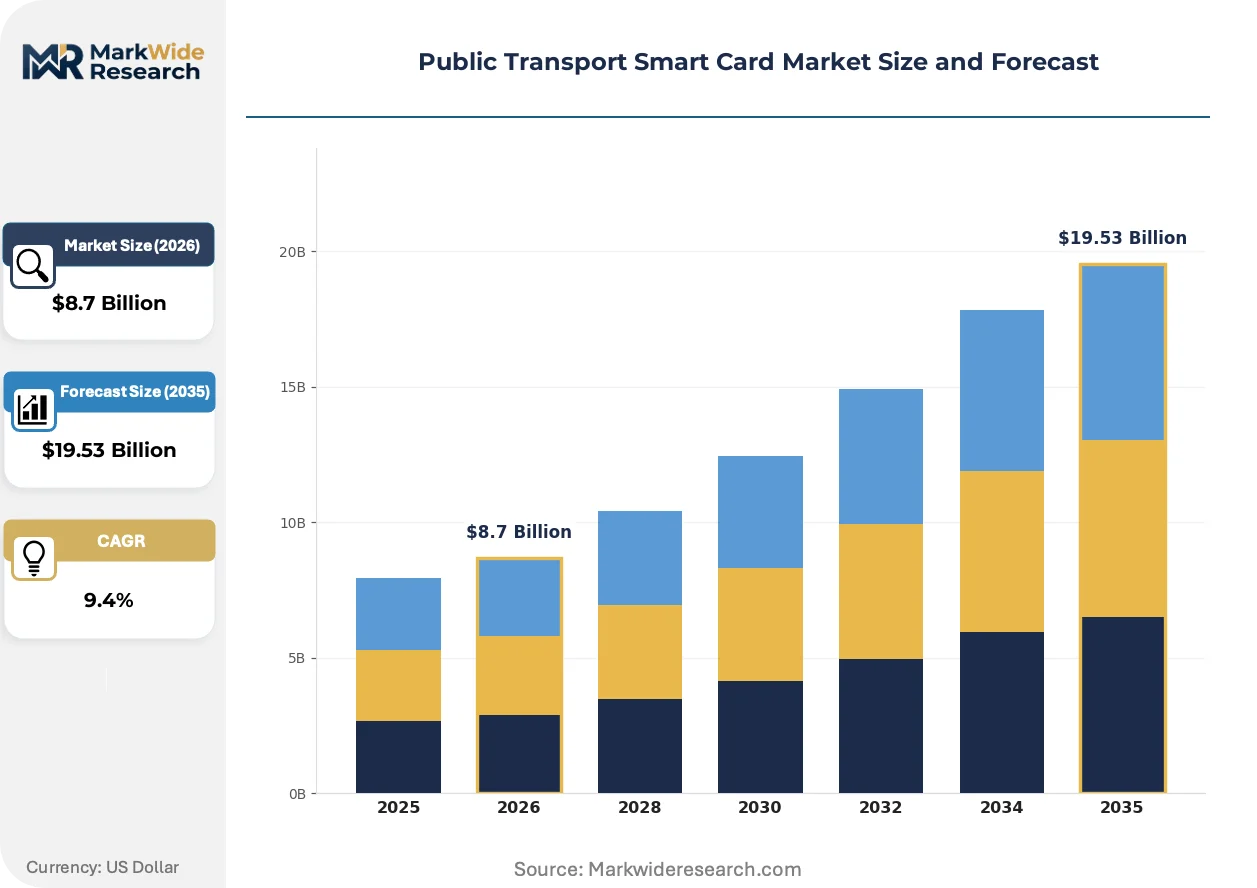
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Contactless, Magnetic Stripe, Smart Chip, Dual-Interface Use Case: Travel, Access Control, Payment System, Loyalty Program End User: Commuters, Tourists, Transportation Authorities, Corporates Technology: RFID, NFC, EMV, QR Code |
| Companies Covered | Thales Group, CPI Card Group Inc., NXP Semiconductors N.V., Oberthur Technologies S.A., Atos SE, Giesecke & Devrient GmbH, IDEMIA SAS, Cubic Corporation, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Transport Smart Card Market Evolving Landscape
Credential virtualization is collapsing the distinction between physical and digital transit payment instruments, forcing hardware-centric vendors to reconstitute around software and platform service models.
Tokenized mobile transit credentials are virtualizing the secure element function that smart cards previously monopolized. Transit agencies in London and Singapore are deploying these solutions at scale, enabling commuters to tap smartphones without pre-registered accounts. This architecture is compressing card issuance volumes while expanding cloud-based fare engine workloads.
REACH chemical restrictions are reshaping card body material specifications across European procurement. The regulation's Substances of Very High Concern list now captures certain flame retardants and plasticizers common in PVC card stock, forcing converters toward bio-sourced polycarbonate alternatives. German and Dutch transit authorities are leading specification revisions.
Commuter preference is pivoting toward fare transparency and trip-by-trip billing rather than stored-value prepayment. Urban millennials in Seoul and Stockholm are rejecting card top-up friction in favor of linked-payment models that settle post-ride. This behavioral shift is accelerating account-based ticketing tenders and displacing traditional card sales channels at station kiosks.
Public Transport Smart Card Market Segmentation
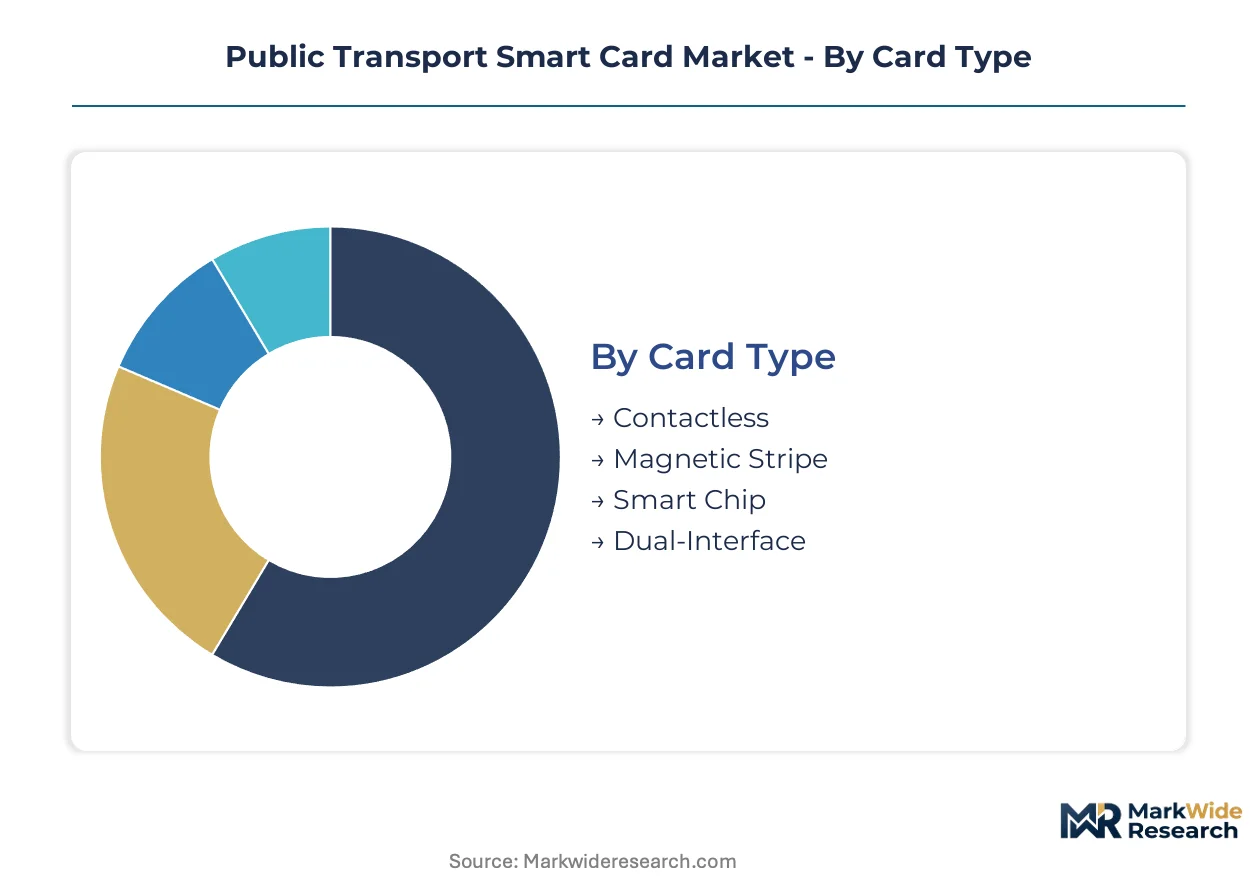
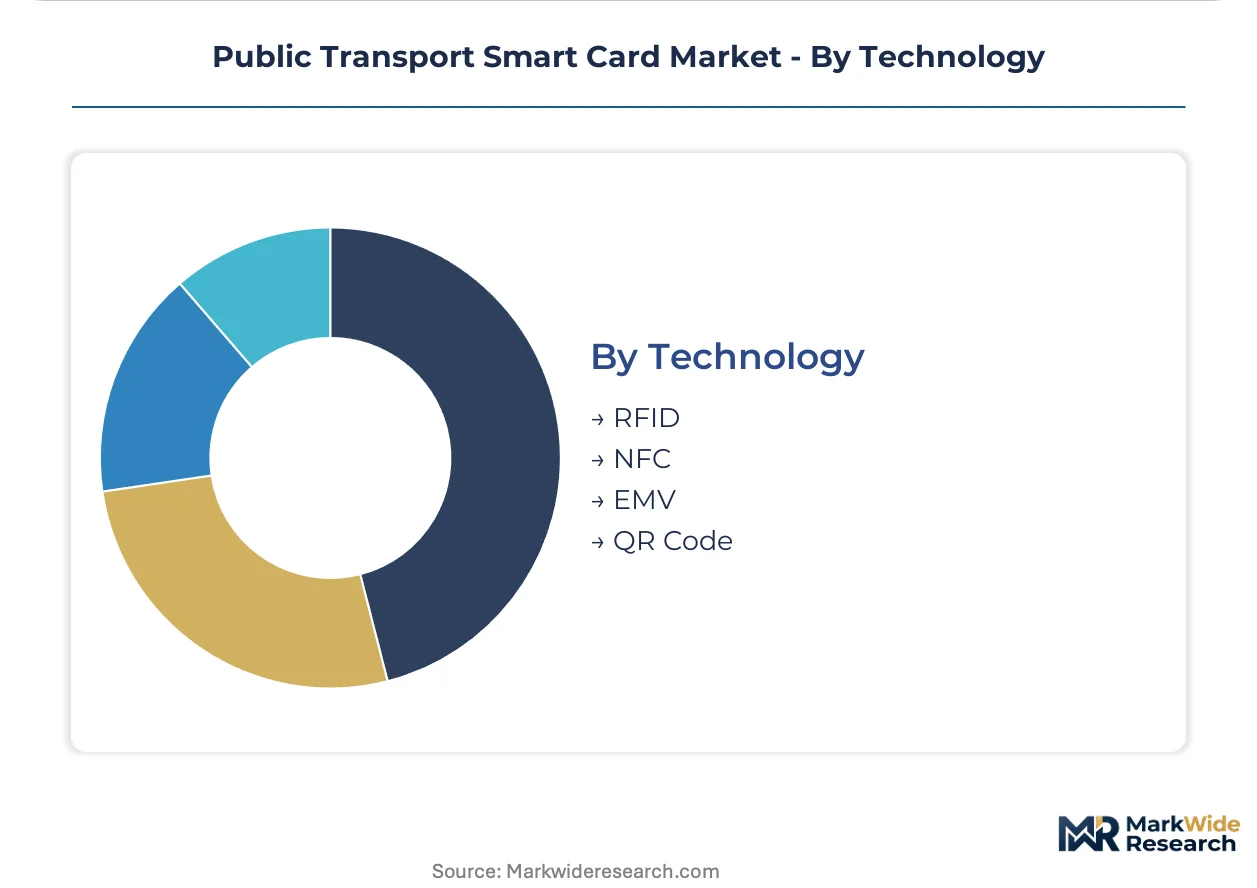
Transit agencies select credential formats based on electromagnetic environment constraints, legacy infrastructure age, and migration timelines toward open-loop bank card acceptance. The segmentation structure reveals how hardware procurement concentrates in contactless form factors while software revenue pools around account-based ticketing integration.
Card Type:
Mature closed-loop systems and emerging open-loop architectures drive divergent form factor demand across agency procurement cycles.
- Contactless:ISO/IEC 14443-compliant cards operating at 13.56 MHz enable sub-300 millisecond transaction completion in high-density rail environments. Seoul and Singapore transit authorities specify these for new procurements as they phase out legacy magnetic infrastructure.
- Magnetic Stripe:Legacy credential format still deployed in São Paulo and Rio de Janeiro metro networks where electromagnetic interference concerns previously delayed contactless migration. Brazilian federal infrastructure financing now unlocks replacement budgets.
- Smart Chip:Embedded microcontroller cards with secure element storage for prepaid fare value. Indian BIS certification mandates favor domestically assembled chip modules.
- Dual-Interface:Hybrid cards supporting both contactless transit gates and contact POS terminals. European agencies under EU Green Deal interoperability mandates specify these for seamless cross-border acceptance.
Contactless handles the majority of throughput; dual-interface is expanding most quickly on share.
Use Case:
Application scope determines whether procurement emphasizes hardware durability or software integration depth.
- Travel:Core transit fare collection across bus, rail, and multimodal networks. London's TfL and Singapore's LTA deploy tokenized mobile variants alongside physical cards.
- Access Control:Building and facility entry integration with corporate campus transit programs. Seoul metropolitan employers bundle these with commuter subsidies.
- Payment System:Open-loop bank card acceptance at transit gates. EMVCo certification requirements govern security specifications for these deployments.
- Loyalty Program:Fare discount and points accumulation schemes. Stockholm transit agencies link these to post-ride settlement models favored by millennial commuters.
Travel commands absolute volume; payment system integration is gaining share fastest.
End User:
Customer type shapes pricing tiers and credential distribution channel strategy.
- Commuters:Daily riders generating recurring fare revenue. These users drive demand for auto-reload and linked-payment convenience.
- Tourists:Short-term visitors purchasing limited-duration passes. Visitor cards in London and Singapore include retail and attraction discounts.
- Transportation Authorities:Municipal agencies procuring credential systems. Their specifications determine EMV certification and GDPR compliance requirements.
- Corporates:Employers subsidizing employee transit through bulk credential issuance. These contracts emphasize centralized account management and usage reporting.
Commuters generate the recurring revenue base; corporate programs show the steepest expansion trajectory.
Technology:
Protocol selection determines hardware supplier concentration and system integration complexity.
- RFID:Passive tag technology underpinning legacy closed-loop infrastructure. Taiwan and South Korean foundry concentration creates allocation risk during semiconductor crunches.
- NFC:Near-field communication enabling smartphone credential virtualization. Purpose-built transit-grade controllers from NXP Semiconductors dominate rail operator specifications.
- EMV:Europay-Mastercard-Visa standard governing open-loop bank card acceptance. Certification timelines routinely extend 18-24 months.
- QR Code:Optical scanning alternative deployed in cost-sensitive markets. Indian transit agencies pilot these for bus fleet modernization.
RFID retains installed base dominance; NFC is climbing the fastest on deployment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication for NFC controllers concentrates in Taiwan and South Korea, exposing transit card issuers to foundry allocation risk during capacity crunches. Municipal procurement frameworks diverge sharply across geographies as agencies weigh closed-loop control against open-loop convenience.
United States
Contactless fare collection upgrades in New York, Chicago, and San Francisco transit agencies drive dual-interface card demand. EMVCo certification timelines govern open-loop bank card acceptance standards. Cubic Corporation anchors system integration contracts across major metropolitan rail networks.
Germany
REACH chemical restrictions force converters toward bio-sourced polycarbonate alternatives for card body specifications. The EU Green Deal interoperability mandates accelerate cross-border transit payment integration. Berlin and Munich transit authorities lead specification revisions for seamless EMV acceptance.
India
BIS certification mandates and PLI scheme incentives reshape domestic smart card assembly economics. Municipal transit agencies in Delhi, Mumbai, and Bangalore modernize legacy ticketing infrastructure. Regional production investments capture captive demand for locally manufactured embedded modules.
South Korea
City-level procurement frameworks fragment transit infrastructure into parallel smart card ecosystems. Seoul and Busan metropolitan rail operators specify purpose-built transit-grade NFC controllers. Thales Group dominates embedded security tenders across these urban networks.
Brazil
Federal infrastructure financing unlocks replacement budgets for magnetic stripe systems in São Paulo and Rio de Janeiro. ANVISA-equivalent transit safety standards govern new contactless deployments. Municipal modernization programs present white-space demand for migration-ready credential platforms.
Public Transport Smart Card Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in semiconductor and secure element supply. The vendor base organizes around three strategic archetypes: embedded security conglomerates, semiconductor fabricators with transit-optimized NFC portfolios, and account-based ticketing software houses. Consolidation pressure concentrates in the middleware layer as agencies demand unified fare engines. Dominant competitive moves include geographic expansion into municipal procurement frameworks and technology licensing for EMV certification acceleration.
Within the embedded security tier, Thales Group and Giesecke & Devrient GmbH exemplify European conglomerates with transit-anchored credential portfolios. NXP Semiconductors N.V. represents the semiconductor archetype, with its corporate structure indicating Dutch origins and foundry-linked supply positioning. These three entities anchor the competitive landscape across hardware procurement cycles and certification-heavy system tenders.
| Leading Market Players |
|---|
| Thales Group |
| CPI Card Group Inc. |
| NXP Semiconductors N.V. |
| Oberthur Technologies S.A. |
| Atos SE |
| Giesecke & Devrient GmbH |
| IDEMIA SAS |
| Cubic Corporation |
| Infineon Technologies |
| Others |
Value Network & Pricing Analysis
Taiwanese foundry undercapacity in NFC controller fabrication is forcing transit card issuers toward longer-term offtake commitments, compressing spot-market flexibility while elevating contract premiums for priority allocation. This utilization squeeze cascades through card body converters and secure element assemblers, reshaping procurement economics across municipal transit agencies.
Pricing Analysis
India's BIS certification dictates the pricing tier structure across domestic and import-competing supply streams. Three-tier pricing structure across premium, standard, and economy levels separates EMV-certified dual-interface cards from closed-loop contactless variants and legacy magnetic stripe credentials. Cost compression in the economy tier is intensifying because Brazilian federal infrastructure financing unlocks volume procurement for magnetic replacement programs. Municipal transit agencies in São Paulo and Rio de Janeiro exhibit the highest price sensitivity, while European rail operators under EU Green Deal mandates absorb premium positioning for interoperability compliance.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant capacity for transit-grade NFC controller production, with United Microelectronics Corporation anchoring trailing-edge secure element fabrication. Semiconductor fabrication concentrates in Taiwan and South Korea, while card body conversion localizes in Germany, India, and Brazil to satisfy regional content mandates. Raw material dependencies encompass polycarbonate resin for REACH-compliant card stock, copper-clad laminate for antenna inlays, and gold wire for chip bonding. Single-source vulnerability in Taiwanese foundry output exposes issuers to allocation risk during capacity crunches. Distribution runs through authorized system integrators holding EMV certification credentials, with Thales Group and Cubic Corporation controlling tier-one agency relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The public transport smart card market is entering a cyclical recovery phase as municipal infrastructure modernization budgets rebound from pandemic-era austerity, with India's PLI scheme and Brazil's federal financing programs providing the demand floor.
For Market Incumbents: Harden embedded security differentiation through proprietary EMV certification acceleration tools, reducing the 18-24 month testing burden that strains vendor working capital. Deepen backward integration into secure element design to offset foundry allocation risk from Taiwanese concentration. Lock long-term offtake agreements with TSMC and Samsung Foundry before capacity crunches intensify spot-market premiums. For New Entrants and Emerging Players: Pursue account-based ticketing software contracts in midsize European cities where legacy system integration complexity has delayed incumbent penetration. Brazilian municipal modernization presents the most penetrable geography, with São Paulo and Rio de Janeiro magnetic stripe replacement creating white-space demand. Lead with cloud-native fare engines that bypass hardware-dependent procurement cycles, offering subscription-based revenue models that align with agency budget constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among account-based ticketing platform providers with multi-year municipal SaaS contracts, offering superior cash flow predictability against hardware-centric competitors. The 5-10 year viability window favors vendors with demonstrated EMV certification track records and established relationships with transportation authorities in India and Brazil. Monitor EMVCo specification revision announcements as the primary inflection signal, as new security mandates typically trigger replacement procurement cycles across installed base infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| EMV Certification Acceleration | Reduces 18-24 month testing timelines that delay revenue recognition for transit agencies. |
| Backward Integration into Secure Elements | Mitigates Taiwanese foundry allocation risk through captive chip design capabilities. |
| Cloud-Native Fare Engine Deployment | Enables real-time fare capping and concession management for millennial commuter preferences. |
| Brazilian Municipal Modernization Partnership | Captures federal infrastructure financing unlocking magnetic stripe replacement budgets. |
| REACH-Compliant Material Transition | Secures European procurement eligibility as ECHA restrictions eliminate PVC card stock alternatives. |
Research Methodology
A standing panel of transit agency procurement directors, EMV certification engineers, semiconductor supply chain managers, and municipal infrastructure financing officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders were cross-validated against secondary sources including EMVCo specification releases, BIS certification registries, European Commission Green Deal implementation reports, and Indian PLI scheme beneficiary disclosures. Bottom-up volume estimates from agency procurement announcements were triangulated with top-down market sizing derived from NFC controller shipment data and card body converter capacity utilization.
Scenario-bracketing anchored the analytical framework, with baseline, upside, and downside trajectories developed across the projection horizon. Segmentation dimensions modeled encompassed card type, use case, end user category, and technology protocol, with additional granularity applied to regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves calibrated to historical replacement cycle patterns and announced modernization program timelines. Forecast inputs included municipal budget appropriation trajectories, foundry capacity expansion announcements, and EMV certification pipeline visibility.
Macroeconomic conditions sit as an overlay; deviation in municipal debt financing costs, semiconductor capital expenditure cycles, or currency volatility in Brazil and India would shift the trajectory. Forecasts reflect underlying assumptions regarding regulatory timeline adherence and technology substitution rates. Quarterly review of EMV certification pipeline data, foundry utilization reports, and transportation authority procurement announcement flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Electric Public Transport System Market