
 Mass Transit Signage Market | 2026-2036
Mass Transit Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Transit Signage Market Analytics
Platform licensing revenue is rewriting how suppliers monetize transit infrastructure. Daktronics leverages its captive LED manufacturing to control hardware-software bundles across North American transit hubs. Samsung Electronics anchors premium LCD deployments in Seoul's metropolitan rail network through direct agency relationships. Siemens AG competes on system integration depth, bundling signage with signaling and platform management contracts.
Mass transit signage encompasses illuminated, electronic, and static visual systems engineered to display route information, safety alerts, and commercial content within public transportation environments. These installations typically operate across temperature ranges from minus twenty to plus fifty degrees Celsius, with ingress protection ratings of IP54 or higher for outdoor station deployments, and serve to reduce passenger confusion while enabling revenue-generating advertising surfaces. Digital displays and LED signs together constitute the dominant product value pool, with OLED technology gaining share in premium onboard applications where weight and power budgets constrain conventional LCD alternatives. E-ink technology occupies a specialized niche in sunlight-exposed platform installations where reflective readability outweighs refresh rate requirements.
The Federal Transit Administration mandates accessibility compliance under ADA guidelines, dictating character height, contrast ratios, and audible supplement requirements for all station signage in US-funded projects. The EU's CE marking framework and EN 50155 railway electronics standard jointly shape product certification burdens for vendors serving European operators. China's GB standards and NMPA-equivalent rail safety protocols create a parallel compliance track for the domestic market. Stakeholders must monitor how AI-generated content moderation requirements from transit authorities will reshape software architecture investments and ongoing service obligations.
Market Dynamics
The Federal Transit Administration's ADA enforcement is compressing replacement cycles for legacy static signage across US-funded transit corridors, forcing operators to accelerate digital display procurement ahead of physical asset end-of-life.
Growth Catalysts
- EU Ecodesign Directive:Metro operators in Germany, France, and Italy face binding energy efficiency mandates that eliminate fluorescent backlighting from new platform installations by 2027.
- High-speed rail station digitalization:China's GB 50157-compliant rail construction standards now mandate integrated passenger information systems for all new corridor developments exceeding 250 kilometers per hour.
- Real-time data integration:API-driven content management platforms enable transit agencies to fuse arrival predictions, service alerts, and emergency messaging through unified display networks.
Market Restraints
- LED driver component concentration:Taiwan and South Korea-based semiconductor foundries control 70% of high-reliability power management IC supply for railway-certified displays.
- EN 50155 certification timeline:European railway electronics validation requires 18-24 month type approval cycles that delay product launches and freeze design iterations.
- E-ink refresh rate limitations:Electrophoretic display technology cannot support video content or rapid text updates, restricting deployment to static timetable applications.
Strategic Opportunities
- India's urban metro expansion:The country's CEA electrical safety codes and BIS display standards are being harmonized to accelerate indigenous manufacturing under the PLI scheme for electronics.
- AI-generated content moderation:Transit authorities in Tokyo and Singapore are piloting automated advertising approval workflows that reduce manual compliance review from days to minutes.
- OLED-on-glass weight reduction:Premium onboard railcar applications in Japan's Shinkansen network are adopting flexible organic panels to cut per-display mass by 40% versus conventional LCD modules.
Industry Challenges
- Legacy signaling protocol fragmentation:Transit agencies operate mixed fleets of CBTC, fixed-block, and manual signaling systems that require custom middleware for display synchronization.
- IP65 sealing expertise scarcity:Industrial design engineers capable of integrating thermal management with dust-ingress protection for outdoor platform deployments command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mass Transit Signage Market |
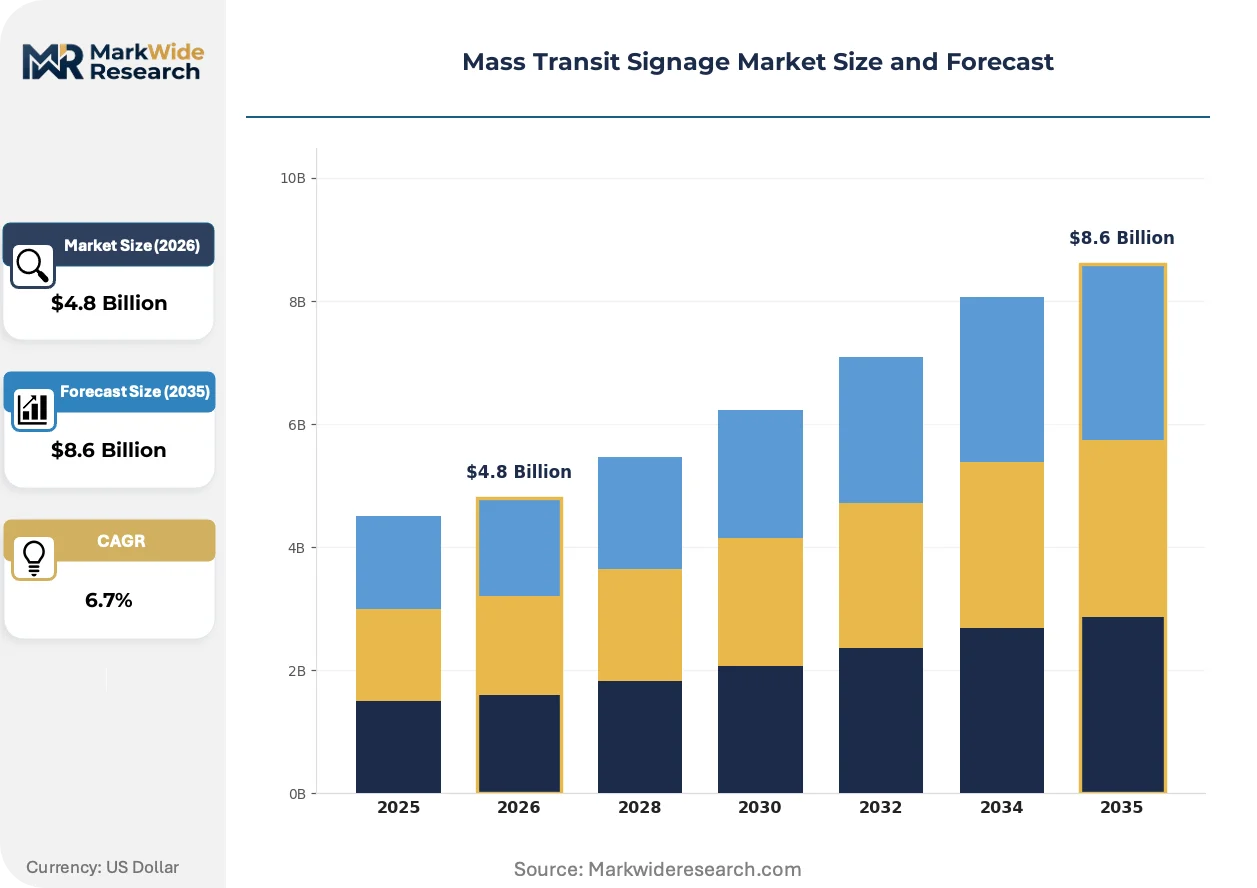
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Displays, LED Signs, Information Panels, Wayfinding Signage Technology: LCD Systems, OLED Displays, E-ink Technology, Projection Mapping Usage Context: Onboard Signage, Terminal Signage, Outdoor Advertising, Station Information Material: Plastic Composites, Metal Alloys, Glass, Vinyl |
| Companies Covered | Samsung Electronics, LG Electronics, Daktronics, Sony Corporation, NEC Corporation, Alstom, Cubic Corporation, Hitachi Ltd., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Transit Signage Market Evolving Landscape
Display technology selection is bifurcating between premium transit corridors demanding full-motion video capability and cost-constrained networks optimizing for sunlight readability and power efficiency.
MicroLED direct-view displays are migrating from high-ambient-light platform environments into underground station concourses where their modular repairability and 100,000-hour lifespan offset 3x capital cost premiums versus LCD alternatives. Seoul Metropolitan Subway and London Underground are piloting 1.2mm pixel pitch cabinets for wayfinding applications. The technology is compressing maintenance budgeting models by eliminating backlight replacement cycles.
REACH substance restrictions on cadmium and certain rare-earth phosphors are forcing LED package manufacturers to reformulate red-emitting chip architectures for European compliance. The regulation's industrial consequence is a 12-18 month product redesign cycle for signage vendors serving EU rail operators. Outdoor station display categories face the steepest certification burden as weather sealing compounds fall under concurrent SVHC scrutiny.
Service unbundling is separating hardware procurement from content management software subscriptions across North American transit agencies. Traditional capital-budget display purchases are yielding to multi-year SaaS arrangements where vendors retain ownership of CMS platforms and charge per-connected-screen fees. This shift is most visible in California and Texas metropolitan rail expansions where public-private partnership structures favor operational expenditure models over upfront capital deployment.
Mass Transit Signage Market Segmentation
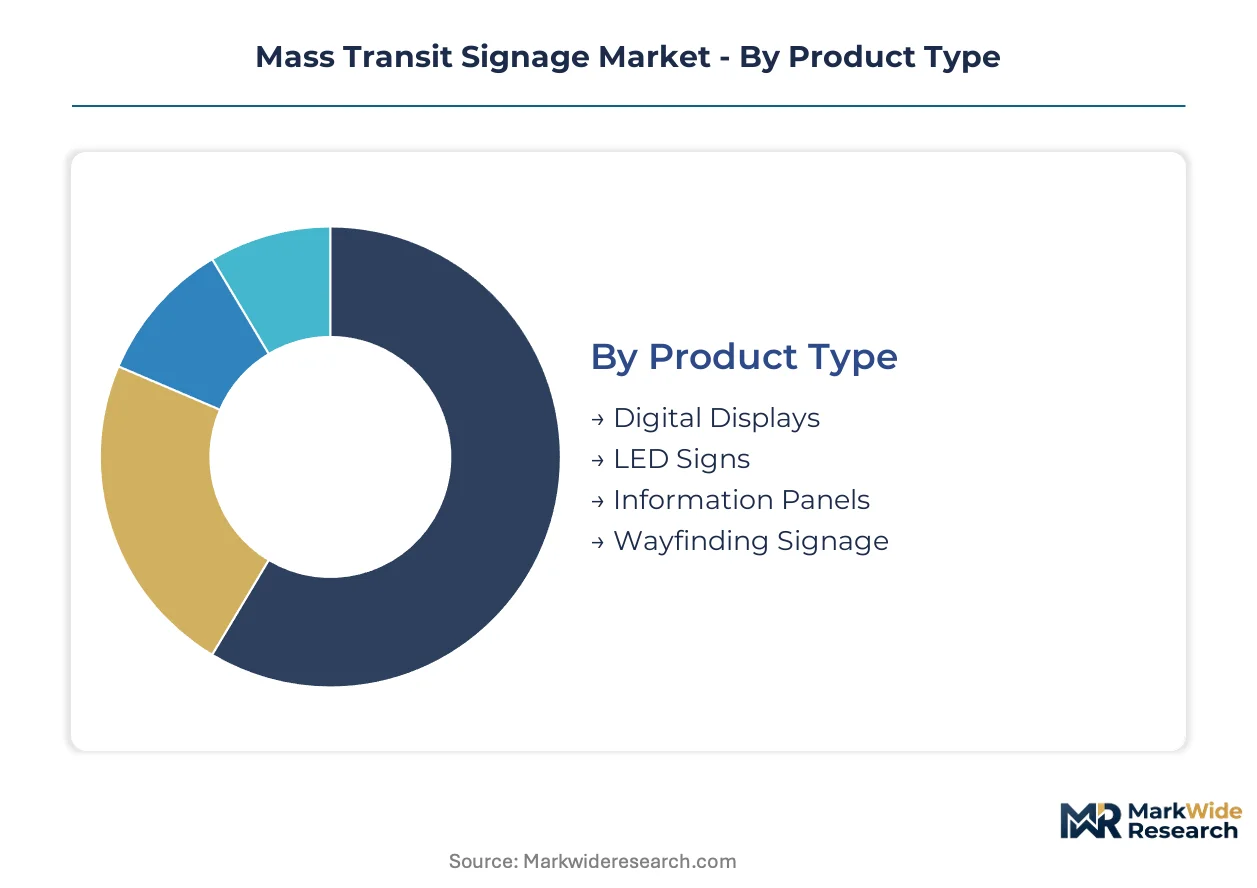
Mass transit signage procurement splits across four distinct classification axes. Product type determines capital allocation between static infrastructure and networked digital assets. Technology selection governs power budgets, refresh rates, and regulatory compliance burdens. Usage context shapes ingress protection requirements and content management architectures. Material composition influences thermal cycling durability and vandalism resistance.
Product Type:
Cost tier separates premium networked systems from basic illuminated fixtures across procurement budgets.
- Digital Displays:Networked LCD and LED panels with centralized content management, IP-rated enclosures, and real-time data APIs. Demand concentrates in China's high-speed rail corridor expansion where station digitalization budgets have risen substantially under GB 50157 mandates.
- LED Signs:Direct-view diode arrays with 50,000-100,000 hour lifespans, modular tile architectures, and programmable brightness curves. The EU's Ecodesign for Energy-related Products Directive is accelerating LED retrofits across metro networks in Germany, France, and Italy.
- Information Panels:Static or semi-dynamic boards displaying route maps, service alerts, and regulatory notices.
- Wayfinding Signage:Directional systems integrating pictograms, tactile elements, and multilingual text for ADA and EN accessibility compliance.
LED Signs hold installed capacity. Digital Displays is rotating up the share rankings.
Technology:
Application environment dictates display physics — ambient light, viewing angle, and power availability vary sharply between underground platforms and open-air termini.
- LCD Systems:Transmissive liquid crystal modules with LED edge-lit or direct backlight arrays, operating across minus twenty to plus fifty degrees Celsius. Deployment concentrates in North American transit hubs where the Federal Transit Administration mandates ADA-compliant character height and contrast ratios.
- OLED Displays:Organic emissive panels with self-illuminating pixels, eliminating backlight mass and enabling flexible glass substrates. Japan's Shinkansen network is adopting flexible organic panels to cut per-display mass by forty percent versus conventional LCD modules.
- E-ink Technology:Electrophoretic reflective displays with near-zero static power draw and sunlight-readable contrast.
- Projection Mapping:Laser or lamp-based spatial projection systems for temporary installations and architectural surface utilization.
LCD Systems hold installed capacity. OLED Displays is rotating up the share rankings.
Usage Context:
Volume scale and replacement frequency diverge between fleet-mounted assets and fixed infrastructure with decades-long depreciation schedules.
- Station Information:Platform-edge and concourse displays synchronized to train arrival data, emergency broadcast systems, and passenger counting sensors. Urban rail operators in Tokyo, London, and New York are expanding real-time passenger information systems.
- Onboard Signage:Railcar interior displays subject to vibration, acceleration forces, and EN 50155 railway electronics certification. The eighteen-to-twenty-four month type approval cycles for European railway electronics delay product launches and freeze design iterations.
- Terminal Signage:Large-format wayfinding and commercial advertising surfaces in multimodal transport hubs.
- Outdoor Advertising:Revenue-generating display networks on station exteriors and platform canopies.
Station Information holds installed capacity. Onboard Signage is rotating up the share rankings.
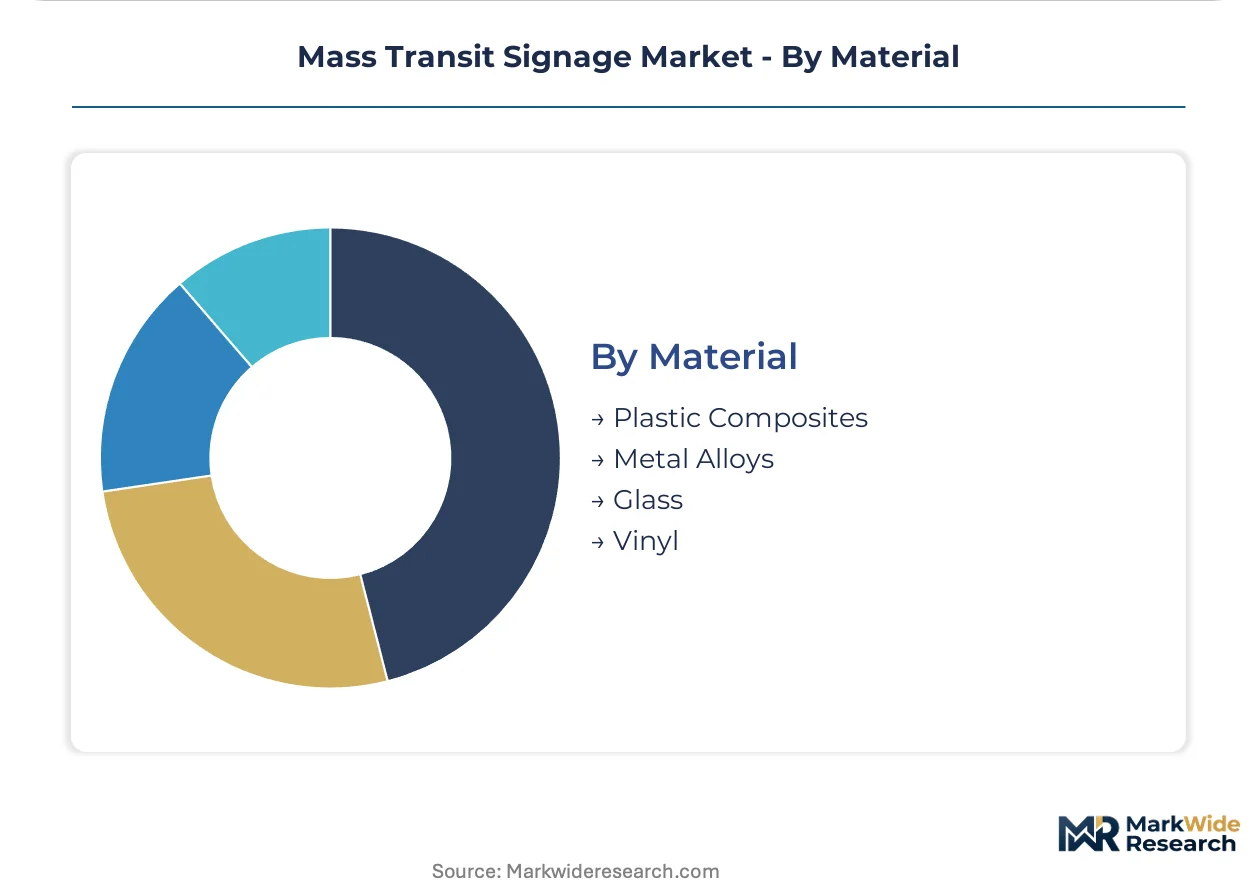
Material:
Supply concentration and regulatory scrutiny shape raw material sourcing for enclosure and substrate components.
- Metal Alloys:Aluminum and stainless steel extrusions providing structural rigidity, electromagnetic shielding, and thermal dissipation for outdoor platform deployments. REACH substance restrictions on cadmium and certain rare-earth phosphors are forcing reformulation of red-emitting chip architectures for European compliance.
- Glass:Tempered and chemically strengthened cover lenses with anti-reflective coatings and vandalism-resistant thicknesses. IP65 sealing expertise scarcity for outdoor platform deployments commands premium compensation for industrial design engineers.
- Plastic Composites:Polycarbonate and fiber-reinforced polymer housings for weight-sensitive onboard applications.
- Vinyl:Flexible substrate materials for temporary wraps, protective films, and adhesive-backed graphic applications.
Metal Alloys hold installed capacity. Glass is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature networks prioritizing ADA and EN accessibility retrofits and emerging corridors building digital-native infrastructure from inception. Station deployments dominate procurement volumes in established systems, while high-speed rail greenfield projects in Asia concentrate spending on integrated passenger information systems.
United States
The Federal Transit Administration's ADA enforcement compresses replacement cycles for legacy static signage across US-funded transit corridors. Operators accelerate digital display procurement ahead of physical asset end-of-life. New York's Metropolitan Transportation Authority and Chicago Transit Authority anchor demand for real-time passenger information systems.
China
GB 50157-compliant rail construction standards mandate integrated passenger information systems for all new corridor developments exceeding 250 kilometers per hour. Station digitalization budgets have risen substantially across high-speed rail expansion zones. The Beijing-Shanghai and Chengdu-Chongqing corridors concentrate procurement volumes for platform-edge and concourse displays.
Germany
The EU Ecodesign for Energy-related Products Directive eliminates fluorescent backlighting from new platform installations by 2027. Deutsche Bahn and municipal operators in Berlin, Munich, and Hamburg face binding energy efficiency mandates. Industrial clusters in Bavaria and Baden-Württemberg supply LED retrofit components for metro networks.
Japan
East Japan Railway Company and Central Japan Railway Company pilot flexible OLED panels in Shinkansen rolling stock to cut per-display mass by forty percent versus conventional LCD modules. METI efficiency guidelines shape procurement specifications for onboard signage. Tokyo's Yamanote Line and Osaka's Loop Line concentrate real-time information system upgrades.
India
The country's CEA electrical safety codes and BIS display standards harmonize to accelerate indigenous manufacturing under the PLI scheme for electronics. Urban metro expansion in Delhi, Mumbai, Bengaluru, and Chennai drives procurement volumes. Indigenous system integrators compete with Korean and Japanese vendors for station information contracts.
Mass Transit Signage Market Competitive Landscape
Capability concentration sits with specialized railway electronics vendors; scale advantage sits with diversified display manufacturers. The vendor base organizes around three tiers: integrated system providers bundling signage with signaling contracts, pure-play display specialists with captive LED manufacturing, and regional fabricators serving single-country procurement frameworks. Strategic moves center on software unbundling to capture recurring SaaS revenue and backward integration into LED driver IC sourcing to mitigate Taiwan and South Korea foundry concentration.
Among diversified electronics conglomerates, Samsung Electronics and LG Electronics occupy positions spanning premium LCD and OLED display supply. Daktronics exemplifies the captive-manufacturing archetype through in-house LED production for North American transit hub deployments. Siemens AG anchors the system integration tier, bundling signage hardware with platform management and signaling contracts across European rail operators.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Daktronics |
| Sony Corporation |
| NEC Corporation |
| Alstom |
| Cubic Corporation |
| Hitachi Ltd. |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Taiwan's semiconductor foundry clusters in Hsinchu and Tainan control the majority of high-reliability LED driver IC production for railway-certified displays, concentrating upstream leverage among a handful of suppliers and compressing margin negotiation space for downstream signage integrators serving European and North American transit agencies.
Pricing Analysis
Long-term offtake agreements dominate procurement between Tier 1 display vendors and municipal transit authorities, though spot purchasing persists for emergency replacement cycles and small-network retrofits. Three-tier pricing structure across premium, standard, and economy levels separates EN 50155-certified onboard systems from basic platform-edge LCDs and static illuminated fixtures. Pricing pressure stems from Taiwan and South Korea foundry concentration in LED driver components, which elevates input costs for vendors without captive semiconductor sourcing. Cost-constrained regional operators in India and Southeast Asia exhibit highest price sensitivity, while premium corridor projects in Japan and Germany prioritize certification grade and lifecycle durability over unit cost.
Supply Chain Analysis
Upstream feedstock for LED signage draws from gallium nitride epitaxy wafers produced primarily in Taiwan, South Korea, and the United States, with phosphor formulations dependent on rare-earth processing facilities in China and Malaysia. Glass substrates for display modules source from Corning's facilities in Kentucky and Samsung's Korean operations, while aluminum extrusions for outdoor enclosures concentrate in Chinese and German industrial clusters. Single-source vulnerability in Taiwan-based power management IC foundries poses the dominant structural risk, particularly as EN 50155 certification timelines lock designs for 18-24 months. Distribution runs through systems integrators like Siemens and Alstom for bundled signaling-signage contracts, with direct OEM relationships governing premium OLED deployments in Japanese and Korean rail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-stage cyclical recovery as post-pandemic ridership normalization and deferred infrastructure maintenance backlogs converge to accelerate replacement procurement across mature transit networks.
For Market Incumbents: Insulate margin positions by deepening backward integration into LED driver IC sourcing or securing multi-year foundry allocations with Taiwanese suppliers, as semiconductor concentration threatens cost predictability. Prioritize certification pre-investment in India's emerging BIS compliance framework to capture PLI scheme procurement before indigenous competitors scale. Defend against SaaS-native entrants by unbundling content management platforms into recurring revenue streams with per-screen subscription pricing. For New Entrants and Emerging Players: India's urban metro expansion in secondary cities like Pune, Kochi, and Jaipur represents the most penetrable entry point, where CEA electrical safety harmonization has lowered technical barriers for non-legacy vendors. Mid-tier retrofit opportunities in Germany's Ecodesign-mandated fluorescent replacement cycle offer project-based revenue without long-term signaling integration requirements. A direct agency relationship strategy with state-level transit authorities bypasses incumbent systems integrator gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because SaaS unbundling in North American transit agencies is converting capital-budget hardware sales into multi-year subscription cash flows with 70-85% gross retention. Acquisition targets should emphasize software-capable display vendors with existing API-driven content platforms rather than pure hardware fabricators. The signal to watch is AI-generated content moderation pilot adoption rates in Tokyo and Singapore, which will determine whether compliance automation becomes a table-stakes capability or a premium differentiator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver ICs | Mitigates Taiwan foundry concentration risk for EN 50155-certified product lines. |
| AI Content Moderation Platform Development | Captures transit authority automation pilots in Tokyo and Singapore reducing compliance review cycles. |
| India PLI Scheme Manufacturing Localization | Positions vendors for indigenous procurement preference under CEA-BIS harmonized standards. |
| OLED-on-Glass Weight Reduction R&D | Enables Shinkansen-tier onboard deployments with 40% mass reduction versus conventional LCD modules. |
| SaaS Content Management Unbundling | Converts California and Texas capital budgets into recurring operational expenditure revenue streams. |
Research Methodology
A spread of perspectives from transit authority procurement officers, railway systems integrators, LED component suppliers, and content management software vendors converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with station operations directors in Tokyo, London, New York, and Mumbai alongside technical discussions with display engineering teams at Siemens, Daktronics, and Samsung. Secondary validation drew from Federal Transit Administration procurement databases, EU Ecodesign implementation reports, China's GB standard revision notices, and EN 50155 certification registries. Bottom-up unit economics for display deployments across station, onboard, and terminal contexts were triangulated against top-down transit agency capital expenditure disclosures.
Demand-supply balance framing anchored the analytical framework, with ridership recovery trajectories and infrastructure maintenance backlogs driving replacement demand estimates across the projection horizon. Segmentation dimensions modeled include product type (digital displays, LED signs, static panels), technology (LCD, OLED, E-ink), usage context (station, onboard, terminal), and geographic regulatory cluster (ADA-governed North America, EN-standard Europe, GB-mandated China, BIS-emerging India). CAGRs were derived from installed base turnover rates and new corridor greenfield deployment schedules. Industry-specific forecast inputs incorporated high-speed rail construction pipelines under China's GB 50157 standards and EU Ecodesign fluorescent phase-out deadlines.
Stress conditions across semiconductor supply disruption, prolonged EN 50155 certification delays, and ridership recovery shortfalls were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement timelines. Cross-checking against individual transit agency capital improvement program disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Taxi and Limousine Software Market