
 Global Light Vehicle (LV) Cabin AC Filters Market | 2026-2036
Global Light Vehicle (LV) Cabin AC Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Light Vehicle (LV) Cabin AC Filters Market Outlook
Synthetic fiber media is shifting toward bio-based cellulose and nanofiber laminates as automakers slash material costs without sacrificing filtration efficiency. Robert Bosch GmbH leverages its Tier 1 integration depth to supply OE-fit cabin filters directly to German and Asian assembly lines. Mann+Hummel GmbH anchors its position through captive testing protocols that exceed ISO 11155-1 baseline requirements. Freudenberg & Co. KG specializes in multi-layer activated carbon composites that target volatile organic compound removal in premium vehicle segments.
Light Vehicle Cabin AC Filters are pleated or layered fibrous media assemblies installed within HVAC plenums to remove particulate matter, pollen, and gaseous contaminants from intake air, with typical pressure drop thresholds below 150 Pa at rated airflow. Their primary commercial purpose is to protect occupant respiratory health while preventing evaporator coil fouling that degrades thermal performance. Activated Carbon and HEPA product types command the dominant margin pools as OEMs spec higher-efficiency media to meet tightening cabin air quality benchmarks. SUV and Sedan vehicle types generate the densest replacement demand due to larger cabin volumes and higher HVAC duty cycles relative to compact hatchbacks.
FDA oversight of antimicrobial claims on filter packaging, EPA tailpipe-to-cabin air quality linkages in regulatory impact assessments, and China's GB/T standard revisions for automotive cabin air filtration collectively elevate compliance costs for non-compliant suppliers. The EU F-Gas Regulation indirectly pressures filter performance by tightening HVAC system leak standards that force more air recirculation through cabin media. Stakeholders must monitor how NMPA alignment with ISO 11155-2 testing protocols reshapes product certification requirements for filters entering Chinese assembly plants.
Market Dynamics
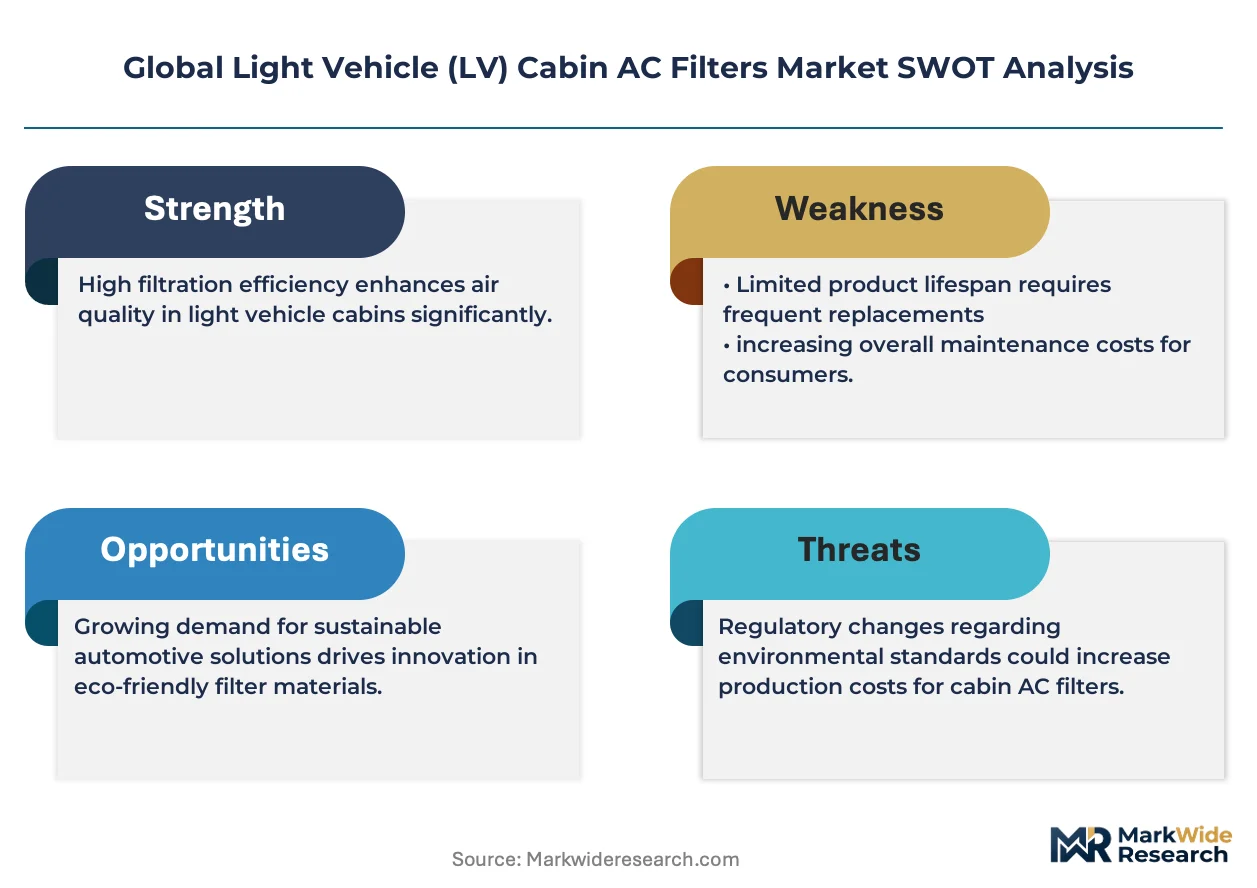
Electric vehicle HVAC architectures demand higher-efficiency cabin filtration as sealed battery cabins intensify air recirculation rates and compress filter replacement intervals across OEM assembly programs.
Growth Catalysts
- EU F-Gas Regulation:Tightened leak-rate standards for automotive refrigerant systems force greater reliance on cabin air recirculation, accelerating premium filter fitment rates in German and French vehicle production.
- Nanofiber laminate media:Multi-layer synthetic-cellulose composites achieve HEPA-grade efficiency at reduced pressure drop, enabling downsized HVAC blower motors in electric SUVs without sacrificing airflow capacity.
- China's dual carbon goals:National mandates for carbon neutrality by 2060 elevate cabin air quality to a consumer-visible sustainability metric, driving activated carbon filter penetration in domestic EV brands.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyester staple fibers constitute 60-70% of synthetic media costs, exposing filter margins to crude-linked input swings without pass-through pricing power.
- Testing protocol fragmentation:Divergent ISO 11155-1, GB/T, and SAE J726 standards force redundant certification investments for suppliers serving multiple assembly regions.
- Extended-life service intervals:OEM-specified 30,000-kilometer replacement cycles in premium European nameplates compress aftermarket volume relative to historical 15,000-kilometer norms.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced manufacturing create localized supply incentives for filter media converters serving Maruti Suzuki and Tata Motors assembly networks.
- Antimicrobial filter coatings:FDA-registered additive claims on packaging differentiate aftermarket products in US retail channels where health-conscious consumers pay measurable premiums.
- Subscription-based filter replacement:Connected vehicle telematics enable predictive HVAC maintenance alerts, converting episodic aftermarket purchases into recurring revenue streams for Tier 1 suppliers.
Industry Challenges
- ISO 11155-2 protocol adoption:China's NMPA alignment with updated test standards requires expensive chamber investments and extended validation timelines for incumbent suppliers.
- Legacy HVAC plenum geometries:Retrofit filter designs must accommodate constrained space envelopes in older vehicle platforms without compromising seal integrity or bypass leakage rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Light Vehicle (LV) Cabin AC Filters Market |
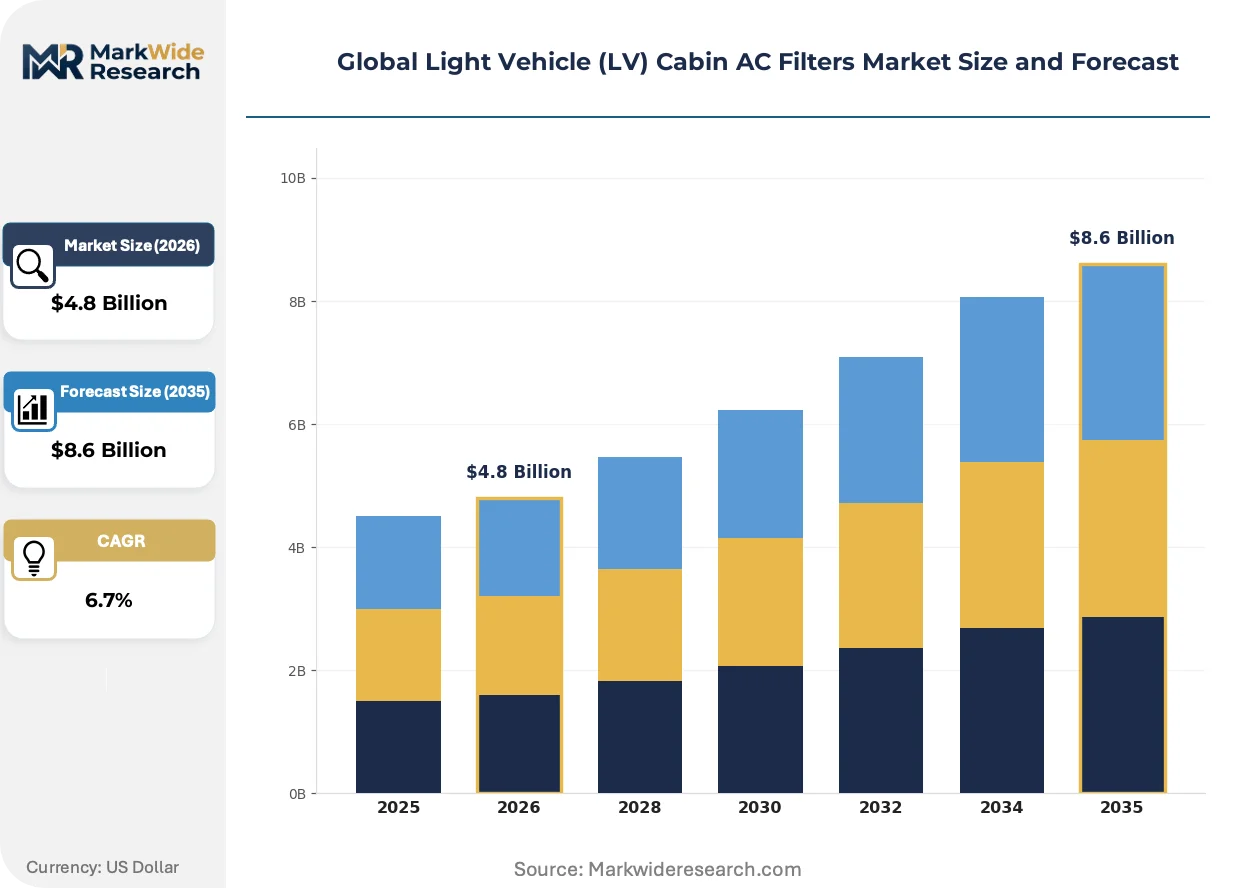
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, HEPA, Electrostatic, Pleated Vehicle Type: SUV, Sedan, Hatchback, Truck Filtration Efficiency: High Efficiency, Medium Efficiency, Low Efficiency, Standard Distribution Channel: Online, Offline, Retail, Wholesale |
| Companies Covered | Robert Bosch GmbH, MAHLE GmbH, Denso Corporation, Mann+Hummel GmbH, Valeo SA, Donaldson Company, Sogefi SpA, Freudenberg & Co. KG, ACDelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Light Vehicle (LV) Cabin AC Filters Market Strategic Shifts
Material science breakthroughs and regulatory convergence are compressing product development cycles while elevating performance benchmarks beyond legacy particulate filtration into gaseous contaminant management.
Bio-based cellulose media derived from agricultural waste streams is rewriting cost-performance tradeoffs in mass-market filter segments. Tier 2 suppliers in Germany and the United States are qualifying these materials for OE-fit programs targeting 2027 model year vehicles. The shift enables automakers to meet Scope 3 emissions disclosure requirements without sacrificing filtration efficiency ratings.
REACH restrictions on perfluorinated compounds are eliminating legacy water-repellent treatments from European-sourced media. Filter manufacturers are pivoting to silicone-based or bio-mimetic hydrophobic coatings that maintain oil-mist resistance in commercial vehicle applications. German KBA type-approval processes now explicitly screen for PFAS content in cabin air components, creating compliance differentiation for early movers.
Fleet operators and large-scale leasing companies are consolidating aftermarket procurement through direct supplier contracts rather than fragmented distributor networks. This bypasses traditional jobber channels in the United States and Western Europe, compressing margin pools for intermediaries while rewarding scale manufacturing with volume guarantees. The concentration is most pronounced in corporate EV fleets where standardized maintenance protocols dominate.
Global Light Vehicle (LV) Cabin AC Filters Market Segmentation
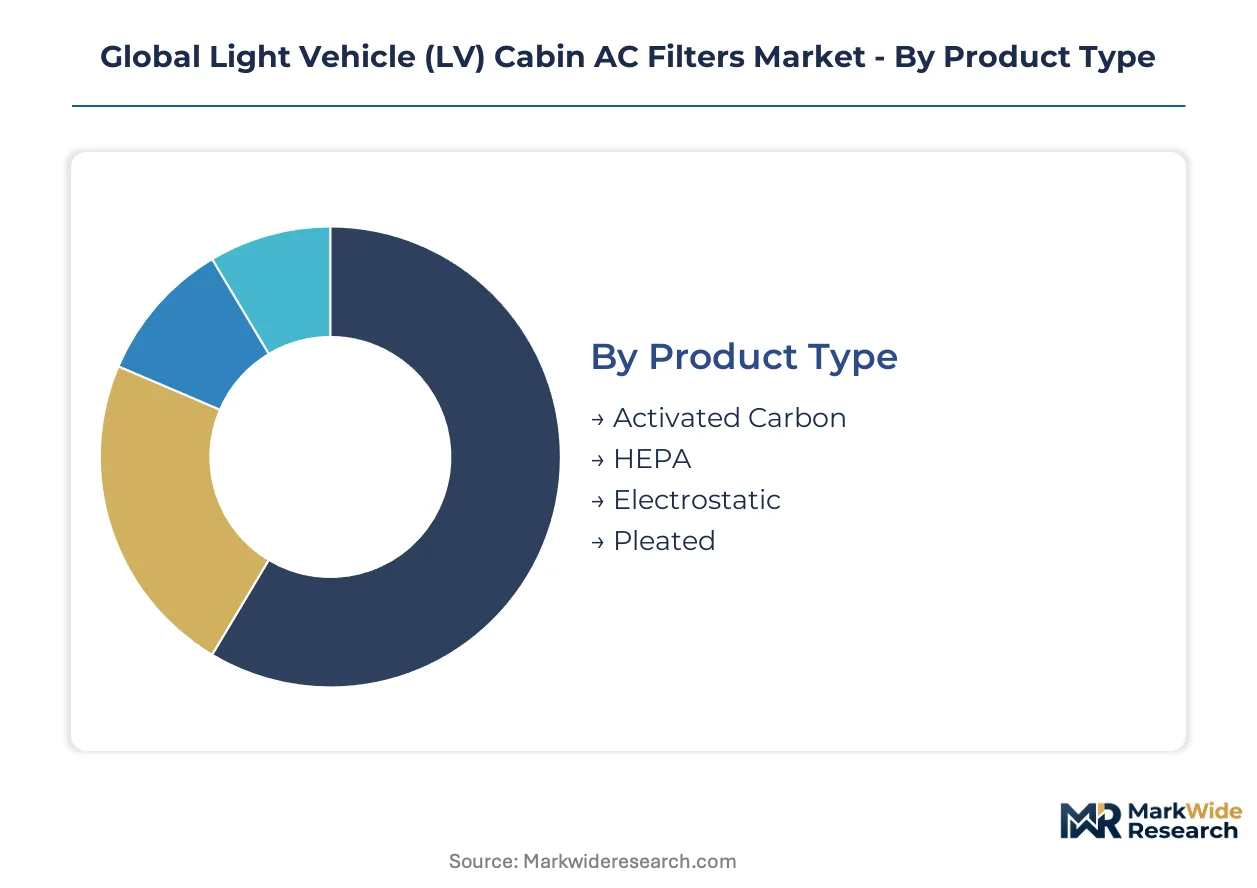
Cabin AC filter segmentation reveals how capital allocation, regulatory pressure, and HVAC architecture complexity concentrate margin pools across distinct product tiers and vehicle platforms. Understanding these divisions exposes where suppliers must deploy testing infrastructure versus where scale manufacturing dominates.
Product Type:
Multi-layer media production demands differentiated capital intensity, with activated carbon composite lines requiring thermal activation kilns and HEPA-grade facilities needing cleanroom laminating chambers that synthetic pleated lines avoid.
- Activated Carbon:Impregnated carbon granules bonded to nonwoven substrates capture VOCs and NOx through adsorption chemistry. German and Chinese OEM fitment programs for premium electric SUVs specify these composites to meet interior air quality mandates under EU F-Gas Regulation and China's GB/T revisions.
- HEPA:Glass microfiber or nanofiber laminates achieve 99.97% particulate retention at 0.3 microns through dense pleat packs. Sealed battery cabin architectures in electric vehicles force higher recirculation rates, compressing replacement intervals and concentrating demand in California and Shanghai assembly networks.
- Electrostatic:Permanently charged synthetic media attracts particles through electrostatic attraction rather than mechanical interception.
- Pleated:Basic cellulose or synthetic folds provide particulate screening at lowest unit cost for mass-market hatchback segments.
Activated Carbon absorbs the bulk of installed capacity; HEPA is expanding most quickly.
Vehicle Type:
Platform HVAC duty cycles and cabin air volumes determine filter surface area requirements, with larger passenger compartments demanding extended pleat depths and higher airflow ratings that strain blower motor specifications.
- SUV:Elevated seating positions and panoramic glass surfaces intensify solar load, forcing continuous HVAC operation that accelerates media loading. Three-row configurations in North American and Chinese domestic markets require dual-filter plenum designs that double per-vehicle content.
- Sedan:Formal rooflines and smaller glass areas reduce thermal stress, though premium German nameplates specify extended-life media that compress aftermarket replacement frequency.
- Hatchback:Compact cabin volumes enable downsized filter cartridges with reduced pleat counts.
- Truck:Commercial duty cycles and cab-over-engine designs expose filters to elevated coarse dust ingestion in agricultural and construction applications.
SUV claims the dominant share of OE-specified premium media; Sedan maintains the densest aftermarket replacement rhythm.
Filtration Efficiency:
Testing protocol investments scale with efficiency tier, as High Efficiency validation requires aerosol challenge chambers and particle counters that Standard-grade manufacturers bypass entirely.
- High Efficiency:HEPA-equivalent or near-HEPA performance targets PM2.5 and ultrafine particulate removal. China's NMPA alignment with ISO 11155-2 protocols forces chamber investments for suppliers serving BYD and NIO assembly programs.
- Medium Efficiency:Balanced pressure drop and particulate capture for mainstream passenger applications.
- Low Efficiency:Basic pollen and coarse dust screening for price-sensitive emerging market vehicles.
- Standard:Legacy particulate ratings meeting baseline OEM requirements without activated carbon or antimicrobial add-ons.
High Efficiency commands the steepest certification burden; Medium Efficiency delivers the broadest volume base.
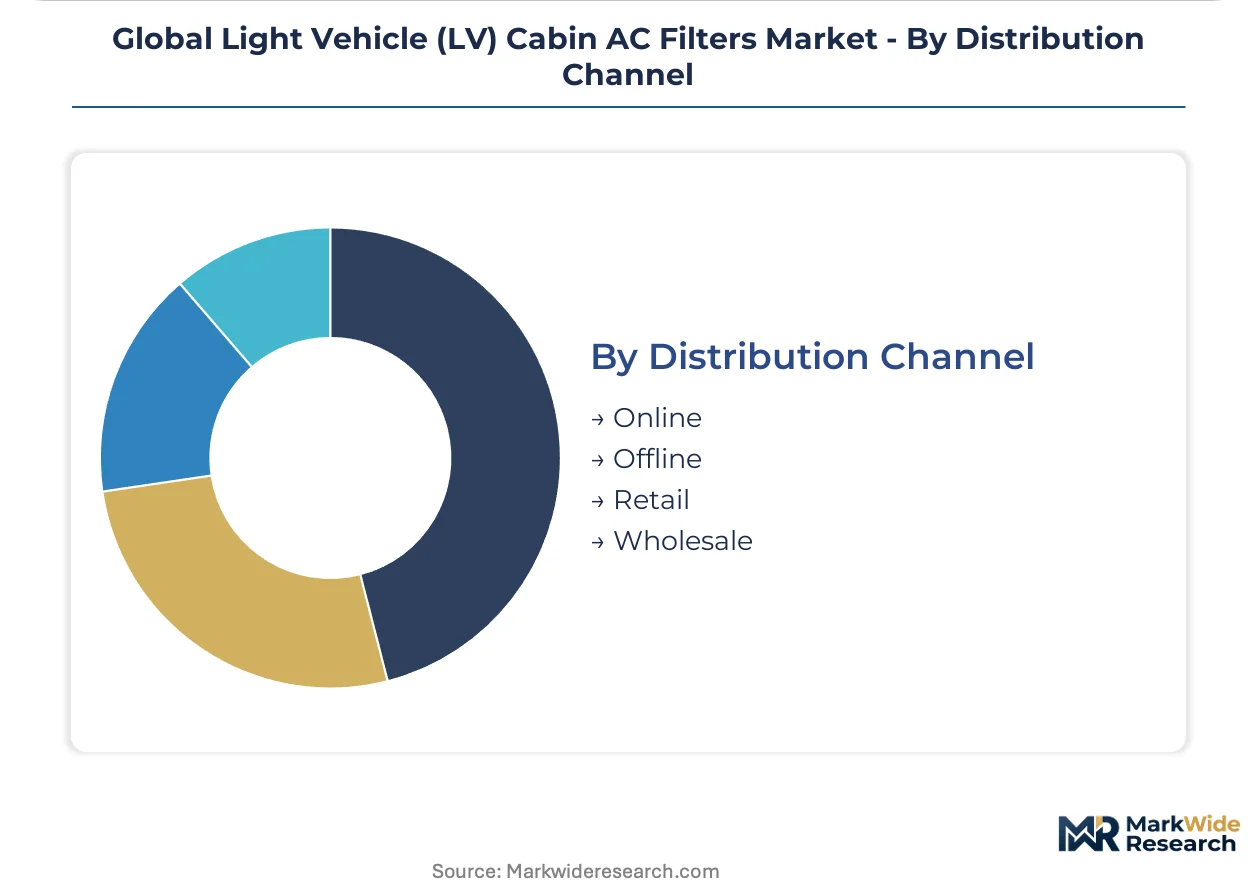
Distribution Channel:
Channel economics diverge sharply on working capital intensity, with wholesale bulk contracts demanding inventory financing that direct-to-consumer online models circumvent through drop-ship fulfillment.
- Online:Direct-to-consumer platforms and marketplace aggregators bypass traditional jobber margins. US retail channels reward FDA-registered antimicrobial claims with measurable price premiums from health-conscious DIY installers.
- Offline:Service bay installation at franchised dealerships and independent garages captures fleet maintenance contracts.
- Retail:Big-box automotive chains and specialty parts stores stock standardized SKUs for immediate replacement needs.
- Wholesale:Volume contracts with fleet operators and leasing companies consolidate procurement, compressing intermediary margins while rewarding scale manufacturing with multi-year volume guarantees.
Wholesale is gaining share fastest among corporate EV fleets; Retail remains the default for emergency replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States as these markets enforce stricter particulate limits and accelerate electric vehicle HVAC fitment programs. OEM assembly networks in these countries specify higher-efficiency media that compress replacement cycles and elevate certification requirements.
Germany
KBA type-approval processes now screen explicitly for PFAS content in cabin air components, forcing suppliers to abandon legacy water-repellent treatments. The EU F-Gas Regulation tightens leak-rate standards for automotive refrigerant systems, driving premium filter fitment in Stuttgart and Munich assembly corridors. Robert Bosch GmbH leverages Tier 1 integration depth to supply OE-fit cabin filters directly to domestic and Asian assembly lines.
China
National dual carbon goals elevate cabin air quality to a consumer-visible sustainability metric, accelerating activated carbon filter penetration in domestic EV brands. NMPA alignment with ISO 11155-2 testing protocols reshapes product certification requirements for filters entering BYD and NIO assembly plants. Shanghai and Shenzhen production clusters concentrate nanofiber laminate qualification programs targeting 2027 model year vehicles.
United States
FDA oversight of antimicrobial claims on filter packaging differentiates aftermarket products in retail channels where health-conscious consumers pay measurable premiums. EPA tailpipe-to-cabin air quality linkages in regulatory impact assessments elevate compliance costs for non-compliant suppliers. Detroit-area OEM technical centers specify extended-life media that compress aftermarket replacement frequency relative to historical norms.
India
The PLI scheme for automotive components creates localized supply incentives for filter media converters serving Maruti Suzuki and Tata Motors assembly networks. BIS standard revisions for automotive cabin air filtration force chamber investments for suppliers qualifying for domestic OE-fit programs. Tamil Nadu and Gujarat manufacturing corridors attract media laminating capacity targeting export and domestic replacement demand.
Japan
METI guidance on vehicle interior air quality pushes OEMs toward HEPA-equivalent specifications in premium electric vehicle segments. JIS standard harmonization with ISO protocols reduces redundant testing burdens for suppliers serving both domestic and export assembly programs. Nagoya-area HVAC component clusters specialize in compact pleat designs for hybrid vehicle architectures with constrained plenum envelopes.
Global Light Vehicle (LV) Cabin AC Filters Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers position thermal activation kilns and cleanroom laminating chambers to capture OE-fit programs for 2027 model year vehicles. The market structure consolidates around German and Japanese Tier 1 systems integrators with captive HVAC divisions, alongside independent filtration specialists with deep testing protocol expertise. Three archetypes define competitive positioning: integrated automotive suppliers controlling full HVAC system specifications, standalone media converters with ISO 11155-2 chamber investments, and aftermarket-focused brands leveraging antimicrobial coating differentiation. M&A activity and geographic licensing agreements represent the dominant competitive moves as scale manufacturers seek regional production footprints without greenfield capital deployment.
Among German-based integrated suppliers, Robert Bosch GmbH and Mann+Hummel GmbH exemplify the Tier 1 archetype with direct assembly line relationships and captive testing protocols exceeding baseline requirements. Freudenberg & Co. KG occupies a position within the specialized media tier, representing multi-layer composite expertise targeting volatile organic compound removal applications. These three entities anchor the competitive landscape through differentiated integration depth rather than pure manufacturing scale.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| MAHLE GmbH |
| Denso Corporation |
| Mann+Hummel GmbH |
| Valeo SA |
| Donaldson Company |
| Sogefi SpA |
| Freudenberg & Co. KG |
| ACDelco |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap media converters in Germany and Japan anchor supply discipline through generational ownership horizons that resist short-term margin compression, translating into stable contract pricing for OEM-fit programs even as petrochemical input costs fluctuate. This ownership structure concentrates pricing power with incumbent suppliers while limiting spot-market volatility for downstream HVAC integrators.
Pricing Analysis
The volume-margin split concentrates aftermarket pleated media in commoditized price bands while OE-fit activated carbon and HEPA composites capture premium positioning through ISO 11155-2 certification requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by filtration efficiency grade and antimicrobial additive registration status. Cost compression in synthetic fiber tiers is intensifying because polypropylene staple feedstock tracks crude-linked indices without full pass-through mechanisms. Fleet procurement managers exhibit highest price sensitivity through consolidated wholesale contracts, whereas German premium OEM technical centers prioritize performance validation over unit cost.
Supply Chain Analysis
Polypropylene staple fiber supply rests on petrochemical complexes in Germany, China, and the United States that dominate global synthetic nonwoven feedstock. Activated carbon granules draw from coconut shell processors in Indonesia and Sri Lanka alongside coal-based thermal activation facilities in China. Single-source vulnerability concentrates in nanofiber laminate equipment where German and Japanese laminating chamber manufacturers control cleanroom-grade installation capacity. Distribution runs through Tier 1 HVAC system integrators that bundle filter cartridges with blower motor assemblies for direct assembly line delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cabin filter market sits in a materials-transition phase as bio-based cellulose displaces synthetic fiber media in mass-market OE-fit programs, compressing development cycles for incumbent converters while opening qualification pathways for agricultural waste processors.
For Market Incumbents: Acquire thermal activation kiln capacity in Southeast Asia to secure coconut shell carbon supply chains before regional export restrictions tighten. Consolidate testing protocol investments by qualifying multi-layer media against both ISO 11155-2 and GB/T standards simultaneously, defending against Chinese domestic suppliers capturing BYD and NIO assembly share through localized certification. For New Entrants and Emerging Players: Begin with aftermarket antimicrobial coating formulations targeting US retail channels where FDA-registered additive claims support measurable price premiums. India's PLI scheme for automotive components offers the most penetrable white-space for media laminating capacity serving Maruti Suzuki and Tata Motors networks, with BIS standard revisions creating qualification barriers that favor early chamber investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor standalone media converters with ISO 11155-2 chamber investments in Germany and China where NMPA alignment timelines have strained validation budgets for sub-scale competitors. The long-term viability window favors suppliers with backward integration into bio-based cellulose feedstocks rather than petrochemical-dependent synthetic fiber exposure. Watch NMPA enforcement consistency as the inflection signal for Chinese market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Cellulose | Agricultural waste processors in Germany and the United States qualify materials for 2027 model year OE-fit programs. |
| ISO 11155-2 Chamber Investment | Chinese NMPA alignment forces validation infrastructure for suppliers serving BYD and NIO assembly plants. |
| Antimicrobial Coating Registration | FDA-registered additive claims differentiate aftermarket products in US retail channels with health-conscious premiums. |
| Subscription-Based Replacement Models | Connected vehicle telematics convert episodic aftermarket purchases into recurring revenue for Tier 1 suppliers. |
| PLI Scheme Localization in India | Production-linked incentives attract media laminating capacity for Maruti Suzuki and Tata Motors networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across Tier 1 supplier procurement, OEM platform engineers, aftermarket distributors, and dealership operations. KBA type-approval documentation, NMPA certification databases, FDA antimicrobial registration records, and vehicle production databases supplied quantitative benchmarks. Bottom-up filter unit economics triangulated against top-down HVAC system value assessments.
Granularity-level modeling disaggregated volume and value across the analysis window by product type, vehicle class, propulsion architecture, and regional production cluster. CAGRs derived from segment-level replacement cycle assumptions, OE-fit penetration rates, and aftermarket channel mix projections. Electric vehicle HVAC duty cycle intensity and sealed cabin recirculation rates served as primary demand drivers in the analytical framework.
EU F-Gas Regulation enforcement delays, NMPA ISO 11155-2 adoption timelines, and petrochemical feedstock volatility are the dominant revision risks. Forecasts reflect assumptions on regulatory convergence speed and electric vehicle assembly mix. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market