
 Tram Systems Market | 2026-2036
Tram Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Tram Systems Market Analytics
Urban transit electrification is realigning procurement priorities across municipal authorities worldwide. Siemens leverages its digital rail platform to anchor large-scale tram modernization programs in Central European networks. Alstom competes through integrated catenary-free solutions that sustain operational flexibility in heritage city centers. Škoda Group specializes in low-floor modular architectures that dominate fleet renewals across Eastern European operators.
Tram systems constitute rail-based urban transit vehicles operating on embedded track with steel wheels, typically drawing 600–750 V DC power via overhead catenary or onboard energy storage for passenger volumes between 200 and 500 per consist. Their primary purpose centers on high-capacity, surface-level urban mobility with lower infrastructure cost than metro alternatives. Light rail installations occupy the largest installed base among type segments, though battery electric technology is expanding fastest as cities eliminate overhead wire visual impact in historic districts. Dedicated right-of-way configurations command premium pricing due to land acquisition and civil engineering intensity.
EU Green Deal transport decarbonization targets, ECHA battery substance regulations, and national rail safety frameworks shape product compliance trajectories across European markets. The EU AI Act introduces emerging conformity obligations for autonomous tram pilot programs. Stakeholders must monitor regulatory timing for catenary-free mandates and energy storage certification standards to align R&D roadmaps with procurement cycles.
Market Dynamics
EU Green Deal decarbonization mandates are forcing municipal transit authorities to accelerate fleet electrification timelines, compressing procurement cycles from historical 8-10 year replacement windows to 5-7 year compressed schedules.
Growth Catalysts
- Catenary-free battery technology:Heritage city centers in Germany and France are mandating overhead wire removal, creating concentrated demand for onboard energy storage systems that preserve urban aesthetic integrity.
- EU Green Deal transport targets:Binding 2030 emissions reduction obligations for urban mobility are redirecting capital budgets from diesel bus expansion toward rail-based electrified alternatives.
- Dedicated right-of-way infrastructure:French and Spanish municipalities are prioritizing segregated tram corridors that deliver superior speed and reliability versus mixed-traffic bus operations.
Market Restraints
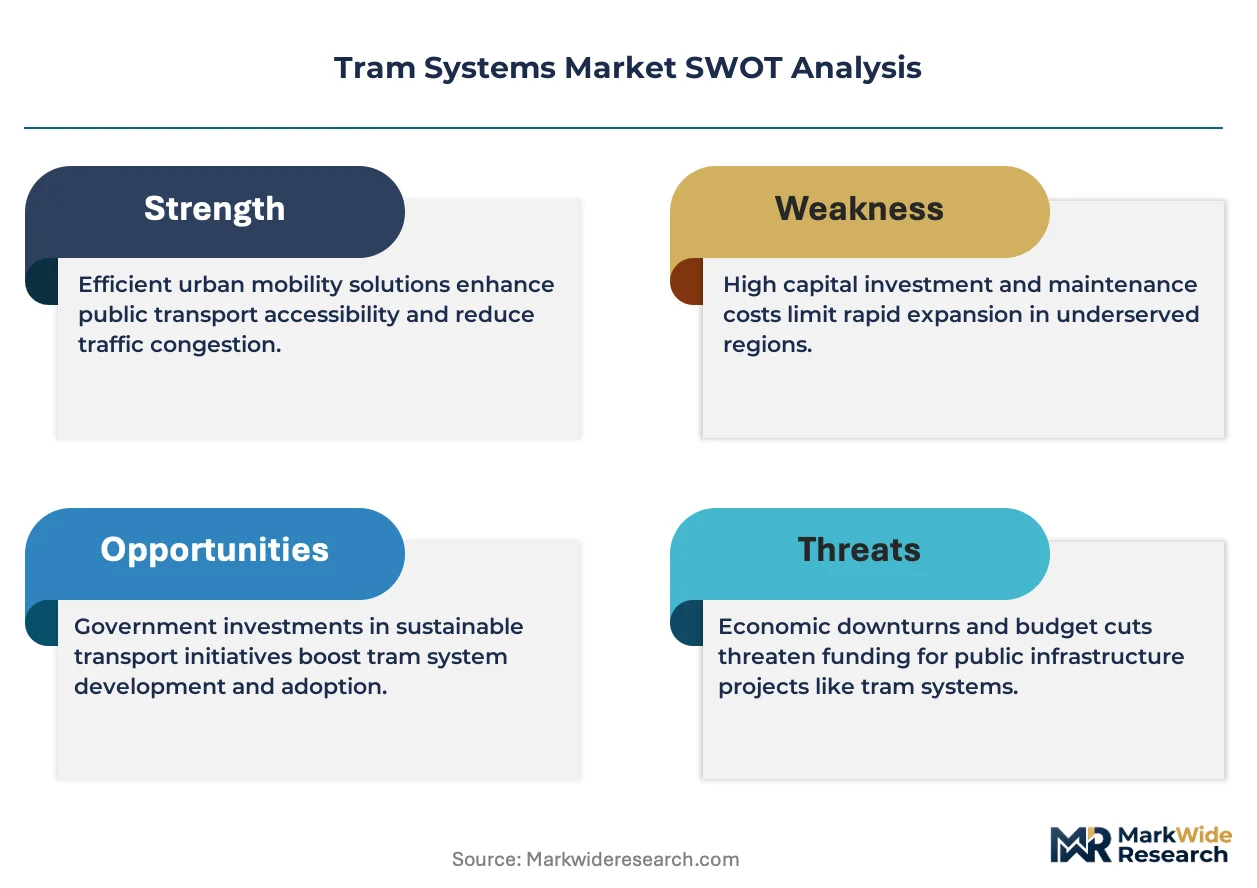
- Lithium-ion cell supply concentration:Battery pack production for tram energy storage depends heavily on East Asian cell manufacturers, exposing European OEMs to geopolitical supply disruption risks.
- Copper and aluminum price volatility:Overhead catenary systems and traction power infrastructure face input cost pressure from commodity market fluctuations.
- Land acquisition costs:Dedicated right-of-way construction in dense urban cores encounters expropriation delays and compensation disputes that extend project timelines.
Strategic Opportunities
- Autonomous tram pilot programs:The EU AI Act is creating a compliance pathway for driverless operation in controlled depot and yard environments.
- Eastern European fleet renewal:Czech, Polish, and Romanian operators are replacing Soviet-era rolling stock with low-floor accessible designs.
- Energy storage certification standards:ECHA battery substance regulations are opening first-mover advantages for OEMs with pre-certified sustainable cell chemistries.
Industry Challenges
- Traction power engineer shortage:Specialized expertise in 750V DC electrification infrastructure is aging out of European utility workforces faster than training programs replenish capacity.
- Catenary-to-battery retrofit complexity:Existing fleet modernization requires simultaneous pantograph removal, battery integration, and charging infrastructure deployment without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tram Systems Market |
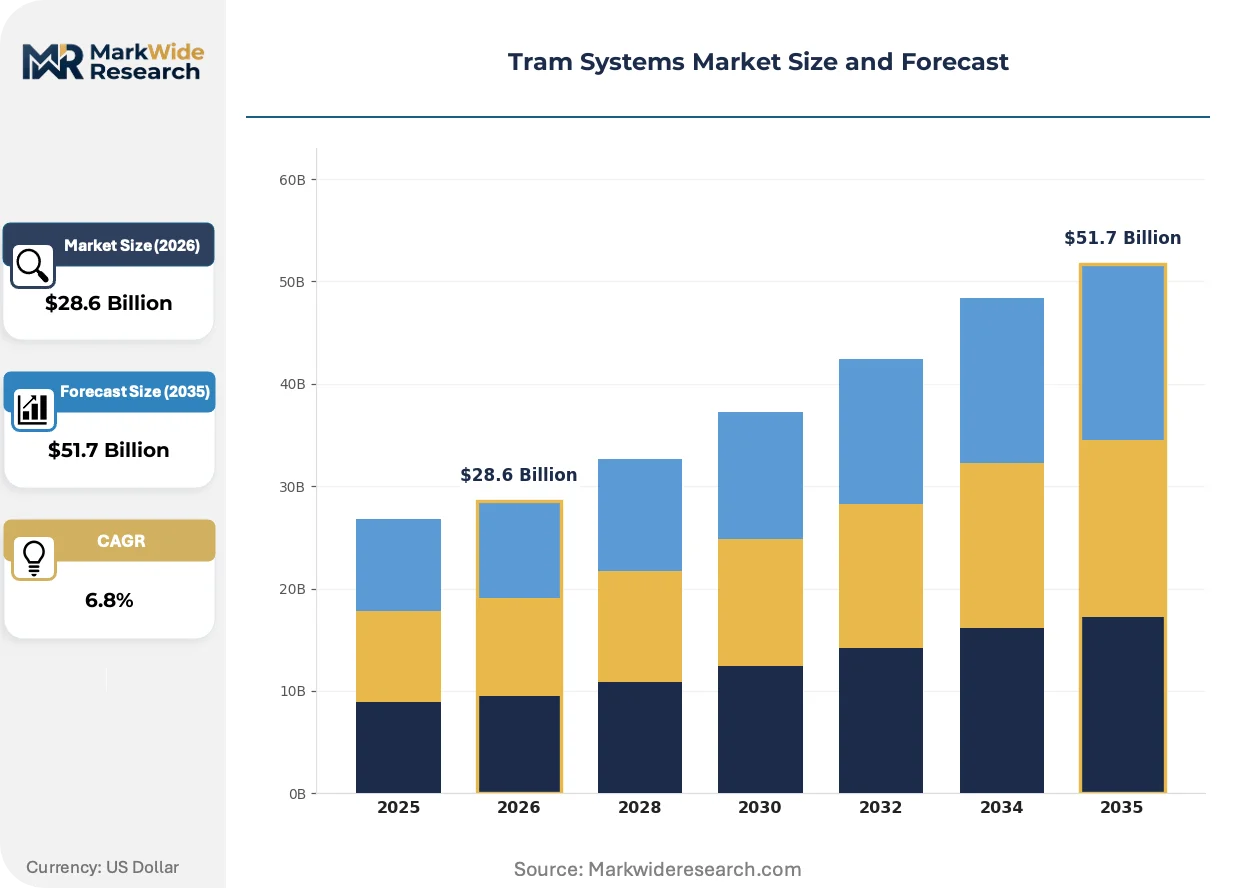
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Light Rail, Heavy Rail, Cable Tram, Modern Tram Technology: Battery Electric, Overhead Electric, Diesel-Electric, Autonomous End User: Public Transport Authorities, Tour Operators, City Planners, Private Operators Installation Type: On-Street, Dedicated Right-of-Way, Elevated, Underground |
| Companies Covered | CAF, Hitachi Rail, Alstom, Thales Group, Škoda Group, Siemens, CRRC, BYD Company, Stadler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tram Systems Market Evolving Landscape
Digitalization of tram operations is compressing maintenance intervals and enabling predictive asset management across European networks. Operators are demanding integrated platforms that unify vehicle health monitoring with traffic signal priority systems.
Supercapacitor-based fast-charging systems are automating opportunity charging at station stops, eliminating the need for extended depot charging infrastructure. Czech and German operators are deploying these systems on peripheral lines with lower frequency service. This technology is automating fleet deployment flexibility by reducing route planning constraints imposed by battery range limitations.
REACH substance restrictions on persistent organic pollutants are forcing insulation material substitutions in traction motors and high-voltage cabling. OEMs are qualifying epoxy resin alternatives that maintain thermal performance without restricted flame retardants. French and Belgian authorities are accelerating compliance verification through centralized pre-approval frameworks.
Municipal procurement departments are consolidating rolling stock and maintenance contracts into 15-20 year lifecycle agreements. This bundling is displacing traditional vehicle-only tenders with performance-based availability contracts. Spanish and Italian regional operators are pioneering this shift, transferring operational risk to manufacturers in exchange for guaranteed uptime metrics.
Tram Systems Market Segmentation
Tram system procurement decisions cascade through multiple technical and operational dimensions. Municipal authorities weigh infrastructure constraints against passenger capacity targets, while technology choices determine long-term energy costs and maintenance regimes. Understanding how these segments intersect reveals where capital deployment concentrates and where emerging configurations are gaining traction.
Type:
Volume installations favor established rail formats with proven maintenance ecosystems, while premium corridor projects explore specialized configurations that command higher unit economics.
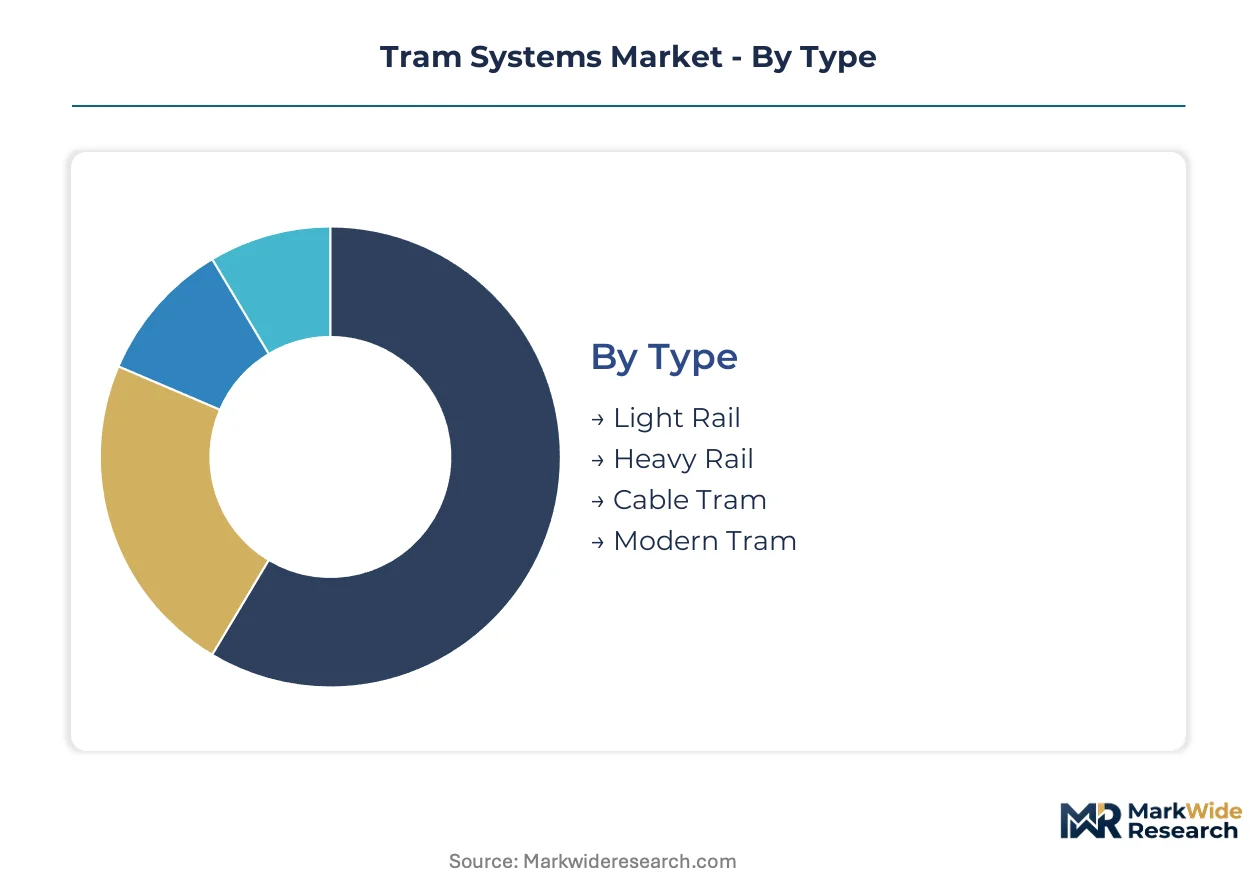
- Light Rail:Surface-level operation on shared or segregated track with 200-400 passenger capacity per consist. German and French municipal networks are expanding these systems under EU Green Deal mandates, prioritizing routes where metro construction costs prove prohibitive.
- Heavy Rail:Higher-axle-load vehicles with enhanced structural frames for demanding terrain or freight integration. Alpine corridors in Switzerland and Austria deploy these for steep-gradient operations where standard light rail specifications fail.
- Cable Tram:Haulage-powered systems using underground cables for extreme gradient environments. San Francisco's heritage infrastructure and select Lisbon routes preserve this technology for topographical necessity.
- Modern Tram:Low-floor accessible designs with modular interior configurations. Czech and Polish operators are standardizing on these for full fleet accessibility compliance.
Mature deployment sits with Light Rail. Newer deployment is concentrated in Modern Tram configurations.
Technology:
Power source selection determines infrastructure investment intensity and operational flexibility across route networks.
- Battery Electric:Onboard lithium-ion or solid-state storage eliminating overhead catenary requirements. Heritage districts in France and Germany are mandating this technology to preserve urban aesthetic integrity while meeting decarbonization targets.
- Overhead Electric:Pantograph-fed 600-750V DC traction through continuous catenary infrastructure. Established networks in Belgium and the Netherlands maintain this for high-frequency trunk lines where energy density demands exceed battery economics.
- Diesel-Electric:Hybrid propulsion for non-electrified extensions or emergency diversion routes. Peripheral Czech and Romanian operators retain limited fleets for infrastructure gaps.
- Autonomous:Sensor-guided operation with remote supervision for depot movements and low-speed environments. The EU AI Act is enabling controlled pilot programs in German yard facilities.
Overhead Electric maintains the largest installed base. Battery Electric is climbing the fastest as catenary-free mandates proliferate.
End User:
Procurement authority shapes contract structure, risk allocation, and lifecycle service expectations.
- Public Transport Authorities:Municipal or regional agencies operating scheduled services with farebox revenue. Spanish and Italian regional operators are pioneering 15-20 year availability-based contracts bundling rolling stock and maintenance.
- Tour Operators:Heritage and scenic route services emphasizing experiential passenger value. Lisbon and Milan maintain specialized fleets for tourist corridor differentiation.
- City Planners:Urban development agencies procuring systems as land-value capture instruments. French municipalities are integrating tram corridors with transit-oriented zoning reforms.
- Private Operators:Concession-based service providers under public service obligation frameworks. Limited penetration in European markets outside UK and Swedish regulatory environments.
Public Transport Authorities dominate procurement volume. Private Operators represent the smallest segment but with expanding concession experimentation.
Installation Type:
Right-of-way configuration determines civil engineering intensity, speed capability, and land acquisition complexity.
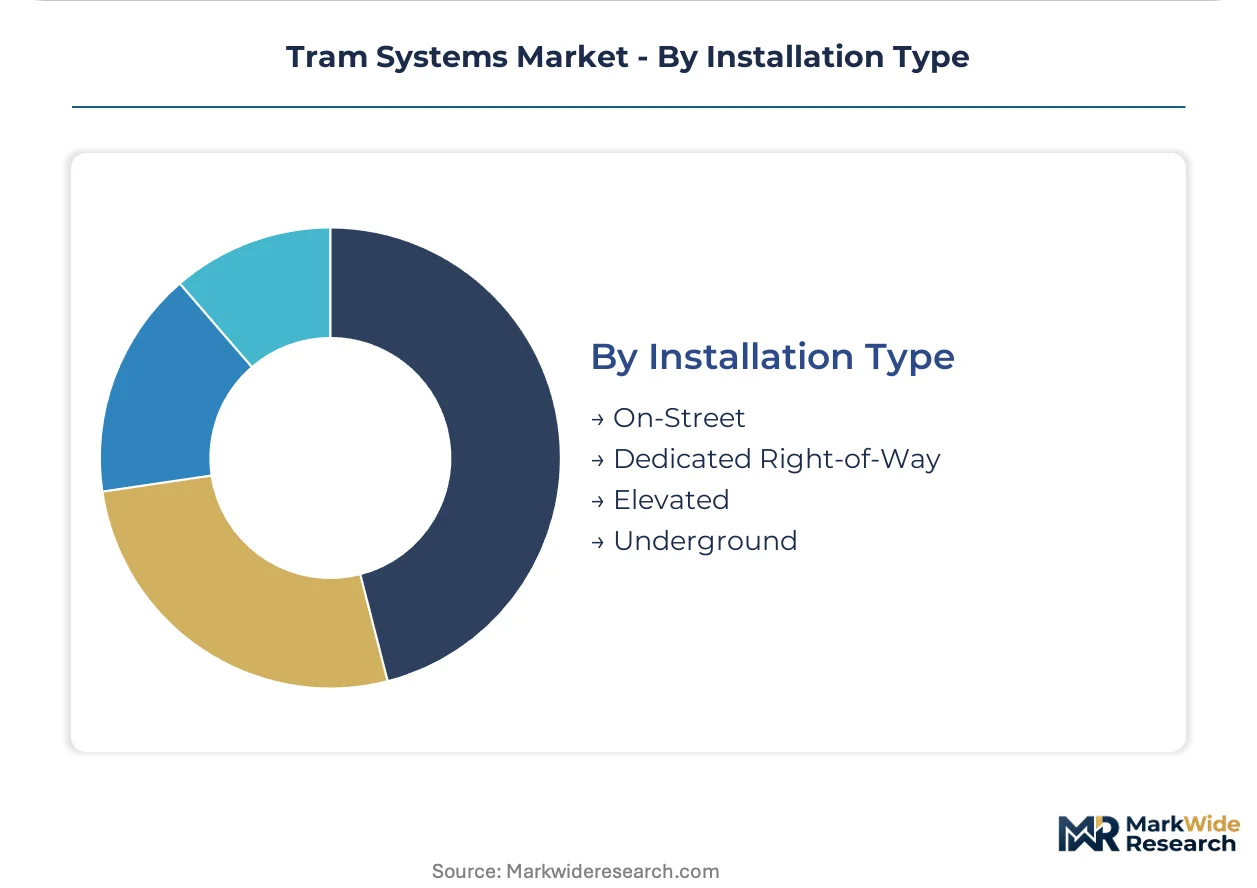
- On-Street:Mixed-traffic or reserved-lane operation with frequent stops and pedestrian interaction. Dense Italian and Spanish historic cores deploy these where property takings face legal barriers.
- Dedicated Right-of-Way:Fully segregated corridors with priority signaling and grade-separated intersections. French and Spanish municipalities are prioritizing these for reliability targets exceeding 98% on-time performance.
- Elevated:Viaduct or bridge structures for water crossings or topographical transitions. Limited deployment in Lisbon and Porto for harbor access routes.
- Underground:Tunnelled sections through density barriers or environmental constraints. Brussels and Budapest utilize short underground segments to traverse sensitive surface corridors.
Dedicated Right-of-Way commands premium pricing per kilometer. On-Street installation retains the broadest geographic spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of tram rolling stock concentrates in Central European manufacturing clusters, while consumption spreads across municipal transit authorities in dense urban corridors. German, French, and Czech OEMs supply battery electric and catenary-free platforms to cities prioritizing heritage district preservation. Demand fragmentation across national procurement frameworks creates regional specialization in technology deployment.
Germany
KBA vehicle certification requirements and EU Green Deal urban mobility mandates are accelerating fleet electrification in Bavaria and North Rhine-Westphalia. Siemens anchors production in Munich, supplying battery electric platforms to Frankfurt and Düsseldorf for catenary-free heritage corridor operations.
France
ANSM urban transport oversight and binding 2030 decarbonization targets are redirecting capital toward segregated tram infrastructure. Alstom manufactures integrated systems at its Saint-Ouen facility, serving Paris Metro expansion and Lyon autonomous pilot programs under EU AI Act frameworks.
Czech Republic
Škoda Group dominates low-floor modular production from its Plzeň headquarters, capturing Eastern European fleet renewal demand. Czech operators are replacing Soviet-era rolling stock with accessible designs compliant with ECHA battery substance regulations.
Spain
Spanish regional operators are pioneering 15-20 year availability-based contracts bundling rolling stock and maintenance. CAF supplies dedicated right-of-way systems to Barcelona and Madrid, where transit-oriented zoning reforms are capturing land value around new corridors.
Poland
Polish municipal networks in Kraków and Wrocław are standardizing on modern tram configurations for full accessibility compliance. Procurement is shifting toward performance-based contracts as operators seek guaranteed uptime metrics from European OEMs.
Tram Systems Market Competitive Landscape
Top-tier vendors anchor high-capacity production for flagship municipal networks, while mid-tier specialists capture regional fleet renewal and heritage modernization programs. The vendor base stratifies across integrated platform providers, modular architecture specialists, and catenary-free technology innovators. Strategic archetypes include full-system integrators, component-focused suppliers, and battery technology pioneers. Competitive moves center on long-term availability contracts and geographic expansion into Eastern European replacement cycles.
Among European integrated platform providers, Alstom, Siemens, and Škoda Group occupy positions across the technology spectrum. Alstom exemplifies the catenary-free solution archetype with heritage district deployments. Siemens represents the digital rail platform integrator serving large-scale modernization programs. Škoda Group anchors the low-floor modular specialist tier dominating Eastern European accessible fleet renewals.
| Leading Market Players |
|---|
| CAF |
| Hitachi Rail |
| Alstom |
| Thales Group |
| Škoda Group |
| Siemens |
| CRRC |
| BYD Company |
| Stadler |
| Others |
Value Network & Pricing Analysis
London Metal Exchange copper price volatility cascades through tram system manufacturing into three-tier pricing structures across premium, standard, and economy levels. Battery cell cost fluctuations from East Asian suppliers compress margins on catenary-free platforms while dedicated right-of-way infrastructure premiums hold firm against commodity swings.
Pricing Analysis
Margin tightening in standard-tier tram configurations reflects lithium-ion cell supply concentration and copper price volatility. Three-tier pricing structure across premium, standard, and economy levels separates full-service lifecycle contracts from vehicle-only procurement. Certification tier under ECHA battery substance regulations and volume scale drive price differentiation. Municipal transport authorities in Eastern Europe exhibit highest price sensitivity due to constrained capital budgets, while French and German heritage corridor operators accept premium positioning for aesthetic compliance.
Supply Chain Analysis
Battery cell supply rests on South Korean and Chinese specialty manufacturers, with European OEMs drawing from concentrated East Asian sources. Traction motor copper windings, aluminum structural extrusions, and semiconductor power electronics constitute critical input dependencies. Single-source vulnerability in solid-state battery cell chemistry creates exposure to geopolitical disruption. Distribution runs through municipal procurement frameworks with 15-20 year availability-based contracts displacing traditional vehicle-only tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tram system manufacturing operates as a supply-constrained market where traction power engineer shortages prop pricing power for integrated platform providers. Capacity bottlenecks in specialized electrification expertise sustain premium positioning for full-system vendors.
For Market Incumbents: Deepen backward integration into battery cell qualification and charging infrastructure deployment to defend against emerging catenary-free specialists. Anchor capacity addition in Czech and Polish manufacturing clusters to capture Eastern European fleet renewal cycles. Certification investment under ECHA battery substance regulations creates switching costs that protect installed base positions. For New Entrants and Emerging Players: Capture autonomous tram pilot program opportunities under EU AI Act frameworks in German depot and yard environments. Heritage city center catenary-free retrofits in France and Italy represent the most penetrable segment for modular battery platform specialists. Partner with municipal operators on performance-based availability contracts to bypass traditional vehicle-only procurement barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor low-floor modular tram specialists with pre-certified sustainable cell chemistries in Eastern European geographies. Five-to-ten year viability hinges on fleet replacement timelines and regulatory compliance positioning. Watch ECHA battery substance regulation enforcement timing as inflection indicator for first-mover certification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell capacity from South Korean suppliers for catenary-free platform deployment. |
| Backward Integration | Captures charging infrastructure and energy storage system production to control total cost of ownership. |
| Regulatory Certification Program | Accelerates ECHA battery substance pre-approval to lock in heritage corridor procurement mandates. |
| Long-term Availability Contract | Transfers operational risk to manufacturers through 15-20 year performance-based maintenance bundling. |
| Geographic Manufacturing Footprint | Establishes Czech and Polish production hubs to serve Eastern European Soviet-era fleet replacement demand. |
Research Methodology
Trade association filings, municipal procurement databases, and OEM technical documentation formed the secondary backbone for this analysis. Primary interviews with fleet planning directors, traction power engineers, and regulatory compliance officers at European transport authorities combined with secondary validation. Bottom-up and top-down triangulation anchored volume estimates across national procurement frameworks and manufacturer production disclosures.
Historical trendline analysis of fleet replacement cycles and electrification investment patterns informed projection modeling across the analysis window. Segmentation dimensions included tram type, power source technology, installation configuration, and procurement authority structure. CAGRs derived from weighted average of national mandate timelines and infrastructure investment pipelines. Battery cost curves and copper price scenarios served as key forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement timing and ECHA battery certification pathway clarity. Forecasts reflect assumptions around municipal capital budget continuity and cell chemistry qualification schedules. A small set of named triggers—autonomous tram regulatory approval, lithium supply disruption, and catenary-free mandate acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Mass Transit Signage Market