
 Demand-Responsive Transit (DRT) Market | 2026-2036
Demand-Responsive Transit (DRT) Market Size, Share, and Industry Trends Forecast 2026-2036
Demand-Responsive Transit (DRT) Market Outlook
Healthcare and paratransit service integration is broadening the addressable base for DRT platforms. Transdev North America leverages its established paratransit contracts to anchor recurring revenue streams across North American transit agencies. Swiftly competes through real-time data infrastructure that feeds dynamic routing algorithms for municipal clients. Ridango specializes in multimodal ticketing platforms that extend its reach into Eastern European markets where legacy systems dominate.
Demand-Responsive Transit denotes algorithmically dispatched shared transportation services that match vehicle supply to real-time passenger requests through digital platforms, typically operating within defined service zones using 8-15 seat vehicles or standard sedans. The primary commercial purpose replaces fixed-route bus coverage in low-density corridors while providing first-mile and last-mile connectivity to trunk transit networks. Microtransit deployments now occupy the fastest-expanding service category as cities replace underperforming fixed routes with zone-based flexible alternatives. GPS Tracking and Automated Dispatch technologies lead margin pools because they reduce per-trip operational costs through dynamic vehicle repositioning and batching of proximate requests. Data Analytics capabilities differentiate mature platforms from basic dispatch tools by enabling demand prediction and service optimization.
The Federal Transit Administration (FTA) shapes US market access through competitive grant programs that fund DRT conversions of fixed-route services. The EU Green Deal and associated national climate plans mandate emissions reductions that favor electric DRT fleets over diesel paratransit vehicles. Stakeholders must monitor how evolving accessibility regulations from the Department of Transportation and European standards bodies redefine minimum service levels for disabled users across digital booking platforms.
Market Dynamics
Fleet electrification mandates under the EU Green Deal are compressing diesel vehicle replacement timelines and forcing capital reallocation toward battery-electric DRT platforms across European municipal procurement cycles.
Growth Catalysts
- EU Green Deal emissions targets:National climate plans in Germany, France, and the Netherlands mandate urban transport decarbonization, accelerating electric DRT fleet conversions and opening subsidy windows for algorithmic dispatch platforms.
- First-mile/last-mile connectivity gaps:Suburban sprawl patterns in mid-sized cities create structural demand for zone-based flexible services that replace underperforming fixed-route bus coverage with dynamic routing.
- GPS Tracking and Automated Dispatch:Real-time vehicle positioning and batching algorithms reduce per-trip operational costs through dynamic repositioning and proximate request clustering.
Market Restraints
- Vehicle supply concentration:Battery-electric van and minibus production concentrates among a limited set of European OEMs, creating procurement bottlenecks for fleet operators scaling DRT deployments.
- Lithium-ion battery cost volatility:Raw material price swings for cathode minerals directly impact total cost of ownership calculations for electric DRT fleets versus retained diesel alternatives.
- Accessibility compliance friction:Evolving Department of Transportation regulations on digital booking platform standards for disabled users create retrofit obligations that delay service launches.
Strategic Opportunities
- Healthcare-paratransit integration:Dialysis centers, rehabilitation facilities, and senior care networks represent underpenetrated demand pools for scheduled DRT services beyond traditional transit agency contracts.
- Eastern European legacy system replacement:Municipalities in Poland, Romania, and Bulgaria operate aging fixed-route infrastructure ripe for zone-based flexible alternatives with multimodal ticketing integration.
- Data Analytics capability differentiation:Demand prediction and service optimization modules enable platform vendors to command premium positioning against basic dispatch-only competitors.
Industry Challenges
- Algorithmic dispatch talent scarcity:Operations research specialists capable of tuning dynamic routing engines for municipal service levels remain concentrated in a handful of technology hubs.
- Legacy transit agency integration complexity:Existing fixed-route scheduling systems and union operating rules create friction for DRT platform deployment requiring real-time operational coordination.
- ADA certification timelines:Wheelchair-accessible vehicle retrofits and driver training compliance extend procurement-to-revenue cycles for paratransit-eligible service tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demand-Responsive Transit (DRT) Market |
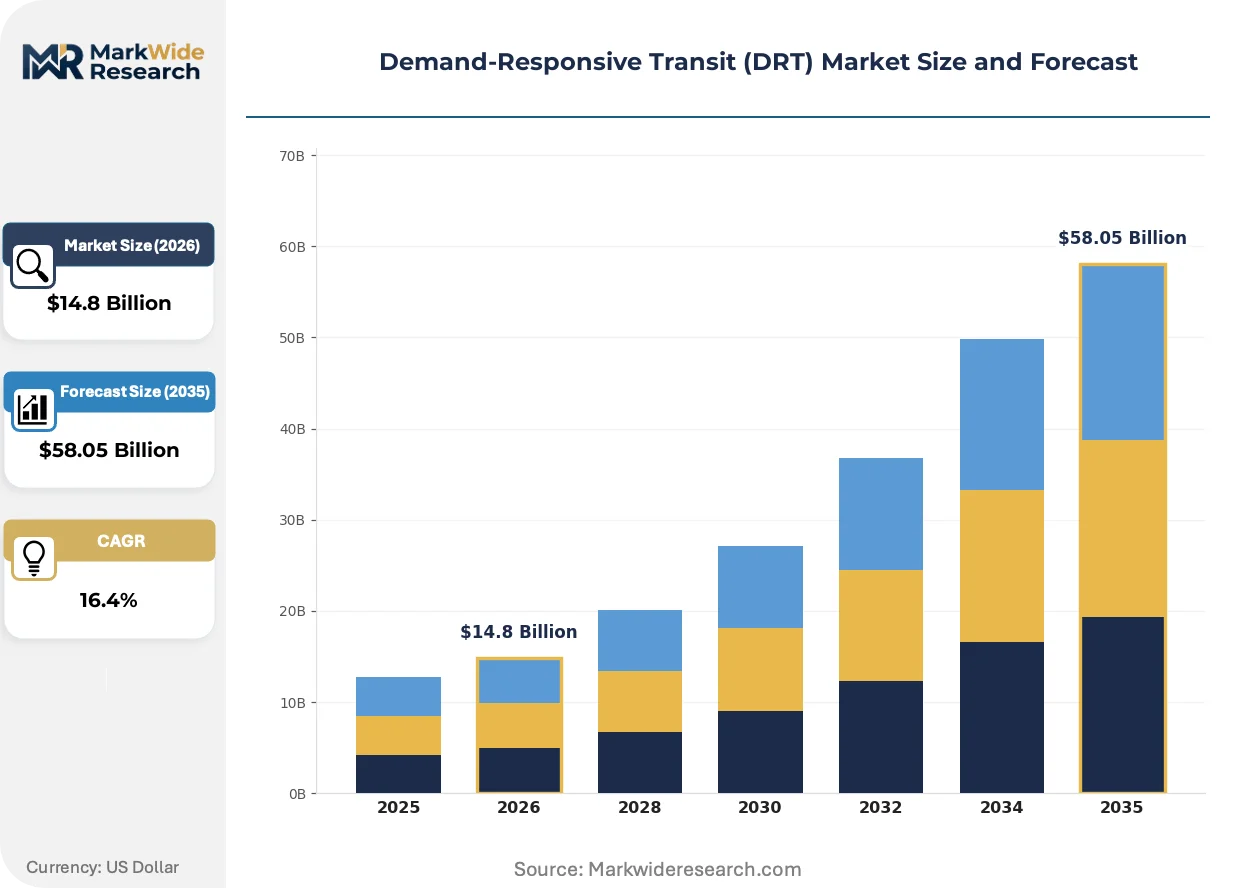
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $58.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microtransit, Vanpool, Carpool, Shuttle Service Technology: Mobile App, GPS Tracking, Automated Dispatch, Data Analytics End User: Public Authorities, Private Operators, Commuters, Disabled Users Application: Urban Mobility, Rural Connectivity, Event Transport, Last-Mile Solutions |
| Companies Covered | Blaise Transit, Transdev North America, Ontra Mobility, MOEV, Edeva, Clever Devices, Swiftly, Xplor, Ridango, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demand-Responsive Transit (DRT) Market Strategic Shifts
Algorithmic dispatch infrastructure is converging with electrified vehicle platforms and multimodal payment systems, creating integrated technology stacks that redefine municipal procurement specifications for flexible transit services.
Dynamic routing engines are converging with real-time traffic data feeds and passenger demand prediction models. Municipal transit agencies in Germany and the Netherlands are deploying these converged platforms to replace fixed-route coverage in low-density corridors. The structural consequence is compressing headways from scheduled 60-minute intervals to sub-15-minute response times without proportional fleet expansion.
The EU Green Deal's F-Gas Regulation and associated national diesel phase-out schedules are mandating electric drivetrain adoption for new DRT procurements. This regulatory pressure is redirecting capital expenditure away from internal combustion engine vehicles and toward battery-electric platforms with depot charging infrastructure. French and Dutch operators are responding fastest, with German agencies trailing due to federal-state funding coordination delays.
Municipal procurement patterns are fragmenting from single-vendor turnkey contracts toward modular platform licensing with separate vehicle and operations procurement. Transit agencies in France and the Netherlands are unbundling software subscriptions from fleet provision, enabling mixed-supplier ecosystems. This shift is most visible in mid-sized cities where in-house data capabilities support direct algorithmic platform management rather than outsourced operations.
Demand-Responsive Transit (DRT) Market Segmentation
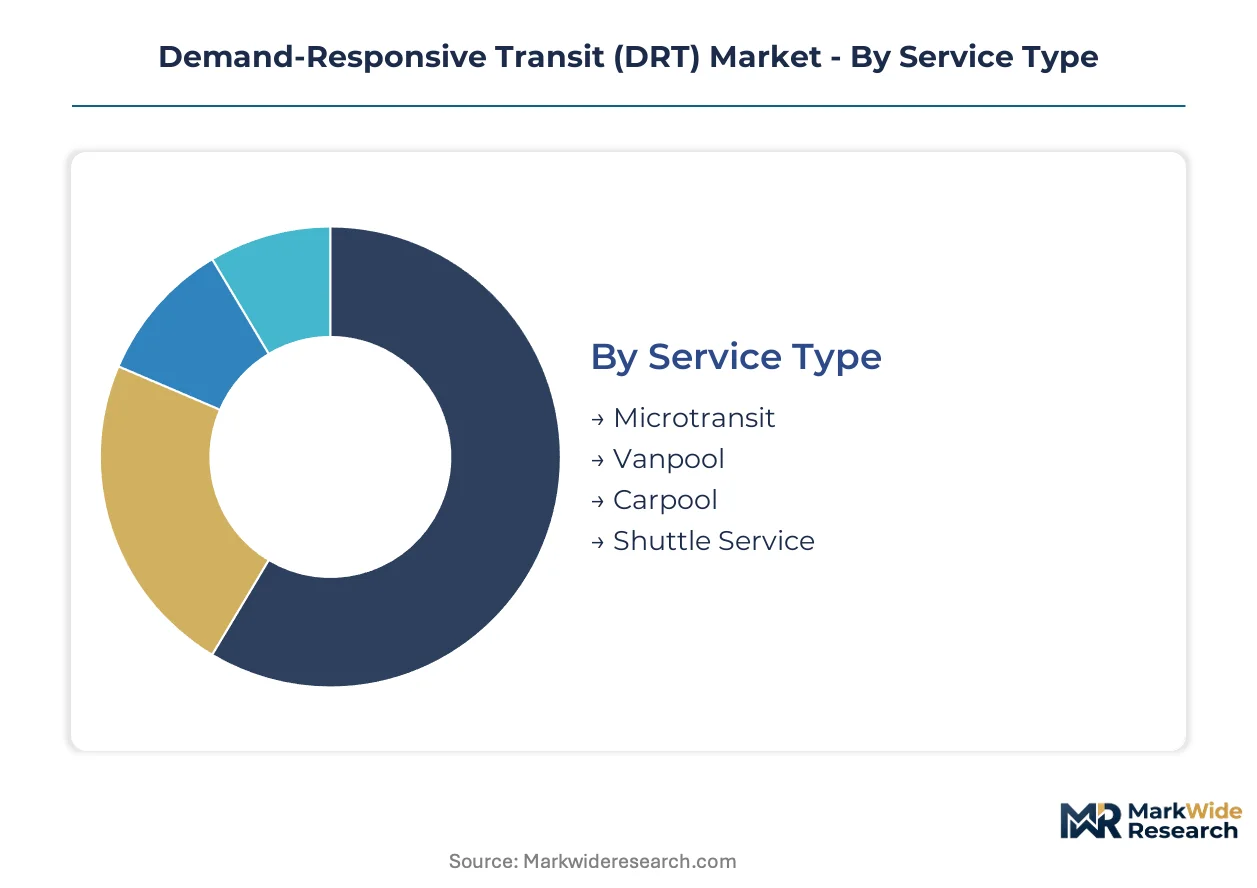
DRT platforms deploy distinct service configurations and technology stacks to match vehicle supply against heterogeneous demand patterns across urban, suburban, and rural geographies. Segmentation reveals how procurement specifications diverge between municipal agencies optimizing for coverage density and private operators prioritizing asset utilization rates.
Service Type:
Technology specifications determine fleet composition and routing flexibility across service configurations.
- Microtransit:Zone-based flexible services operating 8-15 seat vehicles on dynamic routes without fixed schedules. Municipal agencies in Germany and the Netherlands deploy microtransit to replace underperforming fixed-route coverage in low-density corridors, compressing response times from 60-minute headways to sub-15-minute intervals.
- Vanpool:Pre-arranged shared rides serving consistent commuter cohorts along recurring origin-destination pairs. Employer-sponsored programs in France concentrate demand during peak hours, reducing per-seat operational costs through guaranteed ridership pools.
- Carpool:Peer-matched ride sharing utilizing private vehicles with algorithmic passenger pairing. Real-time matching engines in the Netherlands integrate with employer commute benefit platforms.
- Shuttle Service:Scheduled circuits connecting specific nodes such as airports, campuses, or medical complexes. Dialysis centers and rehabilitation facilities in Germany anchor recurring demand for wheelchair-accessible shuttle tiers.
Microtransit leads on scale; vanpool leads on momentum.
Technology:
Platform architecture layers determine operational efficiency thresholds and capital deployment requirements.
- Mobile App:Passenger-facing booking interfaces with real-time vehicle tracking and payment integration. Polish and Romanian municipalities prioritize multimodal ticketing compatibility to bridge legacy transit system gaps.
- GPS Tracking:Real-time vehicle positioning enabling dynamic fleet repositioning and proximity-based request batching. French operators achieve per-trip cost reductions through automated vehicle redistribution algorithms.
- Automated Dispatch:Algorithmic matching engines connecting passenger requests to optimal vehicle assignments. Operations research talent scarcity in German technology hubs constrains deployment velocity for complex routing optimization.
- Data Analytics:Demand prediction modules and service optimization tools differentiating mature platforms. Dutch transit agencies leverage predictive models to pre-position vehicles ahead of anticipated demand spikes.
GPS Tracking commands the largest installed base; Data Analytics shows the steepest expansion trajectory.
End User:
Procurement authority and accessibility requirements shape platform customization and compliance obligations.
- Public Authorities:Municipal transit agencies issuing competitive tenders for zone-based service coverage. EU Green Deal emissions mandates in France and the Netherlands accelerate electric fleet specifications in public procurement cycles.
- Private Operators:Commercial fleets serving corporate campuses, healthcare networks, or residential developments. Rehabilitation facilities in Germany contract directly for scheduled paratransit tiers beyond traditional agency channels.
- Commuters:Individual riders accessing first-mile and last-mile connectivity to trunk transit networks. Suburban sprawl patterns in mid-sized Dutch cities generate structural demand for flexible alternatives to fixed-route buses.
- Disabled Users:Paratransit-eligible passengers requiring wheelchair-accessible vehicles and trained driver assistance. ADA certification timelines in the US and evolving European accessibility standards extend procurement-to-revenue cycles for compliant service tiers.
Public Authorities concentrate procurement volume; Private Operators are gaining share fastest.
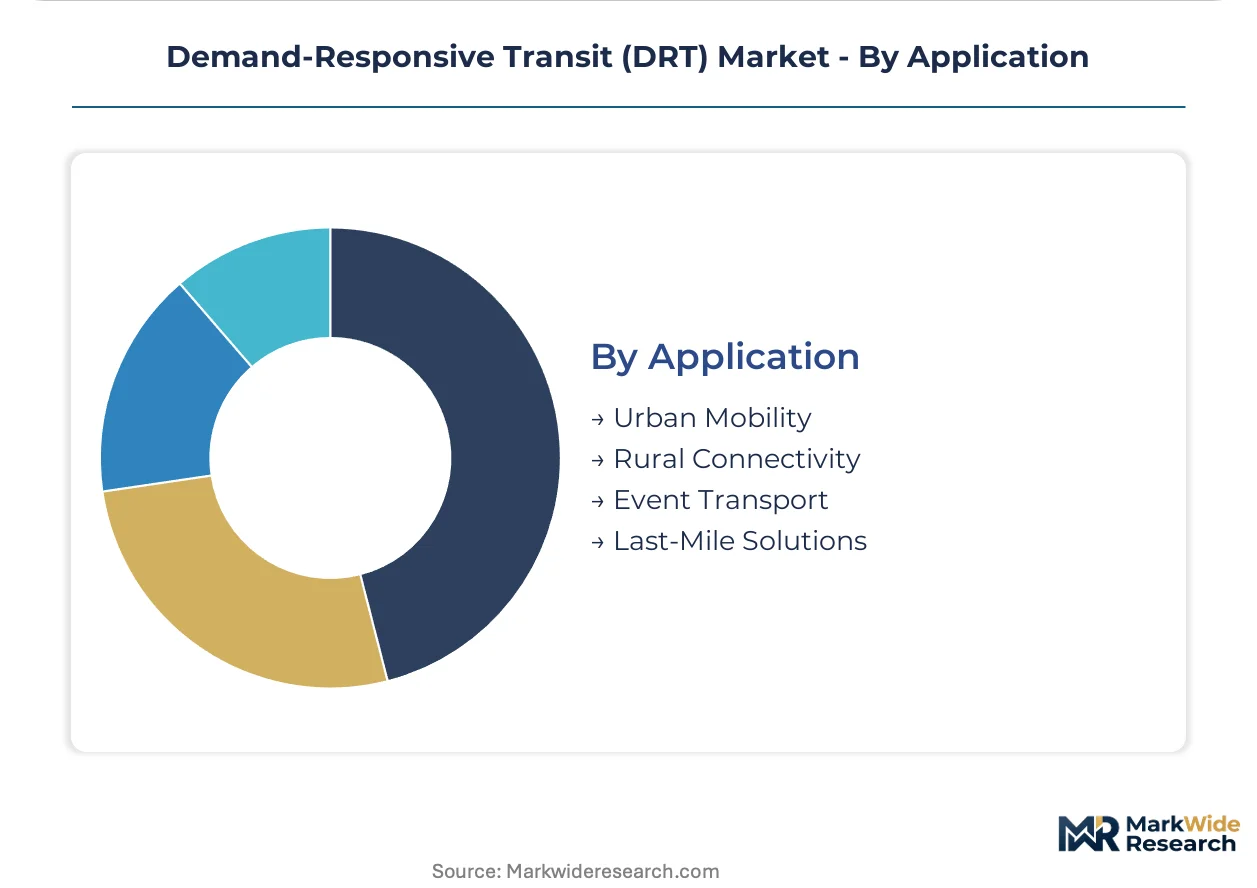
Application:
Use case specificity determines service zone design, fleet sizing, and revenue model selection.
- Urban Mobility:Intra-city flexible transit replacing or complementing fixed-route bus networks. Mid-sized German cities unbundle software subscriptions from fleet provision to enable mixed-supplier ecosystems.
- Rural Connectivity:Sparse-demand services covering dispersed populations without viable fixed-route economics. Bulgarian municipalities operate aging infrastructure ripe for zone-based flexible alternatives.
- Event Transport:Temporary surge capacity for stadiums, festivals, or convention centers. Dynamic routing engines batch proximate requests to minimize deadheading during peak dispersal periods.
- Last-Mile Solutions:Feeder services connecting residential areas to rail stations and trunk transit hubs. The Netherlands leads operational deployments with dense concentrations of multimodal integration points.
Urban Mobility anchors revenue concentration; Last-Mile Solutions demonstrate the most rapid deployment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting DRT platform development toward jurisdictions with aligned subsidy frameworks and accelerated electrification mandates. Capital deployment gravitates toward markets where EU Green Deal compliance costs are offset by national funding programs.
Germany
Federal-state coordination delays have slowed electric fleet conversions relative to neighbors. The KBA enforces stringent vehicle certification timelines that extend procurement cycles for wheelchair-accessible DRT tiers. Munich and Hamburg anchor operational deployments where municipal agencies unbundle software subscriptions from fleet provision.
France
ANSM-aligned accessibility standards and national climate plans mandate urban transport decarbonization. The country's dense concentration of dialysis and rehabilitation facilities generates recurring demand for scheduled paratransit services. Paris and Lyon transit agencies lead procurement of zone-based flexible alternatives to fixed-route coverage.
Netherlands
Randstad municipalities operate the densest concentration of multimodal integration points in Europe. National regulators enforce F-Gas Regulation compliance that accelerates battery-electric fleet specifications. Amsterdam and Rotterdam deploy dynamic routing engines that compress response times from 60-minute headways to sub-15-minute intervals.
United Kingdom
Post-Brexit regulatory divergence creates compliance friction for platforms serving cross-border routes. The Department for Transport oversees evolving digital accessibility standards for disabled users. Greater London and Manchester pilot zone-based services replacing underperforming fixed-route bus coverage in suburban corridors.
Poland
Municipalities operate aging fixed-route infrastructure ripe for algorithmic dispatch platform replacement. National regulators prioritize multimodal ticketing compatibility to bridge legacy transit system gaps. Warsaw and Krakow anchor Eastern Europe's fastest DRT deployment velocity as procurement shifts toward modular platform licensing.
Demand-Responsive Transit (DRT) Market Competitive Environment
Strategic partnership formation dominates the current landscape as vendors seek to bridge capability gaps between software platforms and electrified fleet operations. The vendor base fragments across three tiers: established paratransit operators with agency relationships, pure-play algorithmic dispatch specialists, and multimodal ticketing integrators. Two strategic archetypes have crystallized: vertically integrated operators controlling fleet and software stacks, and asset-light platform licensors enabling mixed-supplier ecosystems. Geographic expansion and technology licensing represent the dominant competitive vectors as vendors seek scale beyond saturated Western European markets.
Among North American service providers, Transdev North America exemplifies the integrated operator archetype through its established paratransit contract base. Swiftly occupies a position among real-time data infrastructure specialists feeding dynamic routing algorithms. Ridango represents the multimodal ticketing tier with penetration into Eastern European markets where legacy system integration creates vendor stickiness.
| Leading Market Players |
|---|
| Blaise Transit |
| Transdev North America |
| Ontra Mobility |
| MOEV |
| Edeva |
| Clever Devices |
| Swiftly |
| Xplor |
| Ridango |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate price volatility cascades through battery-electric DRT procurement cycles, compressing margins for fleet operators while amplifying cost differentials between turnkey platform contracts and unbundled software licensing models.
Pricing Analysis
Direct-to-municipal-agency discounts dominate the channel structure, with software subscription tiers stratifying across premium algorithmic dispatch, standard GPS tracking, and basic fleet management levels. Price differentiation rests on certification grade for wheelchair-accessible vehicle retrofits and integration depth with legacy transit scheduling systems. Cost compression in the mid-tier is intensifying because Polish and Romanian municipalities prioritize multimodal ticketing compatibility over advanced analytics modules. Public transit agencies exhibit the highest price sensitivity due to fixed budget cycles, while private healthcare networks demonstrate lower sensitivity when contracting for scheduled paratransit services.
Supply Chain Analysis
Freight costs for battery-electric chassis from Germany, France, and the Netherlands amplify total landed costs for Eastern European operators lacking localized assembly capacity. The supply chain draws from cathode mineral processing concentrated in China, South Korea, and Indonesia, plus European OEM production of specialized wheelchair-accessible van platforms. Single-source vulnerability persists around lithium-ion cell supply for fleet-scale deployments. Distribution runs through municipal procurement frameworks with extended tender cycles, supplemented by direct contracting for private healthcare facility shuttles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Demand-Responsive Transit market compounds regulatory momentum, with the EU Green Deal's F-Gas Regulation and national diesel phase-out schedules mandating electric fleet conversions that expand the addressable base for algorithmic dispatch platforms.
For Market Incumbents: Cement paratransit contract renewals through accelerated ADA certification investments, countering emerging pure-play algorithmic specialists threatening agency relationships. Deepen backward integration into predictive analytics modules to differentiate against basic dispatch competitors. Prioritize capacity addition in the Netherlands and France where procurement unbundling trends favor mixed-supplier ecosystems. For New Entrants and Emerging Players: Launch via modular platform licensing targeting Bulgarian and Polish municipalities operating aging fixed-route infrastructure ripe for zone-based replacement. White-space concentration sits in Eastern European legacy system replacement and healthcare-paratransit integration for dialysis and rehabilitation networks. Lead with multimodal ticketing compatibility as the primary go-to-market wedge against Western European incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light algorithmic dispatch specialists possessing proven municipal deployments but limited fleet operations scale. Long-term viability favors vendors bridging software platforms with electrified vehicle ecosystems across the next decade's procurement cycles. Watch EU Green Deal subsidy window closures as the inflection signal for capital reallocation toward markets with sustained regulatory support.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unbundled software licensing enables mixed-supplier ecosystems in French and Dutch municipal procurement. |
| Geographic Expansion | Eastern European legacy system replacement offers algorithmic dispatch vendors vendor stickiness through multimodal ticketing. |
| Strategic Partnership | Healthcare network alliances anchor recurring revenue beyond traditional transit agency contract cycles. |
| Acquisition of Specialist Firm | Operations research talent scarcity makes algorithmic routing engine specialists priority targets. |
| Product Launch | Data Analytics modules with demand prediction capabilities command premium positioning against dispatch-only competitors. |
Study Parameters
Multiple input streams — municipal procurement database analysis, fleet operator financial disclosures, and regulatory filing review — were reconciled against primary interviews with transit agency planning officers, paratransit operations directors, platform engineering leads, and healthcare facility logistics managers. Secondary validation drew from EU Green Deal implementation reports, KBA vehicle certification records, ANSM accessibility standards documentation, and national climate plan progress filings. Bottom-up service deployment counts and top-down addressable market sizing were triangulated to establish volume baselines.
Data-stream reconciliation across the modeling period applied service type, technology stack, end-user category, and application use case dimensions. CAGRs were derived from fitted growth curves calibrated against electrification mandate timelines and subsidy program durations. Forecast inputs incorporated battery-electric vehicle cost trajectory assumptions and algorithmic dispatch penetration rates into legacy transit agency procurement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium price spike scenarios or federal-state funding coordination delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Public Transport Smart Card Market