
 Public Transportation Dispatch Software Market | 2026-2036
Public Transportation Dispatch Software Market Size, Share, and Industry Trends Forecast 2026-2036
Public Transportation Dispatch Software Market Insights
Multi-source procurement of dispatch modules is repositioning how transit agencies assemble technology stacks. Optibus leverages AI-native architecture to dominate algorithmic route optimization for large metropolitan operators. GIRO anchors its position in paratransit and demand-responsive scheduling through specialized solver engines. Samsara Networks extends from commercial fleet telemetry into public transit by integrating IoT sensor layers with dispatch dashboards.
Public transportation dispatch software orchestrates vehicle allocation, driver assignment, and passenger-facing information through algorithmic platforms that process real-time GPS feeds, traffic data, and ridership patterns. Cloud-based solutions lead technology adoption due to elastic scaling during peak service hours and reduced capital burden on budget-constrained agencies. AI-driven analytics represents the fastest-expanding technology segment as machine learning models predict demand surges and automate headway adjustments. SaaS deployment dominates among mid-sized transit authorities seeking predictable operational expenditures without dedicated IT infrastructure.
Federal Transit Administration guidelines in the United States mandate accessibility compliance and data interoperability, shaping procurement specifications for dispatch platforms serving ADA-eligible riders. The European Union's F-Gas Regulation and GDPR framework respectively pressure fleet operators toward electric vehicle transition and constrain passenger data handling architectures. Stakeholders must monitor how emerging cybersecurity standards for critical transportation infrastructure reshape vendor qualification requirements and contract renewal criteria.
Market Dynamics
Cloud-native dispatch architectures are compressing procurement cycles as transit agencies abandon on-premise legacy systems for elastic SaaS platforms that scale with ridership volatility.
Growth Catalysts
- EU Green Deal mandates:Municipal operators in Germany and France face binding emissions reduction timelines that require real-time fleet optimization software to electrify bus networks efficiently.
- Demand-responsive transit:Paratransit and microtransit services are expanding in Nordic urban clusters where population density supports algorithmic pooling of passenger trips.
- Edge computing integration:5G-enabled vehicle-to-infrastructure communication is reducing latency for headway adjustments in high-frequency corridor operations.
Market Restraints
- GDPR data localization:Passenger tracking and predictive analytics platforms face architectural constraints that increase compliance engineering costs for cross-border deployments.
- Semiconductor supply concentration:On-board telematics hardware depends on concentrated Asian foundry capacity, creating procurement delays for agencies upgrading legacy vehicle fleets.
- Interoperability standards fragmentation:GTFS-Realtime, SIRI, and proprietary API protocols coexist without unified certification, forcing costly middleware development for multi-vendor environments.
Strategic Opportunities
- India's smart city mission:Tier-2 municipal corporations are procuring integrated transit management systems under centrally funded urban infrastructure programs.
- AI-native predictive maintenance:Convergence of dispatch algorithms with vehicle health monitoring is opening subscription revenue streams beyond pure SaaS licensing.
- Microtransit-rail integration:First-mile/last-mile coordination software represents white space in suburban transit networks where fixed-route coverage is economically unviable.
Industry Challenges
- Legacy system migration complexity:Decades-old CAD/AVL infrastructure in established North American agencies requires phased replacement that disrupts operations during transition windows.
- Specialized workforce scarcity:Transit agencies compete with technology vendors for data scientists capable of tuning machine learning models for irregular demand patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Transportation Dispatch Software Market |
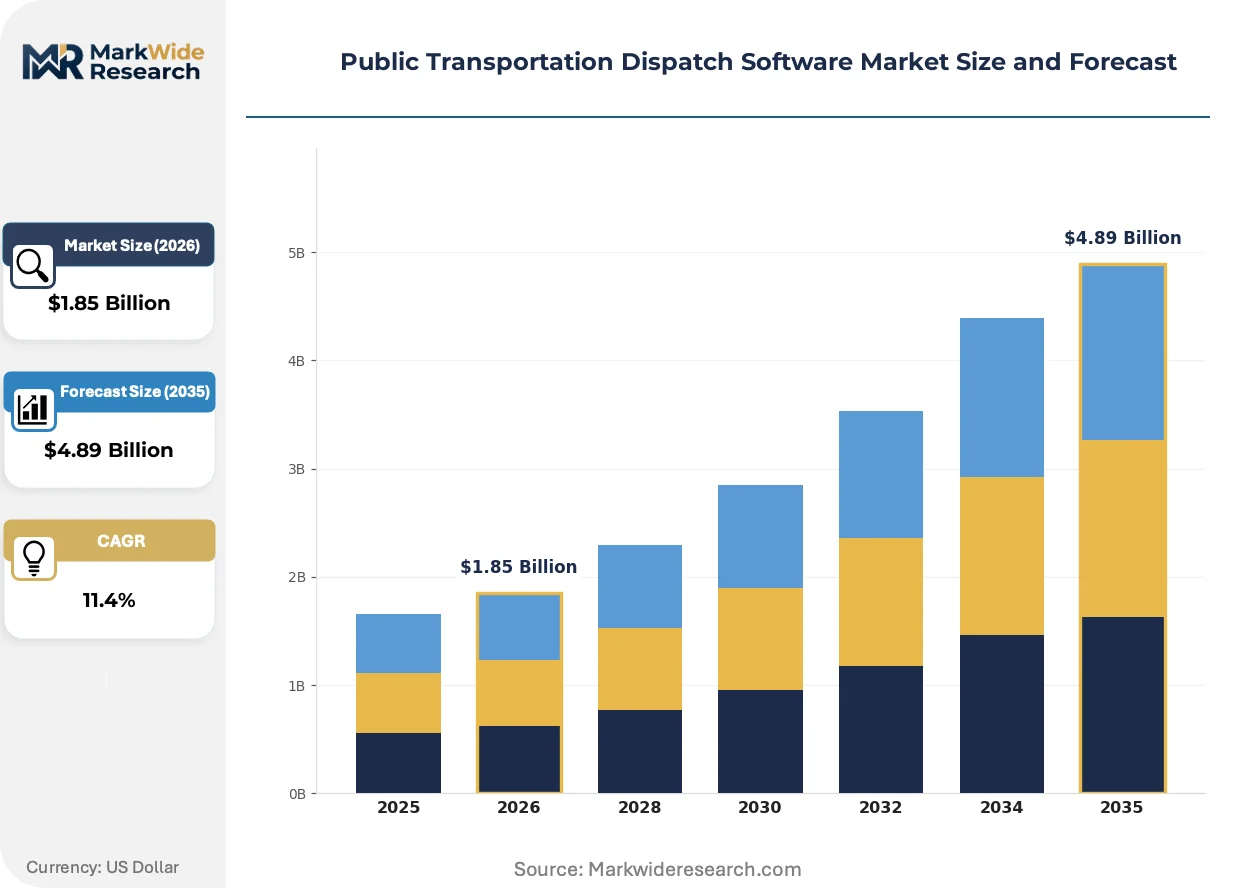
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Route Optimization, Real-Time Tracking, Fleet Management, Customer Communication Technology: Cloud-Based Solutions, Mobile Applications, AI-Driven Analytics, IoT Integration End User: Public Transit Authorities, Private Transport Operators, Rideshare Services, School Transportation Deployment: On-Premises, SaaS, Hybrid Model, Managed Services |
| Companies Covered | Optibus, GIRO, Samsara Networks, Trapeze Group, Verizon Connect, INIT GmbH, GPS Insight, TripSpark Technologies, Goal Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Transportation Dispatch Software Market Trends and Innovations
Algorithmic decision-making is migrating from back-office planning to real-time operational control, compressing the latency between demand signal detection and service adjustment.
Digital twin technology is consolidating around dynamic network simulation platforms that mirror physical transit infrastructure. Metropolitan planning organizations in the Netherlands and Singapore are deploying these systems to stress-test service scenarios before live deployment. The technology is consolidating vendor value propositions from static optimization toward continuous operational intelligence.
The EU AI Act's risk classification framework is imposing documentation and human-oversight requirements on automated dispatch decisions affecting passenger safety. Transit operators deploying autonomous scheduling must maintain algorithmic audit trails that satisfy national market surveillance authorities. European procurement specifications increasingly mandate conformity assessment procedures that extend vendor liability into operational deployment phases.
Subscription-based procurement is displacing perpetual licensing for mid-sized transit authorities seeking to convert capital budgets into operational expenditures. Vendor pricing models are unbundling core dispatch functionality from advanced analytics modules, allowing agencies to scale feature adoption with ridership recovery. This pattern is most pronounced in North American municipal operators recovering from pandemic-induced revenue shortfalls.
Public Transportation Dispatch Software Market Segmentation
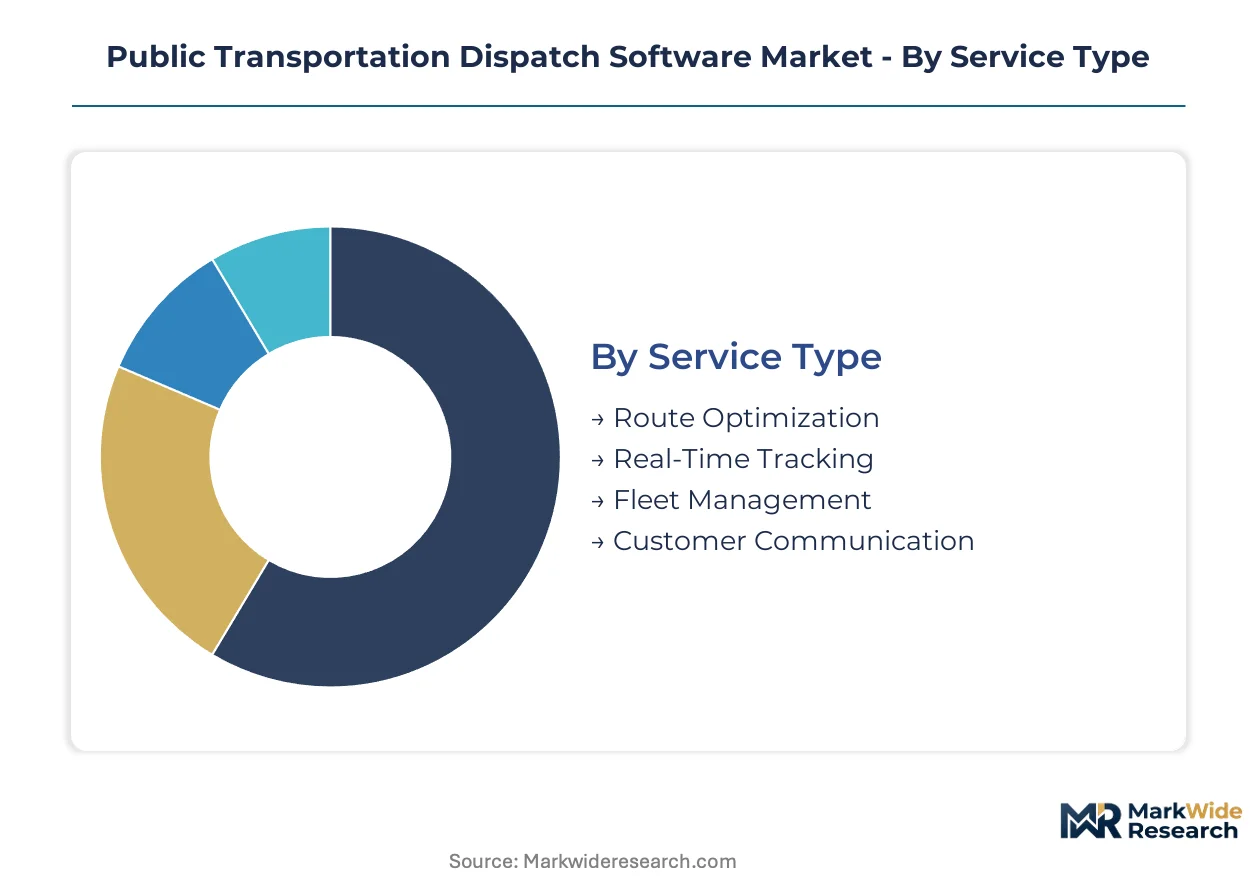
Dispatch software architectures fragment across service layers, technology stacks, and procurement models. Each dimension carries distinct margin profiles and vendor competitive dynamics that reshape how transit agencies assemble operational technology.
Service Type:
Route optimization commands premium pricing while real-time tracking drives volume deployment across mid-sized operators.
- Route Optimization:Algorithmic engines calculate multi-variable pathing across traffic patterns, passenger demand, and vehicle capacity constraints. German municipal operators under KBA emissions mandates deploy these systems to electrify bus networks without service degradation.
- Real-Time Tracking:GPS telemetry fused with predictive arrival algorithms feeds passenger-facing displays and mobile interfaces. Nordic integrated transit networks in Stockholm, Copenhagen, and Helsinki require this capability for multimodal coordination across bus, rail, and ferry services.
- Fleet Management:Vehicle health monitoring, fuel consumption analytics, and maintenance scheduling modules.
- Customer Communication:Automated alerts, service disruption notifications, and accessibility-compliant information delivery systems.
Today's leader: Route Optimization. Tomorrow's challenger: Customer Communication.
Technology:
Cloud infrastructure separates scalable SaaS adopters from capital-constrained agencies while AI capabilities differentiate premium vendor offerings.
- Cloud-Based Solutions:Elastic compute resources scale with ridership volatility during peak hours and special events. Municipal operators in France and the Netherlands favor this model to convert capital expenditures into predictable operational budgets.
- AI-Driven Analytics:Machine learning models predict demand surges, automate headway adjustments, and flag anomalous operational patterns. Singapore's Land Transport Authority deploys these systems for dynamic network simulation before live service changes.
- Mobile Applications:Driver-facing tablets and passenger trip-planning interfaces extending core dispatch functionality.
- IoT Integration:Sensor networks capturing vehicle telemetry, passenger counting, and environmental conditions for operational intelligence.
Cloud-Based Solutions anchor current procurement. AI-Driven Analytics claims the steepest expansion trajectory as EU AI Act compliance requirements reshape vendor qualification.
End User:
Public transit authorities concentrate procurement volume while private operators drive feature velocity through competitive pressure.
- Public Transit Authorities:Municipal and regional agencies operating fixed-route bus, rail, and ferry services under federal accessibility mandates. US operators face FTA guidelines requiring ADA-compliant dispatch platforms with documented interoperability standards.
- Rideshare Services:Algorithmic pooling platforms matching dispersed demand with dynamic vehicle supply. Microtransit operators in suburban US markets and European urban peripheries deploy these systems where fixed-route coverage is economically unviable.
- Private Transport Operators:Contracted shuttle services, airport ground transportation, and corporate commuter programs.
- School Transportation:Specialized routing for student pickup logistics with enhanced safety monitoring and parent notification requirements.
Public Transit Authorities dominate contract value. Rideshare Services expand most quickly as demand-responsive transit reshapes suburban mobility.
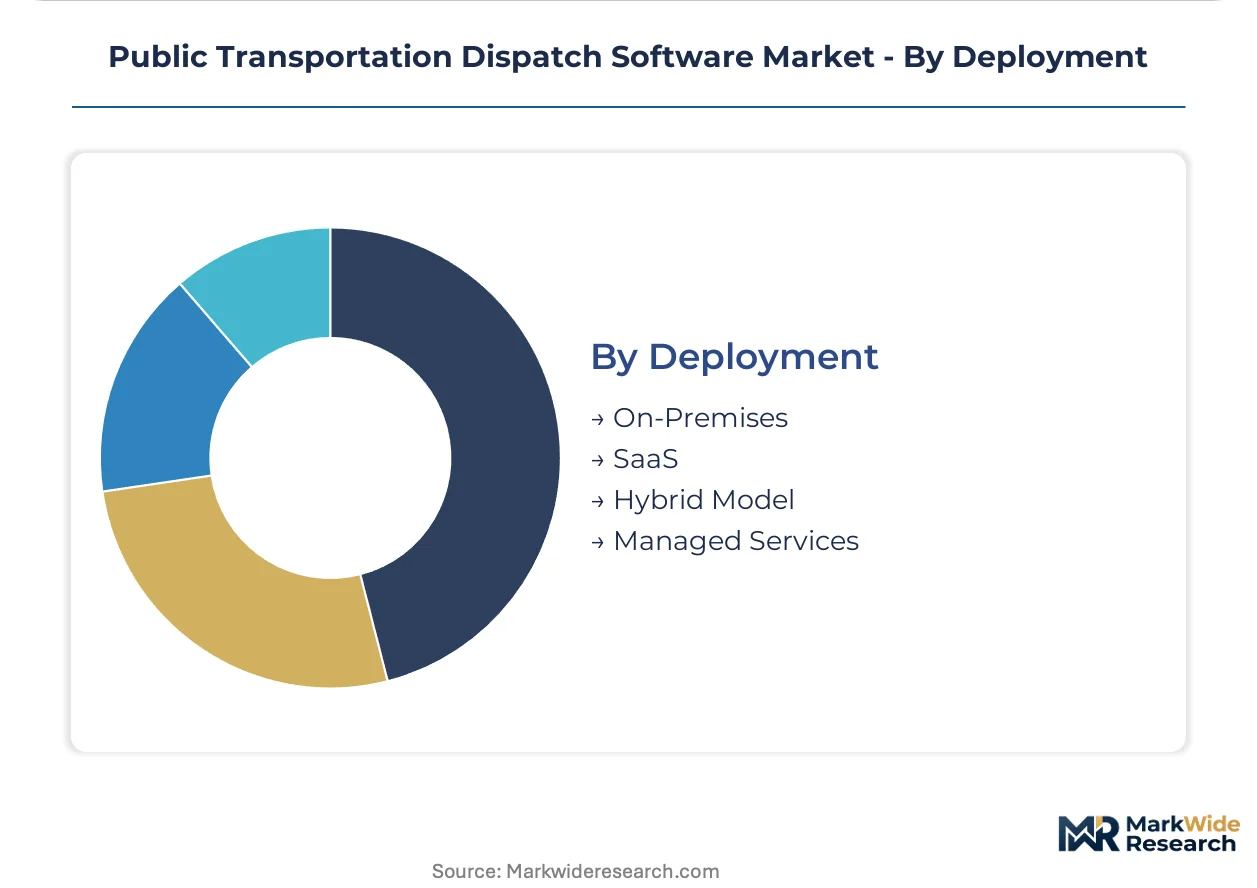
Deployment:
SaaS subscriptions displace perpetual licenses as agencies prioritize operational expenditure flexibility over capital ownership.
- SaaS:Multi-tenant cloud platforms with monthly or annual subscription pricing, automatic updates, and vendor-managed infrastructure. North American municipal operators recovering from pandemic revenue shortfalls favor this model to preserve liquidity.
- Hybrid Model:Critical dispatch functions remain on-premises for latency-sensitive operations while analytics and passenger-facing services migrate to cloud tiers. German operators deploy this architecture to satisfy GDPR data localization requirements for passenger tracking.
- On-Premises:Agency-owned servers and dedicated infrastructure for maximum operational control and cybersecurity isolation.
- Managed Services:Vendor-operated infrastructure with dedicated operational support staff embedded at agency sites.
SaaS captures mainstream adoption. Hybrid Model gains share fastest as cybersecurity standards for critical transportation infrastructure tighten vendor liability frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal transit networks anchor procurement momentum as KBA emissions mandates compress deployment timelines for electrified fleet management platforms.
United States
FTA accessibility guidelines and pandemic revenue recovery shape procurement specifications for mid-sized municipal operators. Federal mandates require ADA-compliant dispatch architectures with documented interoperability standards. Metropolitan planning organizations in Greater Boston and the Pacific Northwest deploy cloud-native platforms to convert capital budgets into operational expenditures.
Germany
KBA emissions enforcement and EU Green Deal binding targets accelerate cloud-based dispatch adoption across municipal bus agencies. GDPR data localization requirements push hybrid deployment models with on-premises passenger tracking and cloud-tier analytics. The Rhine-Ruhr metropolitan cluster leads vehicle-to-infrastructure integration trials for real-time headway optimization.
France
Centrally funded urban infrastructure programs channel procurement toward integrated transit management systems in tier-2 municipal corporations. ANSM oversight of automated decision systems intersects with EU AI Act risk classification for dispatch algorithms. The Île-de-France region deploys dynamic network simulation platforms for multimodal coordination across bus and rail services.
Singapore
Land Transport Authority investments in digital twin technology drive demand for predictive analytics and autonomous scheduling capabilities. The national smart city framework mandates edge computing integration for 5G-enabled vehicle-to-infrastructure communication. The city-state's dense urban core serves as a testbed for algorithmic pooling in demand-responsive microtransit services.
India
Smart city mission funding concentrates procurement volume in tier-2 municipal corporations seeking integrated transit management systems. BIS standards for intelligent transportation systems shape vendor qualification requirements for domestic deployments. The Delhi-NCR and Maharashtra state clusters lead real-time tracking adoption for multimodal bus and metro coordination.
Public Transportation Dispatch Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native architecture and edge computing integration as differentiation vectors. The vendor landscape organizes around three strategic archetypes: algorithmic optimization specialists, paratransit scheduling incumbents, and commercial fleet telemetry extenders. Consolidation pressure intensifies as transit agencies prioritize multi-source procurement of modular dispatch components. Dominant competitive moves include strategic partnerships for IoT sensor integration and portfolio diversification into predictive maintenance subscriptions.
Within the AI-native tier, Optibus exemplifies algorithmic route optimization positioning for large metropolitan operators. GIRO anchors the specialized scheduling segment through demand-responsive and paratransit solver engines. Samsara Networks represents the telemetry extension archetype, integrating commercial fleet IoT layers with public transit dispatch dashboards. These three firms collectively illustrate how vendor qualification increasingly hinges on compliance engineering for EU AI Act documentation requirements and GDPR data localization constraints.
| Leading Market Players |
|---|
| Optibus |
| GIRO |
| Samsara Networks |
| Trapeze Group |
| Verizon Connect |
| INIT GmbH |
| GPS Insight |
| TripSpark Technologies |
| Goal Systems |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal procurement mandates for electrified fleet management are forcing municipal transit agencies toward SaaS subscription models, compressing vendor margins while shifting cost structures from capital expenditure to operational scaling fees.
Pricing Analysis
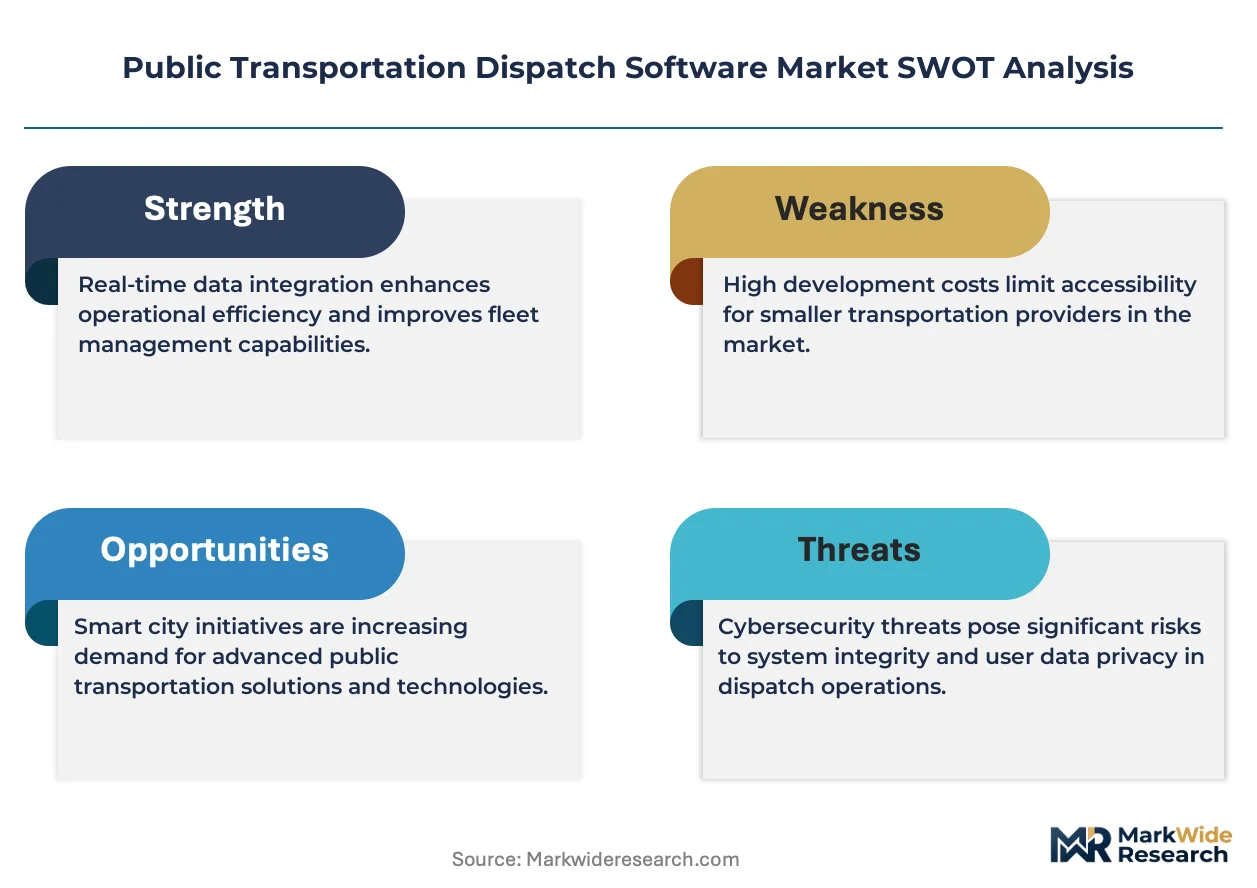
Input-cost pass-through from cloud infrastructure providers and specialized AI engineering talent is reshaping vendor pricing architectures. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in algorithmic sophistication and GDPR compliance certification tier. Pricing pressure stems from mid-sized municipal operators recovering from pandemic revenue shortfalls and demanding modular unbundling. Public transit authorities exhibit highest price sensitivity due to fixed budget appropriations, while rideshare microtransit operators accept premium tiers for demand-responsive capabilities.
Supply Chain Analysis
Regional distribution centers for on-board telematics hardware concentrate in Taiwan, South Korea, and China, creating hub-and-spoke fulfillment patterns for North American and European deployments. Software supply draws from cloud infrastructure concentrated in the United States, Germany, and Singapore, with edge computing components sourced from Japanese and Taiwanese semiconductor fabricators. Single-source vulnerability in Asian foundry capacity for GPS telemetry modules poses structural risk. Distribution runs through vendor-managed SaaS platforms with embedded operational support, displacing traditional licensed software resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act conformity assessment requirements and FTA accessibility mandates continuously reshape procurement specifications and vendor qualification barriers.
For Market Incumbents: Anticipate margin compression from AI-native entrants by deepening algorithmic audit trail capabilities for EU AI Act documentation requirements. Fortify position through backward integration into IoT sensor hardware to reduce telematics procurement delays. Prioritize certification investment for GDPR-compliant hybrid deployment architectures as German operators accelerate adoption.
For New Entrants and Emerging Players: Begin with white-space targeting of India's tier-2 municipal corporations under centrally funded smart city infrastructure programs. Microtransit-rail integration software for suburban first-mile/last-mile coordination represents the most penetrable segment. Pursue channel partnerships with established commercial fleet telemetry providers to accelerate transit agency credibility.
For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native optimization specialists possessing documented EU AI Act compliance engineering capabilities. Long-term viability favors vendors with subscription revenue models extending beyond pure SaaS licensing into predictive maintenance and vehicle health monitoring. Monitor procurement specification shifts toward cybersecurity standards for critical transportation infrastructure as the inflection indicator for vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates dispatch, telemetry, and passenger-facing services into unified operational dashboards for Nordic multimodal networks. |
| Strategic Partnership | IoT sensor alliances with commercial fleet providers accelerate hardware deployment timelines for municipal electrification mandates. |
| Acquisition of Specialist Firm | Demand-responsive scheduling engines address paratransit white space in suburban North American markets. |
| Geographic Expansion | India's smart city mission channels procurement toward integrated transit management in tier-2 municipal corporations. |
| Product Launch | Digital twin simulation platforms enable stress-testing of service scenarios before live deployment in Dutch metropolitan regions. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with transit agency CTOs, municipal procurement officers, platform integration specialists, and vendor solution architects alongside secondary validation. Primary fieldwork drew from FTA guideline documentation, EU Green Deal implementation reports, KBA emissions enforcement records, and smart city mission procurement databases. Secondary sources included SEC filings from listed fleet technology providers, BIS intelligent transportation system standards, and Singapore Land Transport Authority investment disclosures. Bottom-up ridership volume modeling and top-down technology spend estimates were triangulated against vendor-reported contract values.
Rate-of-change decomposition across the analysis window separated baseline fleet replacement cycles from incremental software attach rates and regulatory-driven acceleration effects. Segmentation dimensions modeled include deployment architecture, agency size tier, service type complexity, regional regulatory cluster, and integration maturity. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and stress-tested against electrification timeline commitments. Industry-specific forecast inputs incorporated EU AI Act implementation schedules and FTA accessibility compliance deadlines.
Several conditions sit outside the modeled scope, including sovereign debt crises affecting municipal capital budgets, semiconductor supply disruptions beyond modeled lead times, and cybersecurity incidents triggering procurement freezes. Forecasts reflect documented assumptions regarding ridership recovery trajectories and cloud infrastructure cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Mass Transit Signage Market