
 Passenger Service System Market | 2026-2036
Passenger Service System Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Service System Market Intelligence
Software-defined ancillary merchandising is decoupling passenger service system value from traditional GDS bundles. Amadeus IT Group SA leverages its global distribution footprint to sustain platform dominance across legacy and NDC-enabled environments. Sabre Corporation anchors its competitive stance through specialized retailing analytics for hybrid carrier models. TravelSky Technology Limited dominates the domestic Chinese market with government-backed infrastructure control.
A passenger service system constitutes an integrated software platform managing airline reservations, inventory control, departure control, and ancillary revenue functions through real-time transaction processing with sub-second response requirements. These systems orchestrate passenger-facing operations from booking through boarding, enabling airlines to monetize seats, baggage, and services across direct and indirect channels. Cloud-based deployment leads structural transformation as carriers retire mainframe dependencies, while SaaS models capture fastest expansion by lowering capital barriers for low-cost carriers. Ticketing and loyalty management concentrate margin pools where airlines seek direct channel ownership and personalized retailing.
FAA certification requirements for operational software govern US airline system deployments, while EASA's digital operational resilience standards shape European procurement criteria. China's MIIT imposes data localization mandates on aviation technology vendors serving domestic carriers. India's DGCA mandates passenger service data interoperability for international route approvals. Stakeholders must weigh regulatory fragmentation against platform consolidation as NDC standards mature and sovereign data rules proliferate.
Market Dynamics
Cloud-native platform migration is fragmenting the passenger service system value chain as full-service carriers dismantle decades-old mainframe dependencies and reassemble operations around microservices architectures.
Growth Catalysts
- IATA NDC standards:Airlines in India, China, and Singapore are adopting these retailing protocols to bypass traditional distribution economics and capture direct channel revenue.
- Low-cost carrier SaaS adoption:Subscription deployment models are eliminating capital barriers for emerging airlines across Southeast Asian markets.
- Ancillary merchandising modules:Software-defined unbundling of seats, baggage, and services is creating new revenue streams independent of base fares.
Market Restraints
- Data localization mandates:China's MIIT requirements force vendors to maintain domestic infrastructure, raising operational complexity for foreign platform providers.
- Legacy system technical debt:Decades of mainframe customization create integration friction that slows cloud migration timelines for established carriers.
- FAA certification timelines:Operational software approval processes for US airlines extend deployment cycles and compress vendor margins.
Strategic Opportunities
- India DGCA interoperability mandates:International route approval requirements are creating compliant-system demand among carriers expanding beyond domestic networks.
- Hybrid carrier retailing analytics:Convergence of passenger service data with revenue management systems is opening analytics service adjacencies.
- Direct channel ownership:Airlines are building proprietary booking interfaces that bypass traditional global distribution system economics.
Industry Challenges
- Real-time transaction engineering:Sub-second response requirements for reservation and inventory systems demand scarce distributed systems expertise.
- Multi-cloud orchestration complexity:Carriers operating across regulatory jurisdictions face fragmented deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Service System Market |
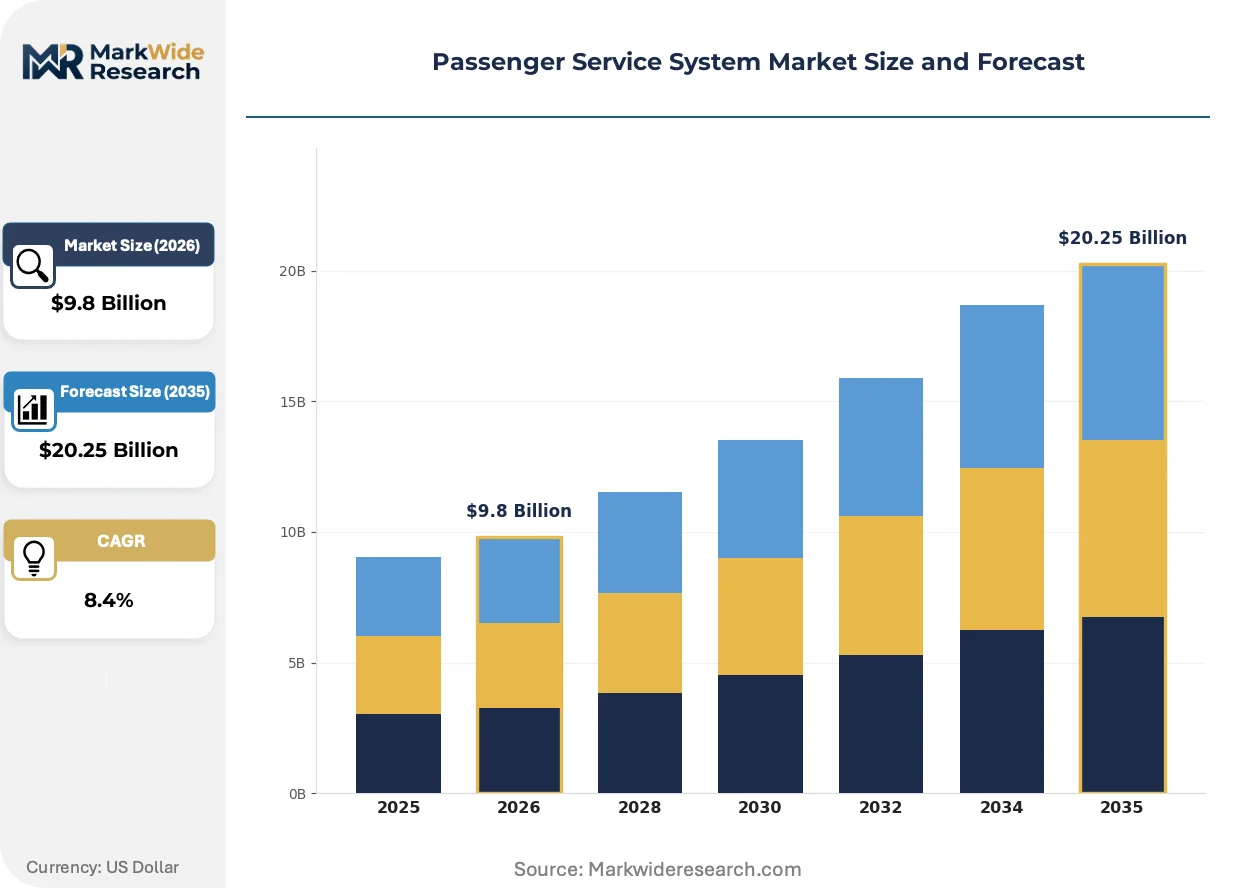
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Check-In, Ticketing, Boarding, Loyalty Management Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Airlines, Travel Agencies, Airports, Ground Handlers Solution: Mobile App, Kiosk Interface, Web Portal, Self-Service |
| Companies Covered | Amadeus IT Group SA, Sabre Corporation, SITA NV, TravelSky Technology Limited, Hitit Computer Services, Bravo Passenger Solutions Pte Limited, Lufthansa Systems GmbH & Co. KG, IBS Software Private Limited, Radixx International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Service System Market Strategic Shifts & Innovations
Platform unification is compressing the boundary between passenger-facing operations and back-office revenue management, eroding the traditional segmentation between reservation, departure control, and merchandising functions.
API-first architecture is unifying previously siloed airline operations into composable service layers. Full-service carriers in Singapore and Australia are deploying these interfaces to enable real-time inventory synchronization across direct and indirect sales channels. This unification is collapsing the historical separation between reservation management and dynamic pricing engines.
EASA digital operational resilience standards are reshaping European procurement criteria for aviation software vendors. Airlines must now demonstrate system continuity capabilities that exceed traditional availability metrics. Low-cost carriers based in Ireland and Spain are accelerating compliance investments ahead of enforcement timelines.
Buyer concentration among mega-carriers is forcing platform vendors toward outcome-based commercial structures. Subscription pricing tied to passenger volumes is displacing perpetual license models in negotiations with Southeast Asian airline groups. This shift is most visible in Malaysia and Thailand where carrier consolidation has reduced the addressable customer base.
Passenger Service System Market Segmentation
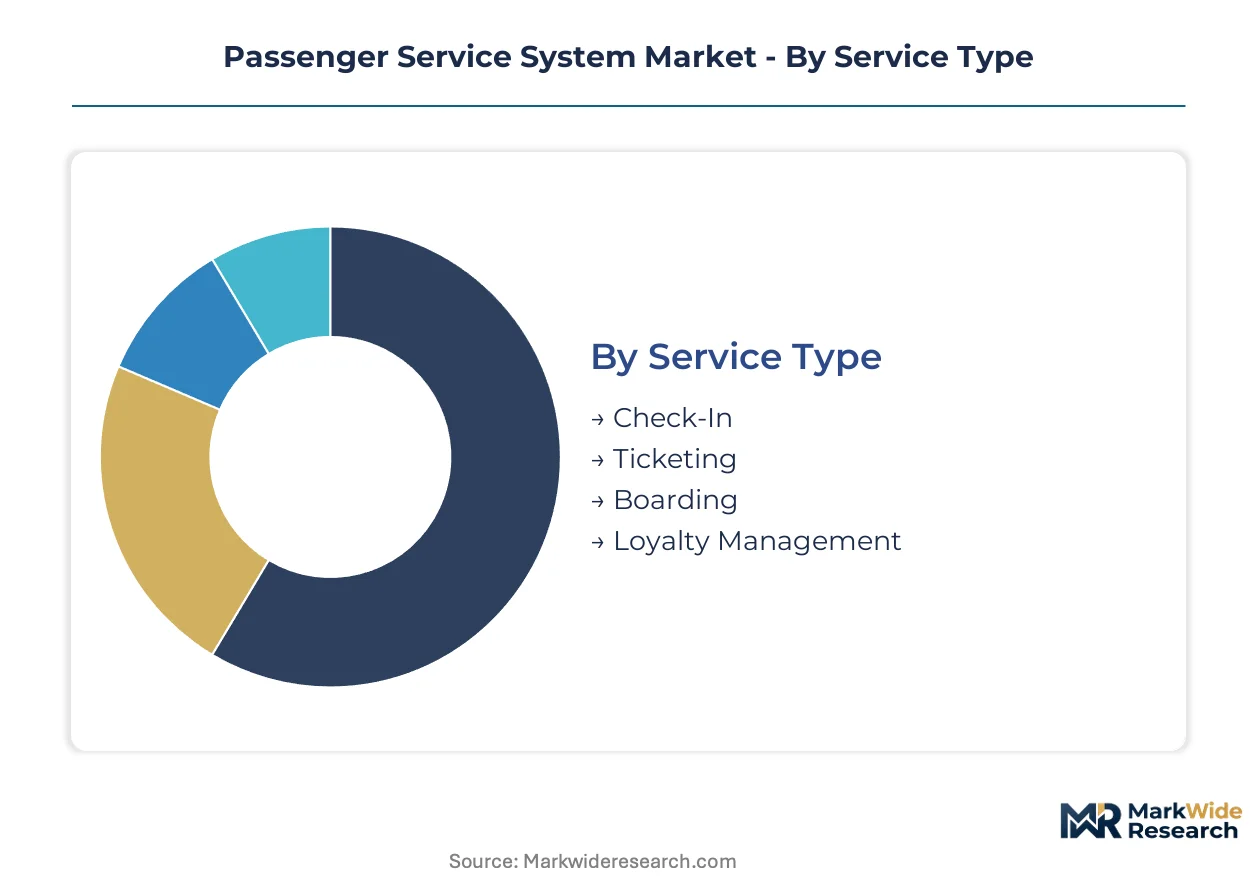
Passenger service system purchasing varies sharply by operational complexity and capital constraints. Airlines prioritize real-time transaction reliability while airports demand multi-tenant interoperability. Deployment choices reflect divergent risk appetites across carrier maturity levels.
Service Type:
Carriers segment their procurement by which passenger touchpoint drives the highest ancillary capture rate.
- Ticketing:Core reservation engines process millions of daily transactions with sub-second latency requirements. Full-service carriers in India and Singapore are modernizing these systems first to enable NDC-compliant direct retailing.
- Loyalty Management:Frequent flyer platforms integrate payment card partnerships and coalition networks. Chinese airlines leverage these modules to monetize member data through cross-industry partnerships with domestic e-commerce platforms.
- Check-In:Biometric-enabled verification systems reduce counter staffing costs for low-cost carriers.
- Boarding:Gate management tools synchronize with aircraft turnaround scheduling to minimize tarmac delays.
Ticketing leads volumes today; loyalty management is gaining share fastest.
Deployment:
Technical debt tolerance distinguishes buyers in this category between legacy operators and digital-native entrants.
- Cloud-Based:Microservices architectures eliminate mainframe dependencies and enable elastic capacity scaling. Southeast Asian low-cost carriers adopt these platforms to avoid data center capital expenditure.
- SaaS:Subscription pricing aligns vendor revenue with passenger throughput, reducing bankruptcy risk for emerging airlines. Indian regional carriers favor this model for rapid route expansion without infrastructure commitment.
- Hybrid:Split deployments retain sensitive passenger data on-premise while pushing merchandising to public cloud.
- On-Premise:Dedicated infrastructure persists among carriers with stringent sovereignty requirements or customized legacy codebases.
On-premise retains installed base dominance; SaaS is climbing the fastest.
End User:
Procurement authority fragmentation creates divergent platform requirements across the aviation value chain.
- Airlines:Full control over passenger data and retailing economics drives direct system ownership. Flag carriers in China and Singapore operate captive technology subsidiaries to maintain platform autonomy.
- Airports:Common-use terminal equipment demands multi-carrier interoperability and shared infrastructure cost models. Major hubs in India mandate standardized interfaces for all operating carriers.
- Travel Agencies:Consolidator platforms require aggregated inventory access across multiple airline systems.
- Ground Handlers:Turnaround coordination tools synchronize passenger processing with baggage and fueling operations.
Airlines command the largest absolute spend; airports represent the steepest expansion trajectory.
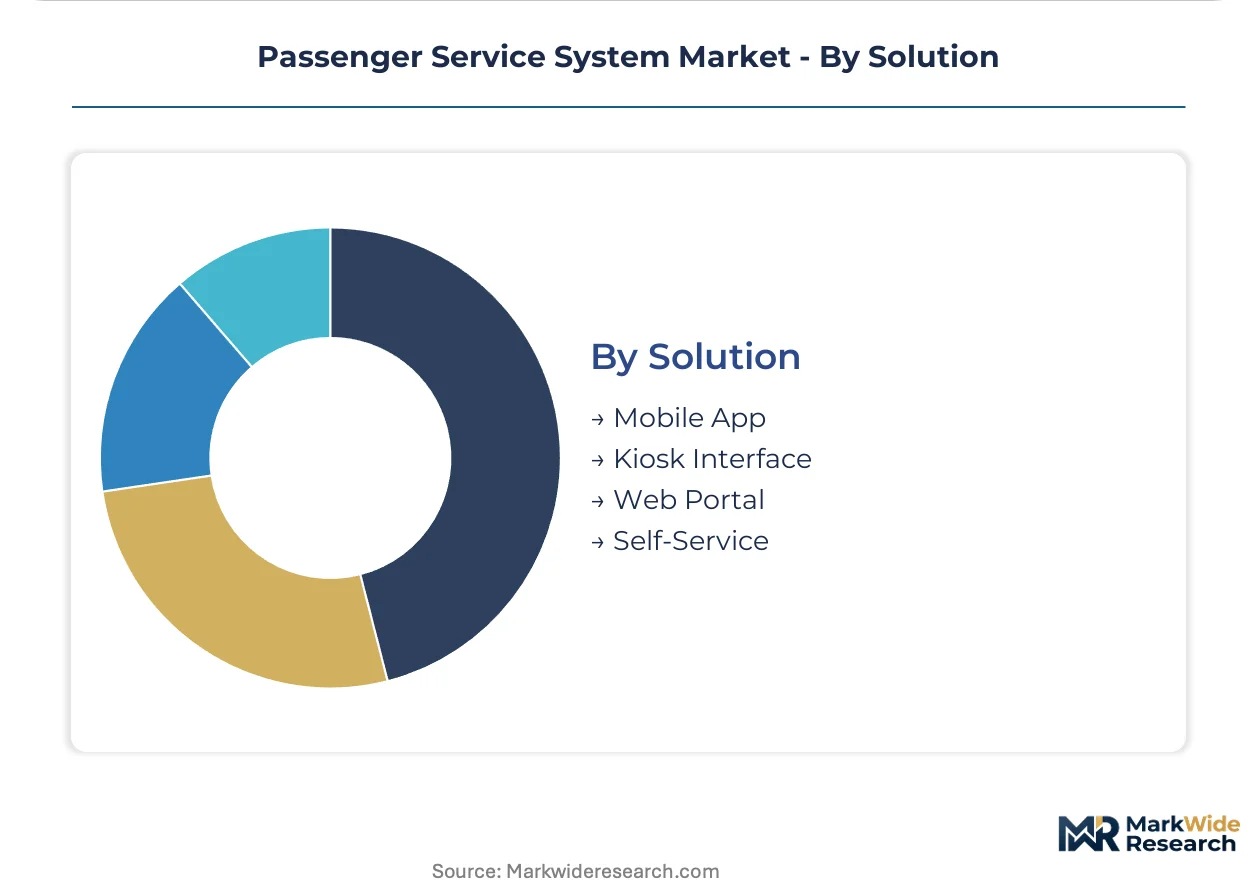
Solution:
Channel ownership strategy determines whether carriers invest in proprietary interfaces or shared infrastructure.
- Mobile App:Native smartphone applications capture direct booking traffic and push ancillary offers during journey planning. Chinese carriers integrate super-app payment wallets to reduce booking friction.
- Self-Service:Automated check-in and rebooking systems minimize contact center costs. Low-cost carriers in Thailand deploy these tools to maintain operational margins on thin base fares.
- Web Portal:Browser-based booking remains essential for corporate travel management integration.
- Kiosk Interface:Airport hardware terminals serve passengers without smartphone access or requiring document verification.
Mobile app leads transaction volumes today; self-service is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing passenger service system procurement as carriers migrate toward jurisdictions with streamlined aviation software certification. Cost-of-compliance gaps between legacy aviation authorities and emerging digital-first regulators are accelerating platform vendor relocation and partnership strategies.
United States
Full-service carriers dominate procurement volumes as they modernize reservation infrastructure for NDC retailing. FAA certification requirements for operational software extend deployment timelines and compress vendor margins. Dallas-Fort Worth and Atlanta hubs concentrate legacy system migration projects among major network airlines.
China
State-backed aviation expansion drives captive technology development through government-controlled platform providers. MIIT data localization mandates force foreign vendors to maintain domestic infrastructure, raising operational complexity. Beijing and Shanghai aviation clusters prioritize proprietary systems for flag carrier digital transformation.
India
Rapid low-cost carrier expansion fuels SaaS adoption as regional airlines avoid data center capital expenditure. DGCA passenger service data interoperability mandates for international route approvals create compliant-system demand. Mumbai and Delhi aviation corridors concentrate hybrid cloud deployments among emerging carriers.
Singapore
Hub carrier consolidation amplifies bargaining power in platform vendor negotiations. IATA NDC standards adoption accelerates direct channel retailing investments. Changi Airport's common-use infrastructure mandates shape multi-tenant interoperability requirements for ground handling technology providers.
Germany
EASA digital operational resilience standards reshape procurement criteria for aviation software vendors. Lufthansa Group's technology subsidiary anchors captive platform development for Star Alliance carriers. Munich and Frankfurt aviation clusters concentrate compliance investments ahead of enforcement timelines.
Passenger Service System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding premium positioning in full-service carrier procurement while modular SaaS providers capture low-cost carrier expansion. Market structure tilts toward oligopoly at the enterprise tier, with three dominant players controlling legacy migration and NDC-enabled environments. Strategic archetypes include captive airline technology subsidiaries, government-backed national champions, and independent software vendors with aviation-specific expertise. Competitive moves center on cloud-native platform development and outcome-based commercial structures tied to passenger throughput.
Among Europe-based platform providers, Amadeus IT Group SA and Lufthansa Systems GmbH & Co. KG occupy positions within the integrated enterprise tier, representing contrasting approaches to airline technology ownership—one as an independent vendor, the other as a captive carrier subsidiary. Sabre Corporation anchors the North American competitive vector, exemplifying the transition from traditional distribution economics toward direct retailing analytics. TravelSky Technology Limited sits within the government-backed national champion archetype, reflecting China's data sovereignty requirements and state-directed aviation infrastructure development.
| Leading Market Players |
|---|
| Amadeus IT Group SA |
| Sabre Corporation |
| SITA NV |
| TravelSky Technology Limited |
| Hitit Computer Services |
| Bravo Passenger Solutions Pte Limited |
| Lufthansa Systems GmbH & Co. KG |
| IBS Software Private Limited |
| Radixx International |
| Others |
Cost & Logistics Intelligence
EASA digital operational resilience standards gate both qualified supply and premium-tier pricing access, as vendors must demonstrate system continuity capabilities exceeding traditional availability metrics before capturing full-service carrier contracts in Europe. Airlines in Germany and France now require certification-backed uptime guarantees that compress margins for uncertified competitors while rewarding compliant providers with outcome-based contracts tied to passenger throughput.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for SaaS deployment models as regional cloud infrastructure expansion enables subscription pricing aligned with passenger volumes rather than perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels differentiates vendors by certification depth and customization scope, with FAA-certified platforms commanding substantial premiums over uncertified alternatives. Pricing pressure stems from low-cost carrier consolidation in Malaysia and Thailand, which amplifies buyer bargaining power and forces vendors toward volume-based commercial structures. Emerging regional carriers exhibit highest price sensitivity, while flag carriers in Singapore and China prioritize platform autonomy over cost minimization.
Supply Chain Analysis
Reverse-logistics flows for legacy mainframe components extend hardware refresh cycles as carriers dismantle decades-old infrastructure and transition toward microservices architectures. Software development concentrates in Ireland, India, and Germany, with cloud infrastructure provisioning drawing from hyperscaler facilities in Singapore, Frankfurt, and Mumbai. Critical dependencies include real-time transaction processing engines, biometric verification modules, and NDC-compliant retailing interfaces. Single-source vulnerability persists in specialized distributed systems engineering talent pools. Distribution runs through direct enterprise sales teams for full-service carriers and channel partnerships for low-cost carrier segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where cost-of-compliance gaps between FAA certification timelines in the United States and streamlined DGCA interoperability mandates in India accelerate vendor relocation toward South Asian procurement hubs.
For Market Incumbents: Lock in platform stickiness through captive technology subsidiary structures that mirror Lufthansa Systems and TravelSky models, insulating core reservation engines from substitution by modular SaaS entrants. Deepen backward integration into cloud infrastructure provisioning to capture margin pools currently flowing to hyperscaler partners. Prioritize EASA digital operational resilience certification investments ahead of enforcement timelines to defend European market position against emerging competitors. For New Entrants and Emerging Players: Regional carriers in India seeking DGCA-compliant systems for international route expansion represent the most penetrable buyer archetype, as these operators lack capital for captive platform development and face urgent certification deadlines. SaaS deployment models eliminate data center expenditure barriers for this segment. Target biometric-enabled self-service modules as entry point, then expand toward loyalty management analytics where Chinese carriers demonstrate monetization potential through cross-industry partnerships. For Investors and Strategic Acquirers: Roll-up economics work for modular SaaS specialists because hybrid carrier retailing analytics convergence creates cross-selling opportunities across previously siloed reservation and revenue management functions. Acquisition targets should demonstrate API-first architecture capabilities and existing NDC compliance. Long-term viability hinges on cloud-native platform development rather than legacy migration services. Monitor IATA NDC adoption velocity among Asia-Pacific full-service carriers as inflection indicator for direct channel retailing investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Microservices architectures eliminate mainframe dependencies for Singapore Airlines and Qantas. |
| NDC Compliance Certification | IATA retailing standards enable direct channel revenue capture bypassing traditional GDS economics. |
| Biometric Self-Service Deployment | Thai low-cost carriers reduce counter staffing costs through automated verification systems. |
| Loyalty Data Monetization | Chinese carriers leverage member data through partnerships with domestic e-commerce platforms. |
| Captive Technology Subsidiary Formation | Flag carriers in China and Singapore maintain platform autonomy through government-backed infrastructure control. |
Research Approach
Direct dialogue with airline chief technology officers, platform engineering directors, aviation procurement managers, and regulatory compliance officers grounded qualitative insights, validated against IATA NDC implementation filings, FAA certification databases, EASA operational resilience guidance documents, and carrier annual technology expenditure disclosures. Bottom-up triangulation across passenger volume forecasts and top-down validation through aviation software vendor revenue patterns ensured segmentation integrity.
Bottom-up modeling aggregated carrier-specific deployment timelines and platform modernization budgets across service type, deployment model, and end-user categories, while top-down analysis cross-referenced aviation authority procurement mandates and hyperscaler infrastructure expansion announcements. CAGRs derived from installed base migration rates and SaaS adoption curves across the analysis window incorporated NDC adoption velocity, data localization enforcement intensity, and low-cost carrier fleet expansion plans as primary demand drivers.
Underlying measurement precision varies by segment; cloud-based and SaaS deployments carry tighter precision than on-premise legacy systems due to transparent subscription reporting. Forecasts reflect assumptions regarding regulatory enforcement timelines and carrier consolidation patterns. Practitioners should monitor DGCA interoperability mandate expansion and EASA digital operational resilience standard adoption rates for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Public Transport Smart Card Market