
 Transit Oriented Development Market | 2026-2036
Transit Oriented Development Market Size, Share, and Industry Trends Forecast 2026-2036
Transit Oriented Development Market Analytics
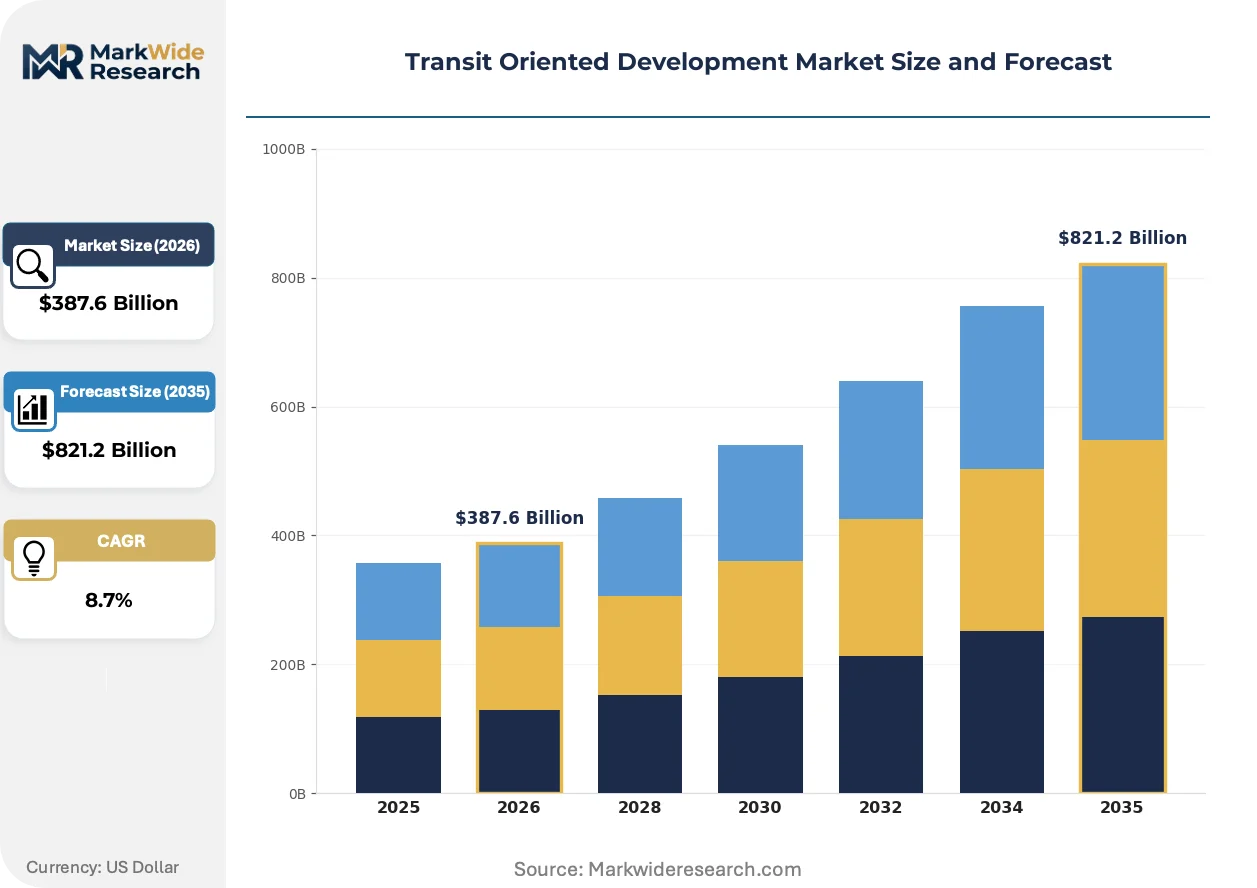
The Transit Oriented Development market is restructuring around a sharp split between premium mixed-use corridors anchored by heavy rail and commodity infill projects tied to bus rapid transit. Trammell Crow Company leverages its vertical development expertise to dominate high-density commercial nodes near commuter hubs. WSP sustains engineering leadership across complex multimodal interchange designs. Parsons anchors public-sector advisory work for agencies navigating federal compliance layers.
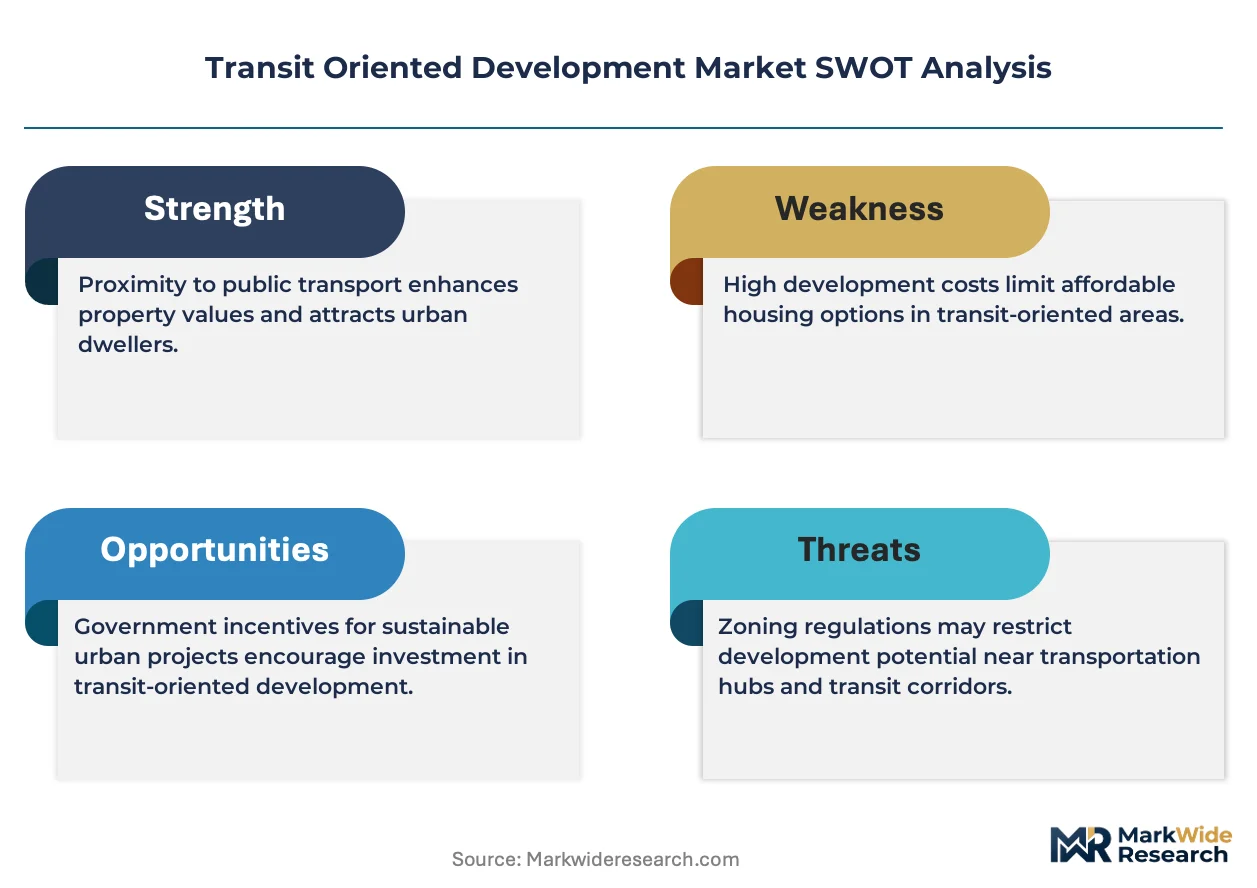
Transit Oriented Development denotes compact, walkable communities engineered within a half-mile radius of high-capacity transit stations, typically integrating residential, commercial, and civic functions through zoning overlays that mandate minimum density thresholds and maximum parking ratios. Its primary commercial purpose is to capture land value uplift from transit accessibility while reducing vehicle miles traveled across metropolitan labor markets. Mixed-Use Development leads investment flows as developers seek diversified revenue streams from single land parcels. Public Transit Integration represents the fastest-growing application segment as agencies convert underutilized parking into revenue-generating assets. Affordable Housing sits at the center of policy-driven margin pools where tax credits and density bonuses reshape project economics.
The Federal Transit Administration coordinates capital grants with local zoning preconditions, while the EPA links brownfield remediation funding to TOD eligibility criteria. State-level enabling statutes in California and Texas determine how regional agencies like BART and DART convert air rights and surplus property. Stakeholders must monitor how infrastructure appropriation cycles interact with municipal fiscal stress to time land assembly and entitlement phases.
Market Dynamics
The Transit Oriented Development market is restructuring around federal infrastructure capital flows that tie transit grants to local zoning preconditions, forcing municipalities to rewrite land-use codes before accessing funding pools.
Growth Catalysts
- IIJA Capital Allocation:The Infrastructure Investment and Jobs Act directs billions toward rail-adjacent projects, requiring density minimums and parking maximums as grant conditions.
- California SB 375 Implementation:Metropolitan planning organizations in the state must coordinate housing and transportation investments, creating automatic TOD eligibility for regional funds.
- Air Rights Monetization:Agencies like BART and DART convert surplus surface parking into developable parcels, unlocking latent land value near existing stations.
Market Restraints
- Construction Cost Escalation:Steel and concrete input volatility compresses developer margins on mid-rise wood-frame projects near bus rapid transit corridors.
- Municipal Fiscal Stress:Local agencies in legacy cities face bond rating pressure that delays infrastructure timing, freezing land assembly phases.
- CEQA Litigation Exposure:California's environmental review statute enables project-level challenges that extend entitlement timelines by 24-36 months.
Strategic Opportunities
- Texas Sun Belt Corridors:DART's Silver Line and Austin's Project Connect create greenfield TOD zones with lighter legacy zoning friction than coastal markets.
- Brownfield Remediation Linkage:EPA funding eligibility tied to TOD criteria converts former industrial parcels near transit into prime development sites.
- Digital Twin Integration:Real-time ridership modeling fused with predictive development pro formas is converging with municipal planning departments, sharpening site selection accuracy.
Industry Challenges
- Multimodal Engineering Talent Scarcity:Complex interchange design requires specialists fluent in both heavy rail and active transportation infrastructure, a shallow labor pool.
- Affordable Housing Compliance Burden:Density bonus programs demand simultaneous navigation of LIHTC, state tax credits, and local inclusionary mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transit Oriented Development Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Residential Developers, Commercial Developers, Public Agencies, Urban Planners Application: Mixed-Use Development, Public Transit Integration, Affordable Housing, Pedestrian Infrastructure Development Stage: Conceptual Design, Construction, Planning Approval, Post-Completion Evaluation Investment Type: Public Funding, Private Investment, Joint Ventures, Grants |
| Companies Covered | Parsons, Santa Clara Valley Transportation Authority (VTA), Trammell Crow Company, Bay Area Rapid Transit (BART), Dallas Area Rapid Transit (DART), The Core Companies, Republic Urban Properties, Keolis, WSP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transit Oriented Development Market Evolving Landscape
Digital infrastructure and policy instrumentation are compressing the gap between transit planning and real estate development, collapsing historically siloed decision timelines into integrated capital programming.
Building information modeling fused with pedestrian flow simulation is converging with transit agency asset management platforms, enabling developers to stress-test site plans against actual ridership patterns before breaking ground. Municipalities in the Bay Area and Washington DC metro deploy these tools to pre-approve zoning envelopes. The technology compresses entitlement risk and accelerates construction loan draws.
The Federal Transit Administration's new land use scoring criteria for New Starts grants now weight proximity to affordable housing units as heavily as travel time savings. Project sponsors must demonstrate upzoning commitments before entering engineering phase. This policy shift most affects Sun Belt cities where zoning remains auto-oriented, forcing Dallas and Phoenix to rewrite comprehensive plans mid-cycle.
Institutional capital deployment patterns are rotating toward operational TOD assets rather than ground-up development, with pension funds acquiring stabilized multifamily near commuter hubs. This preference compresses developer hold periods and shifts risk to value-add operators. The pattern is most visible in California sub-markets where rent stabilization creates yield floor certainty.
Transit Oriented Development Market Segmentation
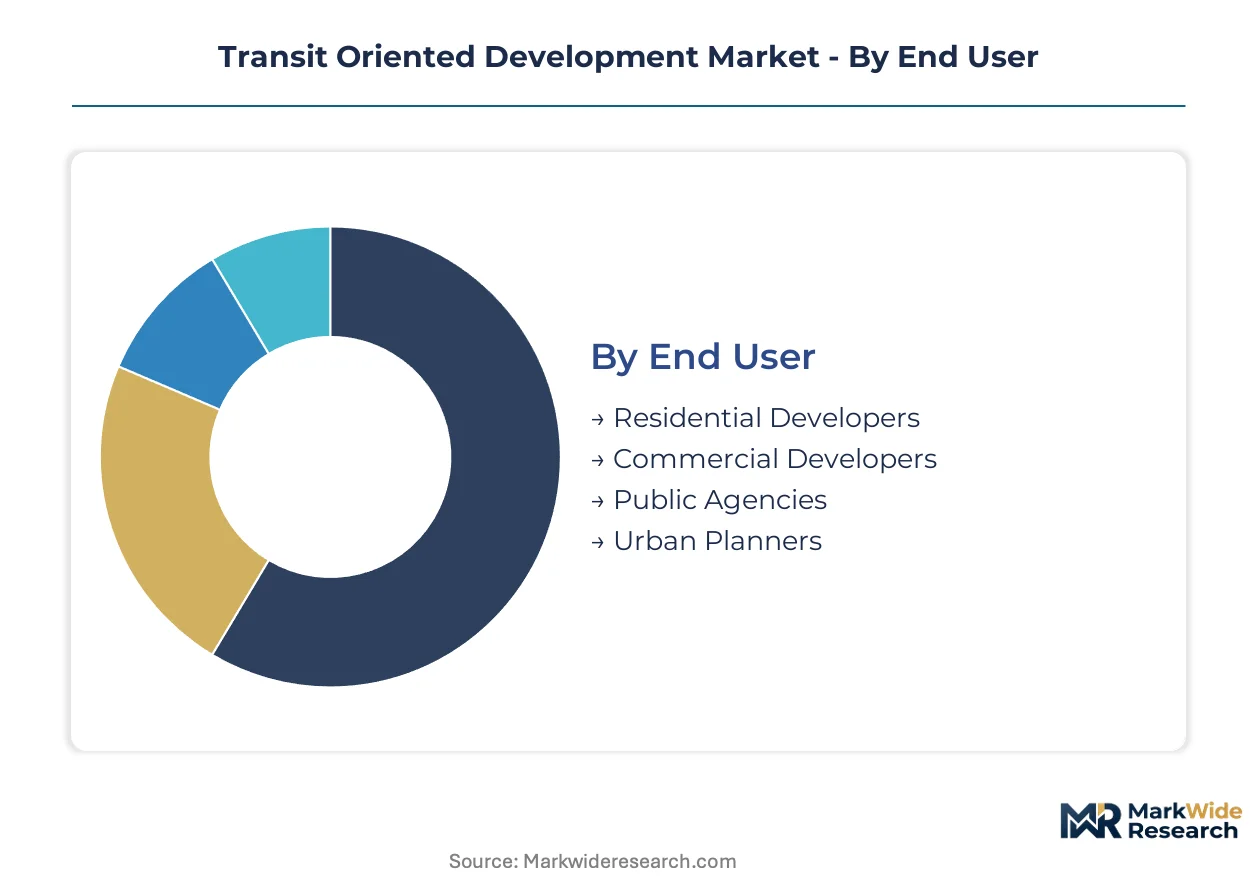
Transit Oriented Development projects require precise matching of capital sources, regulatory stages, and end-user capabilities. Segmentation reveals which developer profiles and funding structures align with specific project typologies across varying entitlement complexity.
End User:
Capital deployment scale and risk tolerance distinguish buyer archetypes in this market.
- Residential Developers:Vertical specialists pursue density bonuses through inclusionary housing mandates, concentrating entitlement efforts in California sub-markets where state law preempts local zoning. Their projects face compressed margins from construction cost volatility on mid-rise wood-frame structures near bus rapid transit corridors.
- Commercial Developers:Office and retail builders anchor mixed-use nodes near heavy rail commuter hubs, seeking diversified revenue streams from single land parcels. Trammell Crow Company dominates this segment through vertical development expertise at high-density commercial nodes.
- Public Agencies:Municipal transit authorities monetize air rights and surplus surface parking, converting underutilized assets into revenue-generating developments. BART and DART lead this conversion strategy across their respective service territories.
- Urban Planners:Technical consultants coordinate zoning overlays and multimodal design standards, bridging siloed transit and real estate decision timelines.
Residential Developers lead on scale; Public Agencies lead on momentum through air rights monetization.
Application:
Functional integration requirements determine technology intensity and regulatory exposure.
- Mixed-Use Development:Integrated residential-commercial-civic programming demands complex entitlement navigation across overlapping zoning jurisdictions. Investment flows concentrate here as developers seek revenue diversification from single parcels.
- Public Transit Integration:Station-area densification and parking conversion projects are expanding most quickly as agencies unlock latent land value. The Federal Transit Administration's New Starts scoring now weights affordable housing proximity equally with travel time savings.
- Affordable Housing:Tax credit layering and density bonus programs reshape project economics, with LIHTC and state credits demanding specialized compliance expertise.
- Pedestrian Infrastructure:Active transportation connections and last-mile circulation improvements complete the walkable catchment radius.
Mixed-Use Development leads on scale; Public Transit Integration leads on momentum.
Development Stage:
Capital risk profiles shift dramatically across the project lifecycle.
- Planning Approval:Entitlement phases face CEQA litigation exposure extending timelines by 24-36 months in California markets. Municipal fiscal stress in legacy cities delays infrastructure timing and freezes land assembly.
- Construction:Steel and concrete input volatility compresses developer margins, particularly on mid-rise projects near bus rapid transit corridors.
- Conceptual Design:Digital twin integration with ridership modeling sharpens site selection accuracy before significant capital commitment.
- Post-Completion Evaluation:Operational asset monitoring informs subsequent phases and validates transit ridership projections.
Construction leads on scale; Planning Approval leads on momentum despite regulatory friction.
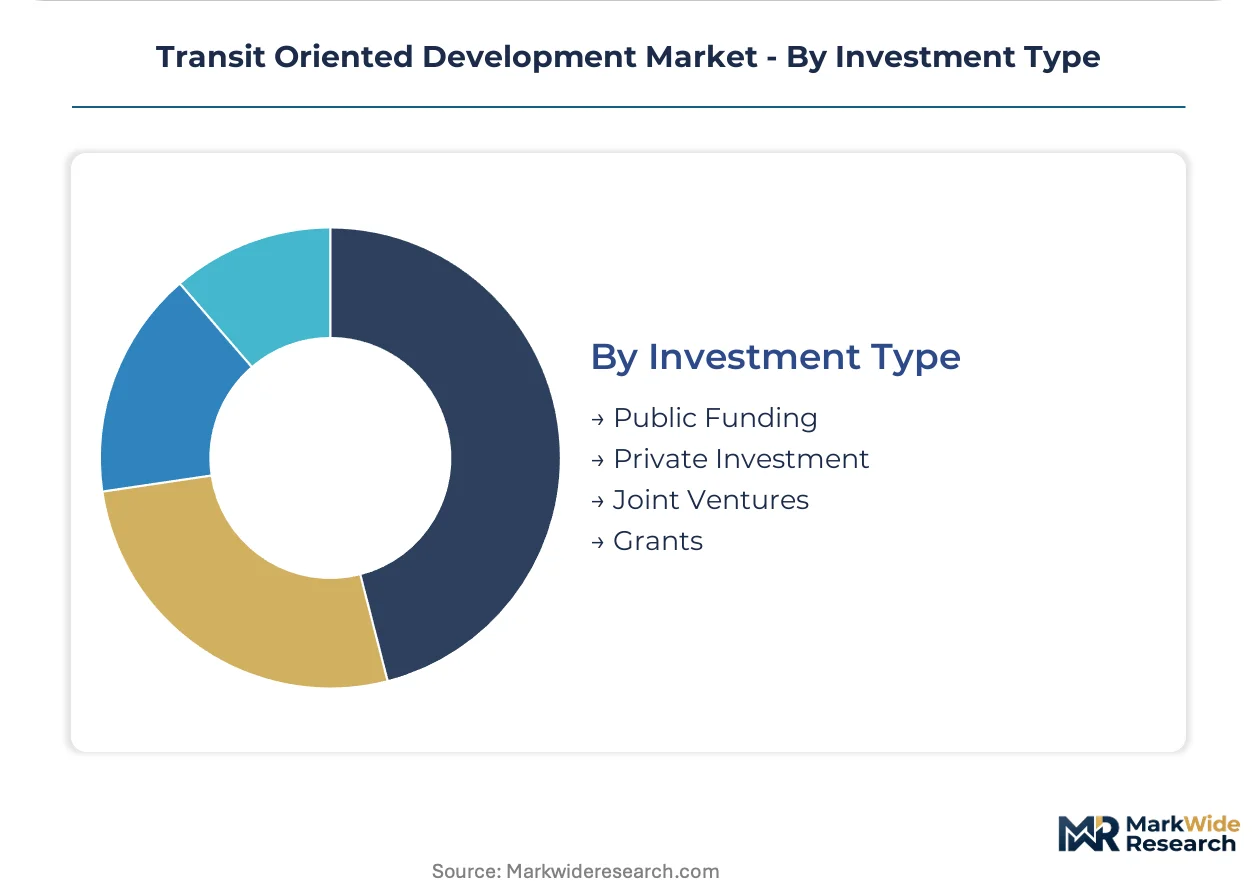
Investment Type:
Return horizon and control requirements structure capital sourcing decisions.
- Private Investment:Institutional capital rotates toward stabilized operational assets rather than ground-up development, compressing developer hold periods. Pension funds acquire multifamily near commuter hubs where rent stabilization creates yield floor certainty.
- Joint Ventures:Public-private structures distribute entitlement risk and align agency land contributions with private development expertise.
- Public Funding:IIJA capital allocation directs billions toward rail-adjacent projects with density minimums and parking maximums as grant conditions.
- Grants:EPA brownfield remediation funding tied to TOD eligibility converts former industrial parcels near transit into prime development sites.
Private Investment leads on scale; Joint Ventures lead on momentum as agencies seek risk-sharing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates federal infrastructure capital more aggressively than Canada, while both markets diverge sharply from European transit finance models. Mexico's emerging corridor investments operate on distinct land-value capture mechanisms.
United States
The Infrastructure Investment and Jobs Act directs billions toward rail-adjacent density mandates, with the Federal Transit Administration conditioning New Starts grants on local zoning pre-approvals. California's SB 375 requires metropolitan planning organizations to coordinate housing and transportation investments, creating automatic TOD eligibility. The Bay Area sub-markets concentrate developer activity around BART station areas where air rights monetization accelerates.
Canada
Municipal transit agencies in Toronto and Vancouver expand mixed-use corridor investments tied to provincial growth plan compliance. Infrastructure Canada coordinates capital grants with regional transportation authorities, while municipal fiscal frameworks in legacy cities face bond rating pressures that delay land assembly timing. The Greater Toronto Area anchors developer concentration around GO Transit expansion corridors.
Mexico
The Secretariat of Agrarian, Territorial and Urban Development promotes compact development near Mexico City Metro expansions, though federal transit capital flows remain thinner than US equivalents. State-level urban development laws in Nuevo León and Jalisco enable densification around Monterrey and Guadalajara light rail corridors. Mexico City Metro anchors the strongest station-area value capture activity.
United Kingdom
The Department for Transport's Housing Infrastructure Fund links transport investment to local plan housing delivery tests, with Homes England coordinating land assembly near Crossrail and HS2 stations. The Greater London Authority's draft London Plan mandates density minimums within 800 meters of transit nodes. London and the Southeast concentrate developer pipelines around Elizabeth Line station areas.
Germany
The Federal Ministry of Transport and Digital Infrastructure directs rail-adjacent development through the Deutschland-Takt integrated timetable program, with state-level urban development statutes enabling density bonuses near Deutsche Bahn stations. Bahnhofsentwicklung programs convert surplus railway land into mixed-use parcels. Berlin and Munich anchor the strongest station-area development pipelines.
Transit Oriented Development Market Competitive Landscape
Top-tier vendors anchor complex multimodal engineering and vertical development, while mid-tier specialists occupy public-sector advisory and regional transit agency niches. The market structures around three strategic archetypes: engineering consultants mastering interchange design, vertical developers controlling high-density commercial nodes, and public agencies monetizing air rights. Competitive positioning depends on entitlement risk distribution and federal compliance navigation. Consolidation pressures favor joint ventures between private developers and transit authorities.
Within the engineering-consultant tier, WSP exemplifies multimodal interchange design leadership, while Parsons occupies public-sector advisory positioning. Among vertical developers, Trammell Crow Company anchors high-density commercial node expertise. These three entities represent distinct capability configurations: WSP and Parsons sit within technical advisory archetypes, while Trammell Crow Company exemplifies private capital deployment at scale.
| Leading Market Players |
|---|
| Parsons |
| Santa Clara Valley Transportation Authority (VTA) |
| Trammell Crow Company |
| Bay Area Rapid Transit (BART) |
| Dallas Area Rapid Transit (DART) |
| The Core Companies |
| Republic Urban Properties |
| Keolis |
| WSP |
| Others |
Value Network & Pricing Analysis
Steel and concrete input volatility propagates through project development tiers, compressing margins on mid-rise wood-frame structures near bus rapid transit corridors while heavy rail-adjacent concrete-and-steel high-rises maintain pricing power through scarcity premiums.
Pricing Analysis
Capacity additions in Texas Sun Belt corridors are reshaping price floors for entitlement-heavy California projects, as lighter legacy zoning friction attracts capital rotation. Three-tier pricing structure across premium heavy-rail nodes, standard bus-rapid-transit corridors, and economy peripheral infill sites reflects entitlement complexity and infrastructure proximity. Cost compression in mid-rise residential tiers intensifies because construction input volatility outpaces rent growth in rent-stabilized sub-markets. Municipal transit agencies exhibit lowest price sensitivity due to air rights monetization mandates, while speculative residential developers face acute margin pressure.
Supply Chain Analysis
Multi-supplier qualification requirements from institutional capital sources mandate diversified sourcing for steel, concrete, and engineered wood products across domestic and Canadian fabrication facilities. Raw material feeds from US Midwest steel mills, Pacific Northwest timber operations, and Mexican cement production anchor project cost structures. Single-source vulnerability concentrates in specialized multimodal engineering talent pools for complex interchange design. Distribution runs through regional building material distributors serving metropolitan construction clusters, with just-in-time delivery coordination critical to phased TOD construction schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transit Oriented Development operates as a geographic-arbitrage play where Texas Sun Belt entitlement timelines compress 18-24 months against California CEQA litigation exposure, rewarding capital deployment toward lighter regulatory friction.
For Market Incumbents: Cement air rights monetization partnerships with BART and DART through long-term ground lease structures that lock in site control. Defensive positioning requires deepening multimodal engineering capabilities to capture complex interchange work as WSP and Parsons face talent scarcity. Threat from institutional capital rotation toward stabilized operational assets compresses developer hold periods and shifts risk to value-add operators.
For New Entrants and Emerging Players: Enter via brownfield remediation specialization linked to EPA funding eligibility criteria, converting former industrial parcels near transit into prime development sites. White-space targets include Austin's Project Connect greenfield zones and Dallas Silver Line corridor pre-entitlement land assembly. Go-to-market positioning as joint venture partners to public agencies seeking risk-sharing structures accelerates pipeline access.
For Investors and Strategic Acquirers: Consolidation pressure builds where municipal fiscal stress in legacy cities delays infrastructure timing and freezes land assembly phases, creating distressed asset opportunities. Long-term viability frames around operational TOD asset platforms with yield floor certainty from rent stabilization. Acquisition target archetype: regional specialists with entitled pipeline in Texas corridors. Signal to watch: Federal Transit Administration land use scoring criteria revisions weighting affordable housing proximity.
| Strategic Initiative | Industry Significance |
|---|---|
| Air Rights Monetization Partnership | BART and DART conversions of surplus parking unlock latent land value near existing stations. |
| Digital Twin Integration | Ridership modeling fused with predictive pro formas sharpens site selection accuracy for developers. |
| Brownfield Remediation Specialization | EPA funding eligibility tied to TOD criteria converts industrial parcels near transit into development sites. |
| Joint Venture Structuring | Public-private partnerships distribute entitlement risk and align agency land with private expertise. |
| Multimodal Engineering Capability Buildout | Complex interchange design talent scarcity creates competitive moat for specialists fluent in heavy rail and active transportation. |
Research Methodology
Direct dialogue with transit agency real estate directors, municipal planning officers, affordable housing developers, and institutional capital allocators grounded qualitative findings in operational realities. Secondary validation drew from Federal Transit Administration capital grant databases, EPA brownfield remediation funding records, state enabling statutes in California and Texas, and municipal comprehensive plan amendments. Bottom-up project pipeline tracking and top-down infrastructure appropriation cycle analysis provided triangulation across data sources.
Bottom-up segmentation modeling across end user archetypes, application functional requirements, development stage risk profiles, and investment type return horizons structured volume and value outputs. CAGRs were derived from project completion velocity tracking and capital deployment pattern analysis. Industry-specific forecast inputs included IIJA appropriation timing, CEQA litigation timeline distributions, and air rights monetization transaction velocity.
Inputs from federal grant databases and municipal planning documents were available through the study window; gaps in proprietary developer pro forma assumptions introduce uncertainty bands around project completion forecasts. Deviation in Infrastructure Investment and Jobs Act reauthorization timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Passenger Service System Market