
 Municipal Vehicles Market | 2026-2036
Municipal Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Municipal Vehicles Market Foresight
North American production capacity for refuse collection chassis is reshaping supplier dynamics across the municipal vehicle supply base. Mack Trucks leverages its integrated powertrain manufacturing to sustain competitive positioning in heavy-duty garbage truck segments. Rosenbauer anchors European market presence through specialized fire and rescue vehicle architectures that extend into municipal emergency response fleets. TATA Motors dominates emerging-market procurement cycles with cost-optimized chassis platforms engineered for high-utilization urban environments.
Municipal vehicles encompass purpose-built trucks, sweepers, plows, and utility units designed for public infrastructure service, typically featuring reinforced frames, low-speed high-torque powertrains, and modular body mounting systems rated for continuous duty cycles exceeding municipal fleet averages. These assets serve waste management, road maintenance, and public transport support functions where operational uptime and total cost of ownership determine procurement outcomes. Garbage trucks command the largest share of fleet investment value, while electric powertrains represent the fastest-expanding segment as battery energy density improvements enable full-route operation without midday charging. Diesel configurations retain dominance in rural municipalities and cold-climate snow plow applications where range and heating loads strain alternative powertrains.
The US EPA enforces emission tiers that compel fleet operators to evaluate compressed natural gas and electric alternatives for urban routes, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices in climate-controlled cab designs. National regulators in China enforce GB standards for commercial vehicle efficiency that filter into municipal chassis specifications through state-owned procurement frameworks. Fleet managers must weigh total cost of ownership against charging infrastructure readiness and residual value uncertainty as powertrain diversification accelerates.
Market Dynamics
Fleet electrification mandates across European and North American municipalities are compressing diesel powertrain procurement cycles while battery-electric chassis manufacturers scramble to match refuse collection duty-cycle requirements. This regulatory compression is redrawing supplier-buyer relationships and capital allocation priorities across the municipal vehicle value chain.
Growth Catalysts
- EPA Clean School Bus Program:Federal funding pools accelerate electric chassis adoption in US public transit support fleets, with waste management operators piggybacking on established charging infrastructure networks.
- Euro VII emission standards:Tightening NOx and particulate limits force premature retirement of legacy diesel garbage trucks across German, French, and Italian municipal fleets.
- Battery energy density improvements:Solid-state and lithium-metal chemistries now enable 200+ kilometer refuse collection routes without midday charging, eliminating the primary operational barrier to full electrification.
Market Restraints
- Lithium and rare earth supply concentration:Cathode material processing capacity clusters in China, exposing European and North American chassis assemblers to geopolitical supply disruptions and price volatility.
- Cold-climate battery performance degradation:Sub-zero temperatures reduce effective range by 30-40 percent, locking diesel dominance in Nordic and Canadian snow removal applications.
- Charging infrastructure capital intensity:Depot electrification requires utility-scale grid upgrades that strain municipal capital budgets, particularly in smaller US cities and Eastern European municipalities.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure investment targets create procurement windows for electric sweepers and compact refuse trucks in 100 designated metropolitan areas.
- Vehicle-to-grid integration:Bidirectional charging protocols allow municipal fleets to sell stored energy back to utilities, transforming parked garbage trucks into revenue-generating grid assets.
- Swedish fossil-free city commitments:Stockholm, Gothenburg, and Malmö binding decarbonization timelines create premium pricing tolerance for hydrogen fuel cell range-extended chassis in heavy-duty applications.
Industry Challenges
- High-voltage technician certification gaps:Fleet maintenance departments lack personnel qualified to service 800-volt battery packs and integrated electric drivetrains, forcing reliance on OEM service networks.
- Residual value uncertainty:Secondary markets for used electric municipal chassis remain undeveloped, complicating total cost of ownership calculations and lease structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Municipal Vehicles Market |
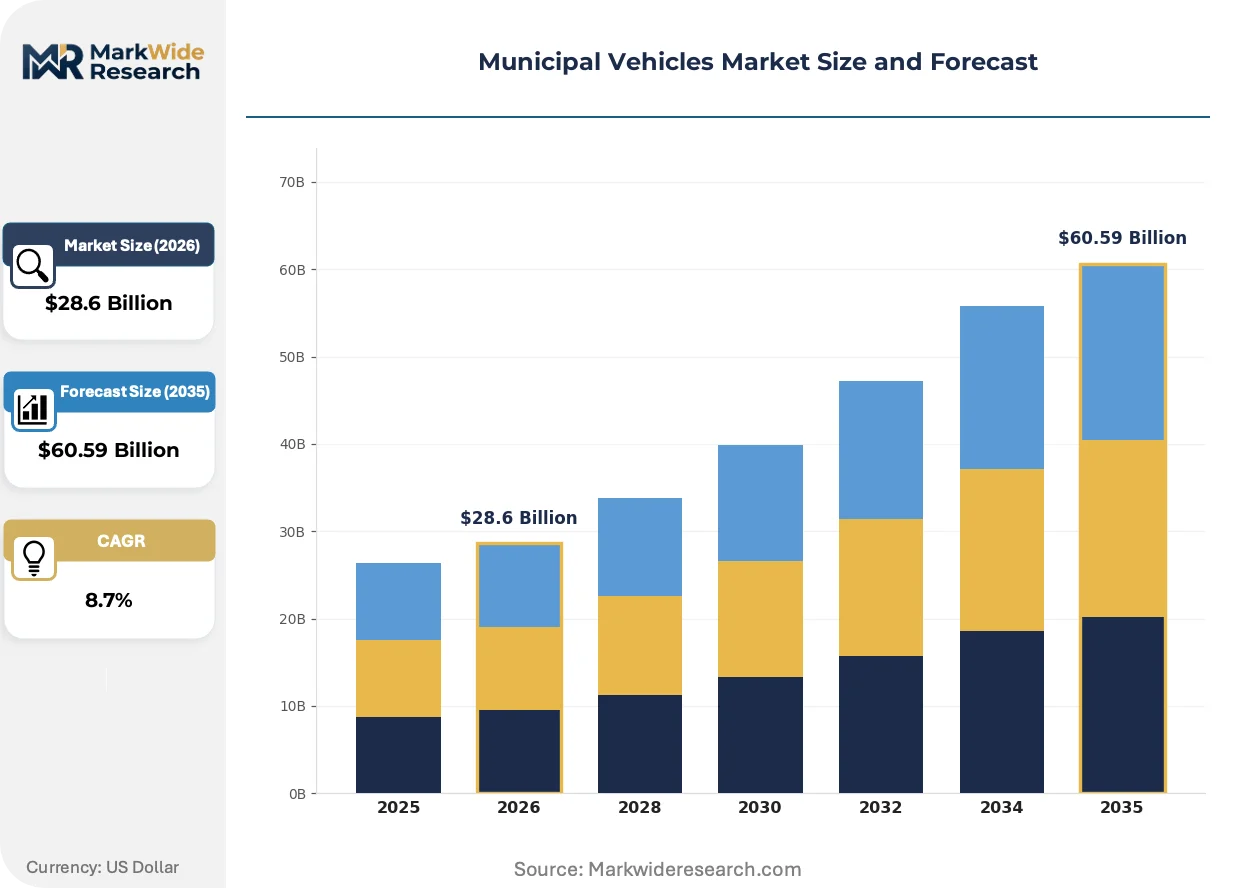
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Garbage Trucks, Snow Plows, Street Sweepers, Utility Vehicles Application: Waste Management, Road Maintenance, Public Transport, Infrastructure Development Power Source: Electric, Diesel, Hybrid, Compressed Natural Gas End User: Municipalities, Government Agencies, Contractors, Private Operators |
| Companies Covered | Mack Trucks, Rosenbauer, TATA Motors, REV Group, Dover Corporation, Autocar Company, Spartan Motors, Kirchhoff Group, Dennis Eagle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Municipal Vehicles Market Shifts & Advancements
Digital twin technology and predictive maintenance platforms are virtualizing traditional fleet management approaches, compressing downtime and reshaping how municipal operators negotiate service contracts with chassis suppliers.
Telematics-integrated battery management systems are virtualizing route optimization for electric refuse trucks. Copenhagen's municipal waste operator deploys real-time state-of-charge monitoring to dynamically adjust collection sequences, eliminating range anxiety without expanding battery capacity. This virtualization of operational planning is reducing per-route energy consumption and enabling smaller, lighter battery packs.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in climate-controlled municipal vehicle cabs. Manufacturers now face redesign mandates for heat pump-based thermal management systems, with compliance deadlines compressing product development timelines. German chassis specialists are accelerating R&D partnerships with automotive HVAC suppliers to meet 2027 certification requirements.
Swedish and Norwegian municipal procurement consortia now bundle vehicle purchases with 10-year energy and maintenance contracts. This performance-based sourcing model transfers operational risk to suppliers while locking in predictable budget outflows for fleet managers. The shift is most advanced in Scandinavian markets where public-sector accounting standards favor operating expenditure over capital commitment structures.
Municipal Vehicles Market Segmentation
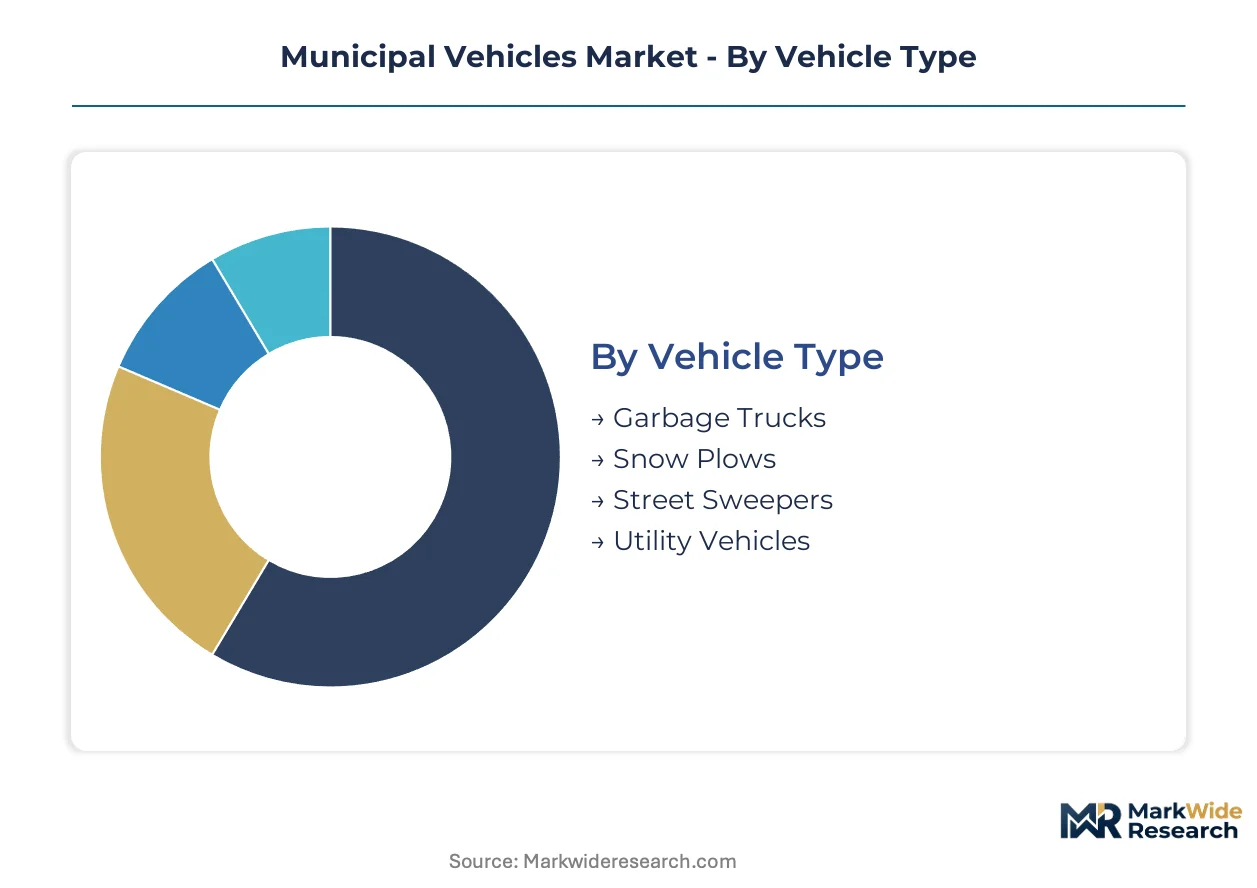
Municipal vehicle procurement decisions cascade through multiple segmentation dimensions, each carrying distinct service lifecycle implications. Fleet managers weigh duty-cycle intensity against charging infrastructure readiness when matching vehicle specifications to operational mandates. Understanding these segment boundaries clarifies where supplier consolidation opportunities and technology substitution risks concentrate.
Vehicle Type:
After-sales service intensity varies sharply across chassis architectures, with refuse collection platforms demanding the most intensive preventive maintenance protocols.
- Garbage Trucks:Reinforced frame designs accommodate hydraulic lifting mechanisms and compaction systems rated for 1,000+ daily cycles. German municipalities facing binding Euro VII compliance deadlines are retiring diesel fleets prematurely, compressing replacement demand into electric chassis procurement windows.
- Street Sweepers:Low-speed high-torque powertrains integrate suction and brush systems for debris collection across urban corridors. Scandinavian cities bundle sweeper acquisitions with decade-long energy contracts, transferring operational risk to suppliers under performance-based sourcing frameworks.
- Snow Plows:Heavy-duty blade mounting systems require structural reinforcements absent in standard chassis designs.
- Utility Vehicles:Modular body mounting accommodates bucket lifts, cable handlers, and lighting rigs for infrastructure maintenance crews.
Garbage trucks hold the largest share; momentum sits with street sweepers as urban air quality mandates accelerate electrification.
Application:
Cost tier stratification separates capital-intensive waste management fleets from seasonal road maintenance deployments.
- Waste Management:Continuous-duty compaction and lifting systems demand reinforced drivetrains engineered for stop-start urban routes. Copenhagen's municipal operator deploys telematics-integrated battery management to dynamically adjust collection sequences, reducing per-route energy consumption without expanding pack capacity.
- Road Maintenance:Seasonal utilization patterns favor diesel dominance in snow removal where sub-zero temperatures degrade battery performance. Canadian municipal fleets retain compression-ignition powertrains for plow applications despite electrification pressures in urban sweeper segments.
- Public Transport:School bus chassis specifications increasingly align with EPA Clean School Bus Program funding requirements.
- Infrastructure Development:Utility truck deployments support construction and maintenance of public works projects.
Waste management commands premium chassis investment; infrastructure development is expanding most quickly as Smart Cities Mission funding flows into Indian metropolitan areas.
Power Source:
Volume concentration in diesel is displacing toward electric as battery chemistry improvements resolve range constraints.
- Electric:Solid-state and lithium-metal chemistries now enable 200+ kilometer refuse collection routes without midday charging. Swedish fossil-free city commitments in Stockholm, Gothenburg, and Malmö create premium pricing tolerance for hydrogen fuel cell range-extended variants in heavy-duty applications.
- Diesel:Compression-ignition powertrains retain dominance in rural municipalities and cold-climate applications where heating loads strain alternative architectures. Euro VII NOx and particulate limits force premature retirement across German, French, and Italian municipal fleets.
- Hybrid:Dual-powertrain configurations bridge infrastructure gaps in transitional markets.
- Compressed Natural Gas:US EPA emission tiers compel fleet operators to evaluate CNG alternatives for urban routes with established fueling infrastructure.
Diesel retains the largest installed base; electric powertrains are gaining share fastest as depot charging infrastructure matures.
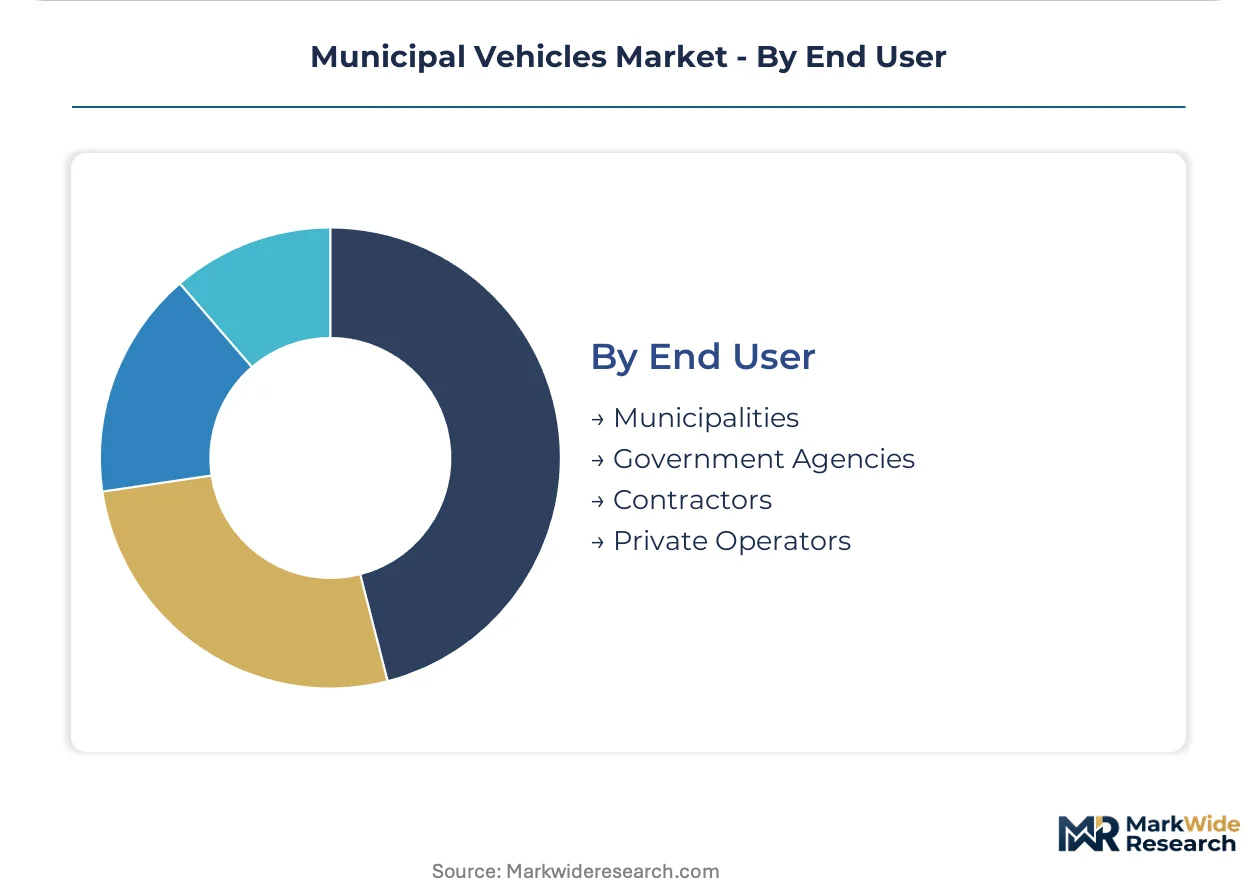
End User:
Customer type determines procurement authority structures and contract duration preferences.
- Municipalities:Direct fleet ownership enables long-term total cost of ownership calculations integrating residual value uncertainty and charging infrastructure capital intensity. US municipal operators piggyback on school bus charging networks to defray depot electrification costs.
- Government Agencies:State-owned procurement frameworks in China filter GB efficiency standards into chassis specifications through centralized tender processes.
- Contractors:Private service providers face compressed asset utilization requirements that favor diesel reliability in early electric transition phases.
- Private Operators:Lease-structured fleet access reduces capital commitment barriers for smaller urban service providers.
Municipalities dominate procurement value; private operators are climbing the fastest as performance-based contracting models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA anchors North American regulatory pressure through the Clean School Bus Program, while Euro VII standards force premature diesel fleet retirements across German and French municipal operators. Battery energy density breakthroughs now enable full-route electric refuse collection in temperate urban corridors.
United States
Municipal fleet managers in California and New York prioritize electric chassis procurement to access federal funding pools. The EPA's emission tiers compel compressed natural gas evaluation for urban waste routes. Chicago and Los Angeles operate the largest electric garbage truck pilot programs, validating depot charging infrastructure at scale.
Germany
Binding decarbonization targets for public fleets accelerate replacement cycles in Bavaria and North Rhine-Westphalia. Euro VII NOx limits force premature retirement of legacy diesel compaction vehicles. Munich and Hamburg lead procurement volume for battery-electric refuse trucks with integrated telematics.
China
State-owned procurement frameworks filter GB commercial vehicle efficiency standards into municipal chassis specifications. The MIIT enforces dual carbon goals that reshape fleet composition in Beijing and Shanghai. Shenzhen operates the world's largest electric street sweeper deployment with vehicle-to-grid integration.
Sweden
Stockholm, Gothenburg, and Malmö enforce fossil-free city commitments with binding 2030 timelines. Municipal procurement consortia bundle vehicle purchases with decade-long energy contracts under performance-based frameworks. Scania and Volvo anchor domestic supply chains for hydrogen fuel cell range-extended heavy-duty applications.
India
The Smart Cities Mission channels infrastructure investment into electric sweeper and compact refuse truck procurement across 100 designated metropolitan areas. BIS efficiency standards filter into state-level tender processes. Maharashtra and Gujarat lead sub-national fleet electrification pilots in Mumbai and Ahmedabad.
Municipal Vehicles Market Competitive Landscape
Integrated powertrain manufacturers and specialized chassis assemblers split the market along duty-cycle complexity lines. Consolidation pressure concentrates among refuse collection platform suppliers facing electrification capex requirements. Three archetypes dominate: legacy truck OEMs with captive engine production, dedicated municipal vehicle specialists with modular body integration, and emerging electric chassis pure-plays with battery-pack integration. Capacity expansion and strategic partnerships represent the dominant competitive vectors as charging infrastructure readiness varies by municipality.
Within the integrated OEM tier, Mack Trucks exemplifies backward control over powertrain manufacturing. Among specialized European fabricators, Rosenbauer occupies a position representing municipal emergency response fleet expertise. TATA Motors anchors emerging-market volume through cost-optimized platform engineering. These three represent distinct geographic and capability archetypes rather than direct substitutability.
| Leading Market Players |
|---|
| Mack Trucks |
| Rosenbauer |
| TATA Motors |
| REV Group |
| Dover Corporation |
| Autocar Company |
| Spartan Motors |
| Kirchhoff Group |
| Dennis Eagle |
| Others |
Supply & Pricing Matrix
Jiangsu Province's cathode material processing clusters concentrate lithium hydroxide refining capacity that feeds directly into European and North American chassis assembler pricing power. Battery pack cost trajectories from this hub cascade through municipal fleet procurement cycles, compressing margins for assemblers lacking long-term offtake agreements or captive cell supply.
Pricing Analysis
Scandinavian municipalities pay 15-25 percent premiums over German counterparts for hydrogen fuel cell range-extended chassis under fossil-free city procurement mandates. Three-tier pricing structure across premium, standard, and economy levels separates Stockholm's bundled energy-service contracts from Eastern European transactional purchases and Indian Smart Cities volume tenders. Pricing pressure stems from lithium carbonate volatility and rare earth magnet cost spikes. Private contractors exhibit highest price sensitivity due to compressed utilization requirements, while Swedish procurement consortia absorb premiums through decade-long performance contracts.
Supply Chain Analysis
CATL, BYD, and LG Energy Solution hold dominant contract manufacturing capacity for municipal vehicle battery packs. Cell production concentrates in China, South Korea, and Poland. Raw material dependencies span Chilean lithium brine, Indonesian nickel laterite, and Chinese rare earth processing. Single-source vulnerability in cathode precursor supply exposes assemblers to geopolitical disruption. Distribution runs through OEM-direct fleet sales for large municipalities and regional dealer networks for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle-to-grid interoperability protocols are transforming parked municipal fleets into distributed energy resources, creating platform-economics inflection where chassis suppliers must bundle energy services to capture procurement decisions.
For Market Incumbents: Harden service network control by certifying high-voltage technicians internally rather than outsourcing to OEM dependency. Secure backward integration into battery pack assembly through joint ventures with cell manufacturers, insulating margin pressure from cathode material volatility. Euro VII compliance deadlines compress replacement windows—capture stranded German diesel fleet demand before pure-play electric entrants scale.
For New Entrants and Emerging Players: Build out vehicle-to-grid integration capabilities as the primary white-space entry vector. Target Indian Smart Cities Mission tenders where incumbent service infrastructure remains undeveloped. Position around compact electric refuse trucks with bidirectional charging as the most penetrable segment, leveraging performance-based contracting to transfer operational risk from municipal buyers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chassis assemblers with captive energy-service bundling capabilities over pure hardware manufacturers. Long-term viability hinges on software-defined fleet management platform ownership rather than metal-bending scale. Acquisition targets should demonstrate integrated telematics deployment with live municipal operator references. Watch for inflection when battery energy density improvements enable 300+ kilometer refuse routes without range-extender hybrids.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks cathode material pricing for chassis assemblers facing lithium volatility from Jiangsu processors. |
| Charging Infrastructure Partnership | Enables depot electrification cost-sharing between OEMs and municipal fleets under EPA funding guidelines. |
| Platform Standardization | Reduces development overhead for electric garbage truck architectures across multiple body integrators. |
| Software-Defined Vehicle Investment | Captures recurring revenue through telematics-optimized route management and predictive maintenance contracts. |
| Geographic Manufacturing Footprint | Positions assembly capacity near Indian Smart Cities Mission procurement clusters to defray logistics costs. |
Research Methodology
Operator-level perspectives from municipal fleet managers, chassis procurement officers, battery system engineers, and aftermarket service directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EPA regulatory filings, EU tender databases, MIIT efficiency standard disclosures, and IEA electric vehicle deployment tracking. Bottom-up unit economics modeling triangulated against top-down market sizing from production database aggregation.
Scenario-bracketing framed demand trajectories across the projection horizon, with segmentation modeling spanning vehicle type, power source architecture, application intensity, and end-user procurement authority. CAGRs derived from fitted growth curves applied to disclosed fleet replacement schedules and regulatory mandate timelines. Forecast inputs incorporated battery energy density improvement curves, charging infrastructure capital cost trajectories, and residual value depreciation assumptions for electric chassis.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hydrogen fuel cell pure-plays or vehicle-to-grid platform specialists would shift outcomes beyond modeled ranges. Quarterly review of municipal tender award flows, battery raw material price indices, and high-voltage technician certification program expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Transit Ticketing Market