
 Automated Fare Collection System Market | 2026-2036
Automated Fare Collection System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Fare Collection System Market Intelligence
Contactless specification-tier upgrades are bifurcating the Automated Fare Collection System landscape as transit operators retire legacy token and magnetic-stripe infrastructure. Cubic Corporation leverages its installed base across North American rail networks to sustain long-term service contracts. Thales Group anchors European deployments through security-certified validation hardware. NXP Semiconductors specializes in NFC controller silicon that dominates embedded transit card architectures.
An automated fare collection system integrates hardware terminals, back-office software, and communication networks to authenticate passengers and process transit payments without manual cashier intervention. These systems typically operate with sub-300-millisecond transaction latency to maintain passenger throughput during peak congestion. Mobile payment solutions and biometric authentication represent the fastest-expanding technology pairings as smartphone penetration and facial recognition accuracy mature in parallel. RFID maintains the largest installed base among core technologies, though NFC is displacing it in new urban rail tenders. Cloud-based installation architectures are capturing disproportionate margin pools by reducing on-premise server maintenance for transit authorities.
The Federal Transit Administration in the United States, the European Commission's Interoperable Fare Management framework, and Japan's Ministry of Land, Infrastructure, Transport and Tourism each enforce payment security and accessibility standards that shape procurement specifications. India's Bureau of Indian Standards and the country's National Common Mobility Card mandate are accelerating domestic system standardization for multimodal transit. Stakeholders must monitor regulatory divergence between open-loop financial compliance and closed-loop transit-specific security architectures when allocating R&D budgets across product portfolios.
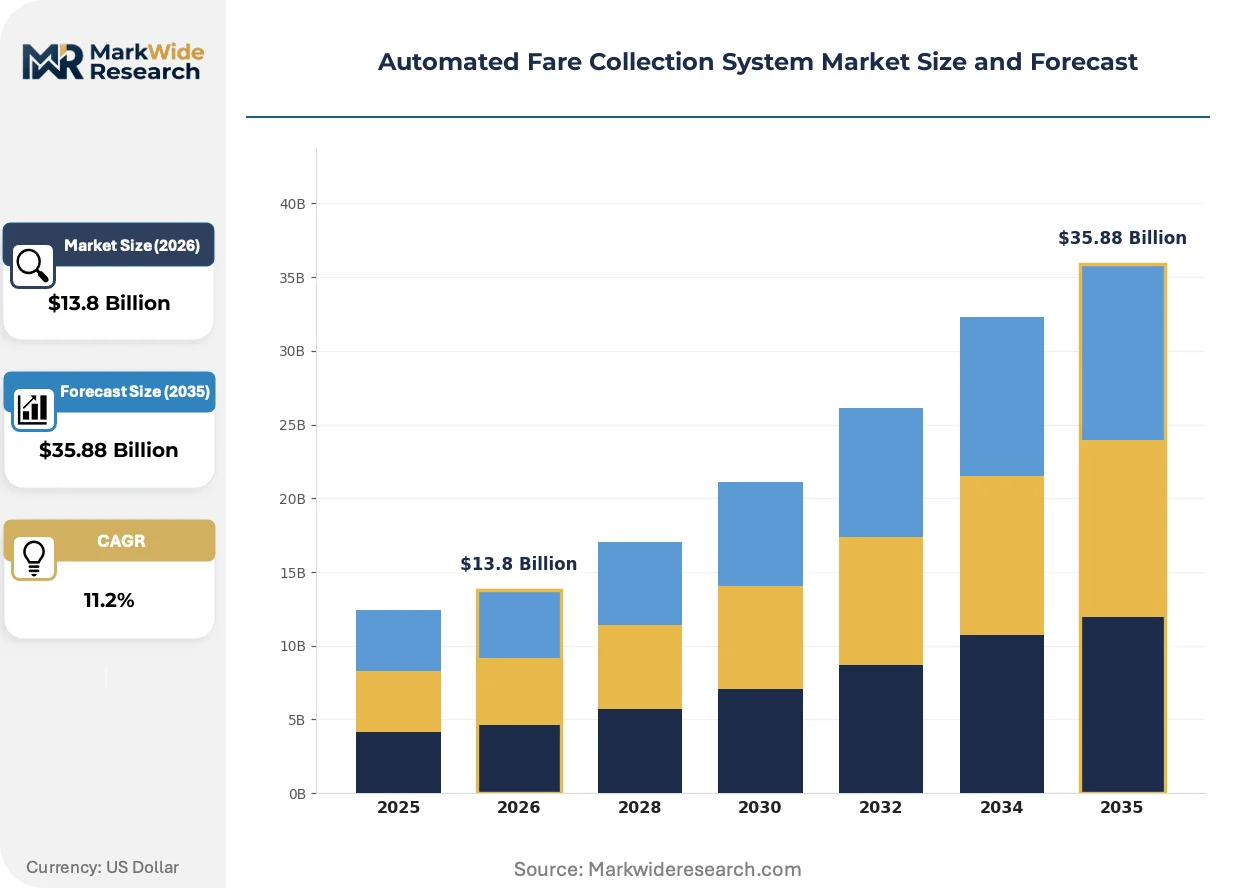
Market Dynamics
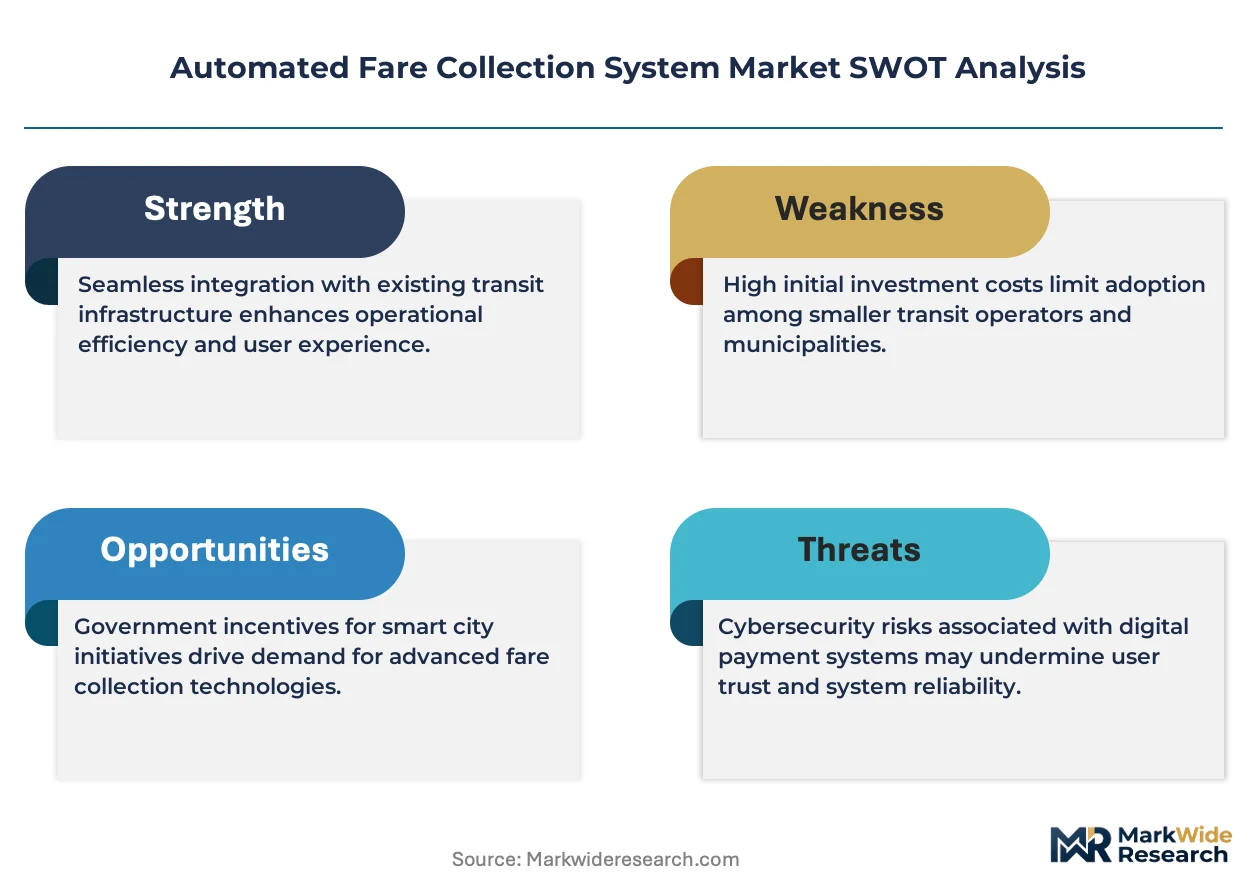
Open-loop payment mandates from transit regulators are forcing wholesale infrastructure replacement across metropolitan rail networks, compressing procurement cycles and reshaping vendor competitive dynamics.
Growth Catalysts
- Contactless NFC specification upgrades:Transit authorities in Japan, South Korea, and Singapore are retiring magnetic-stripe validators to meet EMV compliance deadlines set by financial regulators.
- National Common Mobility Card (India):India's BIS mandate for interoperable multimodal transit cards is standardizing procurement specifications across 23 urban metro corporations.
- Cloud-native back-office architectures:Municipal transit agencies are migrating fare processing to AWS and Azure government clouds to eliminate on-premise server maintenance burdens.
Market Restraints
- Semiconductor supply concentration:NFC controller silicon fabrication concentrates in Taiwan and South Korea, exposing validator manufacturers to foundry allocation volatility.
- Cybersecurity certification friction:PCI DSS Level 1 compliance for open-loop payment acceptance adds 14-18 month validation timelines to product launches.
- Legacy system interoperability:Proprietary protocols from 1990s-era magnetic-stripe systems block seamless hardware upgrades without complete station reconstruction.
Strategic Opportunities
- Biometric-facial recognition convergence:Chinese and Emirati metro operators are piloting gait-recognition payment gates that eliminate physical card or phone requirements entirely.
- MaaS platform integration:First-mile/last-mile ride-hailing bundling creates new revenue streams for AFC providers embedding transit ticketing into Uber and Grab super-apps.
- Sub-Saharan African urban corridors:Lagos, Nairobi, and Addis Ababa lack legacy infrastructure, enabling greenfield contactless deployments without migration costs.
Industry Challenges
- Embedded systems firmware expertise scarcity:Transit validator engineering requires rare specialization in real-time operating systems and secure element programming.
- Station-by-station rollout complexity:Phased hardware replacement across 200+ station networks demands precise passenger communication to prevent fare evasion spikes during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Fare Collection System Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $35.88 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Card Readers, Mobile Payment Solutions, Validation Machines, Ticketing Kiosks Technology: RFID, NFC, QR Code, Biometric Authentication End User: Public Transport Agencies, Rail Operators, Bus Operators, Transit Authorities Installation: Station-based, Vehicle-mounted, Self-service, Cloud-based |
| Companies Covered | Cubic Corporation, Thales Group, Scheidt & Bachmann GmbH, Omron Corporation, NXP Semiconductors, Samsung SDS, LG CNS, Atos SE, LECIP Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Fare Collection System Market Strategic Shifts & Innovations
Payment authentication hardware is undergoing radical form-factor transformation as transit operators prioritize passenger throughput over equipment durability. Three parallel developments are compressing transaction latency and expanding system interoperability.
Multi-protocol NFC controllers are miniaturizing validator circuit boards from palm-sized enclosures to credit-card-dimension modules. European tram operators in Germany and the Netherlands are deploying these compact validators in vehicle-door stanchions rather than dedicated kiosk positions. This form-factor reduction is enabling validator installation in previously space-constrained environments like bus entry steps and ferry gangways.
The European Commission's Interoperable Fare Management framework is mandating account-based ticketing standards across EU member states by 2027. This regulation forces closed-loop transit card systems to accept open-loop bank card credentials at parity pricing. Nordic transit authorities in Sweden and Finland are responding fastest, consolidating 47 separate municipal ticketing schemes into unified national clearinghouses.
Account-based ticketing architectures are displacing card-centric stored-value systems across North American commuter rail networks. Passengers tap contactless bank cards or phones at entry, with fare calculated post-journey based on tap-out location. This model eliminates card issuance and distribution costs for transit agencies while enabling capping and concession automation. The shift is most advanced in London's TfL network and spreading to Chicago, Vancouver, and Sydney.
Automated Fare Collection System Market Segmentation
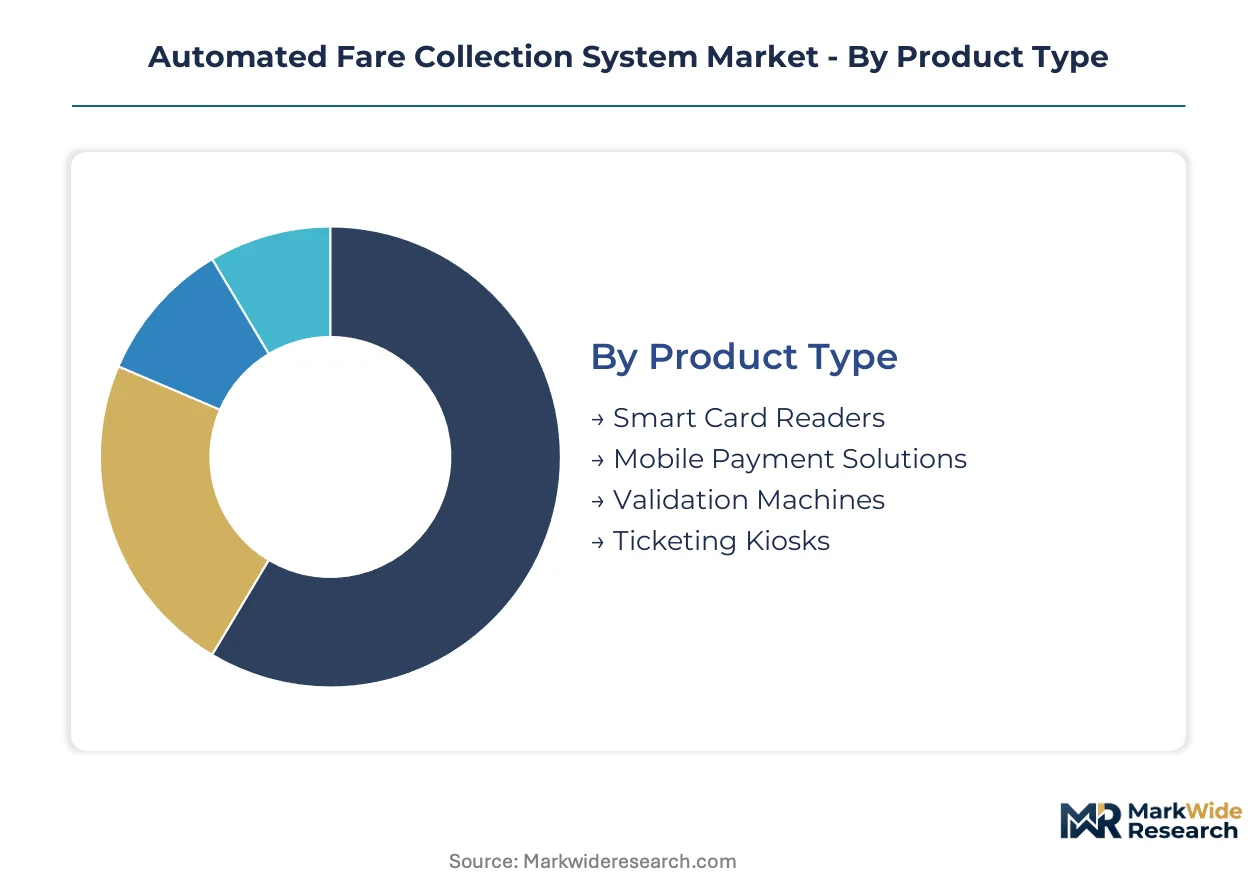
Segmentation in the Automated Fare Collection System market reveals distinct procurement patterns across hardware specifications, authentication protocols, and deployment architectures. Transit authorities select product configurations based on legacy infrastructure constraints, passenger volume profiles, and regulatory compliance timelines.
Product Type:
Hardware flows through direct municipal procurement for rail networks, while mobile solutions increasingly route through SaaS platform partnerships.
- Smart Card Readers:These devices process contactless transit cards through embedded NFC controllers with EMV certification. Demand concentrates in Japanese and South Korean urban rail networks where magnetic-stripe retirement deadlines approach.
- Mobile Payment Solutions:Smartphone-based ticketing applications integrate with transit authority back-office systems via APIs. Indian metro corporations under the National Common Mobility Card mandate are deploying these solutions fastest to achieve multimodal interoperability.
- Validation Machines:Gate-mounted validators authenticate passenger credentials at station entry points.
- Ticketing Kiosks:Self-service terminals issue and reload stored-value cards at high-traffic stations.
By volume, Smart Card Readers lead. By growth pace, Mobile Payment Solutions are expanding most quickly.
Technology:
Cost tiers separate mature RFID installations from premium biometric deployments requiring specialized silicon and certification overhead.
- RFID:Legacy 13.56 MHz radio-frequency identification maintains the largest installed base across European bus networks. German and Dutch operators continue RFID validator deployments in vehicle-door stanchions where hardware miniaturization enables space-constrained installation.
- NFC:Near-field communication controllers enable sub-300-millisecond transaction latency for high-throughput rail gates. East Asian urban corridors in Japan, Singapore, and South Korea are replacing magnetic-stripe infrastructure with NFC-compliant validators to meet financial regulator EMV deadlines.
- QR Code:Two-dimensional barcode scanning supports account-based ticketing without specialized hardware.
- Biometric Authentication:Facial recognition and gait analysis eliminate physical credential requirements entirely.
By installed base, RFID dominates. By replacement velocity, NFC is gaining share fastest.
End User:
Application intensity varies by passenger density and fare complexity across operator categories.
- Public Transport Agencies:Municipal authorities operating multimodal networks require unified clearinghouse architectures. Swedish and Finnish agencies are consolidating 47 separate municipal schemes into national account-based systems under EU Interoperable Fare Management mandates.
- Rail Operators:Heavy rail and metro systems demand highest-throughput validation with sub-300-millisecond latency specifications. London's TfL network anchors this segment with complete account-based ticketing deployment spreading to Chicago, Vancouver, and Sydney.
- Bus Operators:Vehicle-mounted validators prioritize durability over transaction speed.
- Transit Authorities:Regional coordinating bodies standardize procurement across multiple operators.
By procurement value, Rail Operators lead. By system modernization urgency, Public Transport Agencies are ahead.
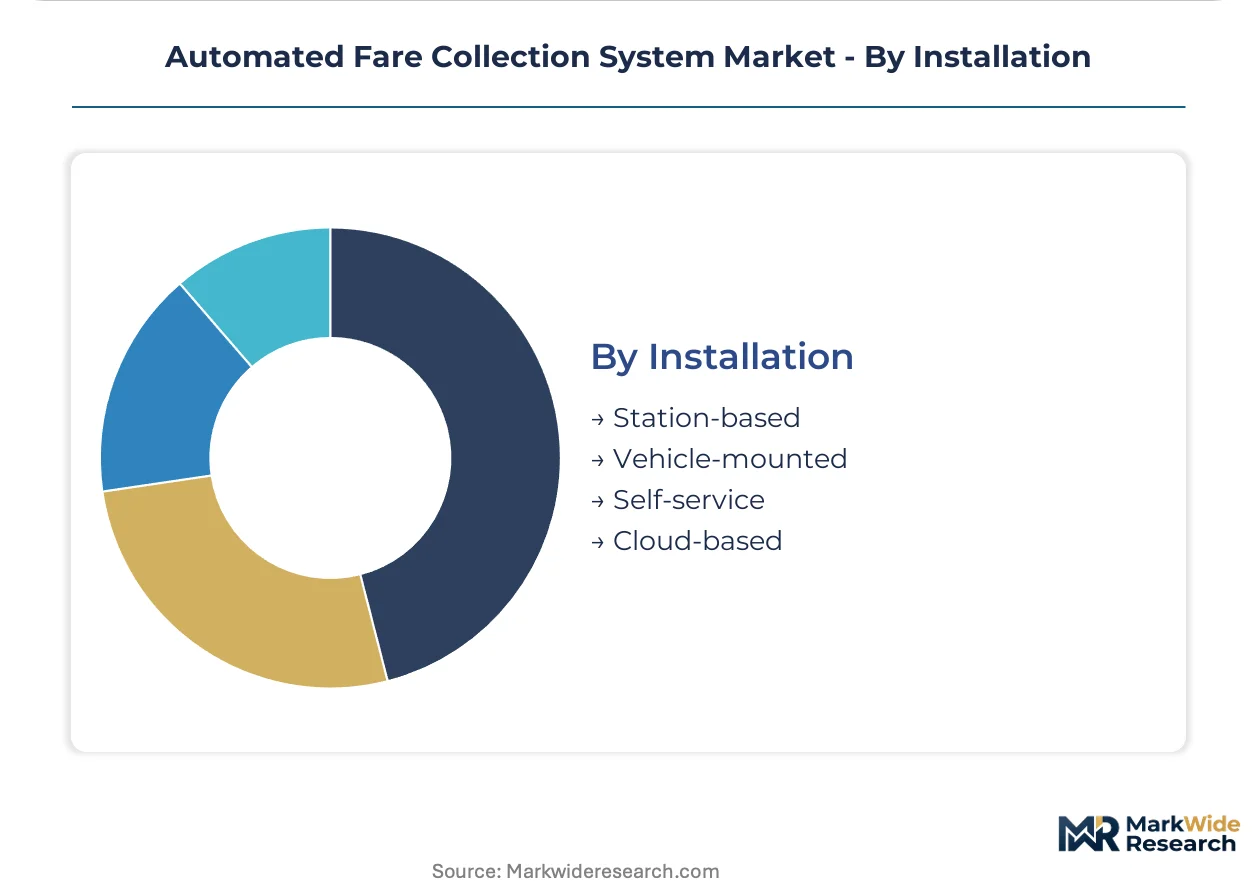
Installation:
Margin pools concentrate in cloud-native architectures that eliminate on-premise server maintenance burdens.
- Station-based:Fixed validators and kiosks at rail and metro platforms process highest passenger volumes. These installations dominate legacy infrastructure replacement cycles across East Asian urban corridors.
- Vehicle-mounted:Bus and tram validators require vibration-resistant enclosures and mobile network connectivity.
- Self-service:Unattended kiosks for card issuance and reloading reduce staffing costs.
- Cloud-based:AWS and Azure government cloud deployments process fare transactions without municipal data center maintenance. North American commuter rail networks are migrating to these architectures fastest to reduce IT overhead.
By deployment count, Station-based leads. By margin expansion, Cloud-based is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net AFC system exports flow from European and East Asian manufacturing clusters toward greenfield transit markets in South Asia and sub-Saharan Africa. Import dependency concentrates in semiconductor components and secure element silicon. Regional procurement patterns diverge sharply between EMV-mandated open-loop upgrades and closed-loop legacy extensions.
United States
Federal Transit Administration capital grants are modernizing legacy magnetic-stripe infrastructure across the largest metropolitan rail networks. PCI DSS Level 1 compliance mandates for open-loop payment acceptance extend product validation timelines. Chicago Transit Authority and Metropolitan Transportation Authority anchor demand concentration in the Great Lakes and Northeast corridors.
Japan
Ministry of Land, Infrastructure, Transport and Tourism deadlines are accelerating retirement of proprietary transit card systems in favor of interoperable EMV architectures. JIS standards for contactless validators shape domestic procurement specifications. Tokyo Metro and JR East dominate deployment volumes across the Kanto urban corridor.
Germany
EU Interoperable Fare Management framework mandates are consolidating 47 separate municipal ticketing schemes into unified national clearinghouses. VDV core applications standards for account-based ticketing reshape validator procurement. Berlin-Brandenburg and Bavarian transit authorities lead hardware replacement cycles.
India
Bureau of Indian Standards mandates under the National Common Mobility Card program are standardizing specifications across 23 urban metro corporations. RBI payment security guidelines for open-loop transit acceptance accelerate cloud-native back-office migration. Delhi Metro Rail Corporation and Mumbai Metro anchor deployment scale in the National Capital Region and Maharashtra.
Singapore
Land Transport Authority specifications for next-generation fare collection emphasize multimodal interoperability between rail, bus, and micro-mobility networks. EMV contactless compliance deadlines align validator procurement with financial regulator timelines. The city-state functions as a demonstration hub for Southeast Asian transit technology transfer.
Automated Fare Collection System Market Key Industry Players
Listed leaders compete with private specialists across hardware fabrication and software integration dimensions. Market structure tilts toward consolidated validator manufacturing with fragmented back-office SaaS provision. Two archetypes dominate: diversified electronics conglomerates leveraging semiconductor captive supply, and transit-specific engineering houses with embedded firmware expertise. Competitive moves concentrate on cloud-native architecture licensing and EMV certification acceleration partnerships.
Within the diversified technology tier, Cubic Corporation and Thales Group exemplify scale-driven positioning across integrated system delivery. NXP Semiconductors occupies a specialist role in NFC controller silicon that anchors embedded transit card architectures. These three entities represent distinct competitive vectors: North American rail network incumbency, European security-certified hardware, and semiconductor component dominance respectively.
| Leading Market Players |
|---|
| Cubic Corporation |
| Thales Group |
| Scheidt & Bachmann GmbH |
| Omron Corporation |
| NXP Semiconductors |
| Samsung SDS |
| LG CNS |
| Atos SE |
| LECIP Holdings Corporation |
| Others |
Cost & Logistics Intelligence
Fourteen-to-eighteen-month PCI DSS Level 1 certification timelines compress validator manufacturer pricing power while concentrating margin pools among foundry-preferred semiconductor suppliers. Transit authorities with EMV-mandated procurement deadlines absorb premium pricing for security-certified hardware, whereas agencies with flexible replacement schedules exploit competitive tendering.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures for integrated AFC system deployments, with three-tier pricing stratification across premium EMV-certified, standard NFC-compliant, and economy RFID-legacy validator tiers. Price differentiation rests on certification grade and after-sales service bundling, with PCI DSS Level 1 compliance adding substantial cost overhead. Cost compression in standard-tier validators is intensifying because Taiwanese foundry allocation volatility raises NFC controller silicon spot pricing. Municipal transit agencies exhibit highest price sensitivity, while national rail operators prioritize throughput specifications over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes expose validator manufacturers to inbound logistics cost volatility and extended component lead times. NFC controller silicon fabrication concentrates in Taiwan and South Korea, with secure element programming expertise clustering in Germany and Japan. Raw material dependencies span semiconductor-grade silicon wafers, EMV-certified secure microcontrollers, and vibration-resistant enclosure alloys. Single-source vulnerability in Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through direct municipal procurement channels for rail networks and SaaS platform partnerships for mobile solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across 23 Indian metro corporations and 47 Nordic municipal schemes creates specialized vendor niches as interoperability mandates multiply buyer archetypes.
For Market Incumbents: Secure long-term service contracts across North American rail networks to lock in recurring revenue against cloud-native SaaS challengers. Deepen backward integration into NFC controller silicon through foundry partnership commitments, insulating margin pools from Taiwan semiconductor allocation volatility. For New Entrants and Emerging Players: Cloud-native back-office migration gaps in mid-tier European tram operators offer white-space entry points where incumbents under-serve with legacy on-premise architectures. Target Indian metro corporations under National Common Mobility Card standardization for fastest procurement velocity, leveraging API-first mobile ticketing platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native AFC software layers as AWS and Azure government cloud deployments eliminate municipal data center infrastructure requirements. Acquire embedded firmware engineering specialists with real-time operating systems expertise, as validator hardware consolidation proceeds faster than software talent supply expansion. Watch EMV certification timeline compression as the signal indicating pricing power inflection toward security-certified hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EMV Certification Acceleration Partnership | Shortens PCI DSS validation timelines for open-loop payment acceptance in FTA-funded networks. |
| Cloud-Native Back-Office Migration | Shifts fare processing to AWS and Azure government clouds, eliminating municipal server maintenance burdens. |
| Biometric Authentication Pilot Deployment | Positions vendors for Chinese and Emirati metro operator gait-recognition procurement specifications. |
| MaaS Platform Integration | Embeds transit ticketing into Uber and Grab super-apps, capturing first-mile/last-mile revenue streams. |
| Greenfield African Market Entry | Exploits absence of legacy infrastructure in Lagos, Nairobi, and Addis Ababa for contactless deployments. |
Research Approach
Cross-validation between primary interviews with transit authority procurement directors, validator engineering heads, and semiconductor supply managers anchors the qualitative findings against secondary validation from Federal Transit Administration capital grant disclosures, EU Interoperable Fare Management framework documentation, and Bureau of Indian Standards certification records. Bottom-up demand modeling triangulates against top-down market sizing across hardware terminal shipments and SaaS platform licensing.
Sensitivity analysis on semiconductor foundry allocation scenarios and EMV compliance deadline shifts shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, authentication protocol, deployment architecture, and passenger volume tier. CAGRs derive from validator replacement cycle analysis and cloud migration velocity indicators, with fare transaction volume elasticity and regulatory compliance timeline rigor serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FTA capital grant regimes, EU Interoperable Fare Management mandates, and India's National Common Mobility Card standardization; material policy shifts would require re-modeling. Supply chain disruption scenarios and cybersecurity certification timeline extensions represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Public Transportation Software Market
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Transit Ticketing Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Electric Public Transport System Market