
 Middle East and Africa Metal Packaging Market | 2026-2036
Middle East and Africa Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Metal Packaging Market Insights
Aftermarket recycling and collection logistics is reshaping margin distribution across the Middle East and Africa Metal Packaging value chain. SAPIN Saudi Arabian Packaging Industry Co. Ltd. leverages its Jeddah manufacturing base to dominate aluminum beverage can supply across the Red Sea corridor. Nampak Limited anchors its position through backward integration into tinplate rolling and steel can fabrication for Southern African food processors. Crown Holdings, Inc. extends its technical service footprint by operating regional refurbishment centers for beverage filling line tooling.
Middle East and Africa metal packaging encompasses rigid and semi-rigid containers fabricated from aluminum alloys, tinplate, or chromium-coated steel, typically ranging from 0.15 mm to 0.35 mm in wall thickness, designed to provide barrier protection against oxygen, light, and mechanical damage for shelf-stable consumer goods. The aluminum cans segment leads volume throughput across the Gulf states, driven by per-capita beverage consumption patterns and the material's infinite recyclability profile. Steel cans retain structural importance in food preservation applications, particularly where retort processing at 121 degrees Celsius demands thermal stability that thinner aluminum gauges cannot reliably deliver. The aerosol form category shows momentum in personal care and household product applications across Moroccan and Egyptian manufacturing clusters.
South Africa's National Regulator for Compulsory Specifications enforces mandatory performance standards for food-contact metal surfaces, while Saudi Arabia's SFDA mandates migration testing for epoxy-based internal coatings. Egypt's EOS and Nigeria's SON both operate import inspection regimes that delay non-compliant metal packaging shipments at port entry. Stakeholders must monitor how extended producer responsibility frameworks evolve across Gulf Cooperation Council member states, as deposit-return obligations will restructure collection infrastructure investment priorities and reshape supplier-customer contracting terms.
Market Dynamics
Extended producer responsibility frameworks across Gulf Cooperation Council member states are forcing beverage and food processors to renegotiate supplier contracts around collection infrastructure ownership and deposit-return scheme participation.
Growth Catalysts
- Aluminum Beverage Can Demand:Carbonated soft drink consumption patterns across Saudi Arabia, UAE, and Qatar are pulling aluminum can procurement volumes upward as bottlers seek lighter-weight, infinitely recyclable formats for hot-climate distribution.
- South Africa's Extended Producer Responsibility:Mandatory recycling targets for metal packaging producers are creating structured demand for domestically fabricated steel cans with verified post-consumer recycled content.
- Retort-Compatible Steel Formats:Food processors in Nigeria's Lagos corridor are converting tomato paste and evaporated milk packaging from glass to tinplate cans capable of withstanding 121-degree Celsius sterilization cycles.
Market Restraints
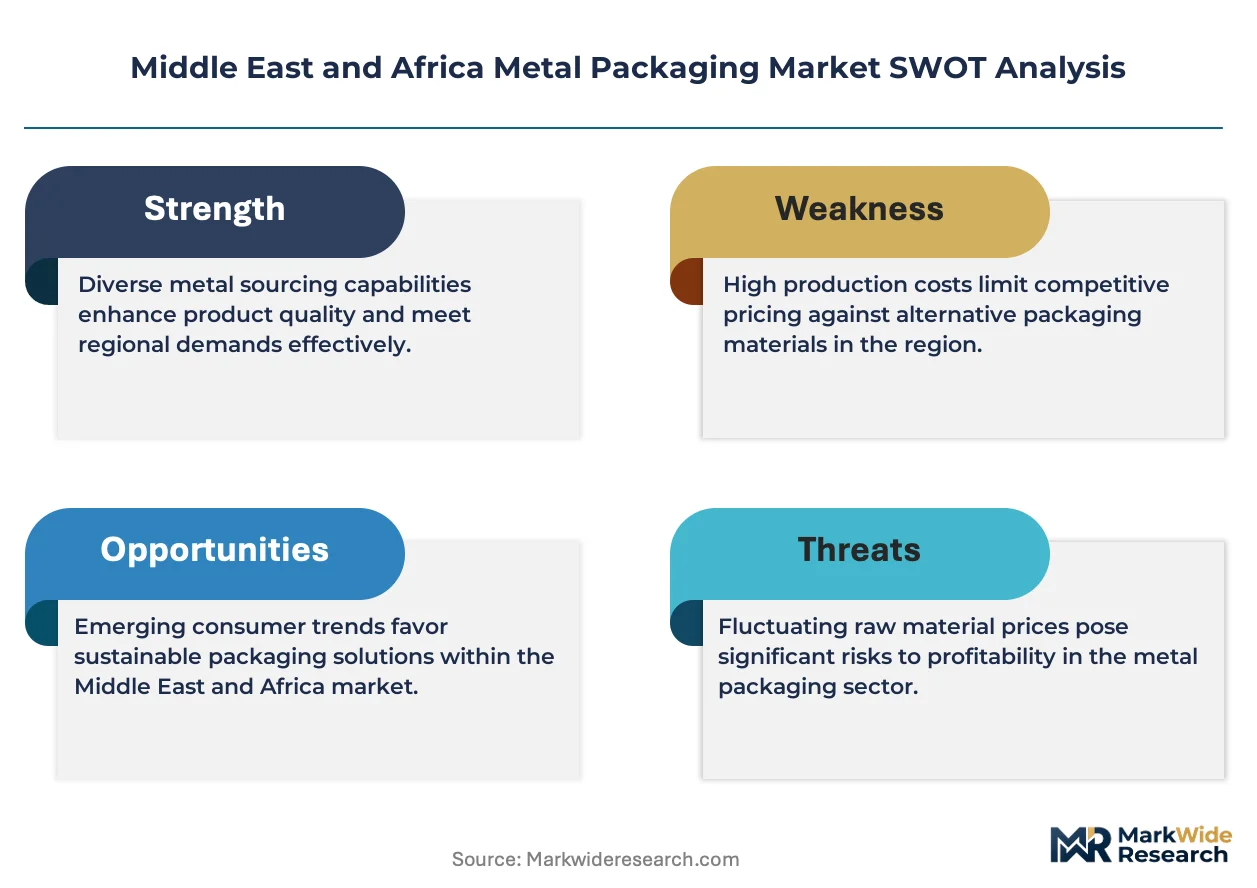
- Tinplate Input Cost Volatility:Cold-rolled steel and tin coating material costs fluctuate with global commodity indices, compressing margin predictability for regional can fabricators serving price-sensitive African markets.
- Import Inspection Friction:Egypt's EOS and Nigeria's SON operate non-harmonized pre-shipment inspection regimes that delay metal packaging container arrivals at Alexandria and Lagos ports, extending working capital cycles.
- Epoxy Coating Migration Testing:Saudi Arabia's SFDA mandates batch-level laboratory verification for food-contact internal coatings, adding compliance cost layers that disadvantage smaller import-dependent distributors.
Strategic Opportunities
- Moroccan Aerosol Manufacturing Clusters:Personal care and household product contract manufacturers in Casablanca-Rabat corridor present underdeveloped demand for aluminum aerosol cans with crimped valve assemblies.
- Deposit-Return Infrastructure Buildout:Pending GCC-wide extended producer responsibility harmonization will create first-mover advantages for metal packaging suppliers offering integrated collection-reverse logistics partnerships.
- Digital Printing Convergence:Direct-to-can inkjet decoration technology combined with shorter-run flexographic presses enables beverage brands to execute seasonal and promotional label variants without cylinder engraving lead times.
Industry Challenges
- Coating Chemist Talent Scarcity:Formulation expertise for BPA-NI epoxy and polyester-based internal coatings remains concentrated among European and Asian technical centers, limiting regional R&D autonomy.
- Retort Equipment Capex Burden:Food processors converting to steel can formats face substantial capital outlays for horizontal and vertical retort sterilization systems, slowing format transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Metal Packaging Market |
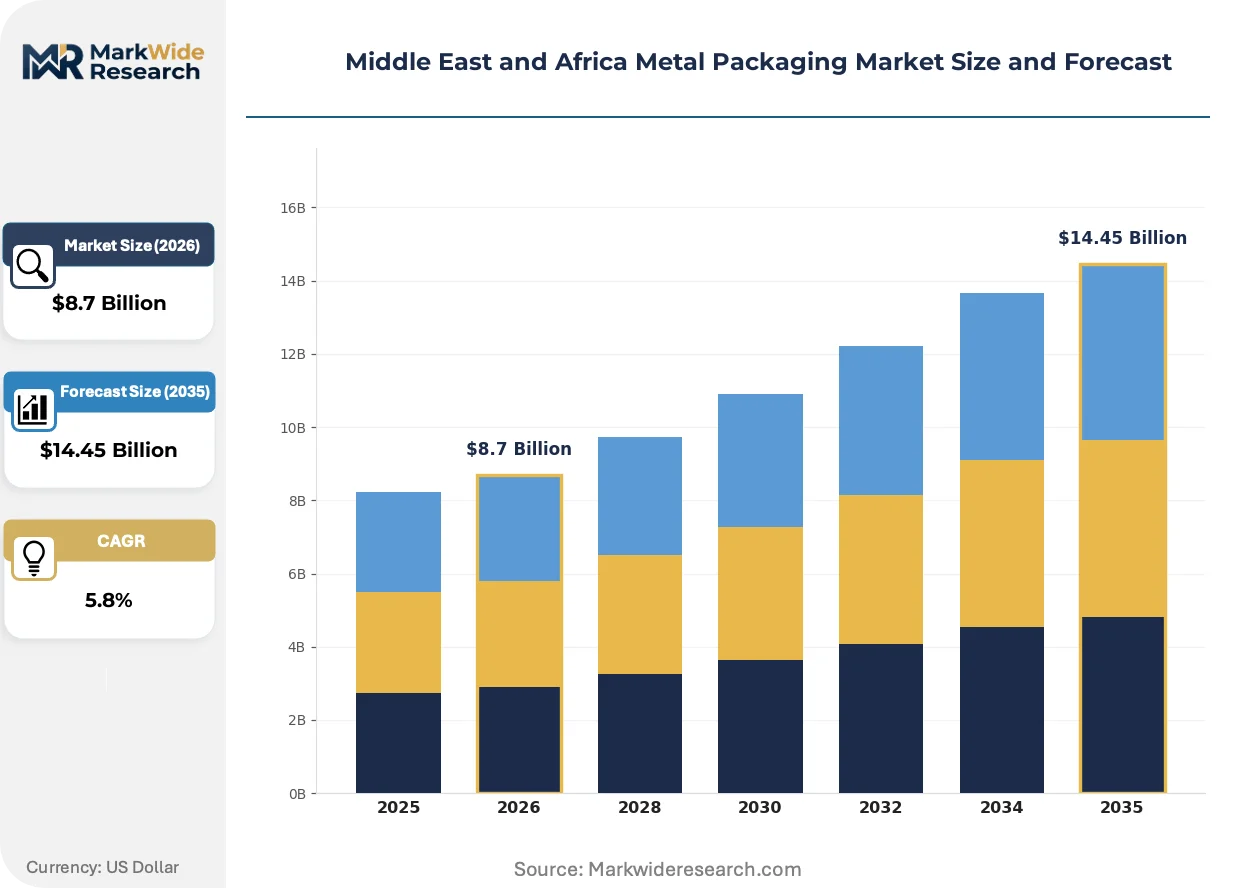
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Metal Boxes, Drums End User: Beverage, Food, Pharmaceuticals, Personal Care Form: Rigid, Flexible, Aerosol, Composite Application: Packaging Solutions, Storage, Transportation, Display |
| Companies Covered | Crown Holdings, Inc., Ball Corporation, SAPIN Saudi Arabian Packaging Industry Co. Ltd., Avon Crowncaps and Containers Nigeria Ltd., Nampak Limited, CANPACK S.A., Mahmood Saeed Beverage Cans and Ends Industry Co. Ltd., Saudi Can Co., Dayal Metal Containers Factory LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Metal Packaging Market Trends and Innovations
Digital workflow integration across design, pre-press, and manufacturing execution systems is compressing new product introduction timelines for beverage and food brands seeking rapid market responsiveness.
Digital inkjet decoration systems capable of variable-data printing and photorealistic imagery are virtualizing the traditional cylinder-engraving bottleneck that historically constrained aluminum can design flexibility. Beverage marketers across Dubai and Riyadh are adopting these systems for limited-edition promotional runs. The technology is virtualizing capital allocation patterns by eliminating tooling amortization requirements for short production batches.
Saudi Arabia's SFDA has tightened migration testing protocols for epoxy-based internal coatings in food-contact metal packaging, requiring documented compliance certificates for every import shipment. This regulatory tightening is redirecting procurement decisions toward suppliers with captive laboratory testing capabilities. Domestic can fabricators with in-house coating validation infrastructure are capturing preferential supply contracts from multinational food processors.
Brand owners are unbundling decoration specifications from volume commitments, negotiating spot contracts for aluminum cans with digitally printed sleeves rather than committing to minimum order quantities for pre-printed formats. This purchasing pattern fragmentation is disrupting traditional converter-customer relationships anchored on long-term cylinder investments. The shift is most visible among craft beverage entrants in South Africa's Western Cape and UAE's emerging non-alcoholic drink segment.
Middle East and Africa Metal Packaging Market Segmentation
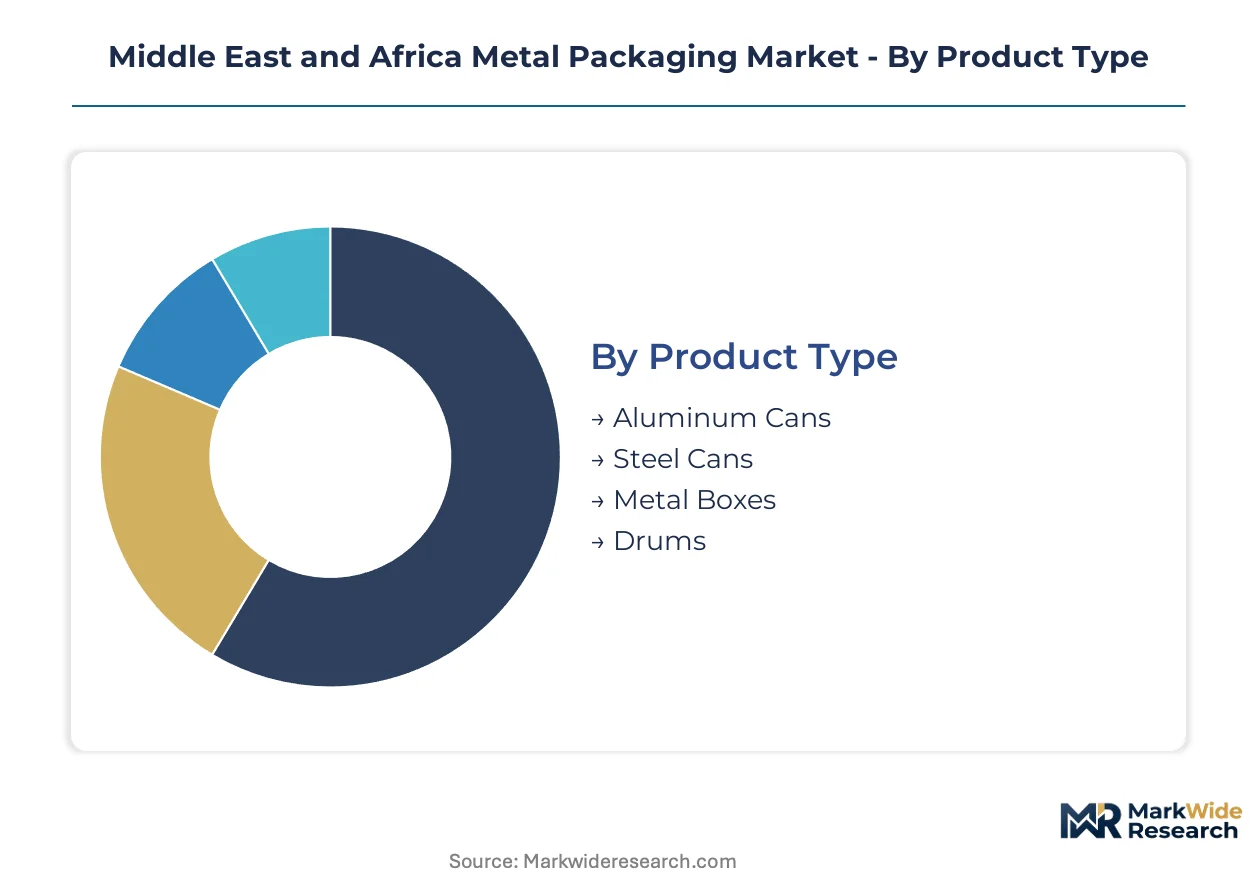
Metal packaging procurement decisions across the Middle East and Africa hinge on thermal performance requirements, recyclability mandates, and filling line compatibility. Segmentation reveals how aluminum and steel formats partition across beverage carbonation, food sterilization, and aerosol propellant applications.
Product Type:
Material composition governs wall thickness, coating chemistry, and end-use thermal tolerance across the value chain.
- Aluminum Cans:Fabricated from 3104-H19 alloy with 0.097 mm body wall thickness and epoxy-phenolic internal linings. Beverage bottlers in Saudi Arabia and UAE are expanding procurement for carbonated soft drinks and energy beverages in hot-climate distribution. The material's infinite recyclability profile aligns with emerging GCC extended producer responsibility frameworks.
- Steel Cans:Constructed from tinplate or tin-free steel with 0.20-0.28 mm gauges, capable of withstanding 121-degree Celsius retort sterilization cycles. Food processors in Nigeria's Lagos corridor are converting tomato paste and evaporated milk packaging from glass to tinplate formats. Cold-rolled steel input cost volatility compresses margin predictability for regional fabricators.
- Metal Boxes:Rectangular tinplate containers for confectionery, biscuits, and premium gift packaging. Moroccan and Egyptian manufacturers utilize these for date exports and seasonal confectionery.
- Drums:Steel drums with 200-liter capacity for industrial chemicals, lubricants, and edible oil bulk transport. South Africa's petrochemical sector drives refurbishment demand for reconditioned units.
Steel cans hold installed capacity for thermal-intensive food applications. Aluminum cans are rotating up the share rankings as beverage bottlers prioritize lightweight logistics.
End User:
Customer procurement patterns diverge between high-volume beverage runs and regulated pharmaceutical serialization requirements.
- Beverage:Carbonated soft drinks, energy drinks, beer, and non-alcoholic alternatives. Aluminum can demand concentrates in Saudi Arabia, UAE, and Qatar where per-capita consumption and hot-climate distribution favor lightweight, chill-responsive formats. Digital printing adoption enables seasonal promotional variants without cylinder engraving lead times.
- Food:Processed tomatoes, evaporated milk, fish, and ready meals requiring retort sterilization. Tinplate cans dominate where 121-degree Celsius thermal stability is mandatory. Nigeria's industrial corridor shows accelerating format conversion from glass.
- Pharmaceuticals:Aluminum tubes and strip packs for ointments and unit-dose medications. Saudi Arabia's SFDA mandates migration testing for epoxy-based internal coatings, favoring suppliers with captive laboratory capabilities.
- Personal Care:Aerosol cans for deodorants, hair sprays, and household products. Casablanca-Rabat manufacturing clusters present underdeveloped demand for aluminum aerosol formats with crimped valve assemblies.
Beverage commands the volume throughput. Food is climbing the fastest as processors retool for steel can sterilization compatibility.
Form:
Structural rigidity versus collapsibility determines barrier performance, shipping cube efficiency, and end-user convenience.
- Rigid:Two-piece and three-piece cans, boxes, and drums maintaining dimensional stability under internal pressure or vacuum. Beverage and food applications dominate; rigid formats withstand stacking loads and automated filling line handling.
- Flexible:Collapsible tubes and semi-rigid foils for pharmaceutical and cosmetic dispensing. Aluminum barrier laminates compete with plastic alternatives on recyclability credentials.
- Aerosol:Pressurized aluminum containers with crimped valve assemblies for personal care and household propellant products. Moroccan and Egyptian manufacturing clusters show emerging demand concentration.
- Composite:Multi-material cans combining metal ends with fiber or plastic bodies. Limited penetration in Middle East and Africa due to recycling infrastructure complexity and EPR tracking challenges.
Rigid formats hold installed capacity across beverage and food. Aerosol is expanding most quickly as personal care contract manufacturing clusters mature.
Application:
Functional purpose dictates performance specifications, regulatory exposure, and customer service requirements.
- Packaging Solutions:Primary containment for shelf-stable consumer goods. Saudi Arabia's SFDA and South Africa's NRCS enforce mandatory performance standards for food-contact metal surfaces, with batch-level migration testing for epoxy coatings.
- Storage:Intermediate bulk containers and drums for industrial chemicals, lubricants, and edible oils. South Africa's petrochemical sector drives demand for reconditioned steel drum circuits.
- Transportation:UN-certified drums and intermediate bulk containers for hazardous material movement. Egypt's EOS and Nigeria's SON operate non-harmonized pre-shipment inspection regimes that delay arrivals at Alexandria and Lagos ports.
- Display:Decorative metal boxes for premium confectionery and gift packaging. Seasonal demand spikes around Ramadan and Christmas purchasing cycles in Gulf and Southern African markets.
Packaging solutions hold installed capacity for consumer-facing applications. Display is rotating up the share rankings as premium confectionery exporters invest in differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Can fabrication capacity clusters around Red Sea and Gulf ports, while African demand pulls supply toward Lagos and Johannesburg industrial corridors. Regulatory divergence between Saudi Arabia's SFDA migration testing and South Africa's extended producer responsibility creates compliance fragmentation. Coastal manufacturing nodes in Morocco and Egypt serve as alternative supply sources for Mediterranean-facing markets.
Saudi Arabia
Carbonated soft drink bottlers in Riyadh and Jeddah are expanding aluminum can procurement for hot-climate distribution networks. The SFDA mandates batch-level laboratory verification for epoxy-based internal coatings in food-contact applications. Jeddah's manufacturing base anchors aluminum beverage can supply across the Red Sea corridor.
United Arab Emirates
Per-capita beverage consumption in Dubai and Abu Dhabi drives demand for lightweight, chill-responsive aluminum formats. MOHAP operates food-contact material safety frameworks aligned with Gulf standardization initiatives. Dubai's logistics hub position enables regional distribution of imported metal packaging containers.
South Africa
Mandatory recycling targets under extended producer responsibility regulations create structured demand for steel cans with verified post-consumer recycled content. The National Regulator for Compulsory Specifications enforces performance standards for food-contact metal surfaces. Johannesburg-Pretoria industrial corridor hosts tinplate rolling and steel can fabrication capacity.
Nigeria
Food processors in Lagos industrial corridor are converting tomato paste and evaporated milk packaging from glass to tinplate retort-compatible formats. SON operates pre-shipment inspection regimes that delay non-compliant metal packaging arrivals at Lagos ports. Lagos manufacturing clusters show accelerating steel can adoption for sterilization-intensive food applications.
Egypt
Alexandria and Cairo manufacturing bases serve Mediterranean-facing demand for metal boxes in date exports and seasonal confectionery. EOS import inspection protocols create port entry friction for non-compliant container shipments. Casablanca-Rabat corridor competition drives Egyptian aerosol can investment in personal care contract manufacturing.
Middle East and Africa Metal Packaging Market Competitive Landscape
Integrated regional fabricators and multinational technical service providers split the market between localized supply security and global technology transfer. Saudi Arabian and South African players anchor capacity ownership through backward integration into tinplate rolling and coating validation infrastructure. Three archetypes dominate: Gulf-based beverage can specialists with captive laboratory capabilities, Southern African steel food can integrators with retort-format expertise, and multinational tooling service operators with regional refurbishment centers. Competitive moves concentrate on deposit-return infrastructure partnerships and digital printing technology licensing.
Among Gulf-based fabricators, SAPIN Saudi Arabian Packaging Industry Co. Ltd. and Saudi Can Co. represent the integrated beverage can archetype with Jeddah manufacturing concentration. South Africa's Nampak Limited exemplifies the steel food can specialist position through upstream control over tinplate rolling. Crown Holdings, Inc. occupies the multinational technical service tier with regional refurbishment center operations.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Ball Corporation |
| SAPIN Saudi Arabian Packaging Industry Co. Ltd. |
| Avon Crowncaps and Containers Nigeria Ltd. |
| Nampak Limited |
| CANPACK S.A. |
| Mahmood Saeed Beverage Cans and Ends Industry Co. Ltd. |
| Saudi Can Co. |
| Dayal Metal Containers Factory LLC |
| Others |
Pricing and Supply Chain Analysis
Cold-rolled steel and tin coating supply concentration in China and South Korea directly determines margin distribution for African can fabricators serving price-sensitive tomato paste and evaporated milk processors. Input cost volatility at the upstream tier compresses predictability for regional converters while deposit-return infrastructure investments reshape downstream contracting terms.
Pricing Analysis
After-sales revenue from collection-reverse logistics partnerships and refurbishment services drives lifetime value for integrated metal packaging suppliers. Three-tier pricing structure across premium certified, standard compliance, and economy import tiers separates fabricators with captive SFDA laboratory capabilities from smaller distributors facing batch-level migration testing cost burdens. Pricing pressure stems from cold-rolled steel commodity index fluctuations and Egyptian EOS pre-shipment inspection delays extending working capital cycles. Price-sensitive African food processors in Nigeria's Lagos corridor negotiate spot contracts, while Gulf beverage bottlers prioritize chill-responsive aluminum formats with verified recyclability credentials.
Supply Chain Analysis
Tariff exposure between Gulf Cooperation Council member states and non-harmonized extended producer responsibility frameworks dominates supply chain risk planning for regional metal packaging distributors. Manufacturing gravity centers on Saudi Arabia's Jeddah corridor, South Africa's Johannesburg-Pretoria industrial belt, and Egypt's Alexandria port zone for Mediterranean-facing markets. Raw material dependencies draw from Chinese cold-rolled steel, Indonesian tin ingot, and European epoxy coating chemistries. Distribution runs through Red Sea and Gulf port clusters with Lagos and Alexandria serving as African demand anchors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent metal packaging suppliers face substitution pressure from fiber-based and flexible plastic alternatives as extended producer responsibility frameworks tighten recyclability mandates across Gulf and African markets.
For Market Incumbents: Pre-empt format displacement by securing backward integration into tinplate rolling and captive coating validation infrastructure. Anchor supply contracts through integrated collection-reverse logistics partnerships as deposit-return schemes restructure GCC procurement terms. Defend against flexible packaging substitution by emphasizing retort-compatible steel thermal performance and infinite aluminum recyclability credentials. For New Entrants and Emerging Players: Moroccan aerosol manufacturing clusters in the Casablanca-Rabat corridor represent the most penetrable entry point for aluminum crimped-valve assembly supply. Nigerian steel can conversion demand from glass-dependent tomato paste processors offers white-space volume for retort-format specialists. Enter through digital printing technology licensing partnerships that eliminate cylinder engraving capital barriers for seasonal beverage promotional runs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Gulf-based beverage can specialists holding Jeddah manufacturing concentration and SFDA-compliant laboratory infrastructure. Five-to-ten year viability hinges on extended producer responsibility harmonization completion across GCC member states. Monitor regulatory implementation timelines as the primary inflection signal for collection infrastructure investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tinplate Rolling | Nampak Limited's upstream control secures margin capture for Southern African food processors. |
| Digital Printing Technology Licensing | Crown Holdings' inkjet decoration systems enable Dubai beverage brands' limited-edition promotional agility. |
| Deposit-Return Infrastructure Partnership | SAPIN's Jeddah base positions for first-mover GCC extended producer responsibility compliance. |
| Captive Coating Validation Investment | In-house SFDA laboratory capabilities redirect multinational food processor procurement decisions. |
| Retort Equipment Scale-Up | Lagos corridor steel can adoption accelerates with horizontal sterilization system availability. |
Research Methodology
Operator-level perspectives from beverage filling line engineers, food processor procurement managers, coating chemists, and GCC regulatory compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from Saudi SFDA migration testing protocols, South Africa NRCS performance standards, Egyptian EOS import inspection records, and Nigerian SON pre-shipment documentation. Customs and trade flow data, SEC filings of multinational packaging suppliers, and regional petrochemical sector drum refurbishment records provided quantitative anchors. Bottom-up can fabrication capacity estimates and top-down beverage consumption projections were triangulated for consistency.
Scenario-bracketing around regulatory implementation pace and commodity price volatility informed the analytical framework across the projection horizon. Segmentation dimensions modeled include material composition tier, end-use thermal requirement, coating chemistry specification, and regional regulatory cluster. CAGRs were derived from volume throughput projections weighted by per-capita consumption patterns and format conversion timelines. Retort sterilization adoption curves and digital printing penetration rates served as industry-specific forecast inputs.
Practitioners should monitor GCC extended producer responsibility harmonization progress, cold-rolled steel commodity index movements, and SFDA coating migration testing protocol amendments for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Aluminum Foil Packaging Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
Metal Aerosol Packaging Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Metal Cans Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Tin Cans Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
Beverage Metal Cans Market