
 Metal Aerosol Packaging Market | 2026-2036
Metal Aerosol Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Aerosol Packaging Market Foresight
Asset-light leasing models for can-coating lines is reconfiguring capital barriers for mid-tier entrants. Crown Holdings, Inc. leverages captive aluminum supply to anchor cost positions across North American personal care contracts. Ball Corporation sustains technical leadership through in-house valve engineering capabilities. Silgan Holdings Inc. competes on specialty can geometries for precision-dose pharmaceutical applications.
Metal aerosol packaging comprises pressurized containers fabricated from aluminum or tinplate, typically ranging from 100 ml to 750 ml capacity, designed to dispense products through a metered valve system using liquefied or compressed gas propellants. These containers serve essential functions in product preservation, controlled dosage delivery, and shelf-life extension across consumer and industrial applications. Personal care aerosols dominate volume throughput due to established deodorant and hair-spray consumption patterns, while specialty cans command premium positioning through barrier-laminated interiors that protect reactive formulations. Pump spray alternatives within valve technology are gaining traction as propellant-free options respond to volatile organic compound scrutiny.
EPA regulates volatile organic compound emissions from consumer product aerosols under 40 CFR 59, while REACH governs chemical substance registration and restriction thresholds across European manufacturing. FDA oversight applies to drug-delivery aerosols, requiring container-leachate testing and stability documentation for pharmaceutical approvals. Stakeholders must monitor evolving propellant substitution pathways and regional recycling infrastructure investments to preserve format competitiveness against plastic alternatives.
Market Dynamics
REACH volatile organic compound thresholds are compressing formulation flexibility across European manufacturing, forcing propellant substitution investments that reshape cost structures and supplier relationships throughout the value chain.
Growth Catalysts
- Sustainable dispensing formats:Personal care brands are converting plastic pump systems to aluminum aerosols for circularity credentials and shelf differentiation in mass retail channels.
- REACH compliance deadlines:Tightening volatile organic compound thresholds in Europe are accelerating capital deployment into low-emission propellant infrastructure and barrier-laminated can interiors.
- Manufacturing cluster consolidation:Production capacity is concentrating in Germany, China, and Brazil, generating scale economies that reduce per-unit coating and forming costs for regional contract customers.
Market Restraints
- Aluminum ingot price volatility:Input cost swings for primary metal squeeze margin predictability for converters without captive smelter arrangements or long-term hedge positions.
- Tinplate supply concentration:Three integrated steel producers control the majority of food-grade electrolytic tinplate output, creating vulnerability to regional mill maintenance cycles and tariff disruptions.
- Pump spray substitution:Propellant-free mechanical alternatives are capturing dermatological and infant care segments where volatile organic compound scrutiny is most intense.
Strategic Opportunities
- Precision-dose pharmaceuticals:Metered valve engineering for inhalation therapies and topical sprays offers premium pricing power through barrier-laminated interiors that protect reactive formulations.
- EU Green Deal circularity mandates:Packaging Extended Producer Responsibility fee structures favor infinitely recyclable aluminum formats over multi-layer plastic competitors in personal care and household categories.
- Industrial maintenance aerosols:Penetration remains shallow in agricultural equipment and marine coating touch-up applications where solvent-based spray delivery dominates manual brush methods.
Industry Challenges
- Valve engineering talent scarcity:Specialized competence in metered-dose mechanism design and propellant compatibility testing concentrates within a handful of technical centers, constraining new product development velocity.
- Coating line certification timelines:FDA container-leachate documentation and stability protocol validation for pharmaceutical approvals extend commercialization cycles by 18-24 months versus cosmetic equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Aerosol Packaging Market |
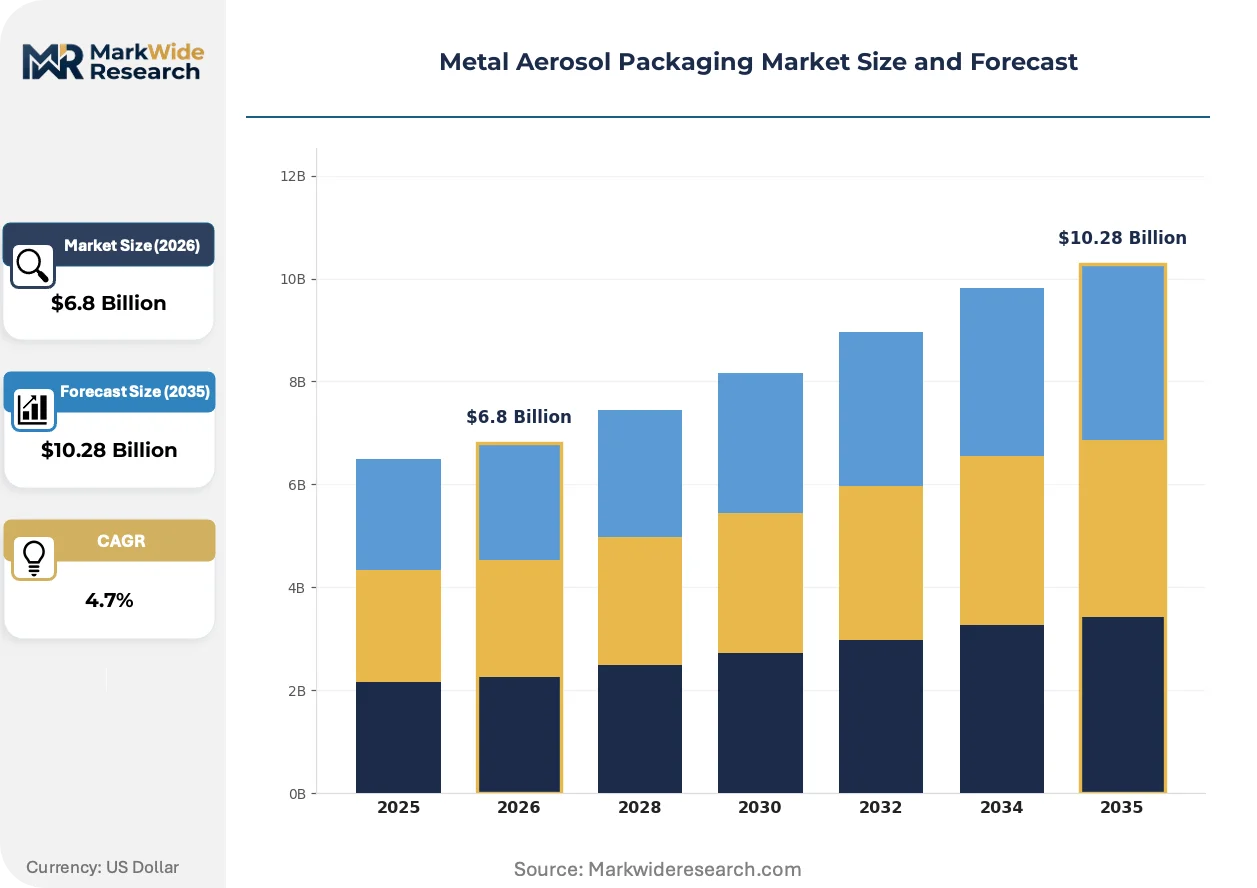
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Paints, Personal Care, Household Products End User: Consumer Goods, Automotive, Food & Beverage, Industrial Technology: Aerosol Spray, Pump Spray, Valve Technology, Propellant Type Packaging Type: Standard Cans, Specialty Cans, Refillable Containers, Dispensers |
| Companies Covered | Crown Holdings, Inc., Ball Corporation, Ardagh Group, CCL Industries Inc., Trivium Packaging, Silgan Holdings Inc., Toyo Seikan Co. Ltd., Exal Corporation, Nampak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Aerosol Packaging Market Shifts & Advancements
Propellant chemistry and valve architecture are undergoing simultaneous transformation as regulatory pressure intersects with brand sustainability commitments, compressing the viable technology set and rewarding early movers with differentiated positioning.
Barrier-laminated aluminum interiors are migrating from pharmaceutical and food-grade applications into premium personal care segments. Deodorant and hair-spray brands in North America and Western Europe are adopting epoxy-phenolic and nylon-based interior coatings to enable water-based and dimethyl ether propellant formulations. This migration from standard unlined aluminum is enabling volatile organic compound reductions of 50-70% while preserving shelf stability for sensitive active ingredients.
EPA 40 CFR 59 volatile organic compound regulations are tightening maximum permissible emissions for consumer product aerosols in the United States. The industrial consequence is accelerated reformulation toward hydrofluorocarbon-152a and compressed nitrogen propellant systems that require redesigned valve flow rates and actuator geometries. Household insecticide and air freshener categories face the most immediate compliance pressure, with manufacturers investing in dual-compartment bag-on-valve systems to separate propellant from product.
Brand procurement departments are consolidating supplier relationships around converters with integrated coating, printing, and valve assembly capabilities. Personal care multinationals are reducing their approved vendor lists from 15-20 regional suppliers to 4-6 strategic partners capable of managing formulation compatibility testing and regulatory documentation. This consolidation is most visible in Germany and Brazil, where manufacturing scale and technical service proximity determine contract awards for pan-European and Latin American product launches.
Metal Aerosol Packaging Market Segmentation
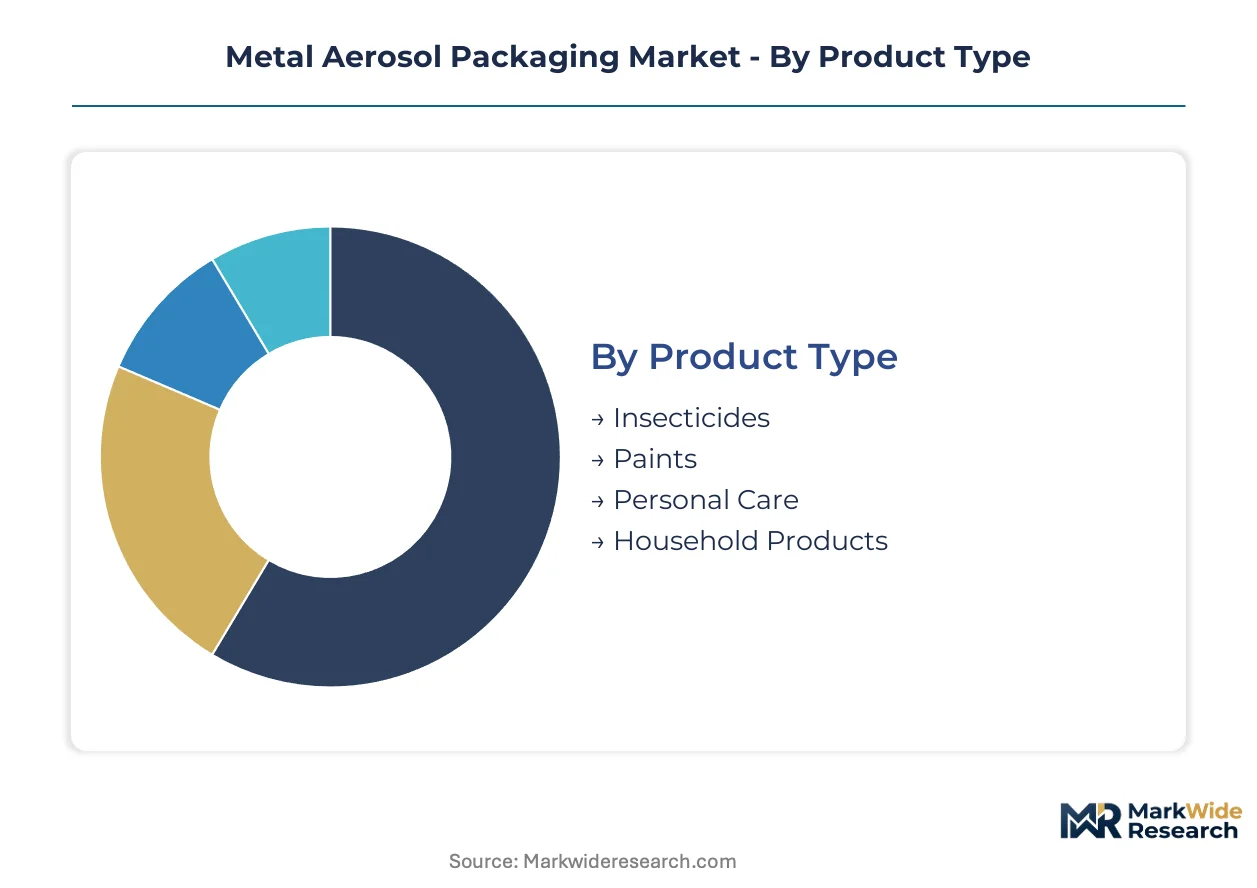
Segmentation in metal aerosol packaging reveals how formulation chemistry, dispensing mechanics, and end-use durability requirements create distinct technical specifications and margin profiles across converter portfolios.
Product Type:
Application chemistry determines interior coating specifications, propellant compatibility testing protocols, and regulatory documentation burdens.
- Personal Care:Deodorant and hair-spray formulations dominate aluminum consumption through unlined and epoxy-phenolic coated interiors. Demand clusters in Germany and Brazil as mass retail chains prioritize shelf differentiation through metallic substrates over plastic alternatives.
- Household Products:Air fresheners and cleaners require barrier-laminated can interiors to prevent corrosion from aggressive solvents. EPA 40 CFR 59 volatile organic compound thresholds are forcing compressed nitrogen and bag-on-valve system adoption across US manufacturing.
- Insecticides:Pyrethroid-based formulations necessitate specialized interior coatings and extended stability documentation.
- Paints:Touch-up spray applications for automotive and marine maintenance demand higher-pressure tolerance and solvent-resistant valve seals.
Personal Care commands the established base. The steepest expansion runs through Household Products as regulatory pressure accelerates sustainable format conversion.
End User:
Customer procurement scale and technical service requirements separate commodity contract terms from premium partnership structures.
- Consumer Goods:Mass-market personal care and household brands drive volume throughput through consolidated supplier relationships. REACH compliance documentation and circularity credentials determine contract awards for pan-European launches from German manufacturing clusters.
- Automotive:Aftermarket lubricants and touch-up paints require precision valve engineering for controlled dosage in maintenance applications. Demand concentrates in North American and Chinese automotive service networks.
- Industrial:Equipment maintenance sprays penetrate agricultural and marine sectors where solvent-based delivery replaces manual brush application.
- Food & Beverage:Whipped cream and cooking spray applications demand food-grade interior coatings and FDA container-leachate testing protocols.
Consumer Goods anchors volume throughput. Automotive applications are climbing the fastest as precision-dose valve engineering commands premium positioning.
Technology:
Dispensing mechanics and propellant chemistry represent the primary axes of regulatory compliance and sustainability differentiation.
- Propellant Type:Hydrofluorocarbon-152a, dimethyl ether, and compressed nitrogen systems require redesigned valve flow rates and actuator geometries to maintain spray performance. EPA and REACH thresholds are compressing viable formulation sets and rewarding early infrastructure investment.
- Valve Technology:Metered-dose mechanisms for pharmaceutical and personal care applications concentrate specialized engineering competence within technical centers in Germany and Switzerland.
- Aerosol Spray:Conventional liquefied gas systems face substitution pressure in dermatological and infant care segments.
- Pump Spray:Propellant-free mechanical alternatives capture volatile organic compound-sensitive applications through actuator compression rather than pressurized gas.
Conventional aerosol spray retains the installed base. Compressed gas and mechanical pump alternatives are gaining share fastest as regulatory scrutiny intensifies.
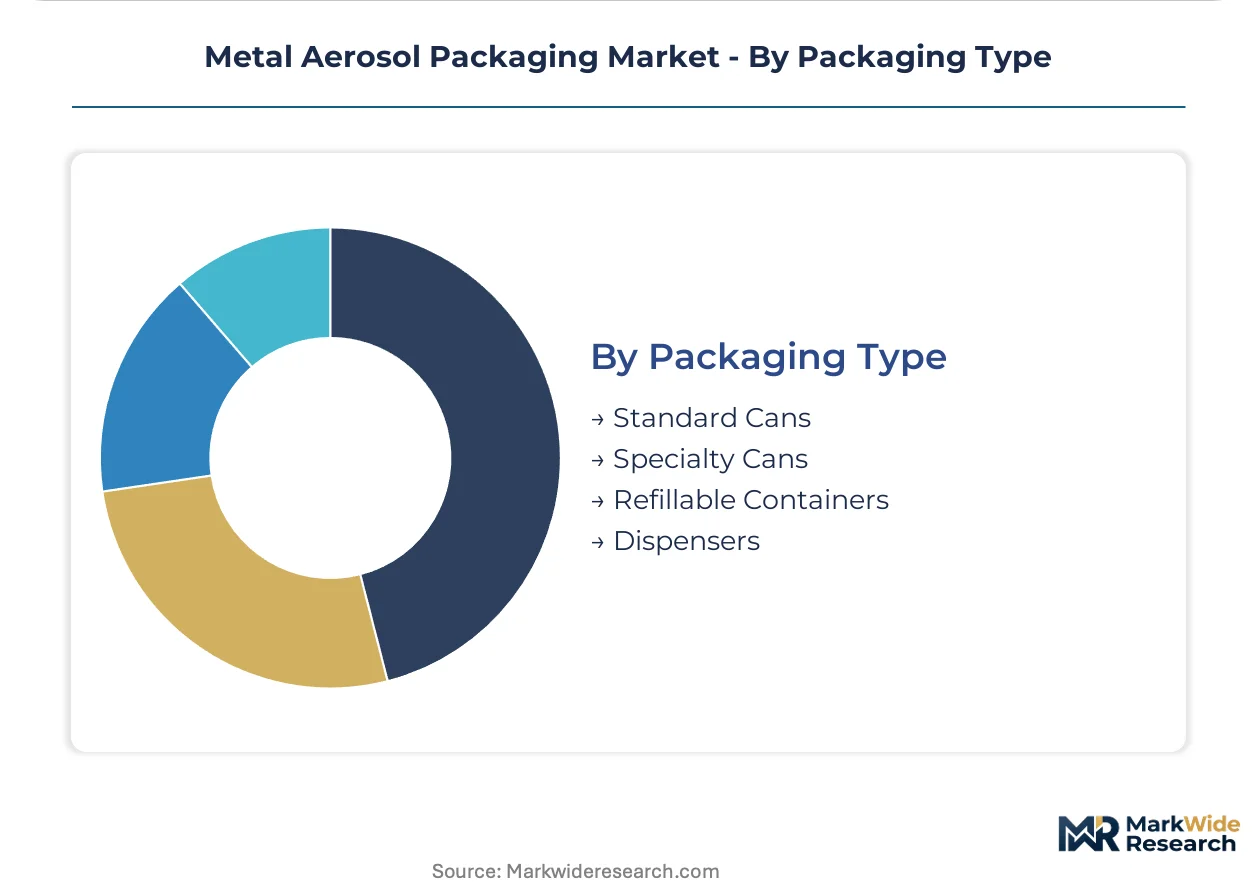
Packaging Type:
Container geometry and barrier properties segment converter capabilities between commodity throughput and specialty premium positioning.
- Standard Cans:Unlined aluminum cylinders for personal care deodorants and hair-sprays generate scale economies through high-speed forming and coating lines. Brazil and China manufacturing clusters compete on coating cost and logistics proximity to regional brand headquarters.
- Specialty Cans:Barrier-laminated interiors with epoxy-phenolic or nylon-based coatings protect reactive pharmaceutical and household formulations. FDA stability documentation extends commercialization cycles versus cosmetic equivalents.
- Dispensers:Bag-on-valve systems separate propellant from product for sensitive formulations.
- Refillable Containers:Circular economy pilots concentrate in EU Green Deal Extended Producer Responsibility frameworks.
Standard cans dominate unit economics. Specialty barrier-laminated formats are expanding most quickly as formulation complexity and regulatory compliance tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal Extended Producer Responsibility fee structures favor infinitely recyclable aluminum formats across member states. Brazil and China manufacturing clusters generate scale economies through coating and forming cost reductions. German technical centers concentrate valve engineering competence for pharmaceutical applications.
Germany
REACH volatile organic compound thresholds compress formulation flexibility for deodorant and hair-spray producers. ECHA registration requirements govern chemical substance documentation for propellant substitutions. Manufacturing concentrates in North Rhine-Westphalia where coating line certification timelines extend pharmaceutical commercialization cycles.
China
Dual carbon goals accelerate compressed nitrogen propellant infrastructure investment across personal care manufacturing. SAMR standards govern aerosol product safety and labeling for domestic consumption. Yangtze River Delta clusters compete on logistics proximity to regional brand headquarters for pan-Asian distribution.
Brazil
ANVISA pharmaceutical regulations require container-leachate testing for metered-dose inhalation therapies. Mass retail chains prioritize shelf differentiation through metallic substrates over plastic alternatives. São Paulo manufacturing bases supply coating cost advantages for Latin American contract customers.
United States
EPA 40 CFR 59 volatile organic compound regulations tighten maximum permissible emissions for household insecticide and air freshener categories. FDA oversight applies to drug-delivery aerosols requiring stability documentation. Midwest forming facilities anchor North American personal care contract volumes.
India
BIS standards govern aerosol container pressure testing and material specifications for domestic market entry. PLI scheme incentives attract coating line investment for export-oriented pharmaceutical can production. Maharashtra industrial corridors develop barrier-laminated capabilities for water-based propellant formulations.
Metal Aerosol Packaging Market Competitive Landscape
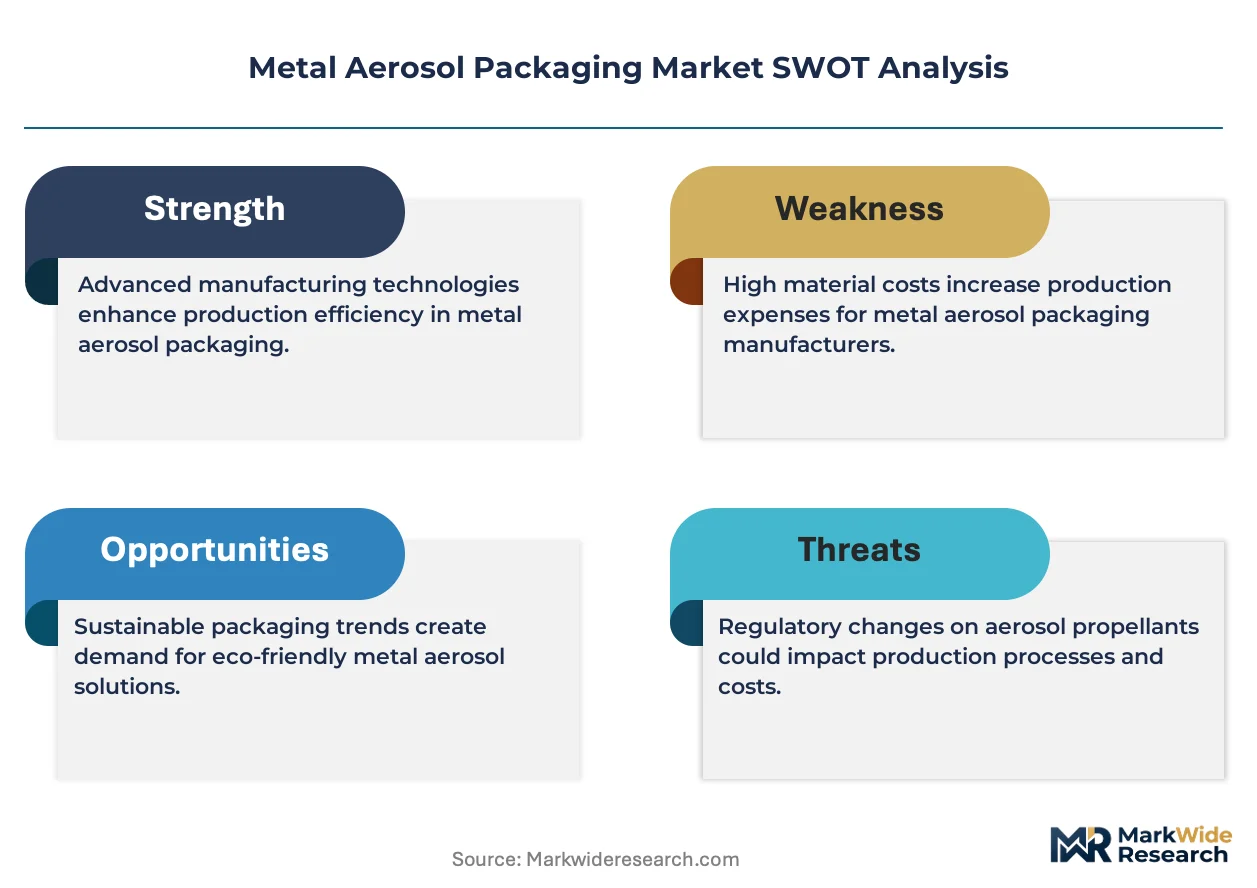
On the supply side, the industry is consolidating around converters with integrated coating, printing, and valve assembly capabilities. Three strategic archetypes dominate: integrated aluminum smelter-converters with captive metal supply, specialty can engineers focused on barrier-laminated pharmaceutical formats, and regional scale players competing on logistics proximity. Dominant competitive moves include backward integration into primary aluminum supply and geographic expansion through asset-light leasing models for coating lines.
Within the integrated converter tier, Crown Holdings, Inc. and Ball Corporation represent archetypes of scale-driven positioning through North American supply chain control. Silgan Holdings Inc. occupies a specialist position among premium-tier fabricators focused on precision-dose geometries. Trivium Packaging anchors European technical service capabilities for REACH-compliant formulation support.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Ball Corporation |
| Ardagh Group |
| CCL Industries Inc. |
| Trivium Packaging |
| Silgan Holdings Inc. |
| Toyo Seikan Co. Ltd. |
| Exal Corporation |
| Nampak Ltd. |
| Others |
Supply & Pricing Matrix
Aluminum ingot price volatility determines both pricing tier spreads and supply chain shape across metal aerosol packaging. Converters without captive smelter arrangements face margin compression that forces tier separation between integrated and non-integrated suppliers.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and cosmetic-grade can production. FDA container-leachate documentation and stability protocol validation extend commercialization cycles, commanding premium pricing for barrier-laminated specialty formats. Pricing pressure stems from REACH volatile organic compound compliance investments that reshape propellant infrastructure costs. Mass-market personal care brands exhibit highest price sensitivity, while pharmaceutical contract customers accept premium positioning for precision-dose valve engineering.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for aluminum sheet and coil inputs. Primary metal supply concentrates in China, Russia, and Canada, with coating chemical dependencies drawing from German and Swiss specialty chemical producers. Single-source vulnerability concentrates in food-grade electrolytic tinplate output controlled by three integrated steel producers. Distribution runs through consolidated converter networks with integrated coating, printing, and valve assembly capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, REACH, and national pharmaceutical authorities creates specialized service niches for converters with compliance documentation capabilities.
For Market Incumbents: Pre-empt pump spray substitution threats by accelerating barrier-laminated interior capacity for water-based propellant formulations. Backward integration into primary aluminum supply secures cost positions against ingot volatility. Crown Holdings and Ball Corporation anchor North American contracts through captive metal supply and in-house valve engineering respectively. For New Entrants and Emerging Players: Establish a beachhead in precision-dose pharmaceutical applications where FDA stability documentation extends commercialization cycles and deters commodity competitors. Industrial maintenance aerosols for agricultural equipment and marine coating touch-up offer shallow penetration with solvent-based spray delivery advantages. Partner with regional brand headquarters in São Paulo or the Yangtze River Delta for logistics-proximity contract awards. For Investors and Strategic Acquirers: REACH volatile organic compound threshold tightening reshapes the acquisition landscape toward converters with low-emission propellant infrastructure. Long-term viability hinges on circular economy positioning under EU Green Deal Extended Producer Responsibility frameworks. Monitor bag-on-valve system adoption rates in household insecticide and air freshener categories as inflection indicators for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Laminated Capacity Expansion | Enables water-based propellant formulations for REACH and EPA compliance in personal care. |
| Backward Integration into Primary Aluminum | Crown Holdings leverages captive supply to anchor cost positions across North American contracts. |
| Precision-Dose Valve Engineering Investment | Silgan Holdings commands premium positioning through specialty can geometries for pharmaceutical applications. |
| Asset-Light Coating Line Leasing | Reconfigures capital barriers for mid-tier entrants seeking regional manufacturing scale. |
| Regulatory Documentation Service Expansion | Trivium Packaging anchors European technical service capabilities for ECHA registration support. |
Research Methodology
A standing panel of coating line operations managers, pharmaceutical packaging procurement leads, personal care brand supply chain directors, and aerosol valve engineering specialists provided ongoing calibration. Primary interviews combined with secondary validation from EPA 40 CFR 59 filings, ECHA registration databases, FDA drug approval documentation, and customs trade data for aluminum sheet and coil movements. Bottom-up unit economics and top-down market sizing underwent iterative triangulation.
Scenario-bracketing framed demand projections across the analysis window. Segmentation dimensions included product type chemistry requirements, end-user procurement scale, propellant technology compliance tiers, and packaging format barrier specifications. CAGRs derived from regression analysis against aluminum consumption patterns and propellant infrastructure investment cycles. Forecast inputs incorporated REACH threshold implementation timelines and EU Green Deal Extended Producer Responsibility fee structures.
Stress conditions across aluminum ingot price bands, tariff regime shifts, and propellant substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and recycling infrastructure investments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Metal Drums Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
India Metal Cans Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
Pressurized Metal Containers Market