
 Egypt Metal Packaging Market | 2026-2036
Egypt Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Metal Packaging Market Foresight
Lightweighting technology is fragmenting traditional steel-heavy production paradigms across Egyptian metal packaging facilities. Ball Beverage Packaging leverages advanced draw-and-wall-ironing lines to anchor aluminum can supply for carbonated soft drink bottlers. Greif Inc. sustains drum manufacturing scale through backward integration into steel coil processing near Suez Canal Economic Zone. Ghandour Brothers Metal Industries (Gcan) competes on regional export routes into Sub-Saharan Africa with coated tinplate containers.
Egypt metal packaging encompasses rigid containers fabricated from aluminum, steel, and tin substrates through deep drawing, three-piece welding, or impact extrusion processes, engineered to provide barrier protection against oxygen, moisture, and light for shelf-stable goods. Cans command the largest product type position, driven by beverage sector pull and recyclability premiums, while drums retain industrial chemical and edible oil storage dominance. Aluminum leads material growth trajectories due to its superior strength-to-weight ratio and established local recycling infrastructure.
Egypt's General Organization for Export and Import Control (GOEIC) enforces mandatory quality inspections on imported metal packaging substrates, while the Egyptian Organization for Standardization and Quality (EOS) maintains local specifications aligned with ISO 9001 and food contact material safety frameworks. Compliance with these regimes determines market access for both domestic fabricators and foreign suppliers. Stakeholders must monitor forthcoming extended producer responsibility regulations and aluminum scrap purity standards that will reshape sourcing economics and recycling network investments.
Market Dynamics
Aluminum lightweighting is forcing capital reallocation across Egyptian metal packaging facilities as beverage producers abandon steel substrates for draw-and-wall-ironing lines. This substrate pivot concentrates procurement power among can fabricators with captive coil supply.
Growth Catalysts
- BIS-equivalent conformity assessments:Egyptian GOEIC enforcement tightens quality thresholds for imported steel substrates, accelerating domestic aluminum can sourcing by Greater Cairo bottlers.
- Edible oil sector pull:Alexandria food processors anchor drum procurement volumes as regional export demand into Sub-Saharan Africa expands.
- Recyclability premiums:Established local aluminum scrap infrastructure lowers effective material costs for beverage packaging versus virgin steel inputs.
Market Restraints
- Steel coil import dependency:Drum manufacturers face input cost volatility from Suez Canal transit disruptions and foreign exchange exposure.
- Substrate switching capex:Three-piece welding lines require full replacement to accommodate aluminum draw-and-wall-ironing, straining mid-tier fabricator balance sheets.
- Tinplate substitution pressure:Coated steel containers for regional export routes face price competition from plastic barrier packaging in price-sensitive African markets.
Strategic Opportunities
- Extended producer responsibility regulations:Forthcoming Egyptian aluminum scrap purity standards will reward early investments in closed-loop recycling networks.
- Suez Canal Economic Zone backward integration:Greenfield steel coil processing capacity can capture import substitution premiums for drum and industrial container supply.
- Sub-Saharan Africa route expansion:Coated tinplate container exports through Port Sudan and Djibouti corridors remain underpenetrated versus Middle Eastern competitors.
Industry Challenges
- Draw-and-wall-ironing technician scarcity:Egyptian technical institutes lack curricula for advanced aluminum can forming, constraining line expansion timelines.
- Multi-substrate certification complexity:EOS food contact material safety frameworks require parallel testing protocols for steel and aluminum, extending product launch cycles.
- Legacy three-piece line stranding:Depreciated welding equipment lacks secondary market liquidity, complicating asset-light transitions to aluminum.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Metal Packaging Market |
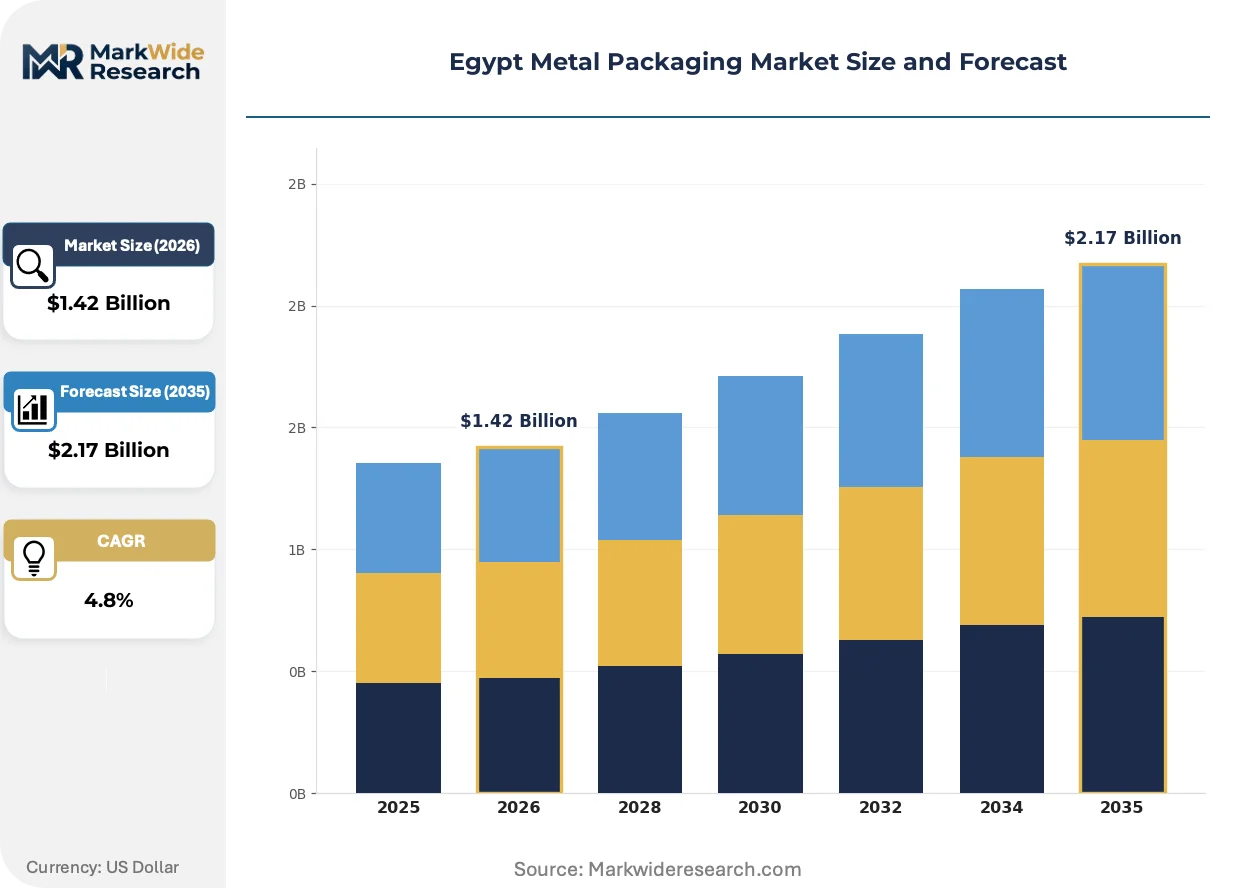
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Drums, Containers, Foils Material: Aluminum, Steel, Tin, Others End User: Food, Beverage, Pharmaceuticals, Personal Care Application: Storage, Transportation, Packaging, Recycling |
| Companies Covered | Greif Inc., Willy Group, Ball Beverage Packaging, Ghandour Brothers Metal Industries (Gcan), El Sharkia Packing Co., Alfouad Packaging, CairoPac, GOHARYMET, Alexmetal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Metal Packaging Market Shifts & Advancements
Digital print direct-to-metal decoration is collapsing traditional label-based branding economics across Egyptian beverage packaging. This shift compresses minimum order quantities and accelerates SKU proliferation for regional bottlers.
High-speed aluminum draw-and-wall-ironing is collapsing steel's historical dominance in carbonated soft drink packaging. Egyptian bottlers in 10th of Ramadan City are retrofitting lines at 18-month cycles. The technology is collapsing batch size economics and enabling seasonal promotional runs previously uneconomical under three-piece steel workflows.
Egyptian Organization for Standardization and Quality alignment with ISO 9001 food contact frameworks is tightening substrate traceability mandates. Fabricators must now document smelter origin for aluminum coil and mill certification for tinplate. Beverage can segments face the steepest compliance cost escalation as end-to-end chain-of-custody documentation becomes mandatory for Alexandria export clearances.
Direct mill relationships are displacing distributor-mediated steel coil procurement among drum manufacturers. Large edible oil processors in Borg El-Arab now specify melt shop origin in tender documents. This concentration of buying power is most visible in industrial chemical storage contracts, where procurement teams audit supplier vertical integration depth before award.
Egypt Metal Packaging Market Segmentation
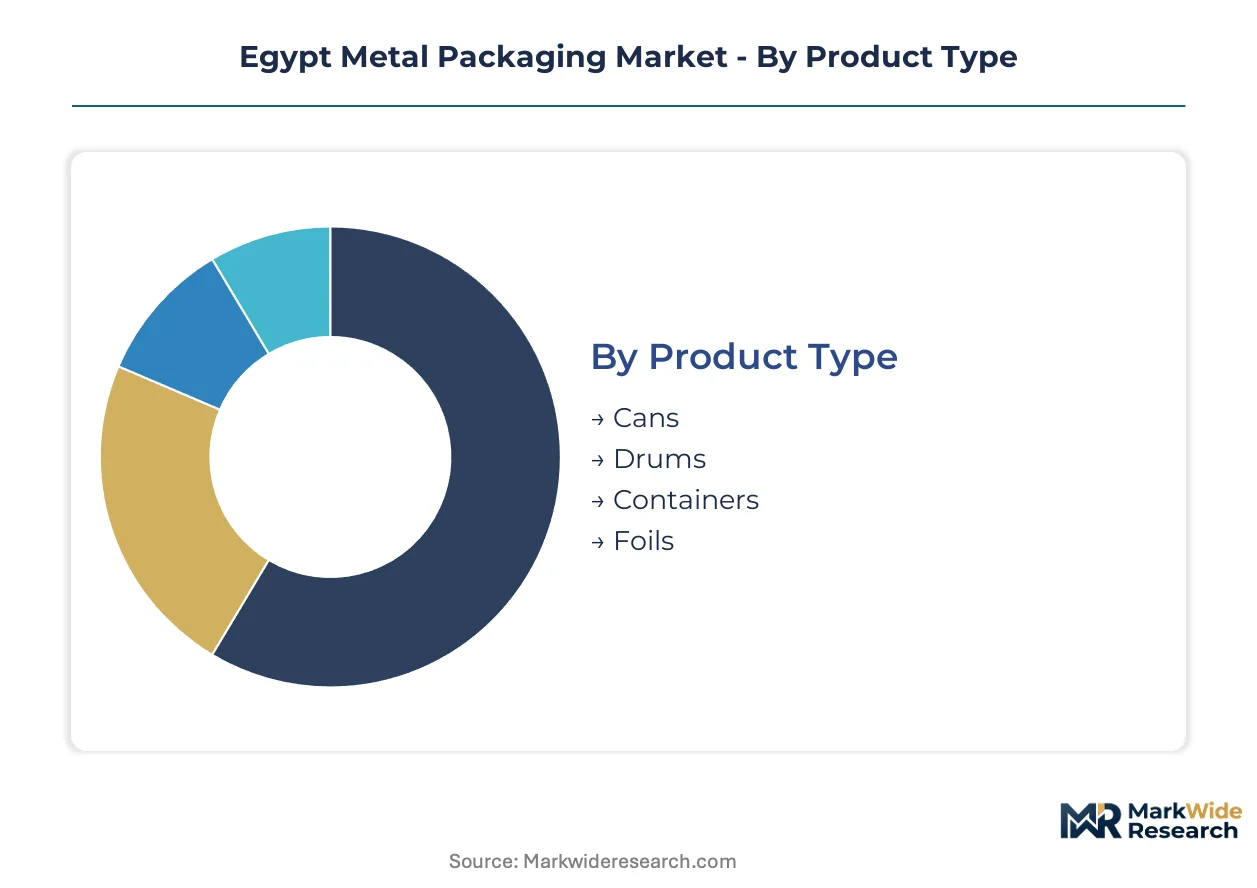
Egypt's metal packaging landscape fragments across substrate technologies, end-use specifications, and regulatory compliance tiers. Fabricators configure production lines around specific material-product combinations that determine barrier performance, recyclability economics, and GOEIC import clearance requirements.
Product Type:
Volume concentration across Egyptian fabrication facilities maps directly to beverage sector procurement cycles and industrial chemical storage contracts.
- Cans:Draw-and-wall-ironing aluminum bodies with necked-in ends provide carbonation retention for Greater Cairo soft drink bottlers. Ball Beverage Packaging operates multiple high-speed lines serving Coca-Cola Egypt and local private label producers, with scrap closed-loop agreements reducing effective aluminum input costs.
- Drums:Welded steel cylindrical containers with rolling hoops and clamp-ring closures store edible oils and industrial chemicals. Alexandria's Borg El-Arab industrial zone hosts concentrated drum demand from soybean oil processors exporting through Dekheila Port.
- Containers:Rectangular and cylindrical tinplate boxes with double-seamed lids serve processed food and aerosol applications. Coated steel substrates face plastic substitution pressure on Sub-Saharan Africa export routes.
- Foils:Rolled aluminum thin-gauge sheets provide household wrap and pharmaceutical blister pack substrates. Local rolling capacity near 10th of Ramadan City supplies confectionery and dairy processors.
Cans hold installed capacity. Drums are rotating up the share rankings.
Material:
Application requirements determine substrate selection across Egyptian packaging procurement, with barrier properties, weight economics, and EOS food contact compliance driving specification.
- Aluminum:Draw-and-wall-ironing grade coil with H19 temper specifications enables two-piece can fabrication. GOEIC's BIS-equivalent conformity assessments on imported steel accelerate aluminum sourcing shifts among beverage producers.
- Steel:Cold-rolled coil with tin or polymer coating provides drum bodies and three-piece can components. Suez Canal transit disruptions and foreign exchange volatility strain input cost predictability for drum manufacturers.
- Tin:Electrolytic tinplate with differential coating weights serves corrosion-sensitive food containers. Regional export demand through Port Sudan corridors sustains coated tinplate container production.
- Others:Stainless steel and specialty alloys address pharmaceutical and high-purity chemical applications. Limited local fabrication capacity forces reliance on imported formed components.
Steel holds installed capacity. Aluminum is rotating up the share rankings.
End User:
Customer type concentration reflects Egypt's consumer goods manufacturing base and pharmaceutical production corridors.
- Food:Processed vegetable, dairy, and confectionery processors in Alexandria and 10th of Ramadan City specify coated tinplate and aluminum foil barriers. EOS traceability mandates now require documented smelter origin for aluminum coil used in export-bound packaging.
- Beverage:Carbonated soft drink and juice bottlers anchor aluminum can demand. Retrofitting timelines for draw-and-wall-ironing lines average 18 months due to technician scarcity at Egyptian technical institutes.
- Pharmaceuticals:Blister packs and aerosol cans require high-purity aluminum and compliance with CDSCO-aligned standards for regional export. Cairo's Obour City pharmaceutical cluster drives specification intensity.
- Personal Care:Aerosol dispensers and cosmetic tins utilize impact-extruded aluminum and drawn steel. Smaller batch sizes favor digital direct-to-metal decoration technologies.
Food holds installed capacity. Beverage is rotating up the share rankings.
Application:
Functional use case determines structural specifications, with load-bearing and barrier requirements varying sharply across the value chain.
- Storage:Long-term containment of edible oils and industrial chemicals demands drum integrity under thermal cycling. Borg El-Arab processors now specify melt shop origin in steel coil tender documents.
- Transportation:Stackable drum designs and reinforced can pallets withstand Suez Canal logistics corridors and Sub-Saharan Africa overland routes. Container corner casting compatibility governs intermodal specifications.
- Packaging:Point-of-sale presentation drives decoration technology selection, with direct-to-metal digital print collapsing traditional label economics. SKU proliferation accelerates among regional bottlers.
- Recycling:Closed-loop aluminum scrap recovery lowers effective material costs for beverage packaging. Forthcoming Egyptian aluminum scrap purity standards will reshape collection network investments.
Packaging holds installed capacity. Recycling is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's metal packaging trade balance tilts toward import dependency for high-grade aluminum coil and cold-rolled steel, while fabricated container exports into Sub-Saharan Africa generate foreign exchange offsets. The country's Suez Canal corridor positioning shapes regional procurement routing for drum manufacturers serving North African edible oil processors.
Greater Cairo
Carbonated soft drink bottlers in 10th of Ramadan City and Obour City drive aluminum can consumption through retrofitted draw-and-wall-ironing lines. GOEIC's BIS-equivalent conformity assessments on imported steel substrates accelerate substrate switching toward domestic aluminum sourcing. Ball Beverage Packaging operates multiple high-speed fabrication lines serving Coca-Cola Egypt and private label producers.
Alexandria
Borg El-Arab industrial zone anchors drum demand from soybean oil processors exporting through Dekheila Port to Sub-Saharan African markets. EOS traceability mandates now require documented smelter origin for aluminum coil used in export-bound packaging. Large edible oil processors specify melt shop origin in steel coil tender documents, concentrating procurement power among vertically integrated suppliers.
Suez Canal Economic Zone
Backward integration opportunities into steel coil processing attract drum manufacturer investment seeking import substitution premiums. Transit disruptions through the canal generate input cost volatility for manufacturers dependent on imported cold-rolled coil. Greenfield processing capacity targets industrial chemical storage contracts requiring audited vertical integration depth.
Delta Region
Food processors in Mansoura and Tanta specify coated tinplate containers for processed vegetable and dairy applications facing plastic substitution pressure. Regional export routes through Port Sudan corridors sustain coated steel container production for price-sensitive African markets. Technical institutes in the zone lack curricula for advanced aluminum can forming, constraining technician supply.
Upper Egypt
Pharmaceutical blister pack demand from Assiut and Sohag facilities pulls high-purity aluminum foil from rolling capacity near 10th of Ramadan City. CDSCO-aligned standards govern regional export specifications for Cairo's Obour City pharmaceutical cluster. Limited local fabrication capacity forces reliance on imported formed components for specialty alloy applications.
Egypt Metal Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around beverage can fabricators with captive coil supply and drum manufacturers with backward integration into steel processing. Three strategic archetypes dominate: multinational packaging specialists with regional headquarters, family-owned metal fabricators serving export routes, and state-affiliated industrial zone operators. Competitive moves concentrate on M&A to secure aluminum coil supply agreements and capacity expansion into Suez Canal Economic Zone greenfield sites.
Among multinational specialists, Ball Beverage Packaging and Greif Inc. exemplify scale-driven archetypes with established Egyptian operational footprints. Ghandour Brothers Metal Industries (Gcan) occupies a position within the regional export-focused tier, while domestic fabricators including El Sharkia Packing Co. and Alfouad Packaging represent mid-cap specialists competing on Sub-Saharan Africa route penetration. These named entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Greif Inc. |
| Willy Group |
| Ball Beverage Packaging |
| Ghandour Brothers Metal Industries (Gcan) |
| El Sharkia Packing Co. |
| Alfouad Packaging |
| CairoPac |
| GOHARYMET |
| Alexmetal |
| Others |
Supply & Pricing Matrix
Suez Canal transit disruptions expose Egyptian metal packaging fabricators to foreign exchange volatility that compresses pricing spreads between premium aluminum coil and standard steel drum tiers while reshaping procurement routing toward backward-integrated suppliers. This chokepoint risk concentrates buying power among edible oil processors and beverage bottlers with direct mill relationships, forcing mid-tier fabricators into narrower margin bands or asset-light exit.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Egyptian drum and container procurement. Price differentiation separates ISO-certified food contact coil from standard industrial grades, with volume scale and melt shop traceability as secondary tiering factors. Cost compression in steel drum segments is intensifying because Suez Canal transit delays extend working capital cycles. Edible oil processors in Borg El-Arab exhibit lowest price sensitivity due to export margin buffers, while regional Sub-Saharan African distributors face acute pressure from plastic barrier substitutes.
Supply Chain Analysis
Tariff exposure between Egypt and steel-exporting jurisdictions in Turkey and Eastern Europe dominates input cost unpredictability for drum manufacturers. Geographic supply concentration draws from China, Turkey, and domestic Suez Canal Economic Zone greenfield sites for cold-rolled coil. Raw material dependencies rest on aluminum ingot, tinplate sheet, and polymer coating resins. Single-source vulnerability sits with imported high-grade aluminum coil for draw-and-wall-ironing lines. Distribution runs through Dekheila Port for Sub-Saharan Africa export corridors and overland routes to Greater Cairo bottling clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's metal packaging sector is approaching a platform-economics inflection as closed-loop aluminum scrap recovery networks and digital direct-to-metal decoration create interoperability standards that reward first-mover scale investments.
For Market Incumbents: Build captive coil supply moats through Suez Canal Economic Zone steel processing investments and scrap closed-loop agreements with Greater Cairo bottlers. Plastic barrier packaging substitution in Sub-Saharan African export routes threatens coated tinplate container margins. Certification investment in EOS food contact traceability documentation secures Alexandria export clearances against mid-tier competitors lacking vertical integration depth. For New Entrants and Emerging Players: Mid-market aluminum can fabricators serving private-label beverage bottlers in 10th of Ramadan City represent the most penetrable entry point given technician scarcity constraints at Ball Beverage Packaging scale. Sub-Saharan Africa route expansion through Port Sudan corridors offers second-mover white space against Ghandour Brothers' established coated tinplate position. Go-to-market execution should lead with seasonal promotional run flexibility enabled by digital direct-to-metal decoration minimum order quantity compression. For Investors and Strategic Acquirers: Forthcoming Egyptian extended producer responsibility regulations reshape the acquisition landscape toward recycling network operators with established collection infrastructure. Five-to-ten-year viability favors fabricators with demonstrated backward integration into coil processing and documented smelter origin compliance. The signal to watch is GOEIC enforcement intensity on BIS-equivalent conformity assessments, which accelerates aluminum sourcing shifts and stranded asset risk in legacy three-piece welding equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Processing | Suez Canal Economic Zone capacity captures import substitution premiums for drum manufacturers serving Borg El-Arab edible oil processors. |
| Closed-Loop Aluminum Scrap Recovery Network | Ball Beverage Packaging scrap agreements with Coca-Cola Egypt reduce effective input costs below virgin aluminum spot benchmarks. |
| Digital Direct-to-Metal Decoration Deployment | SKU proliferation capabilities attract regional bottlers seeking seasonal promotional run economics previously uneconomical under label-based workflows. |
| EOS Traceability Certification Investment | Documented smelter origin compliance secures Alexandria export clearances against competitors lacking end-to-end chain-of-custody documentation. |
| Sub-Saharan Africa Route Expansion | Port Sudan corridor penetration captures coated tinplate container demand from price-sensitive African markets currently served by Middle Eastern competitors. |
Research Methodology
Operator-level perspectives from plant managers at Alexandria drum facilities, procurement leads at Borg El-Arab edible oil processors, beverage bottler technical directors in 10th of Ramadan City, and EOS compliance officers anchored the qualitative base. Primary interview data combined with secondary validation from GOEIC import clearance records, Egyptian Organization for Standardization and Quality specifications, Suez Canal Authority transit statistics, and customs/trade documentation. Bottom-up fabrication capacity assessments and top-down demand modeling from end-use procurement cycles were triangulated to establish volume baselines.
Scenario-bracketing framed analytical approach across the analysis window, with segmentation dimensions spanning substrate technology, product type, end-use application, and regional production cluster. CAGRs were derived from installed capacity expansion timelines, retrofit cycle durations for draw-and-wall-ironing lines, and export demand elasticity into Sub-Saharan African markets. Industry-specific forecast inputs incorporated GOEIC enforcement intensity trajectories and aluminum scrap purity standard implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in Egyptian pound volatility, Suez Canal transit disruption frequency, or Sub-Saharan African import demand would shift the trajectory. Forecasts reflect documented assumptions about technician training pipeline expansion and EOS regulatory implementation pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Metal Drums Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Metal Containers Market
Metal Packaging
India Metal Cans Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Metal Pails Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Global Laminated Steel for Cans Market