
 Europe Metal Packaging Market | 2026-2036
Europe Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Packaging Market Analytics
Modular multipack configurations is recalibrating how beverage and food buyers specify metal containers across European retail channels. Ardagh Metal Packaging SA anchors its position through extensive aluminum can manufacturing scale across Western Europe. Silgan Holdings Inc. competes via specialized closure systems and diverse material capabilities. Ball Corporation dominates beverage can supply to multinational drink brands with high-volume production lines.
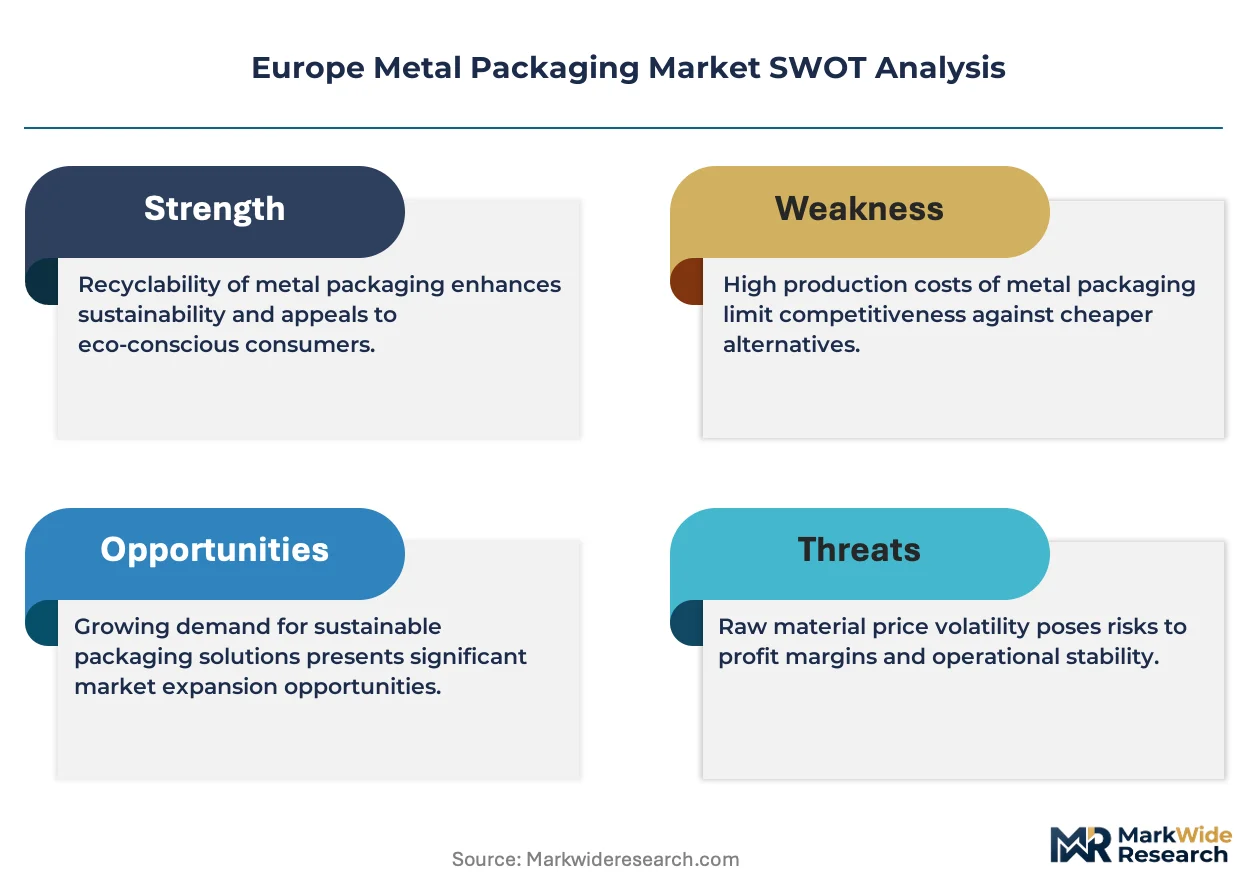
Europe metal packaging comprises rigid and semi-rigid containers formed from aluminum, steel, tinplate, or stainless steel through drawing, ironing, or three-piece welding processes, engineered to provide barrier protection, mechanical strength, and extended shelf stability for consumable and industrial goods. Aluminum cans lead volume within product type segments due to beverage industry procurement scale and recycling infrastructure maturity. Steel drums retains stable demand from chemical and pharmaceutical end users requiring UN-certified hazardous material containment. Flexible foils captures margin concentration in pharmaceutical blister and cosmetic sachet applications where barrier precision commands premium positioning.
EMA packaging guidelines, REACH substance restrictions, and EU Green Deal circular economy mandates collectively shape material composition rules and recyclability verification requirements across European metal packaging supply chains. F-Gas Regulation phase-down timelines pressure aerosol propellant formulations and closure sealing technologies. Stakeholders must monitor evolving Extended Producer Responsibility fee structures and national deposit-return scheme expansions as these mechanisms restructure cost allocation between converters and brand owners.
Market Dynamics
EU Green Deal circular economy mandates are forcing metal packaging converters to reengineer material compositions and verify recyclability across every production batch, compressing legacy process windows and raising compliance costs throughout Western European supply chains.
Growth Catalysts
- REACH substance restrictions:Phased limitations on hazardous coatings accelerate migration toward water-based and UV-cured alternatives, opening specification windows for compliant converters.
- Beverage industry procurement scale:Brewing and soft drink manufacturers in Germany and France are expanding aluminum can lines to replace glass and PET, sustaining volume commitments to domestic metal forming facilities.
- Deposit-return scheme expansions:National implementations across Italy, Spain, and Poland are tightening closed-loop material recovery, improving scrap quality and reducing virgin aluminum input requirements.
Market Restraints
- Aluminum ingot price volatility:LME pricing swings and energy cost pass-through from smelters compress converter margins, particularly for fixed-price annual contracts with multinational beverage brands.
- Steel drum supply concentration:UN-certified hazardous material containment production clusters in Eastern Germany and Northern Italy create geographic vulnerability to logistics disruptions or energy rationing.
- Flexible polymer substitution:High-barrier multilayer films and stand-up pouches capture shelf-stable food applications where metal cans previously dominated, especially in private-label retail segments.
Strategic Opportunities
- Pharmaceutical blister expansion:Cold-form aluminum foil demand is accelerating in Poland and Czech Republic as generic drug manufacturing clusters expand packaging conversion capacity.
- CSRD reporting alignment:Mandatory sustainability disclosures create competitive differentiation for converters offering batch-level carbon accounting and verified recycled content certificates.
- Aerosol propellant reformulation:F-Gas Regulation phase-down timelines pressure brand owners toward compressed gas and mechanical pump alternatives, requiring redesigned valve and closure systems.
Industry Challenges
- Tooling and die engineering expertise:Deep-drawing and ironing process specialists are retiring across Northern Italy and Southern Germany, constraining knowledge transfer for next-generation lightweighting designs.
- EMA packaging guideline compliance timelines:Pharmaceutical metal packaging validation cycles now extend 18-24 months, delaying new product introductions and locking in incumbent supplier relationships.
- Legacy coating line retrofit costs:Converters face capital-intensive equipment replacement to eliminate BPA-based epoxy liners before 2026 regulatory deadlines in multiple EU member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Packaging Market |
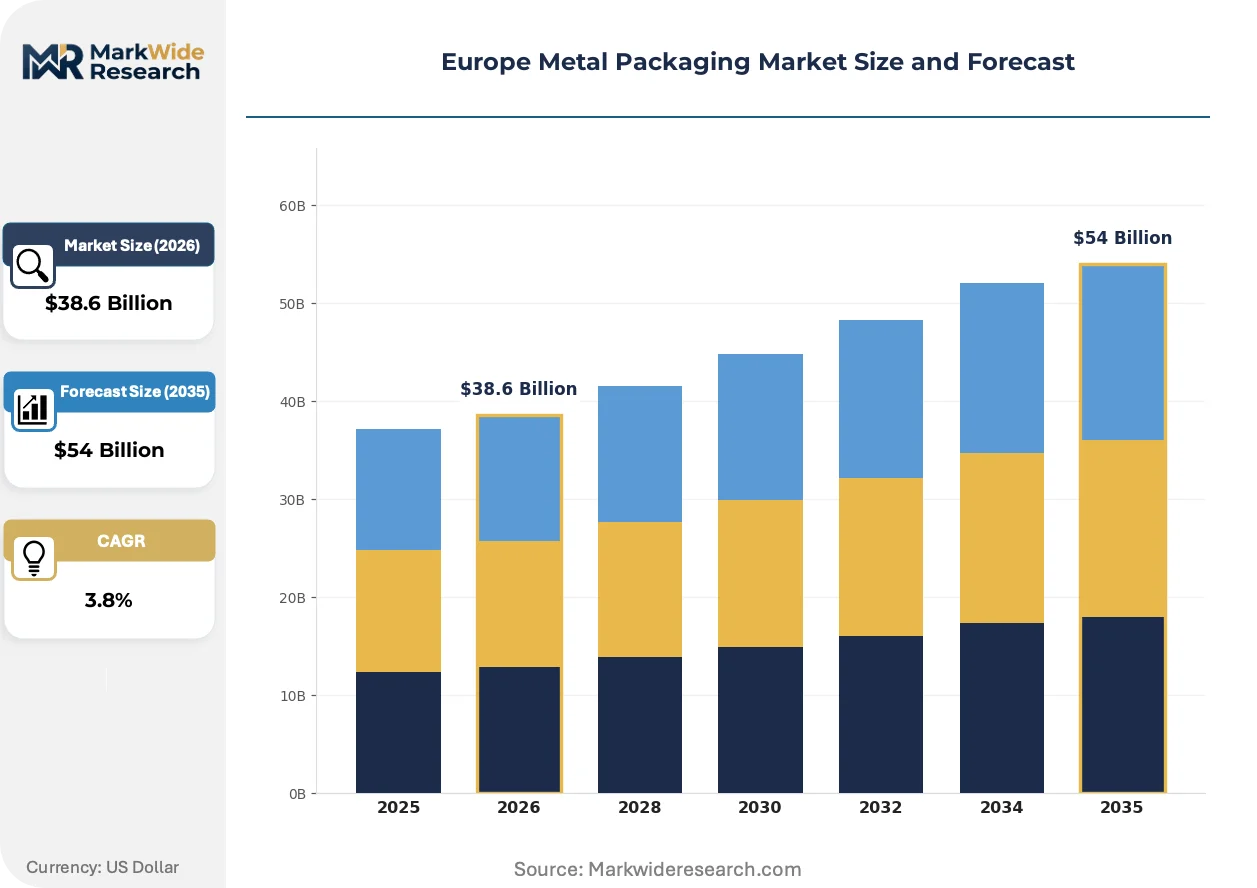
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Foils, Bottles, Drums Material: Aluminum, Steel, Tinplate, Stainless Steel End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Packaging Type: Flexible, Rigid, Aerosol, Closure |
| Companies Covered | CANPACK SA (CANPACK Group), Greif Inc., Ardagh Metal Packaging SA (Ardagh Group), Mauser Packaging Solutions, TUBEX Packaging GmbH, Ball Corporation, Silgan Holdings Inc., Colep Packaging (RAR Group Company), Crown Holdings Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Packaging Market Evolving Landscape
Digital printing and smart packaging integration are recalibrating how European metal packaging converters compete on customization speed and supply chain traceability, compressing traditional analog production economics.
Digital inkjet decoration is rewriting specification protocols for short-run beverage and promotional cans. Craft brewers and seasonal brand campaigns in Belgium and Netherlands are adopting variable-data printing for lot-level traceability and regional marketing variants. This capability is compressing minimum order quantities from hundreds of thousands to tens of thousands, fragmenting production schedules across converter networks.
F-Gas Regulation enforcement is tightening aerosol propellant compliance verification across France, Germany, and Spain. ECHA monitoring requirements now mandate substance-by-substance documentation for hydrofluorocarbon alternatives, forcing reformulation investments and third-party certification cycles. Metal aerosol manufacturers serving cosmetics and household sectors are responding with compressed nitrogen and mechanical actuator development programs.
Retail buyer consolidation is compressing supplier negotiation cycles and unbundling technical service from unit pricing. Discounters and hard-format grocery chains in Poland and Scandinavia are demanding direct converter relationships, bypassing traditional packaging distributors. This disintermediation concentrates volume with vertically integrated manufacturers capable of managing specification, logistics, and compliance documentation in-house.
Europe Metal Packaging Market Segmentation
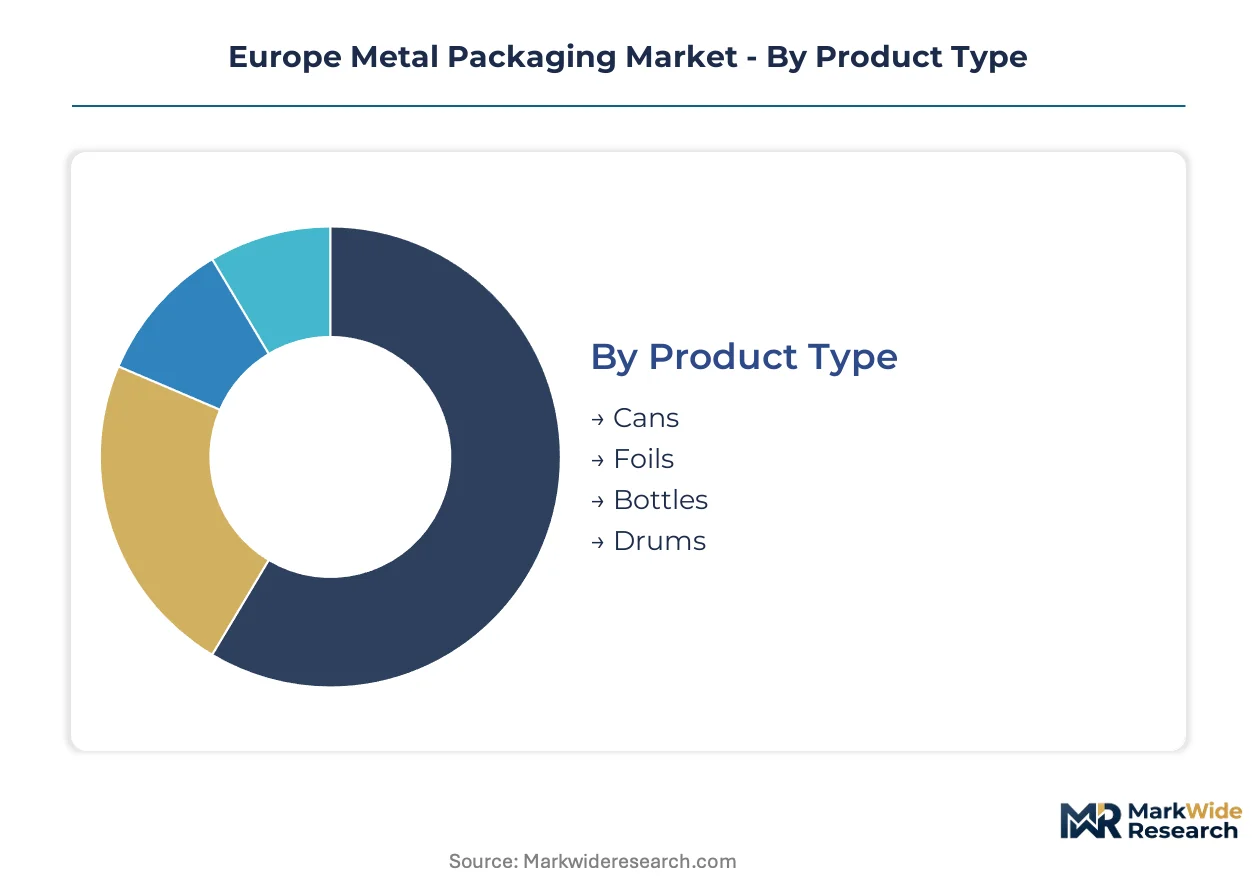
Europe metal packaging segmentation reveals how specification requirements diverge across beverage carbonation pressures, pharmaceutical barrier needs, and chemical containment standards. Procurement patterns in Germany, France, and Italy concentrate volume in distinct product-material combinations that reflect end-use performance mandates and recycling infrastructure maturity.
Product Type:
Drawing and ironing specifications differentiate container performance across carbonated beverage pressures, pharmaceutical sterility, and hazardous material containment.
- Cans:Two-piece aluminum beverage containers dominate procurement volumes through drawing and ironing processes optimized for carbonated drink pressures. German and French brewing clusters sustain high-volume production commitments, with deposit-return scheme expansions improving closed-loop aluminum recovery quality.
- Foils:Cold-form aluminum and multilayer flexible structures serve pharmaceutical blister packs and cosmetic sachets where moisture and oxygen barrier precision commands premium positioning. Poland and Czech Republic generic drug manufacturing clusters are accelerating foil conversion capacity expansion.
- Bottles:Three-piece welded or impact-extruded aluminum containers address niche beverage and personal care applications requiring resealable closures.
- Drums:UN-certified steel containment systems serve chemical and pharmaceutical hazardous material transport under ECHA and national dangerous goods regulations.
Cans lead on scale; foils lead on momentum.
Material:
Alloy composition and substrate selection trace directly to end-use barrier requirements, forming process compatibility, and EU Green Deal recyclability verification mandates.
- Aluminum:3xxx and 5xxx series alloys dominate beverage can body and end stock through continuous casting and hot rolling. LME price volatility and energy cost pass-through from European smelters compress converter margins on fixed-price annual contracts with multinational brands.
- Steel:Tin-free steel and double-reduced electrolytic tinplate serve food can ends and general line containers. Eastern Germany and Northern Italy production clusters create geographic concentration vulnerability to logistics disruptions.
- Tinplate:Low-carbon steel with electrolytic tin coating provides corrosion resistance for acidic food products and aerosol containers.
- Stainless Steel:304 and 316 grades serve pharmaceutical process equipment and premium cosmetic packaging where sterility and chemical inertness justify material cost premiums.
Aluminum commands volume concentration; stainless steel captures margin premiums.
End User:
Regulatory validation cycles and procurement scale separate food and beverage volume concentration from pharmaceutical compliance intensity and chemical containment certification.
- Food & Beverage:Carbonated soft drinks, beer, and shelf-stable foods drive aluminum can and steel food can procurement. REACH substance restrictions on BPA-based epoxy liners are forcing coating line retrofits ahead of member state deadlines.
- Pharmaceuticals:EMA packaging guidelines and 18-24 month validation cycles lock in supplier relationships for blister foil, tube, and primary container applications. Cold-form foil demand is climbing fastest in Central European generic drug manufacturing clusters.
- Cosmetics:Aerosol and specialty metal packaging face F-Gas Regulation propellant reformulation pressures toward compressed gas and mechanical pump alternatives.
- Chemicals:UN-certified steel drum demand remains stable from pharmaceutical and agrochemical sectors requiring hazardous material containment documentation.
Food and beverage anchors procurement volume; pharmaceuticals impose the steepest compliance barriers.
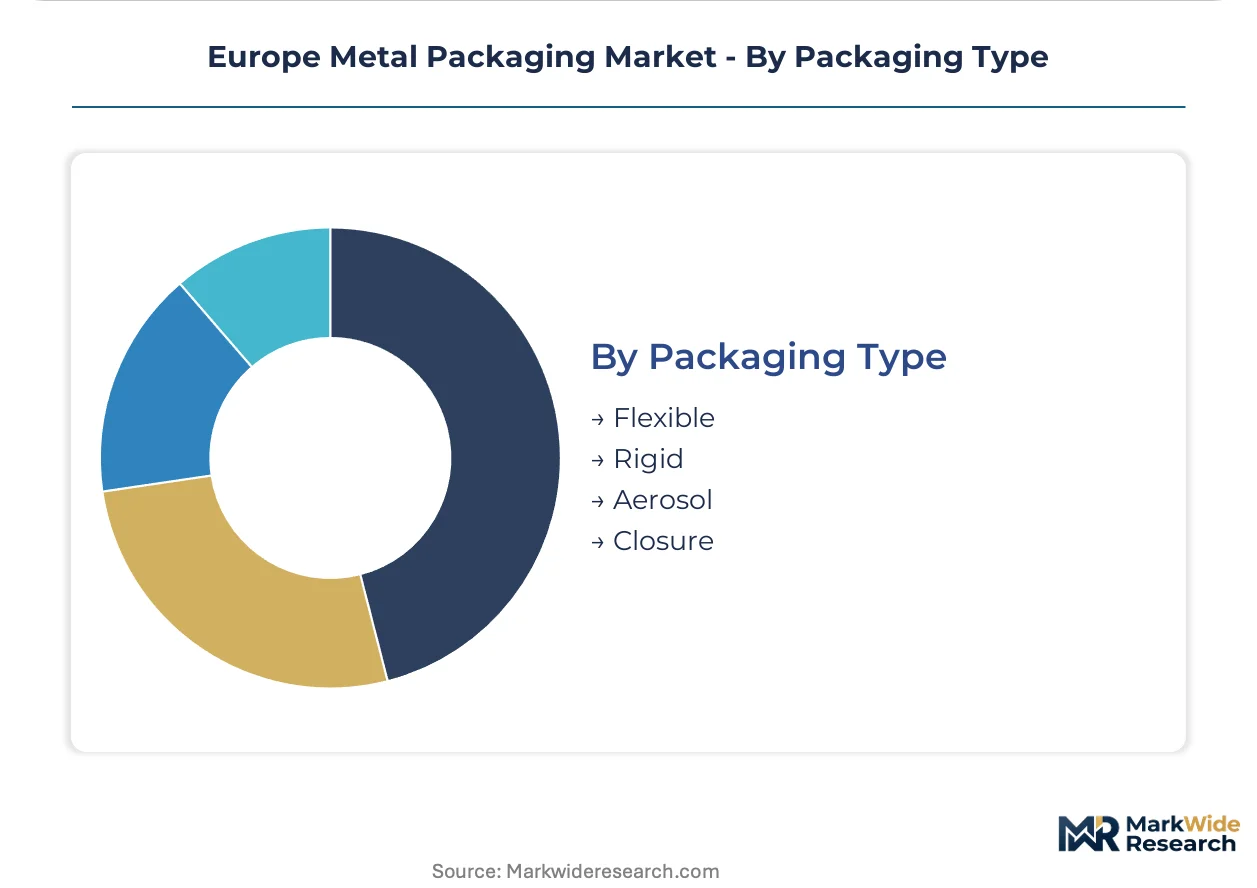
Packaging Type:
Structural rigidity versus conformability determines barrier performance, supply chain cube efficiency, and end-use dispensing functionality.
- Flexible:Aluminum foil laminates and semi-rigid structures serve pharmaceutical blister packs and food lidding where deadfold and barrier precision matter. High-barrier polymer films are displacing metal in select shelf-stable food applications.
- Rigid:Cans, bottles, and drums provide mechanical protection and stacking strength for beverage, food, and industrial applications. Digital inkjet decoration is fragmenting production schedules through short-run customization for craft brewers.
- Aerosol:Three-piece tinplate or aluminum containers with pressure-rated seams serve cosmetics, household, and industrial spray applications. ECHA monitoring now mandates substance-by-substance documentation for hydrofluorocarbon alternatives.
- Closure:Metal crowns, screw caps, and specialty sealing systems complete container functionality for carbonated beverages and wine.
Rigid packaging concentrates manufacturing scale; flexible formats are gaining share fastest in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metal packaging industrialization in Europe traces to nineteenth-century tinplate canning in British and German food preservation sectors, with modern aluminum beverage can scale consolidating across Rhine-Ruhr and Northern Italian manufacturing corridors during the post-war period.
Germany
Bavarian brewing clusters and North Rhine-Westphalia chemical corridors sustain steel drum and aluminum can procurement at continental scale. The national implementation of extended producer responsibility frameworks under EU Green Deal mandates tightens closed-loop aluminum recovery specifications. Düsseldorf-area converter networks are retrofitting coating lines to eliminate BPA-based epoxy liners ahead of 2026 REACH deadlines.
France
Champagne and sparkling wine producers drive specialty closure and bottle demand through Reims and Épernay production zones. ECHA monitoring requirements under F-Gas Regulation now mandate substance-by-substance documentation for hydrofluorocarbon aerosol alternatives. Lille-Nord metal forming facilities are expanding cold-form foil capacity for pharmaceutical blister applications serving Paris-region drug distribution.
Italy
Emilia-Romagna food processing clusters and Lombardy cosmetic manufacturing sustain tinplate food can and aerosol container volumes. National deposit-return scheme expansion timelines are tightening material recovery specifications for aluminum beverage containers. Northern Italian deep-drawing expertise centers around Milan-Brescia tooling corridors, though retiring process specialists constrain knowledge transfer.
Poland
Central European generic drug manufacturing clusters in Warsaw-Łódź corridor are accelerating cold-form aluminum foil conversion capacity. Extended producer responsibility fee structures are restructuring cost allocation between converters and pharmaceutical brand owners. Poznań-area packaging facilities are capturing contract manufacturing migration from Western European cost bases.
Spain
Andalusian olive oil canning and Catalan beverage bottling sustain steel food can and aluminum container procurement. National deposit-return scheme implementation is tightening closed-loop material recovery infrastructure for aluminum scrap quality improvement. Barcelona-area converter networks are adopting digital inkjet decoration for short-run craft beverage customization.
Europe Metal Packaging Market Competitive Landscape
The competitive structure tilts toward scale-driven beverage can specialists with integrated aluminum supply arrangements. Tier-one converters command annual volume commitments from multinational brewing and soft drink brands through fixed-price contracts. Three archetypes dominate: aluminum beverage can scale players, diversified steel and closure system fabricators, and regional specialists in pharmaceutical and aerosol niche formats. Capacity expansion and coating line retrofitting constitute the primary competitive moves as REACH substance restrictions compress compliance timelines.
Among diversified metal packaging fabricators, Ardagh Metal Packaging SA and Silgan Holdings Inc. occupy positions exemplifying scale and specialization archetypes respectively, while Ball Corporation anchors the beverage can volume tier. Ardagh represents the integrated Western European production network model. Silgan exemplifies closure system and multi-material capability positioning. Ball sits within the high-volume multinational brand supply segment where production line throughput determines contract viability.
| Leading Market Players |
|---|
| CANPACK SA (CANPACK Group) |
| Greif Inc. |
| Ardagh Metal Packaging SA (Ardagh Group) |
| Mauser Packaging Solutions |
| TUBEX Packaging GmbH |
| Ball Corporation |
| Silgan Holdings Inc. |
| Colep Packaging (RAR Group Company) |
| Crown Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Multinational beverage brand procurement concentration across Germany, France, and Italy anchors contract-based long-term offtake pricing with annual volume commitments and fixed-price structures that transfer LME aluminum volatility risk to converter balance sheets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UN-certified pharmaceutical containment from general-line food cans and commodity beverage containers. Price differentiation rests on certification grade and volume scale, with EMA-validated pharmaceutical packaging commanding substantial premiums over standard food-grade tinplate. Cost compression in standard beverage can tiers is intensifying because energy pass-through from European smelters compresses converter margins on fixed-price contracts. Private-label retail buyers exhibit highest price sensitivity, while pharmaceutical brand owners prioritize compliance assurance over unit cost.
Supply Chain Analysis
Deposit-return scheme expansions across Italy, Spain, and Poland are tightening closed-loop aluminum recovery flows, improving scrap quality and reducing virgin ingot input requirements for converter networks. Raw material sourcing draws from LME-linked aluminum smelters in Norway and Iceland, tinplate rolling mills in Eastern Germany, and cold-form foil suppliers in Central Europe. Single-source vulnerability concentrates in Northern Italian deep-drawing tooling corridors where retiring process specialists constrain knowledge transfer. Distribution runs through converter-direct relationships with multinational beverage brands and pharmaceutical OEMs, bypassing traditional packaging distributors in Poland and Scandinavia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe metal packaging represents a late-cycle quality story as beverage and pharmaceutical procurement shifts toward premium specifications with verified recyclability certificates and batch-level carbon accounting.
For Market Incumbents: Lock in long-term aluminum supply arrangements with Nordic smelters to hedge LME price volatility exposure on fixed-price beverage contracts. Prioritize coating line retrofit investments ahead of REACH BPA-based epoxy liner deadlines, converting regulatory compliance burden into incumbent supplier stickiness against emerging competitors. For New Entrants and Emerging Players: Capture cold-form aluminum foil demand in Poland and Czech Republic generic drug manufacturing corridors where EMA validation cycles have locked out established Western European suppliers. Target pharmaceutical blister and cosmetic sachet segments with barrier-precision positioning, leveraging shorter qualification timelines with emerging Central European drug manufacturers. For Investors and Strategic Acquirers: Beverage can converters with integrated aluminum supply arrangements are the most active acquirer in this space, consolidating regional capacity to serve multinational brand procurement. Acquisition focus should center on mid-scale pharmaceutical packaging specialists with EMA-validated production lines. Monitor F-Gas Regulation enforcement intensity across France, Germany, and Spain as inflection indicator for aerosol propellant reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Retrofit | Eliminates BPA-based epoxy liners ahead of REACH deadlines in multiple EU member states. |
| Backward Integration into Aluminum Supply | Captures Nordic smelter capacity to hedge LME price volatility on fixed-price contracts. |
| Digital Inkjet Decoration Investment | Enables short-run craft beverage customization compressing minimum order quantities. |
| Cold-Form Foil Capacity Expansion | Serves accelerating pharmaceutical blister demand in Central European generic drug clusters. |
| Deposit-Return Scheme Infrastructure | Tightens closed-loop aluminum recovery specifications improving scrap quality for converter networks. |
Research Methodology
Coverage spans Western Europe and Central Europe, with primary inputs from each region combining converter plant managers, beverage procurement leads at multinational brewing groups, pharmaceutical packaging engineers, and EMA regulatory affairs specialists with secondary validation from ECHA substance restriction databases, EU Green Deal circular economy implementation reports, and national deposit-return scheme regulatory filings. Bottom-up volume modeling triangulates against top-down aluminum and steel consumption data from regional metal industry associations.
Granularity-level modeling operates at product-material-end-use intersections across the analysis window, with separate CAGRs derived for aluminum beverage cans, steel food containers, cold-form pharmaceutical foils, and UN-certified hazardous material drums. Forecast inputs incorporate REACH substance restriction phase-down timelines, F-Gas Regulation enforcement schedules, and national extended producer responsibility fee structure implementations without year-specific anchoring.
Aluminum ingot price volatility, regulatory deadline acceleration, and deposit-return scheme implementation delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on LME pricing corridors and smelter energy cost pass-through rates. Practitioners should monitor ECHA enforcement intensity and national EPR fee announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
India Metal Packaging Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Cans Market
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
Aluminum Cans Market