
 Blister Foil Market | 2026-2036
Blister Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Blister Foil Market Outlook
ISO 15378 certification for pharmaceutical packaging materials is collapsing the supplier base as smaller converters fail to meet audit frequency and documentation depth. Novelis leverages its integrated aluminum rolling capacity to guarantee lot-level traceability for regulated pharma customers. Constantia Flexibles anchors European supply through dedicated cleanroom slitting operations certified for direct-contact drug applications.
Blister foil denotes a thin-gauge laminate, typically 20-40 micron aluminum or multi-layer PVC/PE structures, thermoformed or cold-stamped into cavity arrays to unit-dose oral solids, injectables, and medical devices. Cold forming foil commands premium positioning due to its complete moisture and oxygen barrier without desiccant dependency, while ALU-ALU formats gain share in tropical climate markets where stability testing demands exceed PVC capabilities. The 30-40 micron thickness band dominates volume as blister lines optimize material yield against cavity depth requirements.
FDA's Drug Supply Chain Security Act and EU REACH substance restrictions jointly determine laminate composition eligibility, with DEHP-free PVC transitions now mandatory for pediatric and geriatric dosing formats. India's CDSCO and PLI scheme for active pharmaceutical ingredients indirectly stimulate domestic blister foil capacity as packaging localization follows API manufacturing reshoring. Stakeholders must track evolving monograph updates from USP and EP regarding extractables and leachables testing, as these will redefine qualification costs and supplier switching thresholds.
Market Dynamics
ISO 15378 certification requirements are compressing the supplier base as pharmaceutical packaging converters face escalating audit frequency and documentation depth mandates. Smaller rolling mills and laminators lacking dedicated quality management systems are exiting regulated pharma supply chains, concentrating procurement among integrated aluminum producers with captive cleanroom slitting capacity.
Growth Catalysts
- Chronic disease prevalence:Rising diabetes and cardiovascular medication volumes in India and Brazil are expanding unit-dose oral solid demand. Domestic pharma production scaling under India's PLI scheme for APIs is pulling localized blister foil capacity expansion.
- REACH substance restrictions:EU mandates on DEHP-free PVC for pediatric and geriatric formats are accelerating laminate transitions toward aluminum-polyester structures with enhanced barrier properties.
- Cold forming foil:Complete moisture and oxygen barrier performance without desiccant dependency is commanding premium positioning in tropical climate markets where stability testing demands exceed conventional PVC capabilities.
Market Restraints
- Aluminum input volatility:Primary aluminum ingot price swings and energy cost spikes at European smelters are compressing rolling mill margins and triggering quarterly price adjustment clauses in long-term pharma supply agreements.
- Supplier concentration:Cleanroom-certified slitting operations for direct-contact drug applications cluster in Germany, Switzerland, and India, creating single-source vulnerability for European generic manufacturers.
- PVC technical ceiling:Intrinsic moisture vapor transmission rates limit PVC-based laminates to 60-day shelf life in high-humidity zones, blocking access to tropical export markets for standard-format producers.
Strategic Opportunities
- Southeast Asia localization:Vietnam and Indonesia pharma packaging demand is outpacing domestic foil converting capacity, creating import substitution openings for Indian and Chinese suppliers with ASEAN logistics networks.
- Biologics expansion:Prefilled syringe and wearable injector blister formats for temperature-sensitive biologics represent an emerging application segment with qualification barriers favoring certified incumbents.
- Digital serialization convergence:Integration of printed electronics and NFC-enabled authentication layers into foil lidding is enabling anti-counterfeiting premium pricing and direct-to-pharmacy traceability contracts.
Industry Challenges
- Extractables testing timelines:USP and EP monograph updates on leachables qualification are extending new laminate approval cycles from 18 to 36 months, freezing supplier switching decisions and locking in incumbent pricing.
- Cleanroom capex intensity:ISO Class 8 slitting lines with continuous particle monitoring require $4-7 million per installation, excluding smaller converters from direct-contact pharma qualification.
- Legacy line incompatibility:Thinner 20-micron foil gauges optimized for material yield jam on older blister machines calibrated for 30-40 micron stock, forcing parallel inventory management or capital retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blister Foil Market |
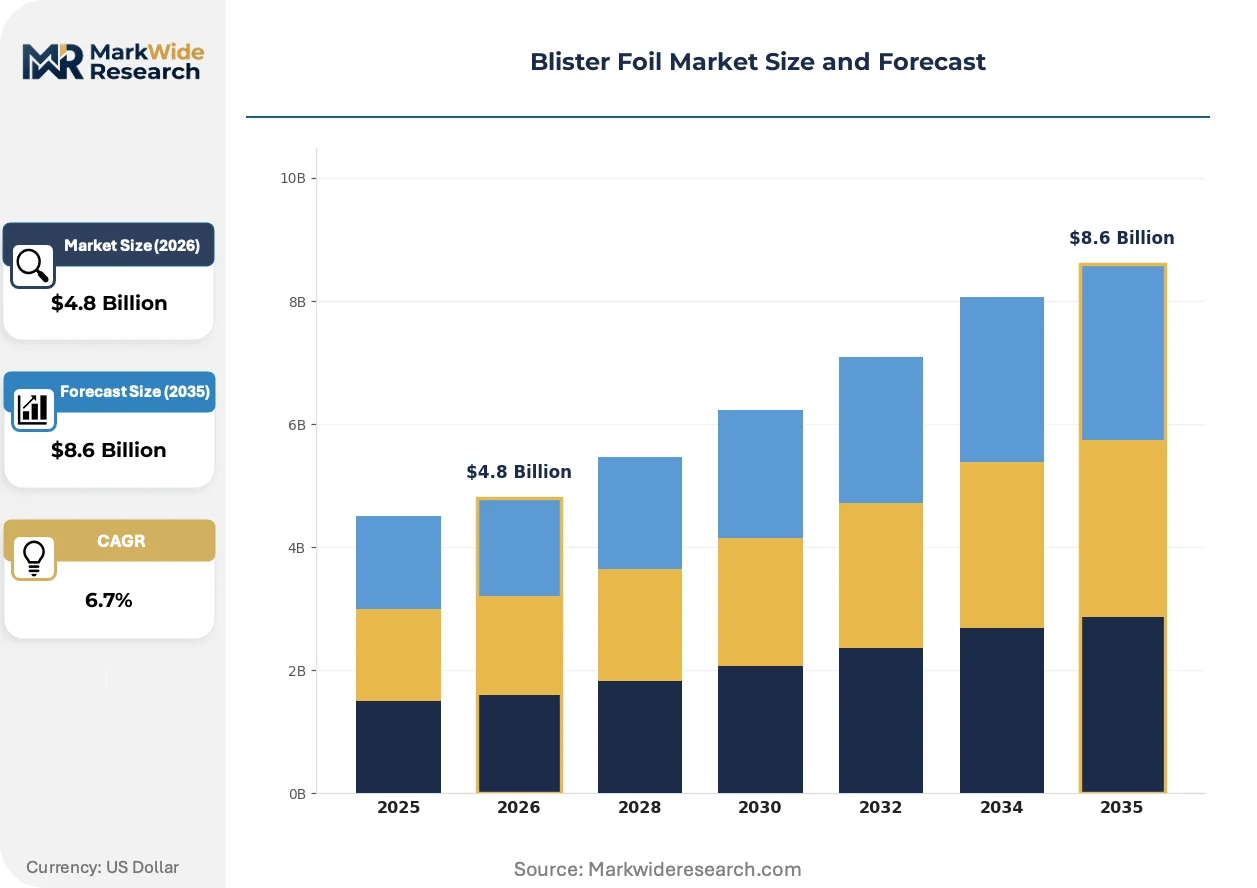
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Forming, PVC, ALU-ALU, Paper End Use Industry: Pharmaceutical, Consumer Goods, Food Packaging, Electronics Thickness: 30 Micron, 40 Micron, 60 Micron, 80 Micron Shape: Flat, Round, Custom, Blister |
| Companies Covered | Klöckner Pentaplast, Novelis, Amcor, Hindalco Industries Ltd., Reynolds Consumer Products, Constantia Flexibles, Tekni-Plex, Huhtamäki Oyj, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blister Foil Market Strategic Shifts
Pharmaceutical packaging specifications are fragmenting across climate zones, patient demographics, and regulatory jurisdictions, forcing foil converters to multiply laminate SKUs and collapse production runs. Material science advances and digital integration are reshaping barrier performance benchmarks and supply chain transparency requirements.
High-barrier polyester-aluminum-polyethylene laminates are fragmenting cold forming foil's historical monopoly on tropical climate protection. Generic manufacturers in Brazil and Nigeria are adopting these structures at mid-tier price points, bypassing ALU-ALU capital intensity while meeting stability testing protocols. The technology is fragmenting premium barrier segmentation into three performance tiers rather than the prior binary cold-form versus thermoform split.
EU REACH substance restrictions on phthalate plasticizers are forcing DEHP-free PVC transitions across all pediatric and geriatric dosing formats. Compounders must reformulate with alternative plasticizers and resubmit extractables profiles, adding 12-18 months to qualification timelines. European generic producers are responding by accelerating aluminum-polyester lidding adoption to eliminate PVC regulatory exposure entirely.
Certification-driven procurement is compressing supplier evaluation cycles as quality departments prioritize ISO 15378 audit scores over unit pricing. Large pharma procurement teams in Germany and Switzerland are unbundling technical qualification from commercial negotiations, awarding multi-year contracts to pre-certified converters before price discussions begin. This behavioral shift is most visible in oncology and hormone therapy packaging where patient safety liability exposure concentrates purchasing power among risk-averse buyers.
Blister Foil Market Segmentation
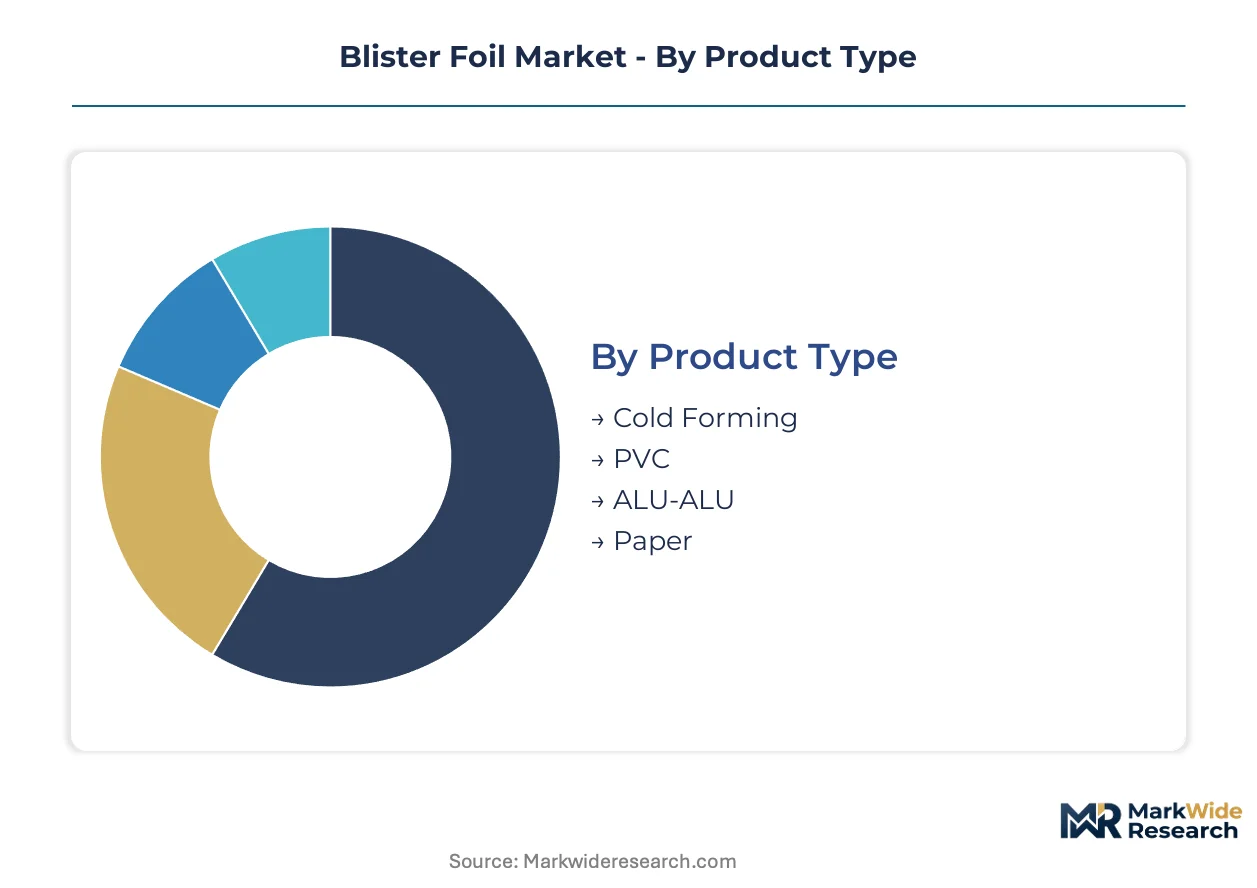
Blister foil procurement channels diverge sharply by product type and end-use, with pharmaceutical direct-buy contracts dominating high-barrier laminates while distributor networks handle standard PVC formats for consumer applications. Thickness and shape specifications further fragment order flows, as cleanroom-certified slitting operations serve regulated pharma while general converters supply food and electronics segments.
Product Type:
Cold forming foil moves through direct pharmaceutical procurement channels with lot-level traceability requirements, while PVC and paper formats flow through packaging distributors serving mid-tier consumer goods manufacturers.
- Cold Forming:Aluminum-polyamide-PVC laminates provide complete moisture and oxygen barrier without desiccant dependency. Demand concentrates in tropical climate markets where stability testing demands exceed conventional PVC capabilities, particularly for export-oriented generic manufacturers in India and Brazil.
- PVC:Thermoformable vinyl structures with aluminum lidding dominate high-volume oral solid dosing. European generic producers are accelerating transitions toward DEHP-free formulations as ECHA REACH restrictions tighten, compressing qualification timelines and freezing supplier switches.
- ALU-ALU:All-aluminum cavity structures deliver maximum barrier performance for moisture-sensitive biologics.
- Paper:Fiber-based substrates with heat-seal coatings serve low-barrier consumer and food applications.
By volume, PVC leads. By growth pace, cold forming is climbing the fastest.
End Use Industry:
Customer type determines margin structure and certification burden, with pharmaceutical buyers absorbing premium pricing for audit-compliant supply chains while food and electronics purchasers prioritize unit economics.
- Pharmaceutical:Unit-dose oral solids, injectables, and medical devices require ISO 15378-certified materials with extractables documentation. India's CDSCO and PLI scheme for APIs is pulling localized blister foil capacity as packaging follows API manufacturing reshoring.
- Consumer Goods:Battery, razor, and toy blister packs use lower-barrier specifications with faster order cycles.
- Food Packaging:Confectionery and portion-control applications demand food-contact compliance without pharmaceutical-grade documentation depth.
- Electronics:Static-dissipative laminates protect semiconductors and components during shipment.
Pharmaceutical commands the highest revenue per ton. Consumer goods delivers the steepest volume expansion trajectory.
Thickness:
Material yield optimization against cavity depth requirements creates four distinct specification bands, with thinner gauges favored by high-speed lines and thicker stocks serving deep-draw applications.
- 30 Micron:Standard lidding foil for thermoformed PVC blisters balances barrier performance with material efficiency. European rolling mills are compressing gauge tolerances to meet yield targets without jamming legacy blister machines.
- 40 Micron:Intermediate specification dominates cold forming base webs where cavity depth demands structural integrity.
- 60 Micron:Heavy-gauge aluminum for deep-draw pharmaceutical applications and industrial packaging.
- 80 Micron:Maximum-thickness stock for extreme barrier requirements and puncture-resistant formats.
The 30-40 micron band captures the majority of tonnage. Thinner 20-micron developments are gaining share fastest among sustainability-focused buyers.
Shape:
Die configuration and forming method determine which converters can supply each geometry, with custom tooling locking in supplier relationships and flat formats enabling spot-market purchasing.
- Flat:Two-dimensional lidding and base webs for standard thermoformed arrays. Indian and Chinese converters with narrow slitting lines are capturing flat-format volume through cost-competitive ASEAN logistics networks.
- Round:Pre-formed cup or disk formats for vial seals and specialty closures.
- Custom:Patient-specific geometries for compliance packaging and combination devices.
- Blister:Pre-formed cavity arrays for direct-fill operations.
Flat formats lead by shipment count. Custom shapes are expanding most quickly as personalized medicine packaging fragments SKU requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's pharmaceutical packaging logistics, while India's Jawaharlal Nehru Port anchors API export corridors that pull blister foil demand through dedicated cold-chain warehousing.
India
Domestic pharma production scaling under the PLI scheme for active pharmaceutical ingredients is pulling localized blister foil capacity expansion. CDSCO serialization mandates for export-bound formulations are tightening material traceability requirements. Ahmedabad and Hyderabad host concentrated converting clusters where ISO 15378-certified slitting lines serve both domestic generic manufacturers and tropical climate export markets.
Germany
Oncology and hormone therapy packaging demand concentrates procurement power among risk-averse buyers prioritizing audit scores over unit pricing. ECHA REACH substance restrictions on phthalate plasticizers are accelerating aluminum-polyester lidding adoption to eliminate PVC regulatory exposure. The Rhine-Main industrial corridor hosts cleanroom-certified operations with dedicated particle monitoring for direct-contact drug applications.
United States
FDA's Drug Supply Chain Security Act serialization requirements are extending laminate qualification timelines and freezing supplier switching decisions. Chronic disease medication volumes for diabetes and cardiovascular therapies are expanding unit-dose oral solid demand. New Jersey and Puerto Rico pharmaceutical manufacturing clusters anchor procurement contracts with lot-level traceability guarantees.
Brazil
Generic manufacturers are adopting high-barrier polyester-aluminum-polyethylene laminates at mid-tier price points to meet tropical climate stability testing protocols. ANVISA extractables documentation requirements are compressing the qualified supplier base for pediatric and geriatric dosing formats. São Paulo state hosts the dominant converting capacity serving both domestic distribution and MERCOSUR export corridors.
Switzerland
Swissmedic certification requirements for biologics packaging are creating qualification barriers favoring incumbents with established extractables profiles. Prefilled syringe and wearable injector blister formats for temperature-sensitive biologics represent an emerging application segment. Basel's pharmaceutical manufacturing cluster drives demand for maximum-barrier ALU-ALU structures with complete moisture and oxygen protection.
Blister Foil Market Competitive Environment
Listed leaders compete with private specialists across certification depth and cleanroom infrastructure. The supplier base compresses as ISO 15378 audit frequency and documentation depth mandates force smaller converters from regulated pharma supply chains. Three archetypes dominate: integrated aluminum producers with captive rolling capacity, dedicated pharmaceutical packaging converters with cleanroom slitting operations, and diversified materials conglomerates with multi-segment laminate portfolios. Competitive positioning sharpens through backward integration into primary aluminum supply and geographic expansion into ASEAN logistics networks.
Within the integrated producer tier, Novelis and Hindalco Industries Ltd. exemplify archetypes leveraging captive aluminum rolling capacity to guarantee lot-level traceability for regulated pharmaceutical customers. Among European-based flexible packaging specialists, Constantia Flexibles occupies a position representing cleanroom-certified slitting operations dedicated to direct-contact drug applications. These three anchors illustrate how certification depth and infrastructure intensity stratify competitive positioning across premium and standard barrier tiers.
| Leading Market Players |
|---|
| Klöckner Pentaplast |
| Novelis |
| Amcor |
| Hindalco Industries Ltd. |
| Reynolds Consumer Products |
| Constantia Flexibles |
| Tekni-Plex |
| Huhtamäki Oyj |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Cleanroom slitting capacity utilization above 85 percent in Germany and India is compressing supplier margins while elevating price floors for ISO 15378-certified foil. This scale concentration lets integrated aluminum producers command premium positioning against smaller converters lacking captive rolling mills.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial foil tiers, with ISO 15378-audited material commanding substantial premiums over standard formats. Cold forming foil draws from complete barrier performance without desiccant dependency, while PVC-based structures face cost compression from DEHP-free reformulation mandates under ECHA REACH. Generic manufacturers in Brazil and Nigeria exhibit highest price sensitivity, whereas oncology and hormone therapy packers absorb premiums to mitigate liability exposure.
Supply Chain Analysis
Container availability on the Rotterdam-Mumbai trade lane and congestion at Jawaharlal Nehru Port are elevating inbound logistics costs for European rolling mills serving Indian pharma clusters. Primary aluminum supply concentrates in China, Russia, and Canada, with secondary converting anchored in Germany, India, and Switzerland. Single-source vulnerability clusters around cleanroom-certified slitting operations in the Rhine-Main corridor. Distribution runs through direct pharmaceutical procurement channels for high-barrier laminates and packaging distributors for standard formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical procurement consolidation among German and Swiss generic manufacturers is shifting bargaining power toward buyers prioritizing audit scores over unit pricing. This buyer-power concentration rewards pre-certified suppliers with multi-year contract security.
For Market Incumbents: Secure captive aluminum rolling capacity to guarantee lot-level traceability as FDA serialization mandates tighten. Deepen backward integration into primary aluminum supply to offset ingot price volatility compressing margins at European smelters. Defend against high-barrier polyester-aluminum-polyethylene substitutes by accelerating ALU-ALU format innovation for tropical climate markets.
For New Entrants and Emerging Players: Cold-chain logistics gaps in Vietnam and Indonesia represent service-layer white space where incumbent footprint remains thin. Target ASEAN pharma packaging demand outpacing domestic converting capacity through partnerships with Indian logistics networks. Pursue qualification for biologics blister formats where Swissmedic and FDA extractables documentation barriers favor agile specialists over diversified conglomerates.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated aluminum producers with cleanroom infrastructure over pure-play laminators facing ISO 15378 audit escalation. Long-term viability hinges on backward integration depth and geographic diversification into ASEAN corridors. Watch cold forming foil adoption rates in tropical climate markets as the inflection signal for premium barrier segment expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum | Captive rolling capacity secures lot-level traceability for FDA serialization compliance. |
| Cleanroom Certification Expansion | ISO Class 8 slitting lines unlock direct-contact pharma contracts with multi-year duration. |
| ASEAN Logistics Network Development | Vietnam and Indonesia demand outpaces domestic converting, creating import substitution openings. |
| High-Barrier Laminate R&D Investment | Polyester-aluminum-polyethylene structures fragment cold forming foil's tropical climate monopoly. |
| Digital Serialization Layer Integration | NFC-enabled authentication commands anti-counterfeiting premium pricing from pharmacy chains. |
Study Parameters
Desk research of customs trade data, ECHA regulatory filings, and pharmaceutical packaging specifications preceded structured interviews with procurement directors at generic manufacturers, quality assurance leads at foil converters, and supply chain managers at integrated aluminum producers. Primary fieldwork across Germany, India, and Switzerland validated secondary findings on certification-driven procurement behavior. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Variance decomposition across product type, end-use industry, thickness specification, and regional regulatory cluster shaped the analytical framework. Cold forming foil penetration rates in tropical markets and PVC transition timelines under REACH restrictions served as industry-specific forecast inputs. CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions across the analysis window.
Underlying assumptions cover sustained ECHA enforcement of phthalate restrictions and stable aluminum ingot supply from primary smelters, with deviation risk concentrated in energy cost spikes at European rolling mills and extractables testing timeline extensions by USP and EP. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
Ampoules and Blister Packaging Market