
 Metal Pails Market | 2026-2036
Metal Pails Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Pails Market Outlook
REACH is recalibrating the cost-of-entry calculus for European metal pail suppliers, forcing reformulation of interior coatings and documentation burdens that smaller fabricators struggle to absorb. Mauser Packaging Solutions leverages its integrated resin-coating capabilities to sustain compliance leadership across EU member states. Behrens Manufacturing, LLC anchors its competitive position through galvanized steel specialization that navigates divergent state-level environmental rules in the American market.
Metal pails are cylindrical containers fabricated from steel, aluminum, or coated steel sheet, typically featuring rolled rims, seamed or welded bodies, and lug or lever-lock closures designed to contain liquids, pastes, or powders under industrial handling conditions. Tight head pails dominate volume in chemical and paint applications where vapor containment and stacking strength prove critical, while open head pails retain structural importance in food-grade uses requiring frequent access. Coated steel commands premium positioning as phenolic and epoxy linings extend product compatibility into aggressive solvent categories that unlined galvanized alternatives cannot serve.
EPA hazardous waste regulations, OSHA container standards, and FDA food contact substance rules collectively shape material selection, testing protocols, and market access thresholds across the industry. The EU F-Gas Regulation indirectly pressures pail demand by accelerating refrigerant reclamation activities that require specialized recovery containers. Stakeholders must monitor evolving PFAS restrictions in both American and European jurisdictions, as these chemicals appear in legacy non-stick interior coatings that face prospective phase-out mandates.
Market Dynamics
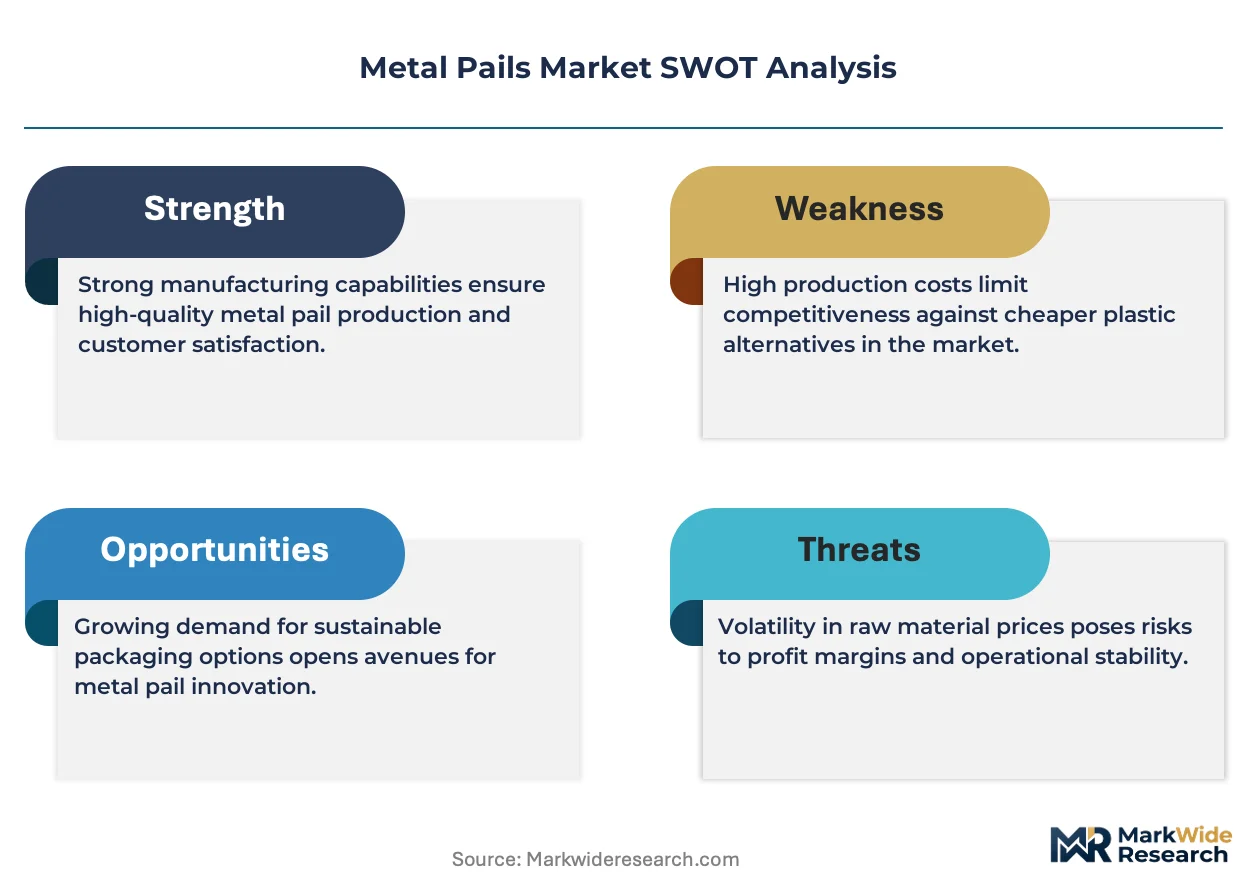
REACH compliance deadlines are forcing European fabricators to abandon legacy coating chemistries faster than capital replacement cycles allow, compressing margins across the coated steel pail segment.
Growth Catalysts
- Hazardous material transport rules:OSHA container standards and UN certification requirements in the United States are mandating vapor-tight tight head pails for solvent-based coatings and agricultural chemicals.
- Refrigerant reclamation mandates:The EU F-Gas Regulation is generating specialized recovery container demand across HVAC service networks in Germany and France.
- Midwest manufacturing concentration:Paint producers and chemical blenders clustered in Ohio, Illinois, and Michigan are expanding coated steel orders for corrosion-resistant solvent packaging.
Market Restraints
- Steel price volatility:Hot-rolled coil input costs fluctuate with energy-intensive European smelter curtailments and scrap availability constraints.
- Coating chemistry concentration:Epoxy and phenolic lining suppliers are consolidating in Germany and the Netherlands, creating single-source vulnerability for UN-certified pail fabricators.
- Plastic substitution:High-density polyethylene drums and intermediate bulk containers are capturing mid-volume chemical shipments where stacking strength requirements relax.
Strategic Opportunities
- PFAS transition services:Fabricators with in-house coating R&D capabilities can capture replacement demand as legacy non-stick interior formulations face phase-out mandates under EPA and ECHA scrutiny.
- Food-grade open head expansion:FDA-compliant lined pails for edible oils and specialty ingredients remain underpenetrated relative to chemical applications.
- Direct-to-blender distribution:Bypassing traditional industrial packaging distributors through vendor-managed inventory programs with large agricultural chemical formulators.
Industry Challenges
- Coating technician scarcity:Application-specific expertise in solvent-resistant epoxy formulations is concentrating at a handful of European and North American facilities.
- UN certification timeline compression:Testing protocols for new interior lining chemistries now require 18-24 month validation cycles that outpace product development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Pails Market |
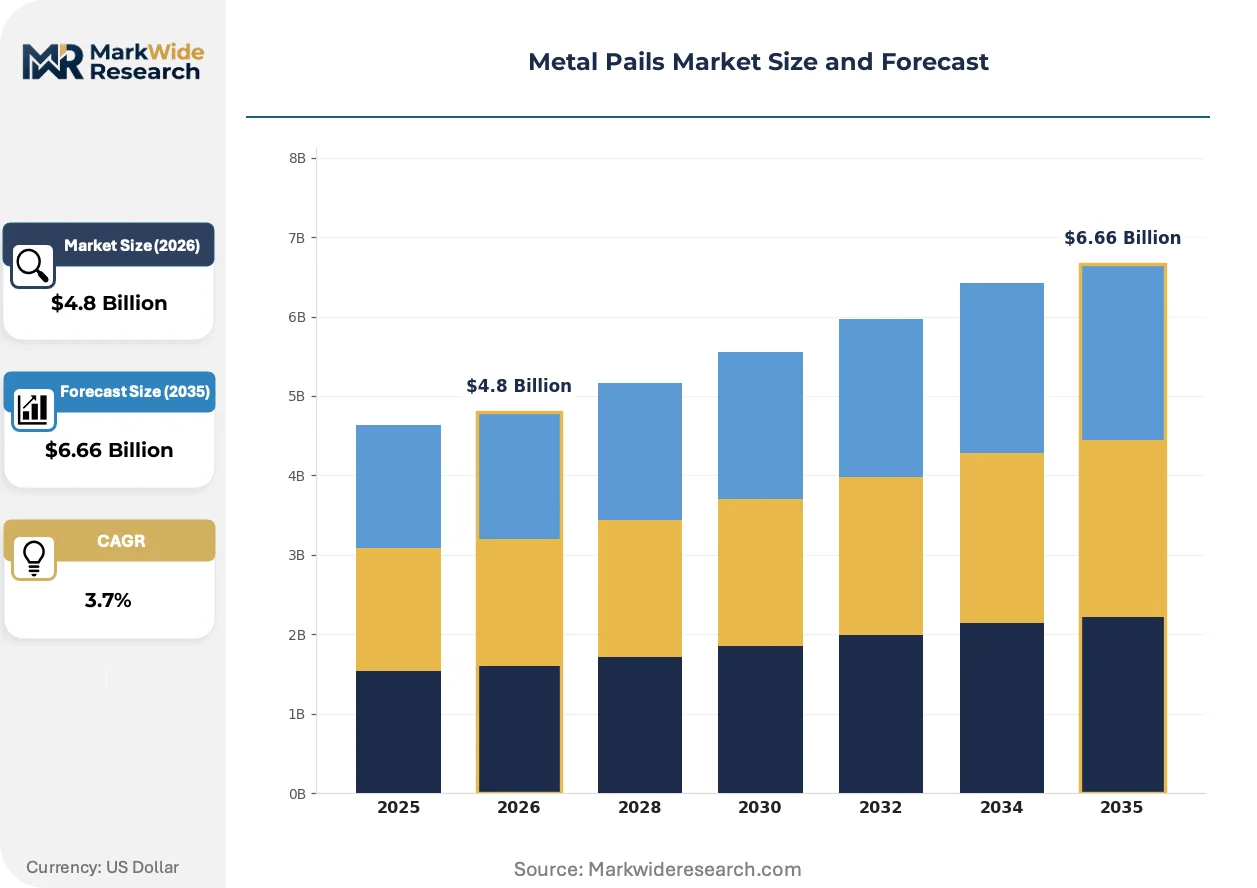
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Head Pails, Tight Head Pails, Specialty Pails, Custom Pails Material: Steel, Aluminum, Galvanized Steel, Coated Steel End User: Food Industry, Chemical Sector, Paint Manufacturers, Agriculture Capacity: 1 Gallon, 5 Gallon, 10 Gallon, 20 Gallon |
| Companies Covered | Mauser Packaging Solutions, CL Smith LLC, P. Wilkinson Containers Ltd., TANKS INTERNATIONAL SRL, Behrens Manufacturing, LLC, Industrial Packaging, ASA Group, Lancaster Container Inc., Aaron Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Pails Market Strategic Shifts
Laser seam welding and automated interior coating deposition are reshaping production economics while regulatory chemistry constraints force material science innovation at the lining-substrate interface.
Robotic seam welding systems are automating the joining of rolled steel bodies with precision that manual operations cannot replicate, particularly for thin-gauge coated stock. Chemical sector buyers in the American Midwest are specifying laser-welded pails for high-value solvent shipments where leak integrity carries liability exposure. This automation is compressing defect rates and enabling thinner wall specifications that reduce material input costs per unit.
REACH authorization requirements for chromium trioxide in passivation layers are forcing reformulation of galvanized steel surface treatments across EU member states. Fabricators serving German chemical exporters must now document alternative corrosion protection chemistries through ECHA notification pathways. The coated steel pail segment bears disproportionate impact because food-contact and chemical-grade specifications demand divergent surface preparation protocols.
Consolidated procurement by multinational paint and coatings producers is displacing fragmented distributor networks with multi-year direct supply agreements. Large agricultural chemical blenders in the United States are unbundling container sourcing from formulation services, creating standalone packaging procurement functions. This concentration is most visible in the Ohio-Illinois manufacturing corridor where three buyers now account for the majority of tight head pail volume.
Metal Pails Market Segmentation
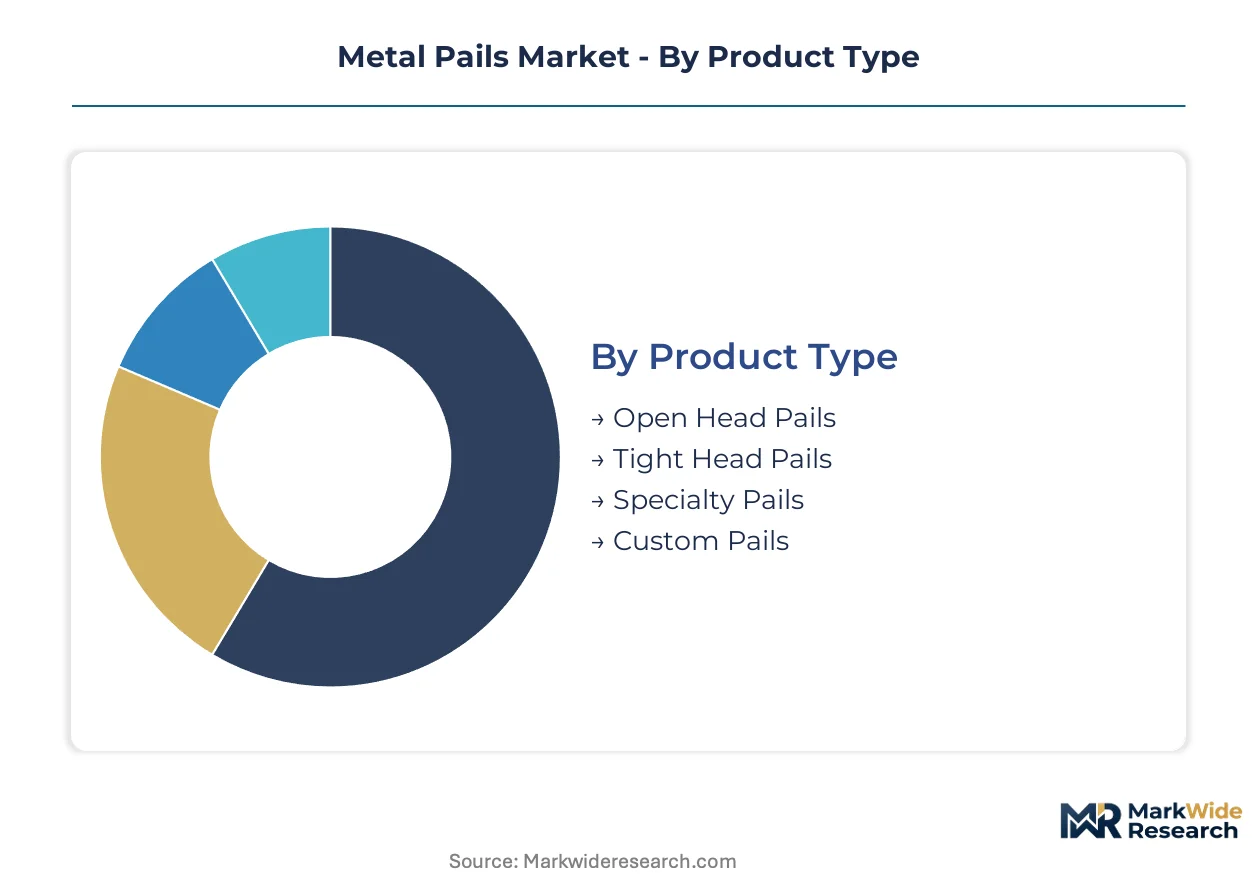
Metal pail segmentation reveals how container specifications align with divergent handling requirements across chemical, food, and industrial workflows. Product geometry, substrate chemistry, and volumetric capacity each impose distinct compliance burdens and procurement patterns that suppliers must navigate simultaneously.
Product Type:
Tight head pails function as standalone sealed systems for hazardous liquid containment, while open head configurations embed into process workflows requiring repeated access.
- Tight Head Pails:Seam-welded cylindrical bodies with permanently attached lids and mechanical closures create vapor-tight seals for solvent-based coatings and agricultural chemicals. Demand clusters with UN-certified specifications for Ohio and Illinois chemical blenders facing OSHA container standards.
- Open Head Pails:Removable lid designs with lug or lever-lock rings accommodate frequent filling and emptying cycles. Food-grade linings for edible oils and specialty ingredients in FDA-regulated facilities concentrate procurement in the upper Midwest.
- Specialty Pails:Custom-engineered geometries for refrigerant reclamation under EU F-Gas Regulation mandates.
- Custom Pails:Application-specific fabrications for proprietary chemical formulations requiring validated interior coating chemistries.
Volume placements concentrate in tight head configurations; the faster expansion belongs to specialty pails serving regulatory-driven reclamation activities.
Material:
Substrate selection trades off corrosion resistance, coating compatibility, and unit economics across chemical exposure profiles.
- Coated Steel:Phenolic and epoxy-lined substrates dominate aggressive solvent categories where unlined alternatives fail. REACH authorization pressures on chromium trioxide passivation in Germany are forcing accelerated reformulation of surface preparation protocols.
- Steel:Cold-rolled unlined bodies serve dry powder and non-reactive paste applications where cost minimization dominates procurement criteria.
- Galvanized Steel:Zinc-coated substrates provide base-level corrosion protection for outdoor storage and construction chemical applications.
- Aluminum:Lightweight non-ferrous construction for specialty chemical shipments where magnetic interference or extreme weight reduction proves critical.
Procurement weight sits with coated steel for chemical-grade specifications; aluminum gains share fastest in premium lightweight segments.
End User:
Industry verticals impose divergent certification regimes—UN hazardous material rules, FDA food contact substance requirements, and EPA hazardous waste protocols each dictate distinct material and documentation specifications.
- Chemical Sector:Solvent manufacturers and specialty chemical blenders in Michigan and Ohio specify coated steel tight head pails with validated epoxy linings for UN-certified transport.
- Paint Manufacturers:Water-based and solvent-based coating producers in the American Midwest require vapor-tight sealing and stacking strength for distribution logistics.
- Food Industry:Edible oil processors and specialty ingredient suppliers need FDA-compliant lined open head configurations with extractables testing documentation.
- Agriculture:Fertilizer and pesticide formulators specify corrosion-resistant containers for field storage and application equipment compatibility.
Order concentration rests with chemical sector buyers; food-grade applications are climbing the fastest as safety documentation requirements tighten.
Capacity:
Volumetric segmentation maps to handling ergonomics, shipping density, and regulatory threshold requirements across industrial workflows.
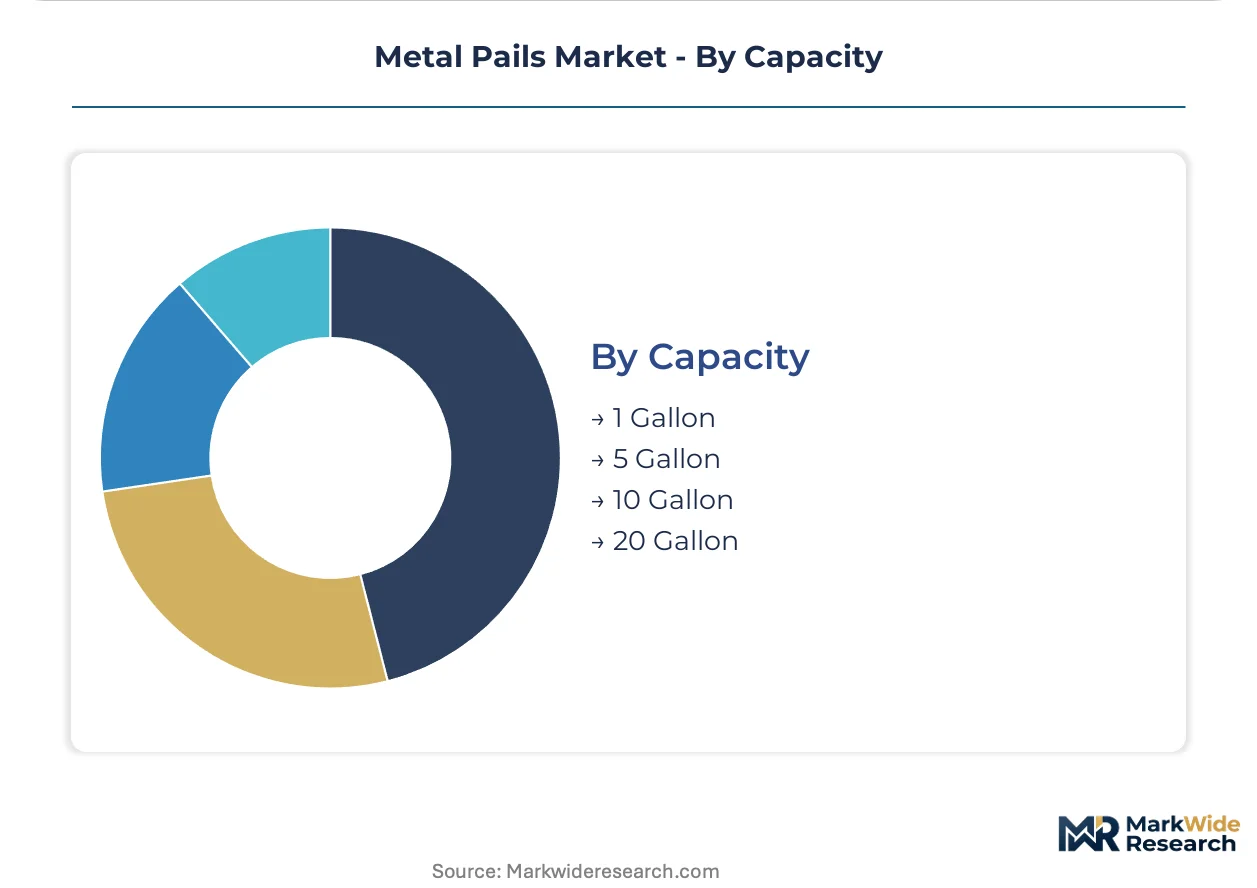
- 5 Gallon:The standard industrial unit for paint, coatings, and chemical distribution balancing manual handling limits with shipping efficiency. Dominates procurement volumes in Ohio-Illinois manufacturing corridor.
- 1 Gallon:Smaller format for specialty chemicals, sampling programs, and retail-scale product distribution requiring single-operator portability.
- 10 Gallon:Intermediate volume for bulk ingredient staging and process integration in continuous manufacturing environments.
- 20 Gallon:Maximum manual handling format for high-volume chemical shipments and agricultural chemical blending operations.
Shipment volumes center on 5-gallon specifications; 1-gallon formats gain share fastest in specialty chemical and sample distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for metal pails clusters in industrial manufacturing corridors where chemical processing and paint production concentrate. German chemical exporters and American Midwest blenders drive specification intensity for UN-certified coated steel containers.
United States
OSHA container standards and EPA hazardous waste protocols mandate vapor-tight tight head pails for solvent-based coatings. Paint producers and agricultural chemical blenders in Ohio, Illinois, and Michigan expand orders for corrosion-resistant coated steel. The Ohio-Illinois manufacturing corridor hosts three buyers accounting for the majority of regional tight head pail volume.
Germany
REACH authorization requirements for chromium trioxide in passivation layers force accelerated reformulation of galvanized steel surface treatments. ECHA notification pathways document alternative corrosion protection chemistries for fabricators serving chemical exporters. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate coated steel pail demand from specialty chemical blenders.
France
The EU F-Gas Regulation generates specialized recovery container demand across HVAC service networks. Refrigerant reclamation mandates accelerate orders for custom-engineered pail geometries in the Île-de-France and Auvergne-Rhône-Alpes regions. Paris-based HVAC distributors specify validated interior coating chemistries for fluorinated gas containment.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for chemical container standards. HSE chemical container guidance and retained EU REACH obligations impose dual documentation burdens on coated steel fabricators. Midlands manufacturing centers around Birmingham and Manchester sustain demand for food-grade open head configurations.
China
GB standards for hazardous material packaging and MIIT industrial safety rules shape coated steel specification patterns. Yangtze River Delta chemical processors specify epoxy-lined tight head pails for solvent shipments. Shanghai-port chemical exporters drive UN certification requirements for international hazardous material transport.
Metal Pails Market Competitive Environment
North American producers anchor one tier; European specialists hold compliance leadership in regulated coating chemistries. The vendor base separates into integrated resin-coating fabricators, galvanized steel specialists, and regional container distributors. Three archetypes dominate: coating-integrated multinationals, substrate-focused metalworkers, and logistics-embedded packaging distributors. Capacity expansion and direct supply agreement displacement of distributor networks represent the dominant competitive moves.
Within the coating-integrated tier, Mauser Packaging Solutions exemplifies compliance leadership across EU member states through in-house resin capabilities. Behrens Manufacturing, LLC occupies a position among galvanized steel specialists navigating divergent American state-level environmental rules. CL Smith LLC represents the distributor-embedded archetype with Midwest manufacturing corridor proximity. These three fabricators illustrate how geographic concentration, regulatory navigation, and substrate specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| CL Smith LLC |
| P. Wilkinson Containers Ltd. |
| TANKS INTERNATIONAL SRL |
| Behrens Manufacturing, LLC |
| Industrial Packaging |
| ASA Group |
| Lancaster Container Inc. |
| Aaron Packaging |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators across the American Midwest and Germany's industrial belt maintain pricing discipline through long-standing relationships with hot-rolled coil suppliers and coating chemistry specialists. Their capital-light ownership structures allow selective investment in UN certification capabilities without quarterly earnings pressure, creating tiered pricing power that separates compliant specialists from commodity producers.
Pricing Analysis
Short lead-time premiums distinguish procurement patterns across the coated steel pail segment, with Ohio-Illinois paint producers paying markup for expedited UN-certified tight head deliveries while spot inventory moves at discount to agricultural chemical blenders with flexible scheduling. Three-tier pricing structure across premium certified, standard coated, and economy unlined tiers reflects certification burden and coating complexity. Cost compression in standard-grade galvanized pails is intensifying because European energy-intensive smelter curtailments feed through to substrate input costs. Agricultural chemical blenders exhibit highest price sensitivity due to unbundled container procurement functions, while specialty refrigerant reclamation buyers accept premium positioning for validated interior chemistries.
Supply Chain Analysis
Domestic-content mandates in American federal procurement and emerging European sustainability reporting requirements are reshaping sourcing patterns for steel substrate and epoxy lining chemistries. Supply concentrates in Germany, the Netherlands, and the United States for coating chemistry formulation, with hot-rolled coil feedstock drawing from integrated mills in the American Midwest and European industrial clusters. Single-source vulnerability concentrates in German and Dutch epoxy and phenolic lining suppliers, creating chokepoint exposure for UN-certified fabricators. Distribution runs through industrial packaging distributors in fragmented networks, though direct supply agreements with multinational paint producers are displacing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines and OSHA container standards erect compliance moats that reward incumbent investment in coating R&D and certification infrastructure. The cost-of-compliance dynamic favors players with captive technical capabilities and documented regulatory pathways.
For Market Incumbents: Anticipate PFAS phase-out mandates by accelerating in-house coating reformulation programs before ECHA and EPA restriction timelines compress competitive response windows. Secure alternative corrosion protection chemistries through backward integration into surface preparation protocols or exclusive supply arrangements with German specialty chemical suppliers. Defensive consolidation of coating technician expertise at key facilities preserves application-specific knowledge that new entrants cannot replicate. For New Entrants and Emerging Players: Direct-to-blender digital procurement platforms offer the most penetrable route for bypassing entrenched distributor relationships with large agricultural chemical formulators in the Ohio-Illinois corridor. Food-grade open head configurations for edible oil processors remain underpenetrated relative to chemical applications, presenting white-space opportunity with lower certification barriers. Vendor-managed inventory programs with Midwest manufacturing clusters provide the specific go-to-market angle for establishing volume credibility. For Investors and Strategic Acquirers: Consolidated procurement announcements by multinational paint producers are the leading indicator that direct supply agreement economics are shifting distributor-embedded players toward strategic vulnerability. Long-term viability rests on coating-integrated capabilities with regulatory documentation depth rather than substrate-only metalworking. Acquisition targets should exhibit in-house epoxy formulation expertise and established ECHA notification pathways. Watch for EU F-Gas Regulation enforcement intensity as the specific signal indicating specialized recovery container demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | In-house epoxy formulation secures REACH compliance leadership against German regulatory deadlines. |
| UN Certification Capacity Expansion | Added testing infrastructure captures Ohio-Illinois chemical blender demand under OSHA mandates. |
| Direct-to-Blender Distribution Launch | Bypassing traditional distributors aligns with unbundled procurement at agricultural chemical formulators. |
| PFAS Transition Service Development | Replacement coating R&D captures phase-out demand under EPA and ECHA scrutiny. |
| Food-Grade Open Head Line Extension | FDA-compliant configurations penetrate underexploited edible oil processor segment. |
Study Parameters
Multi-period observation of REACH authorization timelines, OSHA enforcement patterns, and hot-rolled coil pricing anchored the trend analysis, supplemented by interviews with coating R&D directors, plant managers at Midwest chemical blenders, industrial packaging procurement leads, and ECHA regulatory affairs specialists. Secondary validation drew from customs trade data, SEC filings of integrated packaging multinationals, Cefic chemical industry reports, and EPA hazardous waste tracking databases. Bottom-up volume estimates from end-use sector consumption patterns triangulated against top-down steel substrate supply chain analysis.
Segment-weighting across product type, material substrate, end-use vertical, and regional regulatory cluster shaped the analytical framework. Modeled dimensions included tight head versus open head geometries, coated steel versus unlined alternatives, chemical sector versus food industry buyers, and UN-certified versus non-certified specifications. CAGRs derived from regression of historical shipment patterns against regulatory enforcement intensity and manufacturing capacity expansion announcements. Industry-specific forecast inputs incorporated EPA PFAS restriction timelines and EU F-Gas Regulation phase-down schedules.
The model holds under stable regulatory enforcement intensity and intact steel supply chain flows; deviation in REACH authorization acceleration or European smelter curtailment severity would shift volume and value trajectories. Forecasts reflect documented assumptions regarding coating chemistry substitution rates and distributor network displacement velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Brass Foils Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Australia Metal Packaging Market