
 Europe Functional Water Market | 2026-2036
Europe Functional Water Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Functional Water Market Foresight
The EU Green Deal's packaging sustainability mandates is repositioning procurement priorities across European beverage supply chains. Danone SA leverages its mineral water heritage to dominate shelf-stable formats in France and Benelux. Gerolsteiner Brunnen GmbH & Co. KG anchors its position through captive spring sources in the Volcanic Eifel region. Vitamin Well AB competes via vitamin-fortified formulations tailored to Nordic taste profiles.
Europe functional water comprises non-alcoholic beverages enhanced with bioactive compounds including electrolytes, vitamins, antioxidants, or herbal extracts, typically manufactured through cold aseptic filling to preserve heat-sensitive ingredients and maintain declared potency across shelf life. These products serve hydration needs while delivering targeted physiological benefits such as immune support or exercise recovery. Enhanced water captures premium margin pools as consumers trade up from plain bottled water toward functional claims. Electrolyte-infused variants among ingredient types attract the fastest-growing demand from athletic and post-illness recovery segments. Supermarkets within distribution channels sustain volume throughput, though online retail gains traction through subscription replenishment models.
EFSA governs health claim substantiation under EU Regulation 1924/2006, while the EU Plastics Directive mandates recycled content minimums that reshape packaging material selection. REACH compliance governs additive safety, and the F-Gas Regulation phases down refrigerants used in cold-chain distribution. National regulators including Germany's BfR and France's ANSES layer additional scrutiny on novel ingredients. Stakeholders must monitor evolving EFSA guidance on botanical extracts and prepare for tightened extended producer responsibility schemes that will alter cost structures and competitive moats.
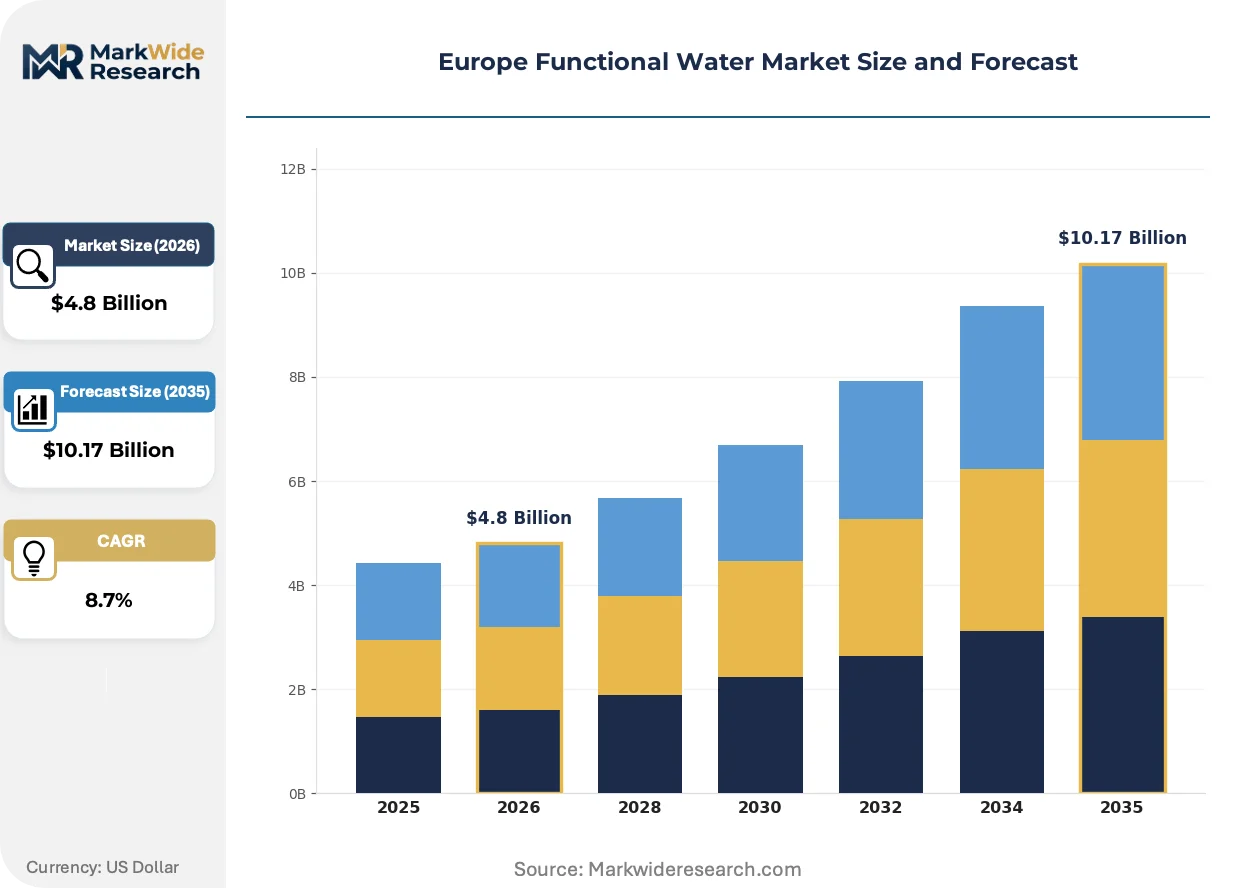
Market Dynamics
The EU Green Deal's packaging sustainability mandates are compressing material choices across European beverage supply chains, forcing producers to abandon virgin PET faster than cost parity would otherwise allow. Cold aseptic filling investments now carry regulatory tailwinds that reshape competitive moats around heat-sensitive bioactive preservation.
Growth Catalysts
- EU Plastics Directive recycled content floors:Mandated minimums for post-consumer rPET in beverage containers accelerate capital redeployment toward compatible filling lines and bottle-to-bottle recycling infrastructure.
- German workplace wellness program expansion:Employer-subsidized hydration stations in corporate campuses normalize per-employee functional water consumption above household purchase rates.
- Electrolyte micro-dosing formulations:Precision mineral blends calibrated to sweat-rate research capture athletic recovery occasions previously served by sports nutrition powders.
Market Restraints
- Volcanic Eifel spring source concentration:Captive mineral water reserves in Germany's Rhineland-Palatinate create geographic supply bottlenecks for premium carbonated variants.
- Aluminum can input cost volatility:LME aluminum price swings compress margin predictability for producers pivoting from PET to metal formats under sustainability pressure.
- EFSA health claim substantiation timelines:Novel botanical extract approvals stretch 18-36 months, freezing innovation pipelines for immune-positioned formulations.
Strategic Opportunities
- Nordic subscription replenishment channels:Sweden and Finland show household penetration gaps for auto-replenishment models that lock in annual volume commitments.
- Post-illness recovery positioning:Hospital discharge protocols and rehabilitation center partnerships open clinical-adjacent consumption occasions beyond traditional fitness.
- CE marking convergence with organic certification:Dual-label products command shelf space premiums in French and Italian pharmacy channels.
Industry Challenges
- Cold aseptic filling technician scarcity:Specialized maintenance and validation skills for hydrogen peroxide sterilization systems concentrate among aging workforces in Germany and Switzerland.
- Extended producer responsibility scheme integration:National deposit-return system fragmentation across Benelux, Nordic, and DACH markets complicates pan-European packaging standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Functional Water Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Water, Enhanced Water, Sparkling Water, Flavored Water Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Stores Target Customer: Athletes, Health-conscious Consumers, Families, Busy Professionals Ingredient Type: Vitamins, Electrolytes, Antioxidants, Herbal Extracts |
| Companies Covered | Nestlé SA, Vitamin Well AB, The Coca-Cola Company, Highland Spring Ltd, Gerolsteiner Brunnen GmbH & Co. KG, PepsiCo Inc., Acqua Minerale San Benedetto SpA, Protein2o Inc., Danone SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Functional Water Market Shifts & Advancements
Cold aseptic filling architectures are consolidating control over European functional water production economics. Three material and behavioral shifts define the current innovation cycle.
Barrier-coated PET bottle technology is consolidating market share among producers seeking aluminum alternatives without shelf-life sacrifice. German and Austrian filling lines are retrofitting hydrogen peroxide sterilization tunnels at accelerated capex cycles. This consolidation is compressing the viable supplier base to equipment manufacturers with integrated blow-fill-seal capabilities.
REACH compliance costs for novel bioactive additives are diverting R&D budgets toward established vitamin and mineral premix portfolios. EFSA's evolving guidance on botanical extract safety is extending substantiation timelines for immune-positioned launches. French and Italian producers are responding by retreating to mineral-electrolyte platforms with existing positive opinions.
Direct-to-consumer subscription models are capturing household pantry space previously held by supermarket impulse purchases. Nordic consumers demonstrate highest trial-to-commitment conversion for quarterly replenishment cycles. Germany's fragmented online grocery landscape slows this shift relative to Stockholm and Copenhagen metro corridors.
Europe Functional Water Market Segmentation
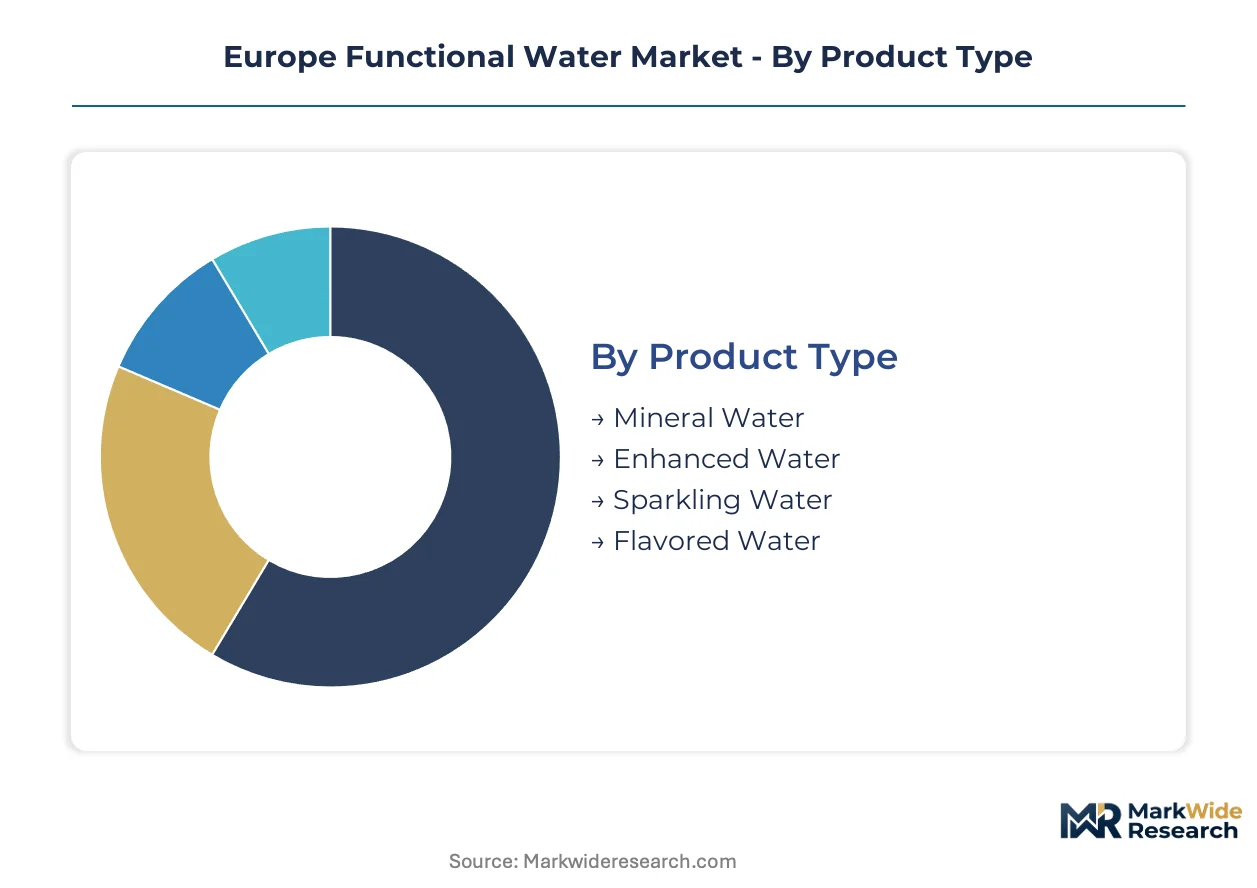
European functional water segmentation reveals divergent margin profiles across product formats and purchase occasions. Cold aseptic filling investments and EFSA health claim pathways create divergent competitive moats by segment. Understanding these structural divides illuminates where capital deployment yields sustainable returns versus commodity exposure.
Product Type:
Volume concentrates in mineral and enhanced formats, while premium margin pools cluster around sparkling and flavored variants with functional positioning.
- Mineral Water:Naturally sourced from captive springs with declared mineral content per EU labeling directives. German workplace wellness programs and French pharmacy channels sustain per-capita consumption above regional averages through employer-subsidized hydration stations.
- Enhanced Water:Bioactive-fortified formulations manufactured via cold aseptic filling to preserve heat-sensitive vitamins and botanical compounds. Electrolyte micro-dosing calibrated to sweat-rate research captures athletic recovery occasions across Benelux fitness club networks.
- Sparkling Water:Carbonated variants leveraging volcanic Eifel mineral reserves for premium positioning. Volcanic source concentration in Rhineland-Palatinate constrains scalable supply expansion.
- Flavored Water:Fruit-infused or essence-dosed products targeting palate fatigue in plain water consumers. Nordic taste profiles favor subtle botanical notes over aggressive sweetness.
Today's leader: Mineral Water. Tomorrow's challenger: Enhanced Water.
Distribution Channel:
Supermarket throughput dominates volume, yet online retail and health stores capture margin through subscription lock-in and clinical adjacency.
- Supermarkets:Hypermarket and grocery chains sustain impulse purchase velocity through chilled fixture placement. German and French retail consolidation limits shelf access for emerging brands without slotting fee capacity.
- Convenience Stores:Grab-and-go hydration for transit corridors and fuel station networks. Urban commuter density in Stockholm and Copenhagen metro corridors sustains premium pricing tolerance.
- Online Retail:Direct-to-consumer subscription models with quarterly auto-replenishment cycles. Nordic households demonstrate highest trial-to-commitment conversion, while Germany's fragmented online grocery landscape slows penetration.
- Health Stores:Pharmacy and specialized wellness retailers with dual-label organic and CE marking products. French and Italian pharmacy channels command shelf space premiums for clinically positioned formulations.
Supermarkets anchor current volume. Online retail claims the steepest expansion trajectory.
Target Customer:
Athletes and health-conscious consumers drive premium tier absorption, while families and professionals sustain mass-market throughput.
- Athletes:Electrolyte micro-dosing demand from endurance sports participants and gym members. German health club membership density exceeds European averages, normalizing functional water as training infrastructure.
- Health-conscious Consumers:Immune support and antioxidant positioning among aging demographics and post-illness recovery segments. EFSA botanical extract approval timelines constrain innovation velocity for this cohort.
- Families:Bulk purchasing and child-friendly flavor profiles with sugar-content scrutiny under national dietary guidelines. School vending machine restrictions in France and Italy limit access points.
- Busy Professionals:Workplace consumption via employer-subsidized hydration stations and corporate campus retail. German corporate wellness program expansion outpaces Southern European adoption.
Health-conscious Consumers dominate premium spend. Busy Professionals represent the fastest volume scaling opportunity.
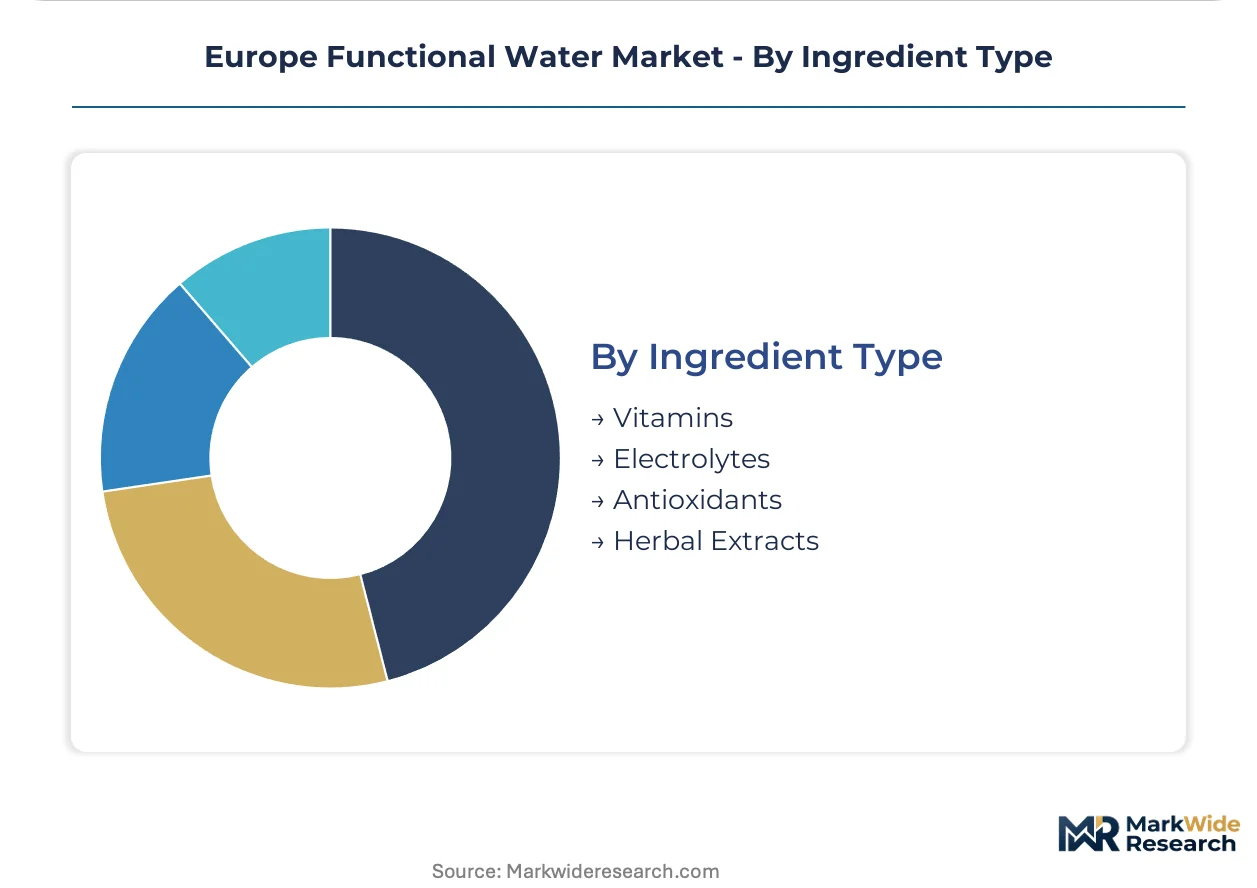
Ingredient Type:
Vitamins and electrolytes concentrate R&D investment due to established EFSA positive opinions, while antioxidants and herbal extracts face substantiation bottlenecks.
- Vitamins:B-complex and vitamin C fortification with existing regulatory approvals and stable supply chains. Nordic producers favor vitamin D positioning given seasonal deficiency patterns.
- Electrolytes:Sodium, potassium, and magnesium blends for hydration optimization and cramp prevention. Precision formulations calibrated to sweat-rate research differentiate premium athletic variants.
- Antioxidants:Polyphenol and flavonoid extracts with substantiation requirements under EU Regulation 1924/2006. REACH compliance costs divert budgets toward established premix portfolios.
- Herbal Extracts:Botanical positioning for stress relief and immune modulation. EFSA novel ingredient approval timelines stretching 18-36 months freeze pipeline velocity for immune claims.
Electrolytes command current athletic occasion dominance. Herbal Extracts await regulatory clarity for immune-positioned expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European functional water production traces its commercial lineage to Germany's Rhineland-Palatinate mineral springs, where volcanic Eifel geology first enabled premium carbonated positioning in the late nineteenth century. This heritage established technical and regulatory precedents that shaped EU-wide standards for mineral content declaration and cold aseptic processing. National market development now diverges around workplace wellness adoption rates, packaging regulation stringency, and subscription commerce maturity.
Germany
Corporate wellness program subsidies and health club density exceeding European averages normalize per-employee functional water consumption above household purchase rates. BfR scrutiny on novel botanical extracts layers additional compliance burden atop EFSA requirements. The Volcanic Eifel region anchors supply for premium carbonated variants, though captive spring concentration constrains scalable expansion.
France
Pharmacy channel dominance and dual-label organic-CE marking products command shelf space premiums for clinically positioned formulations. ANSES maintains parallel safety evaluation pathways for bioactive additives beyond EFSA central procedures. Paris and Lyon metropolitan corridors concentrate demand for antioxidant-positioned variants among aging urban demographics.
Sweden
Household penetration gaps for auto-replenishment subscription models present channel expansion opportunities with highest trial-to-commitment conversion rates. Seasonal vitamin D deficiency patterns drive fortification preferences distinct from Southern European taste profiles. Stockholm metro corridor leads Nordic online grocery consolidation, accelerating direct-to-consumer functional water adoption.
Italy
School vending machine restrictions and sugar-content scrutiny under national dietary guidelines limit access points for flavored variants targeting family consumption. Acqua Minerale San Benedetto SpA heritage in regional spring sourcing shapes competitive expectations for provenance transparency. Northern industrial clusters around Milan and Turin sustain workplace hydration station deployment through employer consortium purchasing.
United Kingdom
Highland Spring Ltd's Scottish captive sources demonstrate how geographic water provenance commands premium positioning independent of functional additive claims. Post-Brexit regulatory divergence from EFSA timelines creates uncertainty for botanical extract approvals. London and Southeast England concentrate demand for electrolyte micro-dosing among urban fitness studio networks.
Europe Functional Water Market Competitive Landscape
Capital-heavy producers with captive spring assets and integrated filling infrastructure compete with asset-light brand architects outsourcing manufacturing to third-party bottlers. Market structure tilts toward consolidation among mineral water heritage players, while functional additive specialists fragment across vitamin, electrolyte, and botanical positioning tiers. Three archetypes dominate: spring-source owners with geographic moats, beverage conglomerates leveraging distribution scale, and Nordic subscription-native challengers. Competitive moves concentrate on cold aseptic filling capacity expansion and pan-European packaging standardization to navigate deposit-return system fragmentation.
Among heritage mineral water owners, Gerolsteiner Brunnen GmbH & Co. KG exemplifies the captive-source archetype with volcanic Eifel provenance anchoring premium carbonated positioning. Danone SA and Nestlé SA represent beverage conglomerate scale, their mineral water heritage providing shelf-stable format dominance across French and Benelux retail consolidation. Vitamin Well AB occupies the challenger tier, its Nordic subscription-native model demonstrating auto-replenishment conversion rates that legacy players struggle to replicate.
| Leading Market Players |
|---|
| Nestlé SA |
| Vitamin Well AB |
| The Coca-Cola Company |
| Highland Spring Ltd |
| Gerolsteiner Brunnen GmbH & Co. KG |
| PepsiCo Inc. |
| Acqua Minerale San Benedetto SpA |
| Protein2o Inc. |
| Danone SA |
| Others |
Supply & Pricing Matrix
The EU Green Deal's packaging sustainability mandates gate qualified supply and premium-tier pricing access by forcing producers toward recycled PET and aluminum alternatives ahead of cost parity. German fitness enthusiasts and corporate wellness programs absorb price premiums for electrolyte-enhanced formats, while compliance investments compress margins for non-compliant suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the European functional water market by certification grade and captive spring provenance. Premium tiers command shelf space through volcanic Eifel mineral heritage and cold aseptic filling investments, while standard formats compete on volume scale in supermarket channels. Price differentiation stems from organic certification dual-labeling and workplace wellness program subsidies. Cost compression in economy tiers intensifies because aluminum input cost volatility and rPET conversion capex squeeze producers pivoting from virgin plastic. Family segments demonstrate highest price sensitivity, whereas German corporate procurement shows lowest elasticity due to employer-subsidized hydration stations.
Supply Chain Analysis
CE marking and EFSA health claim substantiation gate supplier qualification, extending approval timelines for botanical extract formulations and compressing viable ingredient portfolios. Geographic supply concentrates in Germany, France, and Italy, with Rhineland-Palatinate spring sources anchoring premium carbonated variants. Raw material dependencies center on post-consumer rPET flake, LME aluminum ingot, and vitamin-electrolyte premix supply. Single-source vulnerability in volcanic Eifel mineral reserves constrains scalable expansion for heritage producers. Distribution runs through supermarket consolidation in Germany and France, with Nordic subscription channels emerging as alternative downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Functional Water Market functions as a geographic-arbitrage play between German workplace wellness subsidy density and Nordic subscription commerce underpenetration. BfR regulatory stringency in Germany elevates compliance costs that asset-light challengers avoid by manufacturing in lower-scrutiny jurisdictions for export.
For Market Incumbents: Anchor defensive positioning through captive spring source acquisition in Germany's Rhineland-Palatinate and cold aseptic filling capacity expansion ahead of EU Plastics Directive enforcement. Consolidate shelf access through slotting fee capacity in French retail consolidation. Threat substitution from Nordic subscription-native challengers demands channel control investments in auto-replenishment infrastructure. For New Entrants and Emerging Players: Enter via Swedish and Finnish household penetration gaps for quarterly auto-replenishment models with highest trial-to-commitment conversion rates. White-space targets include post-illness recovery positioning through hospital discharge protocol partnerships and Italian workplace hydration station deployment lagging German adoption. Go-to-market angle should leverage vitamin D fortification preferences distinct from Southern European taste profiles. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap mineral water heritage players with volcanic spring assets because EFSA approval timelines freeze innovation pipelines and reward established mineral-electrolyte platforms. Long-term viability favors producers with integrated filling infrastructure and pan-European packaging standardization capabilities. Acquisition target archetype: German or Austrian filling lines with hydrogen peroxide sterilization tunnel retrofit capacity. Signal to watch: extended producer responsibility scheme harmonization across Benelux, Nordic, and DACH deposit-return fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Aseptic Filling Capacity Expansion | Hydrogen peroxide sterilization tunnel investments preserve heat-sensitive bioactive potency for electrolyte micro-dosing formulations. |
| Recycled PET Infrastructure Deployment | Bottle-to-bottle recycling compatibility aligns with EU Plastics Directive mandates and secures regulatory tailwinds. |
| Subscription Commerce Channel Buildout | Quarterly auto-replenishment models capture Nordic household pantry space with conversion rates legacy players struggle to replicate. |
| Captive Spring Source Acquisition | Volcanic Eifel mineral reserves in Rhineland-Palatinate anchor premium carbonated positioning against commodity alternatives. |
| Dual-Label Organic Certification | CE marking convergence with organic certification commands shelf space premiums in French and Italian pharmacy channels. |
Research Methodology
Coverage spans Germany, France, Sweden, Italy, and the United Kingdom, with primary inputs from each national market. The study combined executive interviews with functional water brand managers, category buyers at German and French retail consolidators, cold aseptic filling equipment technicians, and regulatory affairs specialists navigating EFSA and BfR pathways. Secondary validation drew from EU customs records for beverage imports, EFSA health claim register entries, national workplace wellness program enrollment disclosures, and supermarket slotting fee transparency reports. Bottom-up volume modeling triangulated against top-down category spend estimates.
Granularity-level modeling captured product type segmentation at the mineral-enhanced-sparkling-flavored dimension, distribution channel dynamics across supermarket-online retail-health store splits, and ingredient type differentiation by vitamins-electrolytes-antioxidants-herbal extracts. CAGRs were derived from trend extrapolation calibrated to German health club membership density and Nordic subscription penetration trajectories. Industry-specific forecast inputs included aluminum LME price volatility bands and EFSA botanical extract approval pipeline status.
Inputs from EFSA guidance documents and national regulator filings were available through the study window; gaps in real-time extended producer responsibility scheme cost pass-through data introduce uncertainty bands around packaging transition economics. Forecasts reflect documented assumptions on rPET cost parity achievement and workplace wellness program subsidy continuity. A model refresh is warranted upon material change in EU Plastics Directive enforcement timelines or EFSA novel ingredient approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Functional Coffee Market