
 GCC Functional Food Market | 2026-2036
GCC Functional Food Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Functional Food Market Foresight
Saudi Food and Drug Authority (SFDA) tightening of nutrient-content verification standards is shifting procurement priorities across Gulf food manufacturers. Agthia Group PJSC leverages its UAE manufacturing footprint to sustain distribution dominance in fortified beverage categories. Almarai Company anchors Saudi Arabia's dairy-based functional segment through integrated cold-chain logistics. Nestlé Middle East FZE competes on pediatric and elderly nutrition specialization across pharmacy channels.
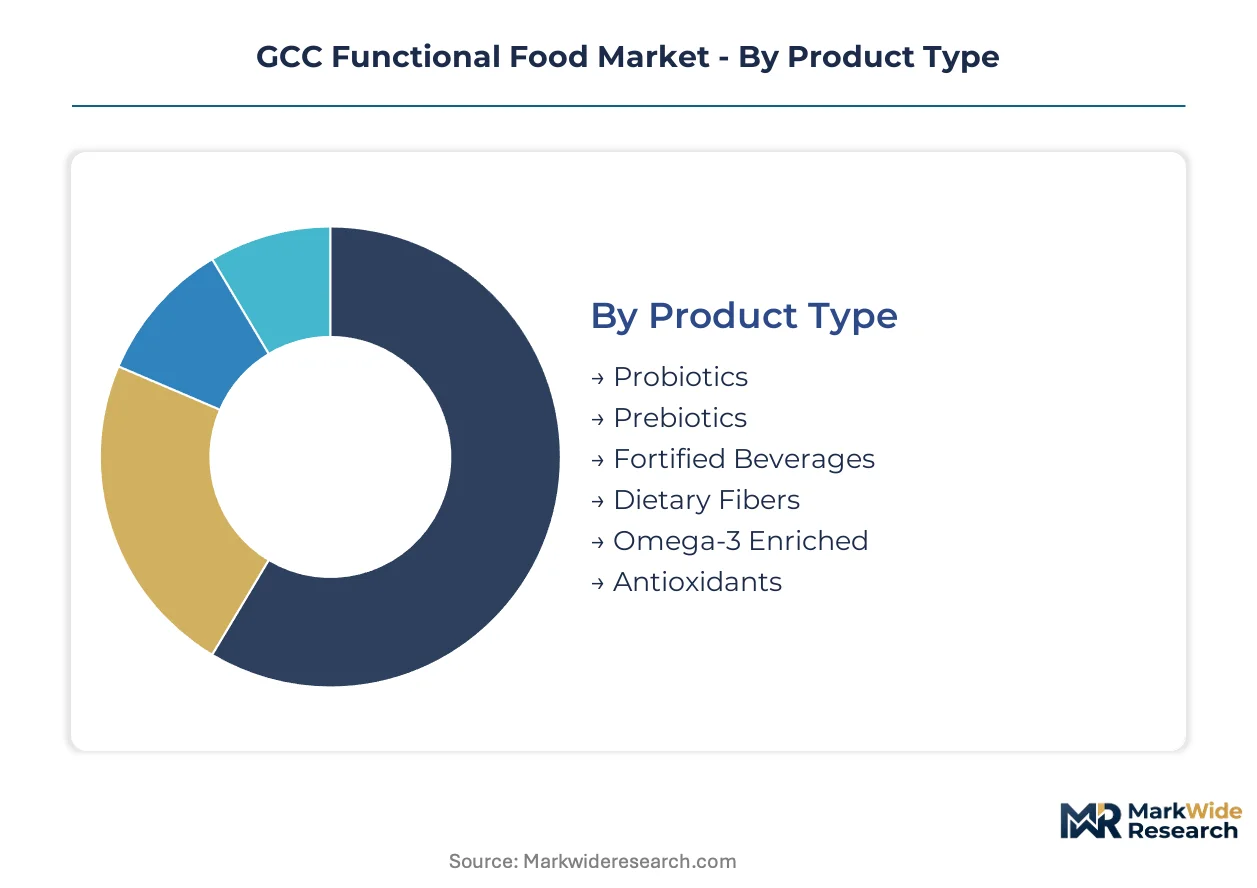
Functional food denotes edible products formulated with bioactive compounds, live microbial cultures, or micronutrient fortificants at clinically relevant dosages, manufactured through controlled fermentation, microencapsulation, or precision blending to deliver physiological benefits beyond basic nutrition. Probiotics and prebiotics occupy the largest product-type margin pools due to digestive health positioning and repeat-purchase loyalty. Fortified beverages represent the fastest-growing product type as Gulf consumers substitute sugar-laden soft drinks with electrolyte and vitamin-enhanced alternatives. Among applications, immune enhancement and cardiovascular support attract disproportionate R&D investment from manufacturers targeting aging Gulf populations with non-communicable disease risk profiles.
SFDA, Emirates Authority for Standardization and Metrology (ESMA), and GCC Standardization Organization (GSO) collectively govern label claims, permissible fortificant levels, and halal certification requirements across member states. These frameworks raise compliance costs for imported functional food while creating preference for locally manufactured products with established regulatory rapport. Stakeholders must monitor evolving GSO harmonization timelines and SFDA claim-substantiation protocols to anticipate which product categories will face accelerated market-access scrutiny.
Market Dynamics
SFDA tightening of nutrient-content verification standards is forcing Gulf food manufacturers to reconfigure formulation pipelines and accelerate local manufacturing investments to maintain market access.
Growth Catalysts
- SFDA claim-substantiation protocols:Stricter Saudi verification requirements elevate consumer trust in fortified products and accelerate pharmacy channel penetration for clinically positioned offerings.
- Diabetes and cardiovascular disease prevalence:Non-communicable disease burden across Saudi Arabia and the UAE drives physician-recommended functional food adoption in clinical nutrition channels.
- Microencapsulation advances:Controlled-release fortificant technologies enable heat-stable probiotic incorporation into ambient beverages, expanding distribution beyond cold-chain constraints.
Market Restraints
- Halal certification complexity:GSO harmonization delays create divergent national standards that fragment production runs and inflate compliance auditing costs.
- Probiotic strain supply concentration:Dependence on European and North American culture suppliers exposes manufacturers to currency volatility and extended lead times.
- Fermentation infrastructure scarcity:Limited regional bioreactor capacity constrains live-culture product scaling and forces reliance on imported intermediate ingredients.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:Lower functional food penetration rates in smaller Gulf states create first-mover advantages for fortified beverage entrants establishing pharmacy networks.
- E-commerce direct-to-consumer channels:Subscription-based personalized nutrition platforms bypass traditional retail markups and capture repeat-purchase loyalty through data-driven formulation.
- ESMA-GSO convergence timeline:Anticipated regulatory harmonization across Emirates Authority for Standardization and Metrology and GCC Standardization Organization will streamline multi-country labeling and reduce SKU proliferation.
Industry Challenges
- Food technologist scarcity:Limited regional expertise in bioactive compound stability and halal-compliant encapsulation stretches R&D timelines and inflates compensation costs.
- Cold-chain capex intensity:Probiotic dairy distribution requires refrigerated transport and storage infrastructure that demands substantial capital deployment in ambient-dominant retail environments.
- Clinical trial substantiation timelines:SFDA requirement for local population-specific efficacy data extends product development cycles and delays revenue recognition for novel functional claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Functional Food Market |
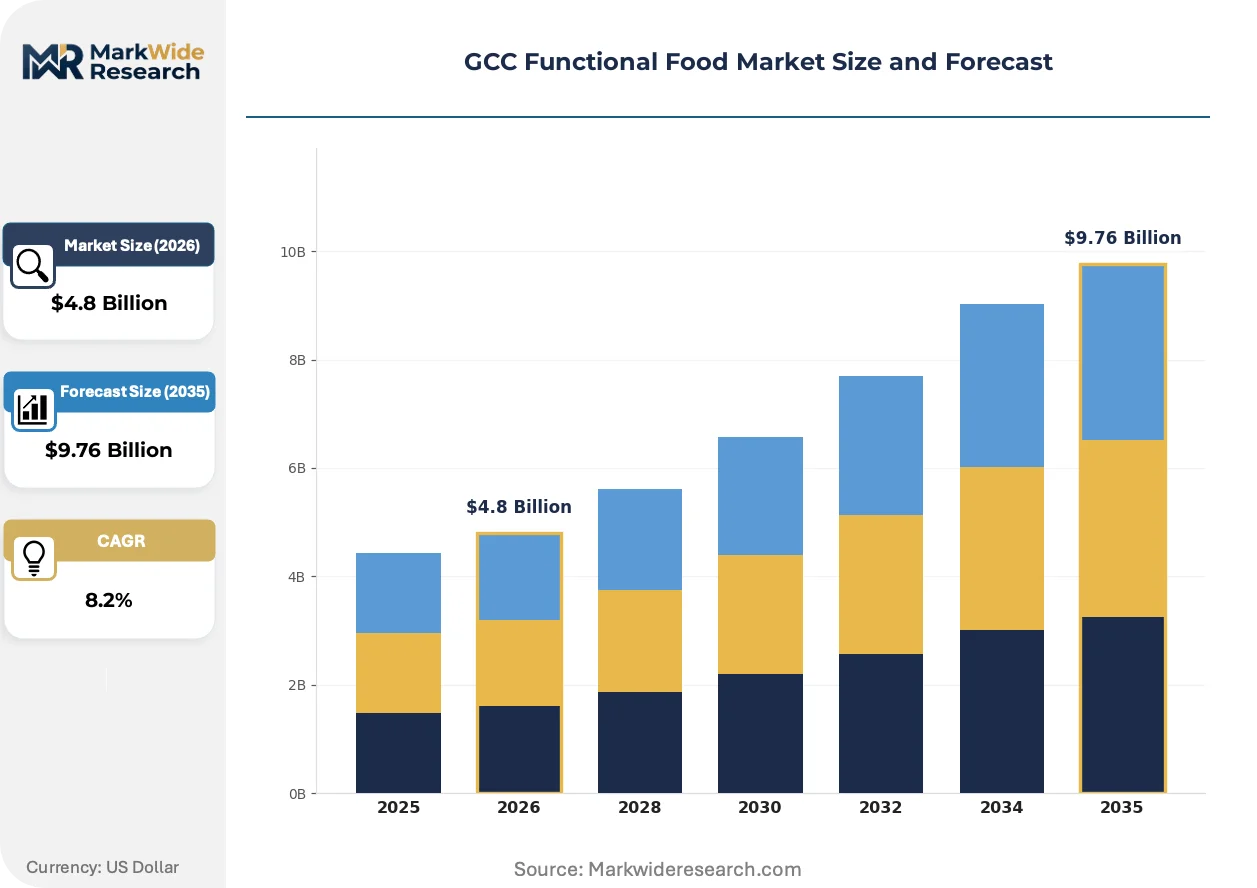
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Fortified Beverages, Dietary Fibers, Omega-3 Enriched, Antioxidants Application: Digestive Health, Cardiovascular Support, Immune Enhancement, Bone Strength, Weight Management, Cognitive Function Consumer Type: Children, Adults, Elderly, Athletes, Pregnant Women, Students Distribution Channel: Supermarkets, Pharmacies, Online Retailers, Health Stores, Specialty Shops, Convenience Stores |
| Companies Covered | Agthia Group PJSC, Baladna Q.P.S.C., Almarai Company, Savola Foods Company, IFFCO, Nestlé Middle East FZE, National Food Products Company (NFPC), PepsiCo, Danone Middle East, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Functional Food Market Shifts & Advancements
Precision fermentation and AI-driven formulation platforms are compressing development timelines while regulatory convergence pressures reshape competitive positioning across Gulf manufacturing hubs.
Microencapsulation technology is converging with precision fermentation-derived bioactives to enable shelf-stable probiotic incorporation into ambient beverages previously limited to refrigerated formats. Saudi and UAE beverage manufacturers are adopting these hybrid processing systems to expand distribution into convenience stores and petrol station networks. This convergence is compressing the traditional cold-chain dependency that has constrained functional dairy penetration in smaller Gulf markets.
SFDA's 2024 nutrient-content claim verification mandate requires local clinical substantiation for all cardiovascular and immune-positioned products. Gulf manufacturers must now commission population-specific efficacy studies or reformulate to generic fortification claims. Pediatric and elderly nutrition segments face the steepest compliance burden as these categories attract the most aggressive functional positioning.
Pharmacy channel preference is displacing supermarket impulse purchasing for clinically positioned functional foods across Dubai and Abu Dhabi corridors. Physicians and licensed pharmacists now intermediate a growing share of probiotic and prebiotic recommendations, replacing self-directed retail selection. This channel migration concentrates margin capture among pharmacy chains with established dietitian consultation services.
GCC Functional Food Market Segmentation
Functional food purchasing decisions in the GCC diverge sharply across consumer life stages, clinical positioning, and channel accessibility. Manufacturers must align formulation investments with these discrete demand pockets to optimize R&D spend and distribution economics.
Product Type:
Formulation complexity and stability requirements dictate procurement premiums and manufacturing partner selection.
- Probiotics:Live microbial cultures requiring cold-chain integrity or advanced microencapsulation for ambient stability. Saudi Arabia's pharmacy networks and Dubai's premium supermarket corridors concentrate demand as physician recommendations displace self-directed purchasing.
- Fortified Beverages:Vitamin, mineral, and electrolyte-enhanced drinks manufactured through precision blending or controlled fermentation. UAE consumers in Dubai and Abu Dhabi corridors are substituting these for sugar-laden soft drinks, accelerating pharmacy and petrol station network penetration.
- Prebiotics:Non-digestible fibers that selectively stimulate beneficial gut microbiota.
- Dietary Fibers:Isolated or synthetic fiber additives targeting digestive regularity and glycemic control.
- Omega-3 Enriched:EPA and DHA fortification through fish oil or algal lipid incorporation.
- Antioxidants:Polyphenol, carotenoid, or vitamin E addition for oxidative stress reduction claims.
Volume sits with probiotics; growth tilts toward fortified beverages.
Application:
Clinical substantiation burden and physician intermediation intensity vary dramatically by physiological target.
- Digestive Health:Probiotic and prebiotic positioning for gut microbiome modulation. Saudi Arabia's SFDA claim-verification protocols elevate compliance costs but reinforce consumer trust in clinically substantiated offerings.
- Immune Enhancement:Vitamin D, zinc, and specific probiotic strain formulations targeting pathogen resistance. Pediatric and elderly segments in UAE pharmacy channels drive disproportionate R&D investment due to higher physician intermediation rates.
- Cardiovascular Support:Omega-3, plant sterol, and fiber-based cholesterol management claims.
- Bone Strength:Calcium and vitamin D fortification targeting post-menopausal women and aging populations.
- Weight Management:Protein enrichment and satiety-inducing fiber formulations.
- Cognitive Function:DHA, phosphatidylserine, and nootropic botanical positioning.
Maturity clusters around digestive health; steepest expansion trajectory belongs to immune enhancement.
Consumer Type:
Purchasing authority and price sensitivity shift across household decision-making structures.
- Adults:Health-conscious 25-55 demographic driving self-directed functional food adoption across fortified beverages and probiotic dairy. Saudi Arabia's urban centers and UAE's Dubai corridor concentrate this segment's purchasing power.
- Elderly:Physician-recommended clinical nutrition with elevated compliance burden for cardiovascular and immune claims. Pharmacy channel dominance in Abu Dhabi and Riyadh shapes distribution priorities for this cohort.
- Children:Parent-mediated purchasing with stringent safety and halal certification requirements.
- Athletes:Performance-oriented protein and electrolyte positioning.
- Pregnant Women:Folate, DHA, and iron fortification with obstetrician guidance.
- Students:Cognitive enhancement and convenience-driven fortified beverage consumption.
Margin capture concentrates with elderly consumers; volume expansion favors adults.
Distribution Channel:
Channel selection determines claim aggressiveness, price realization, and required clinical substantiation depth.
- Pharmacies:Licensed pharmacist intermediation for clinically positioned probiotics and pediatric nutrition. Dubai and Abu Dhabi pharmacy chains with embedded dietitian services command premium positioning and repeat-purchase loyalty.
- Supermarkets:Impulse-driven fortified beverage and functional dairy selection in Saudi Arabia's hypermarket networks and UAE's premium retail formats.
- Online Retailers:Subscription-based personalized nutrition platforms bypassing traditional retail markups.
- Health Stores:Specialty positioning for organic and clean-label functional food.
- Specialty Shops:Premium imported functional food with established regulatory rapport.
- Convenience Stores:Ambient-stable fortified beverage penetration enabled by microencapsulation advances.
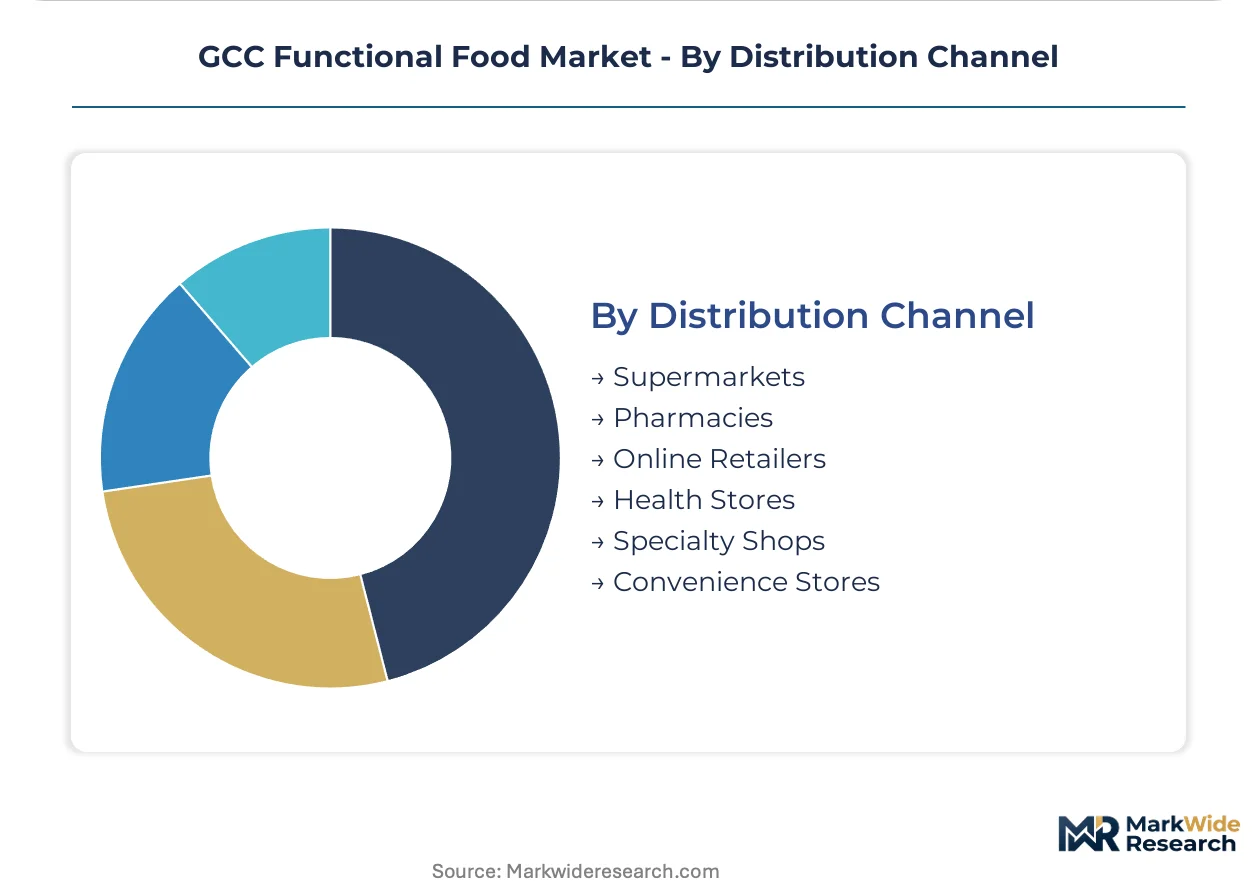
Revenue concentrates in pharmacies; convenience stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's pharmacy and premium supermarket corridors command the strongest functional food penetration in the Gulf, with Abu Dhabi and Riyadh corridors following as concentrated demand nodes.
Saudi Arabia
Urban centers in Riyadh and Jeddah drive self-directed probiotic dairy adoption among health-conscious adults aged 25-55. SFDA tightening of nutrient-content verification standards elevates compliance costs but reinforces consumer trust in clinically substantiated cardiovascular and immune claims. The Eastern Province industrial corridor anchors local manufacturing investments as Gulf food manufacturers reconfigure formulation pipelines.
United Arab Emirates
Dubai and Abu Dhabi corridors concentrate pharmacy channel dominance where physicians and licensed pharmacists intermediate probiotic recommendations. MOHAP alignment with ESMA standards streamlines multi-emirate labeling while creating preference for products with established regulatory rapport. Ambient-stable fortified beverages penetrate convenience stores and petrol station networks through microencapsulation advances.
Kuwait
Lower functional food penetration rates create first-mover advantages for fortified beverage entrants establishing pharmacy networks. The country's national food regulator maintains halal certification requirements that fragment production runs pending GSO harmonization. Kuwait City's retail corridors remain underdeveloped for clinically positioned nutrition compared to Saudi and UAE benchmarks.
Qatar
Doha's premium retail formats attract imported functional food with established regulatory rapport across pediatric and elderly nutrition segments. The national standardization body applies GCC-wide halal frameworks that raise compliance costs for non-local manufacturers. West Bay's pharmacy chains with embedded dietitian services capture disproportionate margin from physician-recommended clinical nutrition.
Bahrain
Manama's retail environment lags in functional food shelf space allocation relative to population health indicators. The national food control directorate enforces fortificant level caps that constrain aggressive functional positioning. Seef and Muharraq corridors present expansion opportunities for ambient-stable probiotic beverages bypassing cold-chain infrastructure constraints.
GCC Functional Food Market Competitive Landscape
Premium-margin players sit above commodity-margin players across clinical substantiation depth and pharmacy channel access. The market structures around three tiers: integrated dairy conglomerates with captive cold-chain logistics, beverage specialists leveraging UAE manufacturing footprints for distribution dominance, and multinational nutrition divisions competing on pediatric and elderly specialization. Consolidation pressure intensifies as SFDA claim-substantiation protocols favor established regulatory rapport. Dominant competitive moves include local manufacturing investments to maintain market access and pharmacy network partnerships to capture physician-intermediated recommendations.
Within the integrated dairy tier, Almarai Company and Baladna Q.P.S.C. exemplify Gulf-based conglomerates with captive supply chain control over probiotic distribution. Agthia Group PJSC occupies a position among UAE-centered beverage specialists sustaining fortified category leadership through manufacturing proximity to Dubai and Abu Dhabi corridors. Nestlé Middle East FZE represents multinational nutrition division archetypes competing across pharmacy channels on clinically positioned pediatric and elderly formulations. These three anchors illustrate how geographic manufacturing footprint and regulatory rapport determine competitive positioning under tightening SFDA verification standards.
| Leading Market Players |
|---|
| Agthia Group PJSC |
| Baladna Q.P.S.C. |
| Almarai Company |
| Savola Foods Company |
| IFFCO |
| Nestlé Middle East FZE |
| National Food Products Company (NFPC) |
| PepsiCo |
| Danone Middle East |
| Others |
Supply & Pricing Matrix
SFDA tightening of nutrient-content verification standards is forcing Gulf food manufacturers to absorb elevated clinical substantiation costs or reformulate to generic claims, compressing margin structures across imported and locally manufactured product tiers. This regulatory pressure differential creates pricing power for established players with existing regulatory rapport while raising effective barriers for new entrants lacking population-specific efficacy data.
Pricing Analysis
Value-based pricing anchored to clinical outcomes and physician recommendations commands premium realization in pharmacy channels across Dubai and Abu Dhabi corridors. Three-tier pricing structure across premium clinically substantiated, standard fortified, and economy generic tiers reflects certification depth and claim aggressiveness. Pricing pressure stems from SFDA local trial requirements extending development timelines and inflating substantiation budgets. Adult self-directed purchasers in Saudi Arabia's hypermarket networks exhibit highest price sensitivity; elderly pharmacy-dependent consumers in UAE show lowest elasticity due to physician intermediation.
Supply Chain Analysis
Refrigerated freight costs and cold-chain infrastructure scarcity in smaller Gulf markets constrain probiotic dairy distribution economics. Probiotic strain supply concentrates in European and North American culture houses; microencapsulation inputs draw from specialized German and Japanese technology suppliers. Single-source vulnerability in live culture supply exposes manufacturers to currency volatility and extended lead times. Distribution runs through pharmacy chains with embedded dietitian services in UAE, hypermarket networks in Saudi Arabia, and emerging convenience store channels enabled by ambient stability advances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA claim-substantiation protocols function as a cost-of-compliance moat, elevating barriers for entrants lacking local clinical trial capabilities while rewarding incumbents with established regulatory rapport and population-specific efficacy portfolios.
For Market Incumbents: Anticipate accelerated GSO harmonization timelines by pre-positioning multi-country label configurations and consolidating fermentation infrastructure investments in Saudi Arabia's Eastern Province industrial corridor. Defensive priority rests on deepening pharmacy network partnerships in Dubai and Abu Dhabi to capture physician-intermediated recommendation flows before subscription-based personalized nutrition platforms disintermediate traditional retail channels. For New Entrants and Emerging Players: Pharmacy chains in Kuwait and Bahrain represent the most penetrable channel infrastructure given lower functional food saturation and less entrenched incumbent relationships. White-space opportunity concentrates in ambient-stable fortified beverages bypassing cold-chain constraints in Manama and Seef corridors. Go-to-market priority should anchor on ESMA pre-certification to accelerate multi-emirate deployment upon GSO convergence. For Investors and Strategic Acquirers: Re-rating potential sits with UAE-centered beverage specialists possessing established manufacturing footprints and regulatory rapport given anticipated SFDA verification standard export across GCC member states. Long-term viability favors targets with integrated precision fermentation capabilities and captive cold-chain logistics. Signal to watch is GSO harmonization implementation velocity as inflection indicator for multi-country label consolidation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Local Clinical Trial Investment | SFDA population-specific efficacy requirements elevate compliant player market access and pharmacy channel preference. |
| Microencapsulation Technology Licensing | Ambient stability partnerships with German and Japanese suppliers expand distribution beyond cold-chain constraints into convenience retail. |
| Pharmacy Network Partnership | Embedded dietitian services in Dubai and Abu Dhabi chains capture physician-intermediated recommendations and repeat-purchase loyalty. |
| Precision Fermentation Capacity Buildout | In-house bioactive compound production reduces strain supply concentration risk and accelerates formulation iteration cycles. |
| ESMA Pre-Certification Positioning | Anticipatory regulatory rapport streamlines multi-emirate labeling ahead of GSO harmonization implementation. |
Research Methodology
Multi-period observation of SFDA regulatory filing patterns, ESMA standard adoption timelines, and GSO harmonization protocols anchored the trend analysis, supplemented by interviews with regulatory affairs directors at Gulf food manufacturers, pharmacy chain procurement managers in Dubai and Abu Dhabi, and clinical nutrition specialists at Saudi tertiary hospitals. Secondary validation drew from SFDA public guidance documents, ESMA technical regulations, GSO standardization bulletins, and customs trade data on functional food ingredient imports. Bottom-up manufacturer capacity assessments and top-down consumption pattern modeling were triangulated to reconcile supply-side and demand-side estimates.
Input-output matrix framing connected probiotic strain availability, microencapsulation technology adoption curves, and cold-chain infrastructure deployment to volume and value trajectories across the projection horizon. Segmentation dimensions modeled included product type stability requirements, application-specific clinical substantiation burden, consumer life-stage purchasing authority, and channel intermediation intensity. CAGRs were derived from iterative convergence of demand elasticity estimates and supply constraint functions. Industry-specific forecast inputs incorporated SFDA claim-verification protocol evolution and ambient stability technology diffusion rates.
Caveats apply where GSO harmonization delays, probiotic strain supply disruptions, or SFDA claim-substantiation requirement expansion could materially shift the outlook for market access economics and competitive positioning. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Global Functional Mushrooms Market