
 North America Protein Bar Market | 2026-2036
North America Protein Bar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Protein Bar Market Analytics
Aftermarket subscription and loyalty program revenue is tilting toward direct-to-consumer channels, reducing reliance on conventional retail slotting fees. Quest Nutrition LLC leverages its e-commerce infrastructure to sustain recurring purchase rates. Clif Bar & Company anchors its position through outdoor sports sponsorships and climate-advocacy branding. General Mills Inc competes by extending its distribution muscle into convenience and drugstore placements.
A protein bar is a shelf-stable, extruded or cold-pressed food product containing ten to thirty grams of protein per serving, bound by syrups, fibers, or lipids, and manufactured through high-shear mixing, forming, and enrobing processes designed for portable nutrition and satiety. Sports Nutrition bars dominate shelf space and command premium price points due to performance positioning and gym-channel density. Plant-Based ingredient sourcing is expanding fastest as formulators replace whey with pea, rice, and fava protein isolates to capture flexitarian households. Chocolate flavor profiles occupy the largest volume share, though savory variants are emerging in meal-replacement positioning.
The FDA governs nutrition fact panel accuracy and protein content claims under Food Labeling Guide standards, while the USDA oversees organic certification pathways that premium brands pursue. Health Canada and the Canadian Food Inspection Agency enforce bilingual labeling and protein quality rating methods that influence cross-border formulation decisions. Stakeholders must monitor evolving clean-label enforcement thresholds and state-level sugar-tax proposals that could reshape ingredient economics and regional pricing structures.
Market Dynamics
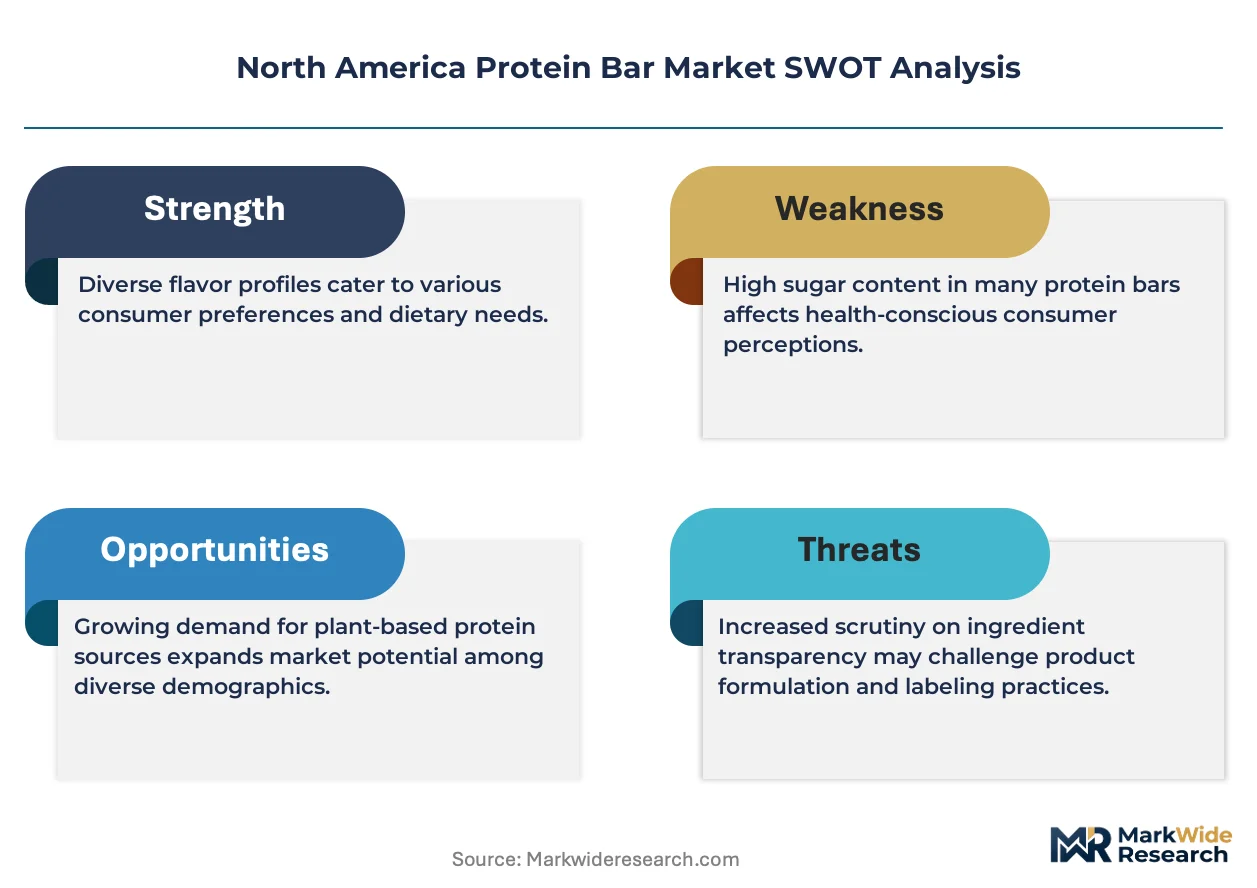
FDA nutrition labeling modernization is compressing formulation cycles as brands reformulate to meet updated protein content claim thresholds, forcing simultaneous compliance investments and clean-label innovation pipelines.
Growth Catalysts
- Plant protein isolate technology:Pea, rice, and fava protein extraction advances enable taste-parity with whey, capturing flexitarian households across the United States and Canada.
- California urban corridor density:Health-conscious metropolitan populations in Los Angeles and San Francisco sustain premium pricing for functional nutrition products.
- USDA organic certification pathways:Premium brands pursue organic credentials to differentiate in crowded retail environments and command shelf placement.
Market Restraints
- Input cost volatility:Cocoa and whey protein concentrate prices swing with commodity markets, compressing margin predictability for mid-tier manufacturers.
- Supply concentration risk:Pea protein isolate production concentrates in Saskatchewan and Manitoba, creating regional dependency for plant-based formulations.
- Technical limitation:Shelf-stable savory flavor profiles remain challenging to execute without accelerated lipid oxidation or off-notes.
Strategic Opportunities
- Pacific Northwest outdoor recreation:Washington and Oregon trail systems and ski resorts offer underpenetrated placement for performance-positioned bars.
- Direct-to-consumer subscription infrastructure:Recurring revenue models reduce slotting fee dependence and capture lifetime value through personalized nutrition algorithms.
- Health Canada bilingual labeling harmonization:Cross-border formulation standardization opens unified production runs for US-Canada distribution.
Industry Challenges
- Clean-label enforcement thresholds:FDA scrutiny of "natural" and "no added sugar" claims demands accelerated legal review and packaging redesign cycles.
- High-shear extrusion equipment capex:Texture innovation requires capital-intensive forming and enrobing line upgrades that strain mid-cap balance sheets.
- Protein quality rating compliance:Health Canada's PDCAAS and DIAAS calculation methods create formulation complexity for products targeting both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Protein Bar Market |
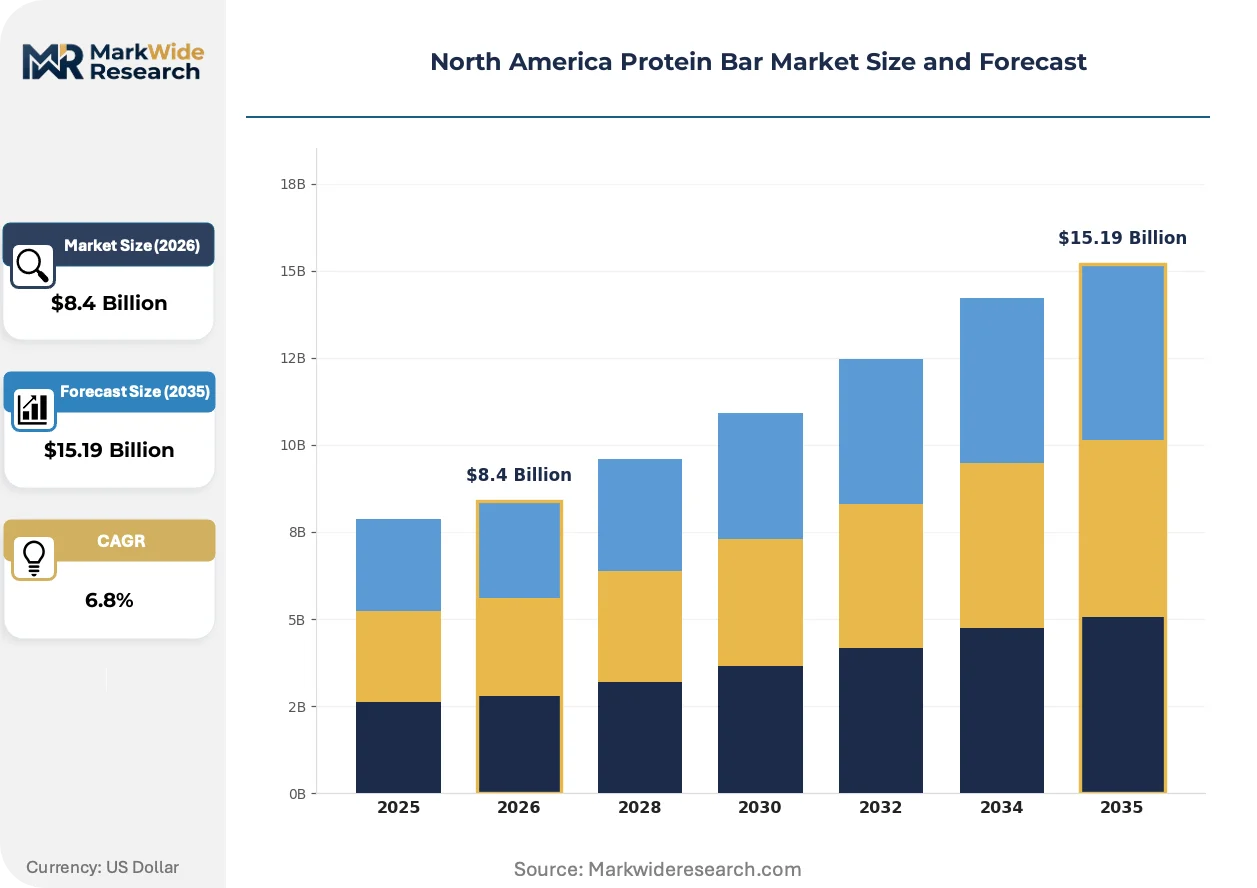
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Nutrition, Meal Replacement, Dietary Supplement, Snack Ingredient Source: Plant-Based, Animal-Based, Dairy, Nut Flavor Profile: Chocolate, Vanilla, Fruity, Savory Packaging Type: Box, Pouch, Wrapper, Bulk |
| Companies Covered | Clif Bar & Company, Quest Nutrition LLC, The Kellogg Company, Glanbia PLC, General Mills Inc, Mars Incorporated, Mondelez International Inc, Simply Good Foods Co, PowerBar, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Protein Bar Market Evolving Landscape
Protein bar manufacturing is undergoing rapid process and ingredient transformation as sustainability mandates and precision nutrition reshape what consumers expect from portable food.
Cold-pressed bar technology is hybridizing with traditional extrusion methods to preserve heat-sensitive micronutrients and probiotic inclusions. Functional food startups and established sports nutrition brands are adopting hybrid equipment lines at pilot scale. This convergence is compressing the texture gap between shelf-stable and refrigerated fresh bars, enabling new premium positioning.
Health Canada's updated protein quality rating enforcement is forcing reformulation of cross-border products to meet DIAAS calculation standards. Manufacturers must now document amino acid digestibility scores rather than rely on crude protein percentages. The sports nutrition segment is responding fastest, with gym-channel brands investing in third-party testing infrastructure to maintain performance claims.
Subscription-based replenishment is displacing impulse purchases in urban professional households. Direct-to-consumer platforms capture recurring orders through personalized flavor rotation and workout-calendar integration. California and New York metropolitan areas show the highest adoption of auto-ship models, reducing price sensitivity through convenience lock-in.
North America Protein Bar Market Segmentation
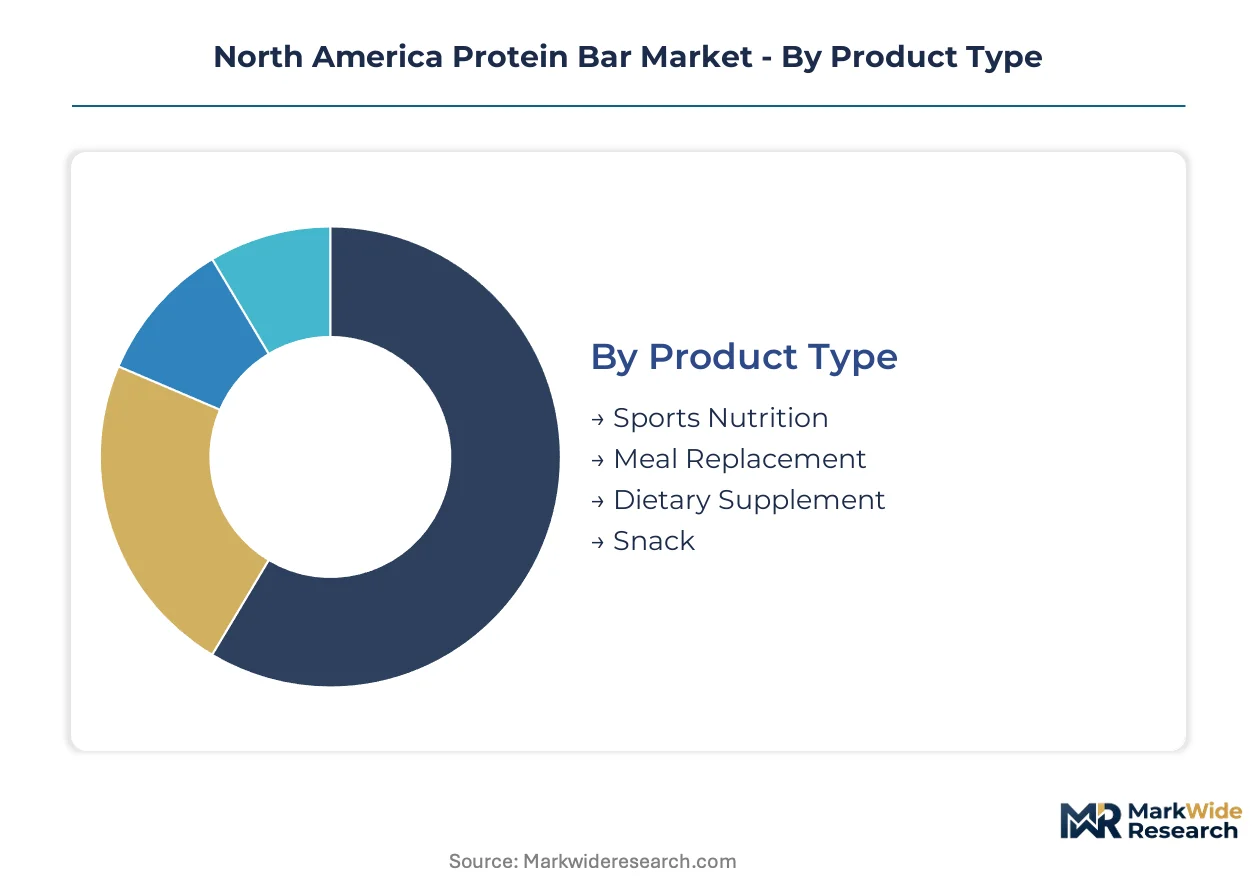
Segmentation in the North America protein bar market reveals how formulation priorities, consumption occasions, and channel economics create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure across the United States and Canada.
Product Type:
Mature positioning dominates established gym and drugstore channels while emerging formats capture meal-replacement occasions.
- Sports Nutrition:Extruded bars with ten to thirty grams of protein per serving, engineered for glycogen replenishment and muscle protein synthesis. Demand concentrates in California metropolitan fitness studios and Pacific Northwest outdoor recreation hubs driven by performance-claim substantiation requirements under FDA guidelines.
- Meal Replacement:Higher caloric density with balanced macronutrient ratios intended for satiety across four-hour windows. Adoption accelerates among remote workers in Toronto and Vancouver seeking desk-side nutrition without preparation time.
- Dietary Supplement:Fortified with vitamins, minerals, or adaptogens positioned under DSHEA regulatory frameworks. Health Canada bilingual labeling requirements complicate cross-border packaging for this segment.
- Snack:Lower protein thresholds emphasizing portability and taste accessibility. Convenience store placement in Texas and Florida suburban corridors sustains volume throughput.
Sports Nutrition handles the majority of throughput; Meal Replacement is expanding most quickly on share.
Ingredient Source:
Cost tier stratification separates premium positioning from commodity formulations.
- Plant-Based:Pea, rice, and fava protein isolates replacing whey in flexitarian households. Saskatchewan and Manitoba production concentration creates supply vulnerability for North American formulators.
- Animal-Based:Collagen and egg white proteins targeting specific amino acid profiles for joint and skin health claims. Premium pricing in Pacific Northwest natural food cooperatives.
- Dairy:Whey and casein concentrates with superior PDCAAS scores under Health Canada calculation methods. Wisconsin and New York dairy belt proximity reduces logistics costs for domestic manufacturers.
- Nut:Almond and peanut butter bases delivering lipid-bound protein with minimal processing. Allergen labeling requirements under FDA Food Allergen Labeling and Consumer Protection Act increase compliance overhead.
Plant-Based is gaining share fastest; Dairy maintains the highest absolute volume position.
Flavor Profile:
Application occasion determines whether sweetness or complexity drives repeat purchase.
- Chocolate:Cocoa-based coatings and inclusions commanding the largest volume share through enrobing production lines. Côte d'Ivoire and Ghana cocoa price volatility compresses margin predictability.
- Vanilla:Clean-label vanilla extract and natural flavor positioning for pediatric and senior nutrition segments. Premium extraction costs limit mass-market penetration.
- Fruity:Berry and citrus inclusions requiring acid-stable protein matrices to prevent syneresis. Summer seasonal demand spikes in Southeast United States.
- Savory:Herb, cheese, and spice profiles targeting meal-replacement occasions without sugar fatigue. Technical challenges with lipid oxidation and shelf-stable texture constrain formulation success rates.
Chocolate dominates absolute throughput; Savory shows the steepest expansion trajectory despite technical barriers.
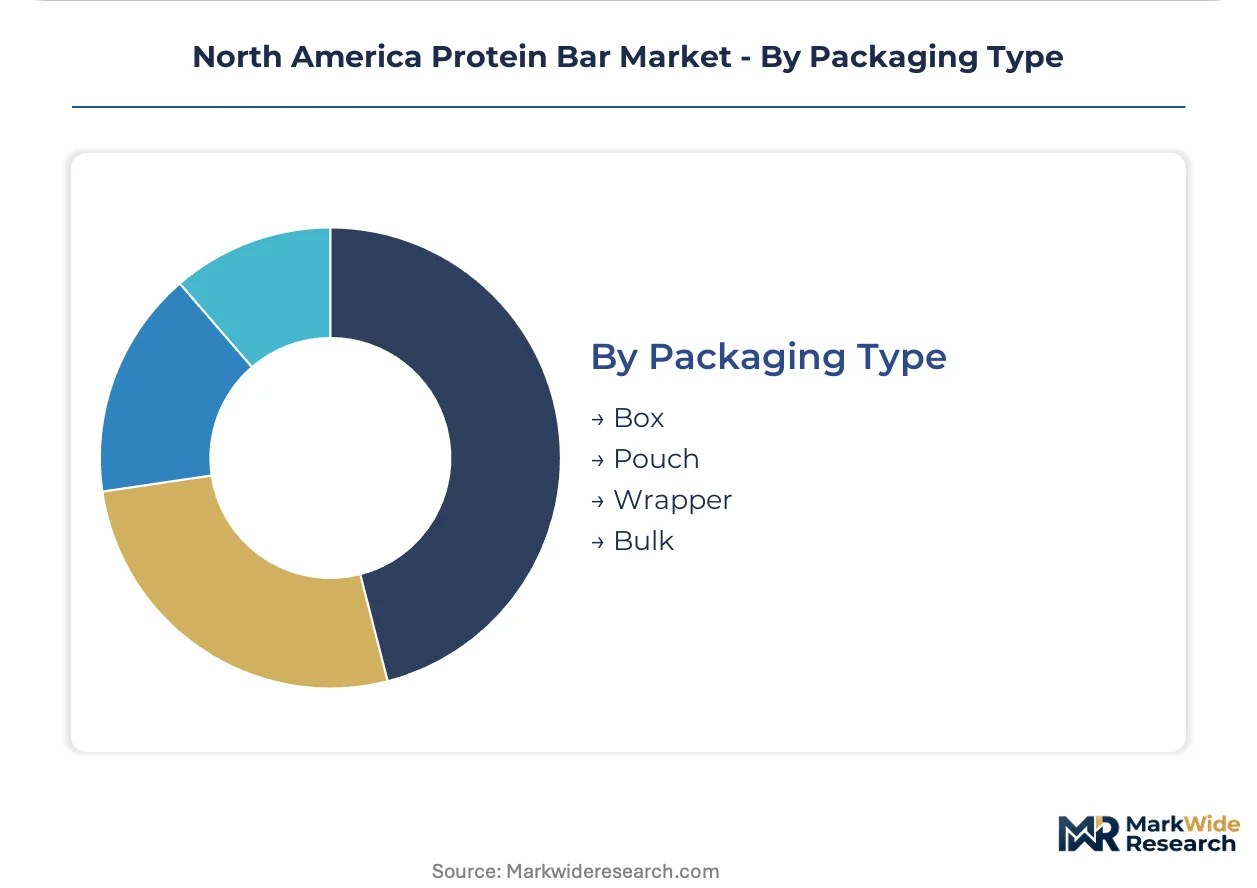
Packaging Type:
Customer type and purchase occasion shape unit economics across channels.
- Box:Multi-count retail packaging for pantry stocking and subscription replenishment models. E-commerce fulfillment centers in Ohio and Pennsylvania optimize for dimensional weight shipping.
- Pouch:Resealable flexible formats for portion-controlled consumption and outdoor portability. Washington and Oregon trailhead retail placement growing.
- Wrapper:Single-serve flow-wrapped units for impulse purchase at gym checkouts and convenience stores. Highest per-unit packaging cost due to material and labor intensity.
- Bulk:Unwrapped or minimally protected formats for food service, corporate wellness programs, and institutional procurement. Minimal branding opportunity limits premium positioning.
Wrapper handles the majority of unit volume; Box is climbing the fastest on revenue contribution through direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pea protein isolate production concentrates in Saskatchewan and Manitoba, creating regional dependency for plant-based formulations across the continent. California and New York metropolitan corridors anchor premium consumption, while Pacific Northwest outdoor recreation hubs sustain performance-positioned demand.
United States
Fitness enthusiasts in Los Angeles and San Francisco sustain premium pricing for functional nutrition products. The FDA's nutrition labeling modernization forces simultaneous compliance investments and clean-label innovation pipelines. Ohio and Pennsylvania e-commerce fulfillment centers optimize box-format dimensional weight shipping for subscription replenishment models.
Canada
Remote workers in Toronto and Vancouver accelerate meal-replacement adoption for desk-side nutrition without preparation time. Health Canada and the Canadian Food Inspection Agency enforce bilingual labeling and protein quality rating methods that influence cross-border formulation decisions. Prairie Provinces pea protein processing facilities supply North American formulators with isolate feedstock.
California
Health-conscious urban populations sustain the highest adoption of auto-ship subscription models through personalized flavor rotation. State-level sugar-tax proposals reshape ingredient economics and regional pricing structures for conventional formulations. Silicon Valley technology corridors incubate direct-to-consumer platforms capturing recurring orders through workout-calendar integration.
Pacific Northwest
Washington and Oregon trail systems and ski resorts offer underpenetrated placement for performance-positioned bars in outdoor recreation channels. Washington and Oregon trailhead retail placement for resealable pouch formats is climbing. Seattle and Portland natural food cooperatives command premium pricing for animal-based collagen and egg white protein variants.
Southeast United States
Convenience store placement in Texas and Florida suburban corridors sustains volume throughput for snack-positioned lower-protein formats. Summer seasonal demand spikes for fruity berry and citrus inclusions requiring acid-stable protein matrices. Regional distribution networks prioritize wrapper-format single-serve flow-wrapped units for impulse purchase velocity.
North America Protein Bar Market Competitive Landscape
Sports nutrition specialists and diversified consumer packaged goods conglomerates split the market between performance-claim authenticity and distribution muscle. The vendor base organizes around three strategic archetypes: pure-play sports nutrition brands, outdoor lifestyle anchors, and legacy food manufacturers extending into functional nutrition. Consolidation pressure intensifies as mid-cap specialists face capital-intensive extrusion equipment upgrades. Dominant competitive moves include direct-to-consumer subscription infrastructure buildout and climate-advocacy branding differentiation.
Within the outdoor lifestyle tier, Clif Bar & Company anchors positioning through sustainability-forward brand identity. Quest Nutrition LLC exemplifies the pure-play sports nutrition archetype with e-commerce-first recurring revenue models. General Mills Inc represents diversified conglomerate extension, leveraging existing distribution networks into convenience and drugstore channels. These three entities collectively illustrate the strategic tension between authentic performance positioning and mass-market accessibility.
| Leading Market Players |
|---|
| Clif Bar & Company |
| Quest Nutrition LLC |
| The Kellogg Company |
| Glanbia PLC |
| General Mills Inc |
| Mars Incorporated |
| Mondelez International Inc |
| Simply Good Foods Co |
| PowerBar |
| Others |
Value Network & Pricing Analysis
Interstate 80 freight corridors linking Saskatchewan pea protein processing to California distribution centers impose cost dynamics that cascade through both supply concentration and downstream price differentiation across the United States and Canada.
Pricing Analysis
FDA nutrition labeling modernization dictates the pricing tier structure across the North America protein bar market. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified sports nutrition from conventional formulations and private-label commodity bars. Price differentiation hinges on certification grade and brand positioning rather than ingredient cost alone. Cost compression in the mid-tier is intensifying because cocoa and whey protein concentrate commodity volatility compresses margin predictability. Convenience store buyers in Texas and Florida suburban corridors exhibit the highest price sensitivity, while Silicon Valley technology corridor professionals show the lowest.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates supply chain risk assessment for cross-border protein bar manufacturers. Pea protein isolate production concentrates in Saskatchewan and Manitoba, while cocoa sourcing draws from Côte d'Ivoire and Ghana, and whey protein concentrate feeds from Wisconsin and New York dairy belt operations. Single-source vulnerability in Prairie Provinces pea processing creates formulation bottlenecks for plant-based product lines. Distribution runs through Ohio and Pennsylvania e-commerce fulfillment centers for subscription box formats, with wrapper-format single-serve units flowing through regional convenience store distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America protein bar market is recovering from input cost cyclicality as cocoa and dairy commodity prices normalize from peak volatility. This cyclical recovery supports margin expansion for manufacturers with locked-in supply contracts.
For Market Incumbents: Build switching-cost moats through direct-to-consumer subscription infrastructure and personalized nutrition algorithms. Quest Nutrition LLC exemplifies this approach with recurring revenue models that reduce slotting fee dependence. Consolidate position by acquiring Prairie Provinces pea protein processing capacity to secure isolate feedstock against supply concentration risk. FDA clean-label enforcement thresholds demand accelerated legal review investments to defend performance claims. For New Entrants and Emerging Players: Pacific Northwest outdoor recreation channels in Washington and Oregon represent the most penetrable entry point for performance-positioned bars, with trailhead retail placement for resealable pouch formats still climbing. Washington and Oregon ski resort concession networks offer underpenetrated placement relative to saturated California gym channels. Launch through climate-advocacy branding partnerships with outdoor sports sponsorships to differentiate from established players. For Investors and Strategic Acquirers: Cold-pressed bar technology specialists with hybrid extrusion pilot lines present the most attractive acquisition target archetype for capability expansion. Long-term viability across the analysis window favors manufacturers with in-house protein isolate extraction or backward integration into ingredient processing. Watch Health Canada DIAAS enforcement implementation as the inflection indicator for cross-border formulation standardization opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Infrastructure | Quest Nutrition LLC's e-commerce-first model reduces slotting fee dependence and captures lifetime value. |
| Climate-Advocacy Brand Repositioning | Clif Bar & Company's sustainability-forward identity anchors differentiation in outdoor lifestyle channels. |
| Backward Integration into Pea Protein Processing | Saskatchewan and Manitoba isolate production concentration creates captive supply advantages for plant-based formulations. |
| Hybrid Cold-Pressed Extrusion Technology | Functional food startups adopting hybrid equipment lines compress the texture gap between shelf-stable and fresh bars. |
| Health Canada Bilingual Labeling Harmonization | Cross-border formulation standardization opens unified production runs for US-Canada distribution economics. |
Research Methodology
A standing panel of brand managers, category buyers at natural food cooperatives, supply planners at protein isolate processors, and channel sales heads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA Food Labeling Guide documentation, USDA organic certification databases, Nielsen retail audit data, and Health Canada regulatory filings. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Scenario-bracketing around commodity price volatility and regulatory enforcement timing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, ingredient source, flavor profile, and packaging format alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation adjusted for input cost normalization and channel shift dynamics. Forecast inputs incorporated Prairie Provinces pea protein processing capacity expansion and California sugar-tax proposal progression.
Macroeconomic conditions sit as an overlay; deviation in cocoa commodity prices, dairy futures volatility, or cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions about FDA enforcement timing and Health Canada DIAAS implementation pace. Material shifts in Prairie Provinces pea protein isolate production capacity or California state-level sugar-tax enactment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Very Low Calorie Desserts Market