
 Asia-Pacific Protein Bar Market | 2026-2036
Asia-Pacific Protein Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Protein Bar Market Outlook
FSSAI nutrition labeling enforcement is expanding the cost-of-entry calculus for imported protein bars entering India. Quest Nutrition leverages captive whey sourcing to sustain margin structures under tighter scrutiny. MuscleBlaze anchors its position through deep distribution into tier-two and tier-three Indian fitness centers. Glanbia PLC competes on dairy protein specialization, occupying the premium sports nutrition tier across Australian and Japanese channels.
Asia-Pacific protein bars are shelf-stable, high-protein food products typically containing 10-30 grams of protein per serving, manufactured through cold extrusion or baked processes with binding agents such as glycerin or maltitol to achieve chewy texture and extended ambient stability. Their primary commercial purpose is delivering convenient macronutrient supplementation for active consumers between meals or post-exercise. Sports Nutrition bars lead value generation due to higher protein density and price positioning, while Plant-Based ingredient sourcing is the fastest-expanding dimension as lactose intolerance rates and vegan athleticism climb across East Asian markets. Meal Replacement bars retain structural importance in Japan and South Korea where portion-controlled eating patterns align with single-serve formats.
FSSAI in India, Food Standards Australia New Zealand, and China's SAMR collectively shape protein bar compliance through divergent allergen declaration rules, protein content verification protocols, and import registration requirements that fragment cross-border formulation strategies. Manufacturers must navigate this regulatory mosaic through localized production or reformulation investments rather than standardized global recipes. Stakeholders should monitor emerging front-of-pack labeling mandates as the decisive variable for shelf access and consumer trust across Southeast Asian retail expansion.
Market Dynamics
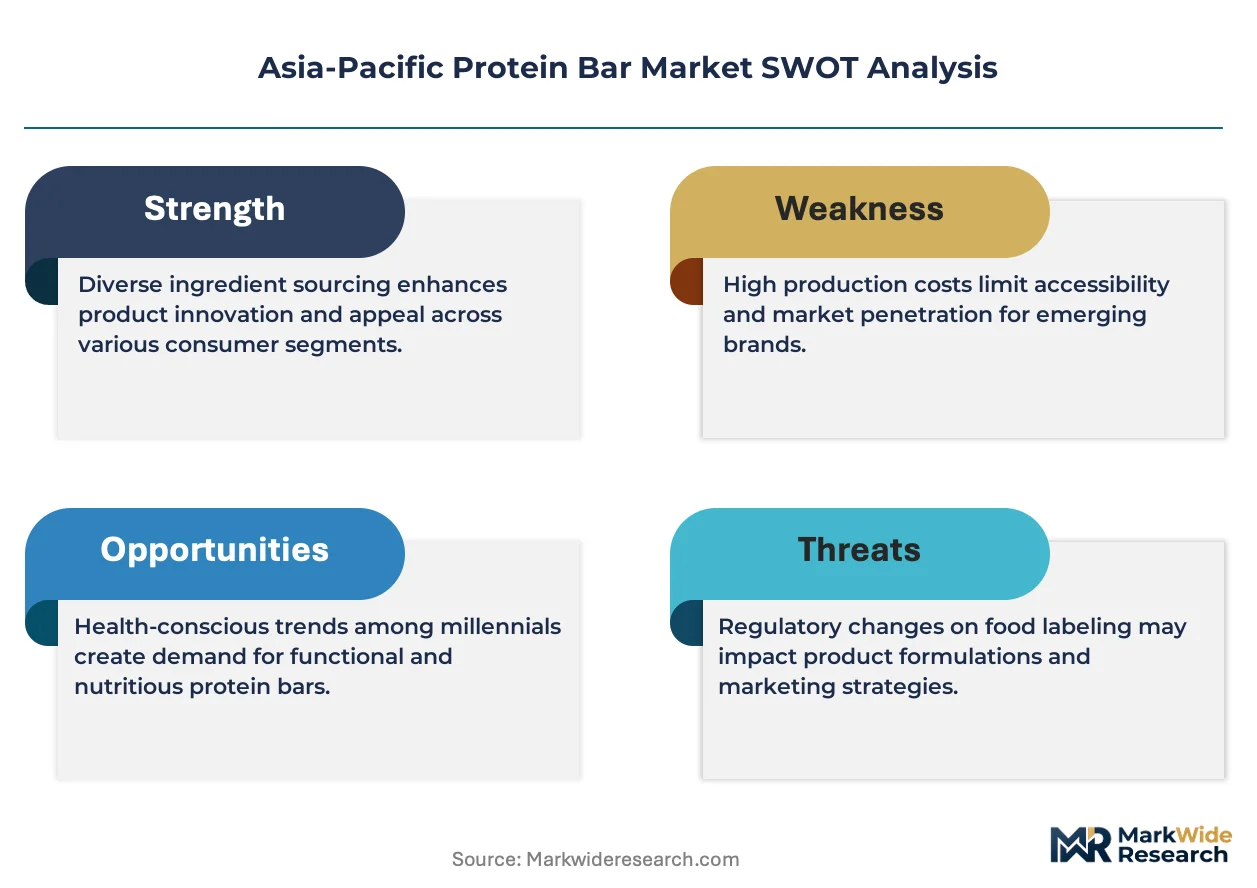
India's FSSAI nutrition labeling enforcement is compressing margins for imported protein bars while amplifying domestic manufacturing advantages across tier-two and tier-three fitness centers.
Growth Catalysts
- FSSAI Labeling Mandates:Tightened protein content verification protocols in India are disqualifying substandard imports and clearing shelf space for compliant domestic producers.
- Lactose Intolerance Prevalence:East Asian markets are accelerating plant-based protein adoption as whey alternatives gain formulation parity through pea-rice protein blends.
- Gym Penetration:China's tier-one cities are sustaining premium protein bar consumption through elevated disposable income and boutique fitness studio density.
Market Restraints
- Whey Protein Concentration:Global dairy protein supply chains center on New Zealand and Australian processors, exposing margin volatility to Oceania climate events.
- Cross-Border Registration:China's SAMR import filing requirements impose 12-18 month approval timelines that freeze formulation standardization across Asia-Pacific portfolios.
- Whole Food Substitution:Fresh prepared meals and yogurt parfaits in Japanese convenience retail are capturing share from ambient-stable protein formats.
Strategic Opportunities
- Vietnam and Philippines:Gym membership growth in Ho Chi Minh City and Manila is outpacing protein bar distribution infrastructure, creating first-mover whitespace.
- PLI Scheme Alignment:India's production-linked incentive schemes for food processing are subsidizing domestic extrusion and packaging capacity expansion.
- Telehealth Integration:Dietitian-prescribed sports nutrition protocols in South Korea are opening clinical channel access for medical-grade protein formulations.
Industry Challenges
- Reformulation Velocity:Divergent allergen declaration rules between Food Standards Australia New Zealand and FSSAI force parallel R&D tracks that strain technical teams.
- Cold Chain Gaps:Ambient-stable bar requirements conflict with emerging clean-label preservative-free demand, squeezing shelf-life engineering capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Protein Bar Market |
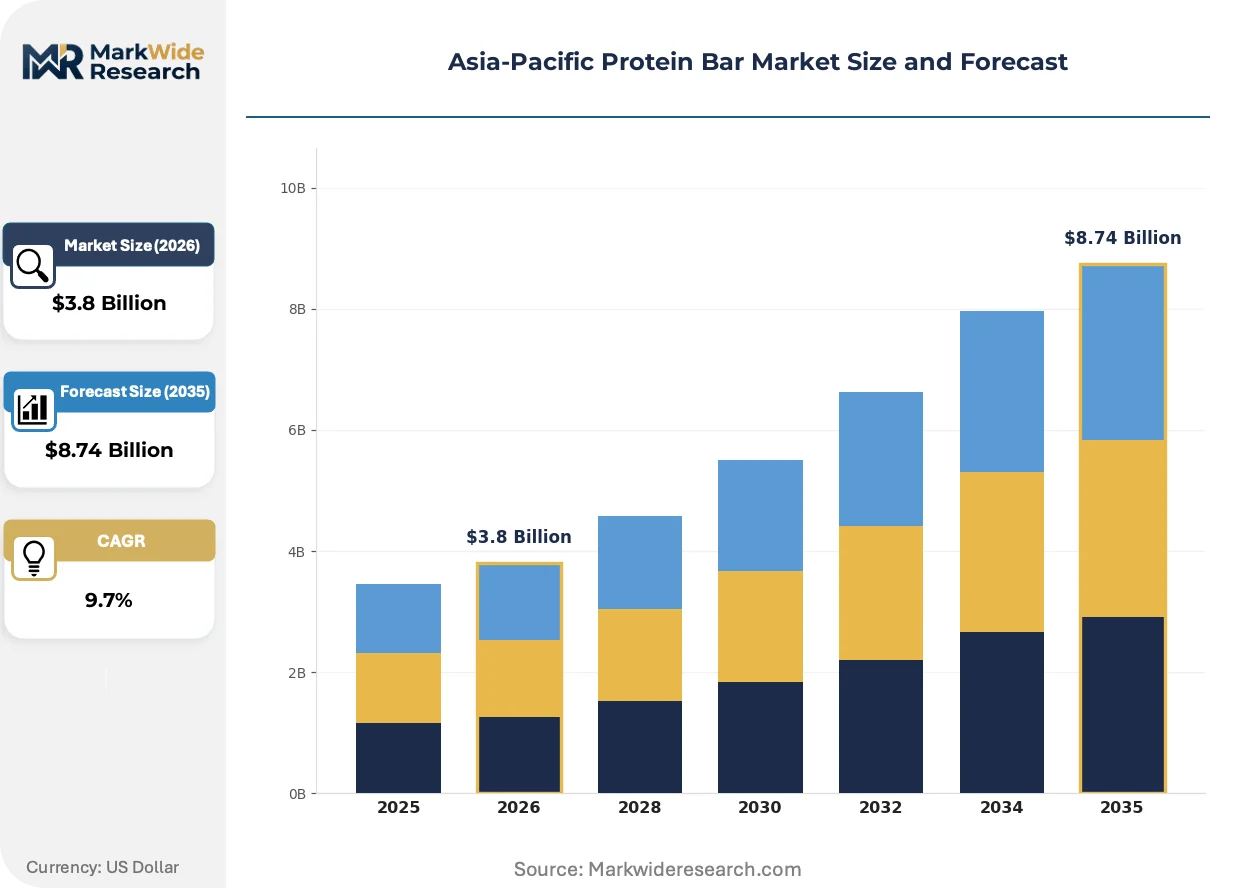
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacement, Sports Nutrition, Snack Bar, Organic Ingredient Source: Whey Protein, Plant-Based, Casein, Egg Protein Flavor Profile: Chocolate, Vanilla, Berry, Peanut Butter Target Consumer: Athletes, Health-Conscious Individuals, Fitness Enthusiasts, Weight Management |
| Companies Covered | PepsiCo, Clif Bar & Company, Glanbia PLC, Amway Corporation, Quest Nutrition, General Mills, Mondelez International, MuscleBlaze, The Kellogg Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Protein Bar Market Strategic Shifts
Asia-Pacific protein bar innovation is pivoting from macronutrient density wars toward texture engineering and regulatory pre-compliance as competitive differentiators.
Precision fermentation-derived dairy proteins are converging with traditional whey processing economics. Singaporean and Australian ingredient startups are scaling microbial protein platforms that bypass lactose entirely. This convergence is compressing the cost premium between animal and precision-fermented protein isolates, enabling mid-tier brands to claim clean-label dairy credentials without supply chain exposure to Oceania powder markets.
Food Standards Australia New Zealand is implementing stricter glycemic index disclosure requirements for meal replacement classifications. Manufacturers must now commission third-party clinical testing for products positioning above 20 grams protein per serve. Australian brands with existing sports nutrition certification pipelines are absorbing these costs faster than Asian importers, shifting competitive advantage toward Antipodean formulation expertise.
Gym-goers in Seoul and Tokyo are fragmenting their protein consumption across multiple micro-servings rather than single post-workout bars. Convenience retail is responding with 15-gram mini-format launches that displace traditional 60-gram SKUs. This pattern is most visible in South Korean CU and 7-Eleven chains, where grab-and-go protein now competes directly with onigiri and kimbap for chilled fixture space.
Asia-Pacific Protein Bar Market Segmentation
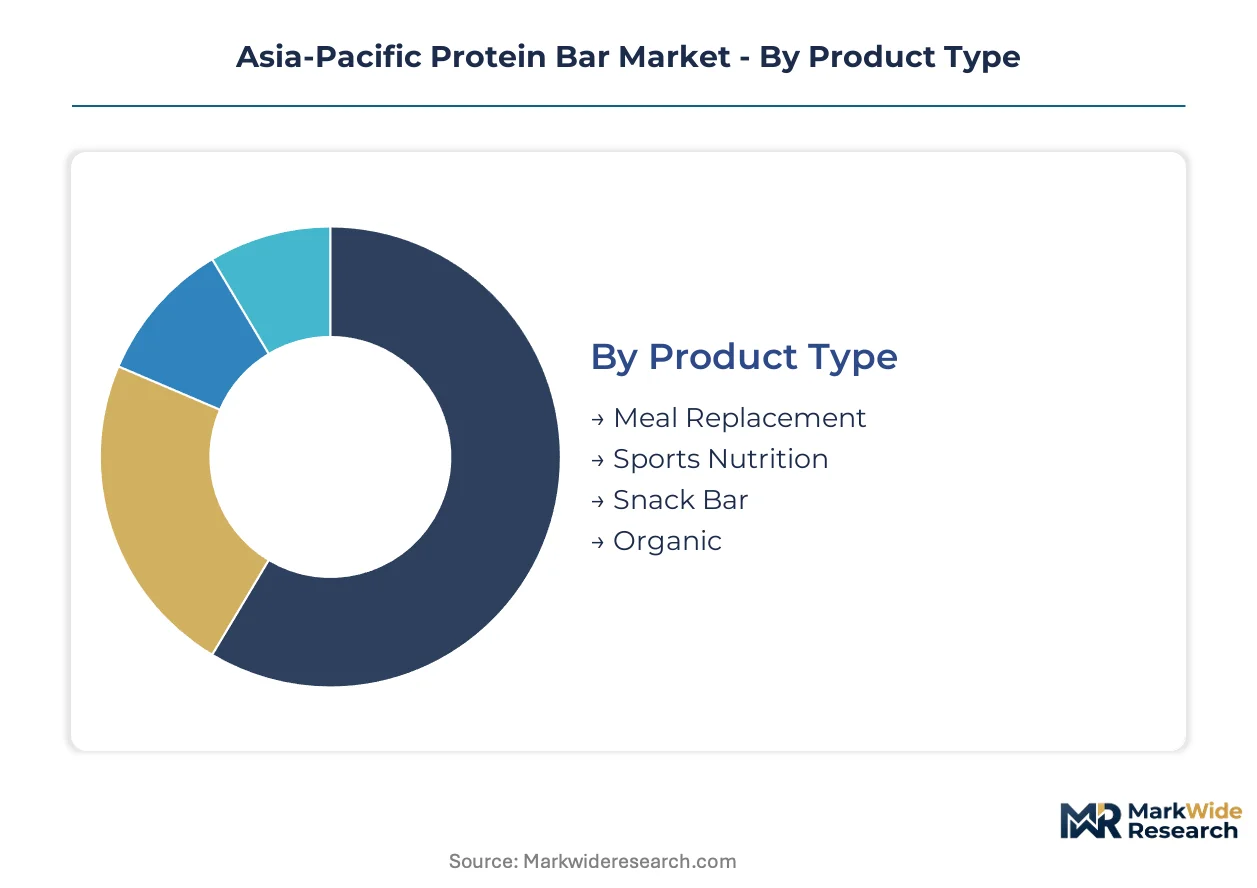
Asia-Pacific protein bar segmentation reveals how manufacturers balance standardized formulations for scale against customized variants for regulatory compliance and palate localization. Each dimension carries distinct margin implications and supply chain requirements.
Product Type:
Standardization pressure peaks in mass-market formats while premium tiers demand bespoke texture engineering and clinical validation protocols.
- Sports Nutrition:Cold-extruded bars delivering 20-30 grams protein per serve with glycerin-bound chew profiles. Demand concentrates in Shanghai and Beijing boutique fitness studios where disposable income supports premium positioning alongside FSSAI-compliant domestic alternatives.
- Meal Replacement:Portion-controlled formulations with vitamin fortification and glycemic index certification per Food Standards Australia New Zealand protocols. Japanese convenience retail channels favor these for single-serve meal substitution in Tokyo and Osaka commuter corridors.
- Snack Bar:Lower protein density formats (10-15 grams) competing with traditional confectionery. Indian tier-two cities show rising penetration as gym culture spreads beyond metropolitan cores.
- Organic:Certified ingredient sourcing with full traceability documentation. Australian organic dairy protein supply chains anchor this tier for export into Southeast Asian premium retail.
Most installed capacity flows through Sports Nutrition. Expansion is steepest in Meal Replacement.
Ingredient Source:
Cost tier stratification separates commodity dairy proteins from precision-fermented and plant-based alternatives with divergent margin structures.
- Whey Protein:Concentrate and isolate formats dominating sports nutrition formulations. New Zealand and Australian processors control global supply, exposing pricing to Oceania climate volatility and currency fluctuation.
- Plant-Based:Pea-rice protein blends achieving formulation parity with whey in East Asian markets where lactose intolerance prevalence exceeds regional averages. Singaporean precision-fermentation startups are compressing cost premiums through microbial protein platforms.
- Casein:Slow-release protein for overnight recovery applications. Japanese sports nutrition specialists favor this for sleep-phase muscle protein synthesis positioning.
- Egg Protein:Allergen-constrained niche with complete amino acid profiles. South Korean functional food manufacturers utilize this for clean-label alternatives to dairy-dominant formulations.
Volume concentration remains with Whey Protein. Plant-Based is gaining share fastest through East Asian market penetration.
Flavor Profile:
Palate localization intensity varies by format, with chocolate and vanilla permitting global recipes while berry and peanut butter demand regional adaptation.
- Chocolate:Universal acceptance enabling standardized global production runs. Cocoa butter alternatives and glycemic index management dominate technical differentiation.
- Vanilla:Neutral base for protein masking in high-density formulations. Australian brands leverage existing sports nutrition certification pipelines for rapid flavor line extensions.
- Berry:Yuzu and matcha variants for Japanese and South Korean convenience retail. Local fruit sourcing requirements fragment supply chain standardization.
- Peanut Butter:Texture engineering challenges with oil separation control. Indian domestic manufacturers exploit FSSAI compliance advantages for this flavor-dominant segment.
Chocolate and Vanilla absorb majority production volume. Berry formats are expanding most quickly through East Asian flavor localization.
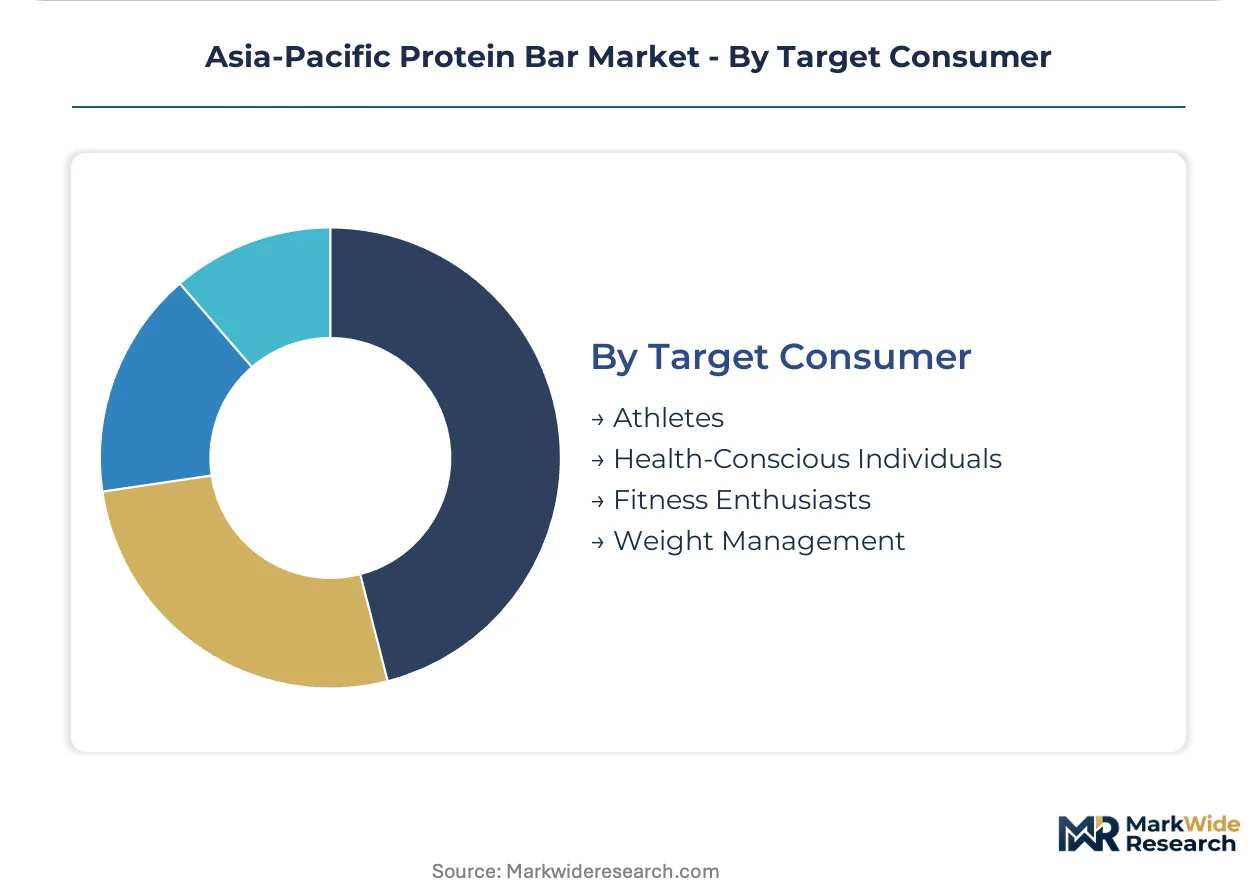
Target Consumer:
Customer maturity separates established athlete segments with predictable purchase patterns from emerging health-conscious demographics with experimental buying behavior.
- Fitness Enthusiasts:Core repeat purchasers with brand loyalty and subscription-based consumption. India's tier-two and tier-three gym networks represent underdeveloped distribution infrastructure with first-mover potential.
- Athletes:Performance-verified formulations with batch-tested certification requirements. Australian and Japanese channels demand third-party analytical validation for competitive positioning.
- Health-Conscious Individuals:Clean-label and preservative-free demand creating shelf-life engineering tension. Seoul and Tokyo micro-format trends (15-gram servings) originate from this segment's grazing behavior.
- Weight Management:Calorie-controlled and portion-regulated formulations. South Korean telehealth integration is opening clinical channel access for dietitian-prescribed protocols.
Fitness Enthusiasts represent the largest addressable base. Health-Conscious Individuals are climbing the fastest through mini-format adoption and clean-label premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific protein bar industry traces its commercial lineage to Australian sports nutrition exports in the early 2000s, with Sydney and Melbourne manufacturers establishing cold-extrusion standards later adopted across East Asian markets. Japanese convenience retail then pioneered single-serve meal replacement formats that reshaped regional consumption patterns.
China
Shanghai and Beijing boutique fitness studios sustain premium protein bar demand through elevated disposable income and boutique studio density. SAMR import filing requirements impose 12-18 month approval timelines that freeze formulation standardization. Yangtze River Delta manufacturing clusters are absorbing domestic production shifts to bypass cross-border registration delays.
India
Tier-two and tier-three gym networks in Pune and Hyderabad represent underdeveloped distribution infrastructure with first-mover potential. FSSAI nutrition labeling enforcement is compressing margins for imported bars while amplifying domestic manufacturing advantages. Maharashtra and Karnataka food processing corridors are expanding extrusion capacity under PLI scheme subsidies.
Japan
Tokyo and Osaka commuter corridors favor portion-controlled meal replacement formats aligned with single-serve eating patterns. METI standards for functional food claims require clinical validation that elevates compliance costs for foreign entrants. Kanto region convenience retail chains are fragmenting protein consumption into 15-gram micro-servings displacing traditional 60-gram SKUs.
Australia
Sydney and Melbourne sports nutrition specialists anchor premium tier positioning through third-party analytical certification pipelines. Food Standards Australia New Zealand glycemic index disclosure requirements for meal replacement classifications favor domestic incumbents with existing testing infrastructure. Victorian dairy protein processing clusters supply whey concentrate and isolate formats across Asia-Pacific export channels.
South Korea
Seoul Capital Area gym penetration and telehealth integration are opening clinical channel access for dietitian-prescribed sports nutrition protocols. MFDS regulations for medical-grade functional foods create certification barriers that domestic manufacturers navigate faster than importers. Busan-Ulsan logistics hubs facilitate refrigerated distribution of clean-label preservative-free formats competing with ambient-stable alternatives.
Asia-Pacific Protein Bar Market Competitive Environment
The competitive structure tilts toward diversified nutrition conglomerates with captive dairy supply chains and domestic compliance specialists leveraging regulatory proximity. Market concentration splits between global FMCG portfolios with protein bar line extensions and focused sports nutrition houses with certified manufacturing pipelines. Two strategic archetypes dominate: multinational food corporations with extrusion capacity scale, and regional specialists with localized formulation expertise. Competitive moves center on backward integration into dairy protein sourcing and geographic licensing partnerships to bypass import registration bottlenecks.
Among multinational nutrition portfolios, PepsiCo and General Mills exemplify scale-driven archetypes with cross-category brand leverage and established Asia-Pacific distribution infrastructure. Glanbia PLC occupies a position within the premium sports nutrition tier, representing dairy protein specialization across Australian and Japanese channels. MuscleBlaze anchors the domestic compliance specialist archetype, leveraging FSSAI regulatory proximity to capture tier-two and tier-three Indian fitness center penetration that foreign entrants struggle to access.
| Leading Market Players |
|---|
| PepsiCo |
| Clif Bar & Company |
| Glanbia PLC |
| Amway Corporation |
| Quest Nutrition |
| General Mills |
| Mondelez International |
| MuscleBlaze |
| The Kellogg Company |
| Others |
Value Chain & Pricing Dynamics
FSSAI nutrition labeling mandates gate qualified supply and premium-tier pricing access for protein bars entering India, compressing margins for imported formulations while domestic manufacturers capture compliance arbitrage. This regulatory filter reshapes procurement decisions across Asia-Pacific as buyers weigh certified domestic sourcing against reformulation costs for cross-border portfolios.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the Asia-Pacific protein bar market by certification grade and protein density. Sports nutrition bars with FSSAI verification or Food Standards Australia New Zealand glycemic index certification command price premiums over unverified alternatives. Pricing pressure stems from whey protein concentrate volatility tied to New Zealand dairy auction cycles. Fitness enthusiasts in Chinese tier-one cities show least price sensitivity, while Indian tier-two snack bar buyers drive volume through economy-tier procurement.
Supply Chain Analysis
Freight cost differentials between Oceania dairy protein origins and Southeast Asian manufacturing hubs favor localized extrusion capacity in Maharashtra and Karnataka food processing corridors. Whey protein concentrate and isolate feedstocks center on New Zealand and Australian processors, with pea-rice protein blends emerging from Singaporean precision-fermentation platforms. Single-source vulnerability concentrates in Oceania climate exposure. Distribution runs through gym network direct-to-consumer channels in India and Japanese convenience retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific protein bar market functions as a geographic-arbitrage play where FSSAI compliance costs in India diverge from SAMR registration timelines in China, creating manufacturing-location premiums for domestic extrusion capacity.
For Market Incumbents: Cement channel control through captive whey sourcing arrangements with New Zealand processors to buffer Oceania climate volatility. Deepen FSSAI certification pipelines ahead of front-of-pack labeling mandates to defend shelf access against emerging domestic competitors in Indian tier-two fitness centers. For New Entrants and Emerging Players: Launch via telehealth-integrated clinical channels in South Korea where MFDS medical-grade functional food certification creates defensible positioning. Target Vietnam and Philippines gym membership growth in Ho Chi Minh City and Manila ahead of protein bar distribution infrastructure buildout. For Investors and Strategic Acquirers: Roll-up economics work for domestic compliance specialists with FSSAI regulatory proximity because fragmented Indian tier-two and tier-three fitness center distribution resists scale entry by multinational portfolios. Watch SAMR import filing timeline compression as the signal for China manufacturing shift inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Protein Sourcing | Captive whey supply from New Zealand processors insulates margin structures from Oceania climate auction volatility. |
| FSSAI Pre-Certification Investment | Early compliance with front-of-pack labeling mandates secures shelf access ahead of enforcement tightening in Indian retail. |
| Precision-Fermentation Protein Partnership | Singaporean microbial protein platforms bypass lactose supply chains entirely for East Asian plant-based positioning. |
| Telehealth Channel Integration | South Korean dietitian-prescribed protocols open clinical access for medical-grade formulations beyond commodity sports nutrition. |
| Mini-Format Product Line Extension | 15-gram SKUs align with Seoul and Tokyo convenience retail fragmentation competing against onigiri and kimbap fixtures. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sports nutrition brand managers, FSSAI regulatory consultants, gym network procurement heads, and Australian dairy protein processors with secondary validation against customs records, FSSAI enforcement circulars, and Food Standards Australia New Zealand glycemic index disclosure protocols. Bottom-up extrusion capacity assessments and top-down retail audit data triangulated volume estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baseline consumption patterns and post-regulatory enforcement adjustment phases. Segmentation modeling spanned product type, ingredient source, flavor profile, and target consumer archetype across the analysis window. CAGRs derived from protein density adoption curves and gym penetration elasticity coefficients, with whey protein concentrate price indices and PLI scheme subsidy schedules as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMR import filing timeline extensions or FSSAI front-of-pack mandate acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Functional Water Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Antioxidant Beverages Market