
 Hiking Functional Energy Bars Market | 2026-2036
Hiking Functional Energy Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Hiking Functional Energy Bars Market Insights
Clean-label ingredient certification is rotating through the hiking functional energy bars category as the dominant quality-tier upgrade. Clif Bar leverages its organic supply chain to command premium shelf placement in outdoor specialty retailers. Nature Valley sustains mass-market penetration through economies of scale in granola bar production. PROBAR specializes in whole-food formulations that appeal to ultralight backpackers seeking caloric density.
Hiking functional energy bars are shelf-stable, nutrient-dense food products engineered to deliver balanced macronutrients and electrolyte replenishment during sustained physical exertion in remote terrain. Manufacturers typically cold-press or bake blends of oats, nut butters, dried fruits, and protein isolates into portable formats rated for temperature stability across alpine and desert conditions. Protein bars occupy the highest margin tier within product type segmentation due to ingredient cost premiums and sports-performance positioning. Organic ingredient formulations capture accelerating demand among Leave No Trace practitioners who prioritize environmental supply chain accountability. Individually wrapped packaging dominates trail-ready convenience despite rising sustainability scrutiny over single-use materials.
The FDA governs nutrition fact panel accuracy and health claim substantiation for all bars sold in the United States, while the USDA organic seal governs certification premiums that command retail price separation. The EPA's emerging guidance on compostable packaging materials will reshape supplier qualification requirements for brands targeting federal land access permits. Stakeholders must monitor how state-level extended producer responsibility laws in California and Oregon cascade into packaging redesign timelines and material cost structures.
Market Dynamics
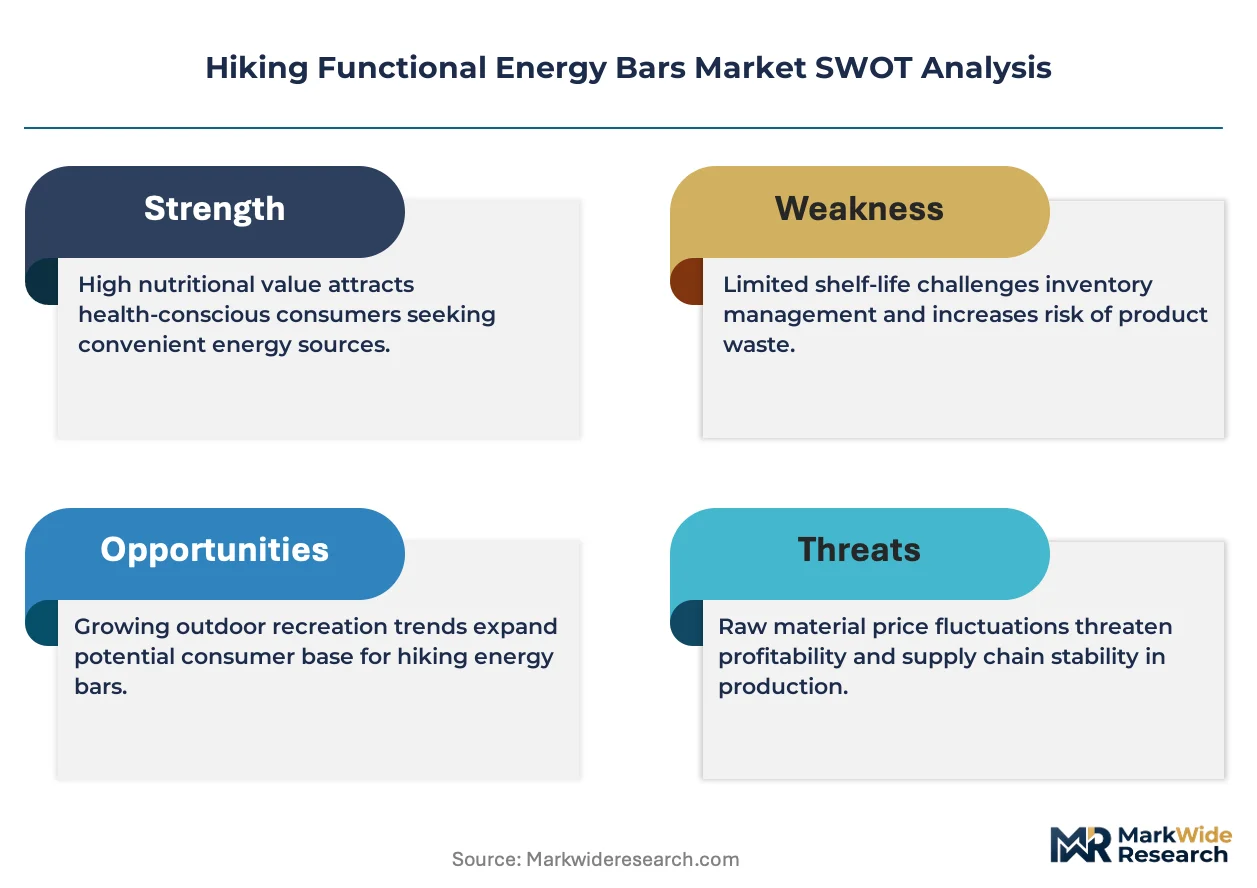
The FDA's updated nutrition labeling requirements for packaged foods are forcing reformulation across the hiking functional energy bars category, compressing shelf-stable product development timelines while elevating clean-label certification as the primary quality differentiator in outdoor specialty retail channels.
Growth Catalysts
- Trail Running Participation Surge:Alpine climbers and trail runners represent an expanding buyer segment seeking caloric density in portable formats. This end-use vertical drives demand for electrolyte-replenishment formulations rated for temperature stability across remote terrain.
- USDA Organic Certification Premiums:The USDA organic seal governs certification premiums that command retail price separation. Leave No Trace practitioners prioritize environmental supply chain accountability, accelerating demand for organic ingredient formulations.
- Pacific Northwest Demand Concentration:Outdoor recreation participation rates remain elevated in the Pacific Northwest region of the United States. This geographic cluster concentrates buyer density and shapes regional distribution priorities for shelf-stable nutrient-dense products.
Market Restraints
- Protein Isolate Input Cost Volatility:Protein bars occupy the highest margin tier within product type segmentation due to ingredient cost premiums. Whey and plant-based protein isolate prices fluctuate with agricultural commodity cycles, compressing manufacturer margins.
- Single-Use Packaging Regulatory Friction:Rising sustainability scrutiny over individually wrapped materials creates compliance pressure. The EPA's emerging guidance on compostable packaging materials will reshape supplier qualification requirements for brands targeting federal land access permits.
- Granola Bar Substitution Threat:Nature Valley sustains mass-market penetration through economies of scale in granola bar production. Lower-cost alternatives capture price-sensitive consumers seeking portable nutrition without sports-performance positioning.
Strategic Opportunities
- California Extended Producer Responsibility Laws:State-level packaging redesign timelines and material cost structures create first-mover advantage for compostable-format innovators. Brands securing compliant supply chains early will access premium shelf placement in West Coast outdoor retailers.
- Ultralight Backpacker Segment White Space:Whole-food formulations appealing to ultralight backpackers remain underdeveloped relative to protein-bar saturation. Caloric density per ounce represents an unmet specification in current product portfolios.
- Cold-Press and Low-Temperature Bake Convergence:Manufacturing technology pairing cold-press forming with low-temperature dehydration preserves enzyme activity and extends shelf stability. This process innovation enables clean-label claims without synthetic preservatives.
Industry Challenges
- Compostable Certification Timeline Compression:ASTM D6400 and BPI certification for compostable packaging requires 180-day testing cycles that lag product launch schedules. Brands face launch delays or non-compliant material substitutions.
- Organic Supply Chain Reconfiguration Friction:Clif Bar's captive organic supply chain demonstrates the capital intensity of backward integration into certified ingredient sourcing. Mid-tier manufacturers lack balance sheet capacity to replicate this structure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hiking Functional Energy Bars Market |
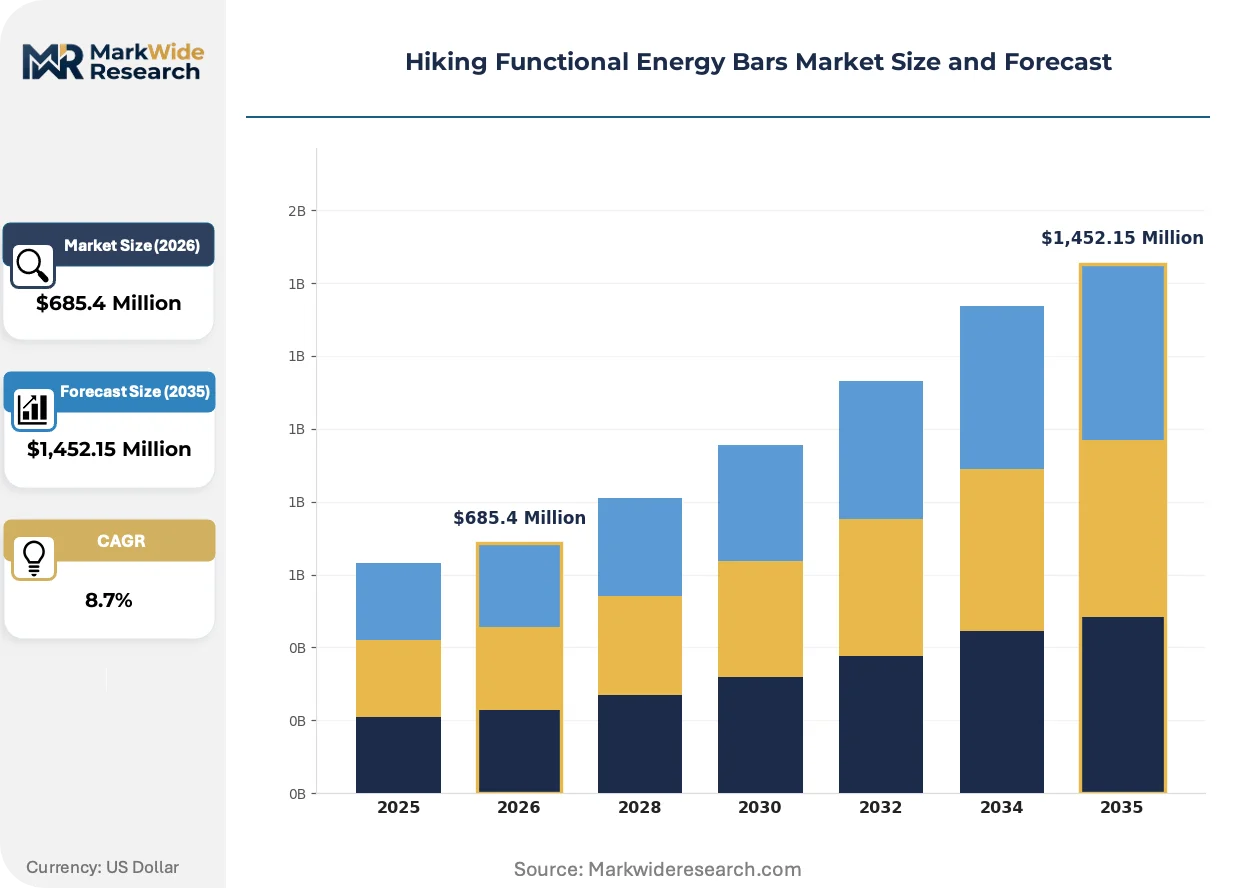
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Nut Bars, Granola Bars, Vegan Bars Ingredient Type: Organic Ingredients, Gluten-Free, High-Fiber, Low-Sugar Target Consumer: Athletes, Outdoor Enthusiasts, Health-Conscious Individuals, Students Packaging Type: Bags, Boxes, Pouches, Individually Wrapped |
| Companies Covered | Clif Bar, Nature Valley, Luna Bar, PROBAR, Kate's Real Food, TAOS Bakes, Bobo’s Oat Bars, General Mills, Chia Charge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hiking Functional Energy Bars Market Trends and Innovations
Cold-press manufacturing technology is decomposing traditional baked-bar dominance while regulatory pressure on packaging materials accelerates material science investment. Buyer behavior shifts toward supply chain transparency are reshaping certification requirements.
Low-temperature dehydration equipment is decomposing the baked-bar format's cost advantage by enabling whole-food preservation without synthetic binders. Ultralight backpackers and alpine climbers adopt these products at accelerating rates despite 15-20% price premiums. The technology is decomposing margin structures for conventional high-heat processing lines as clean-label claims become table stakes in outdoor specialty retail.
The EPA's emerging compostable packaging guidance is mandating ASTM D6400 or BPI certification for brands seeking federal land access permits. Industrial consequence includes supplier qualification overhauls and 12-18 month packaging redesign timelines. Products targeting Pacific Northwest national parks and Bureau of Land Management terrain face the most immediate compliance pressure, with manufacturers accelerating biodegradable film partnerships.
Leave No Trace practitioners now verify supply chain accountability through third-party organic certification rather than brand marketing claims. This behavioral shift displaces conventional loyalty programs in outdoor specialty retail channels. The Pacific Northwest and Colorado Front Range demonstrate the most pronounced preference rotation, with REI and independent gear shops prioritizing USDA-certified inventory.
Hiking Functional Energy Bars Market Segmentation
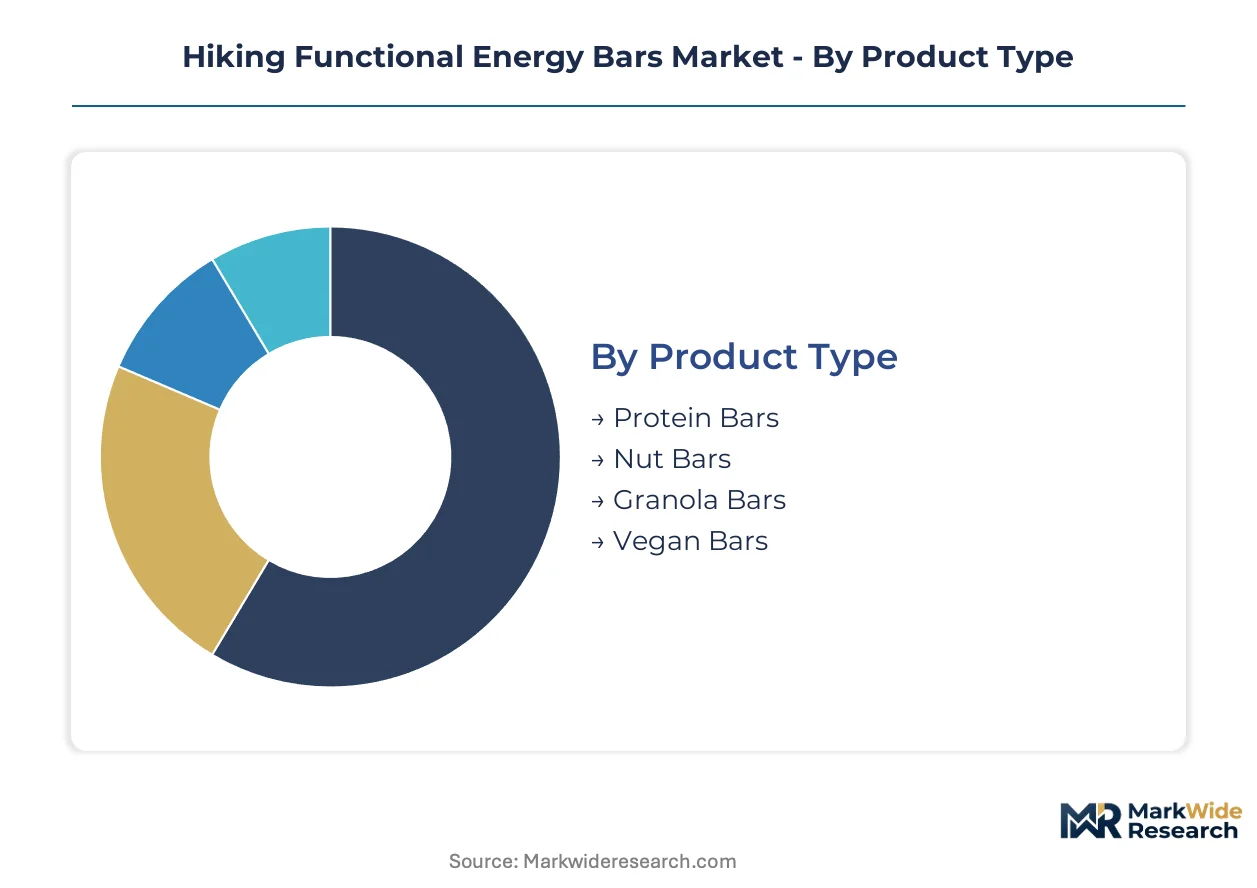
Segmentation in the hiking functional energy bars market determines regulatory compliance pathways, margin architecture, and distribution channel selection. Each dimension carries distinct certification requirements and end-use specifications that reshape manufacturer priorities.
Product Type:
FDA nutrition labeling thresholds and USDA organic certification tiers differentiate margin potential across format categories.
- Protein Bars:Cold-pressed or baked formulations incorporating whey, casein, or plant-based isolates deliver 15-25g protein per serving. Alpine climbers and trail runners in the Pacific Northwest drive concentrated demand for electrolyte-fortified variants rated for temperature stability across remote terrain. Whey and plant protein input costs fluctuate with agricultural commodity cycles, compressing manufacturer margins.
- Nut Bars:Whole-food formulations centering almond, cashew, or peanut butter bases achieve caloric density without synthetic binders. Ultralight backpackers prioritize these products for ounce efficiency, though 15-20% price premiums limit mass-market penetration.
- Granola Bars:Oat-based formats with dried fruit inclusions sustain volume leadership through economies of scale in high-heat processing.
- Vegan Bars:Plant-protein and seed-based compositions exclude all animal derivatives to capture dietary-restricted segments.
Protein bars handle the majority of throughput; nut bars are the fastest mover on share.
Ingredient Type:
Certification premiums stratify pricing power across supply chain accountability tiers.
- Organic Ingredients:USDA organic seal compliance mandates third-party verification of synthetic pesticide exclusion and non-GMO status. Leave No Trace practitioners in Colorado and the Pacific Northwest prioritize environmental supply chain accountability, accelerating demand concentration in REI and independent gear shops.
- Gluten-Free:Formulations excluding wheat, barley, and rye derivatives target celiac and sensitivity populations with dedicated production line requirements.
- High-Fiber:Chicory root, inulin, and oat fiber fortifications support digestive health positioning.
- Low-Sugar:Monk fruit, stevia, and allulose substitutions reduce glycemic impact while maintaining palatability.
Organic ingredients command the steepest certification premiums; low-sugar formulations are climbing the fastest on consumer preference indices.
Target Consumer:
Activity intensity and purchase frequency separate volume buyers from premium segment captives.
- Athletes:Competitive endurance athletes require precise macronutrient ratios and electrolyte replenishment for sustained exertion.
- Outdoor Enthusiasts:Weekend hikers and campers prioritize shelf stability and portability over performance optimization.
- Health-Conscious Individuals:Clean-label seekers verify supply chain accountability through certification rather than brand marketing claims.
- Students:Price-sensitive convenience buyers substitute granola bars for meal replacement in campus retail channels.
Outdoor enthusiasts sustain the largest purchase volume; health-conscious individuals are gaining share fastest on certification-driven loyalty rotation.
Packaging Type:
EPA emerging guidance on compostable materials and state extended producer responsibility laws reshape format viability.
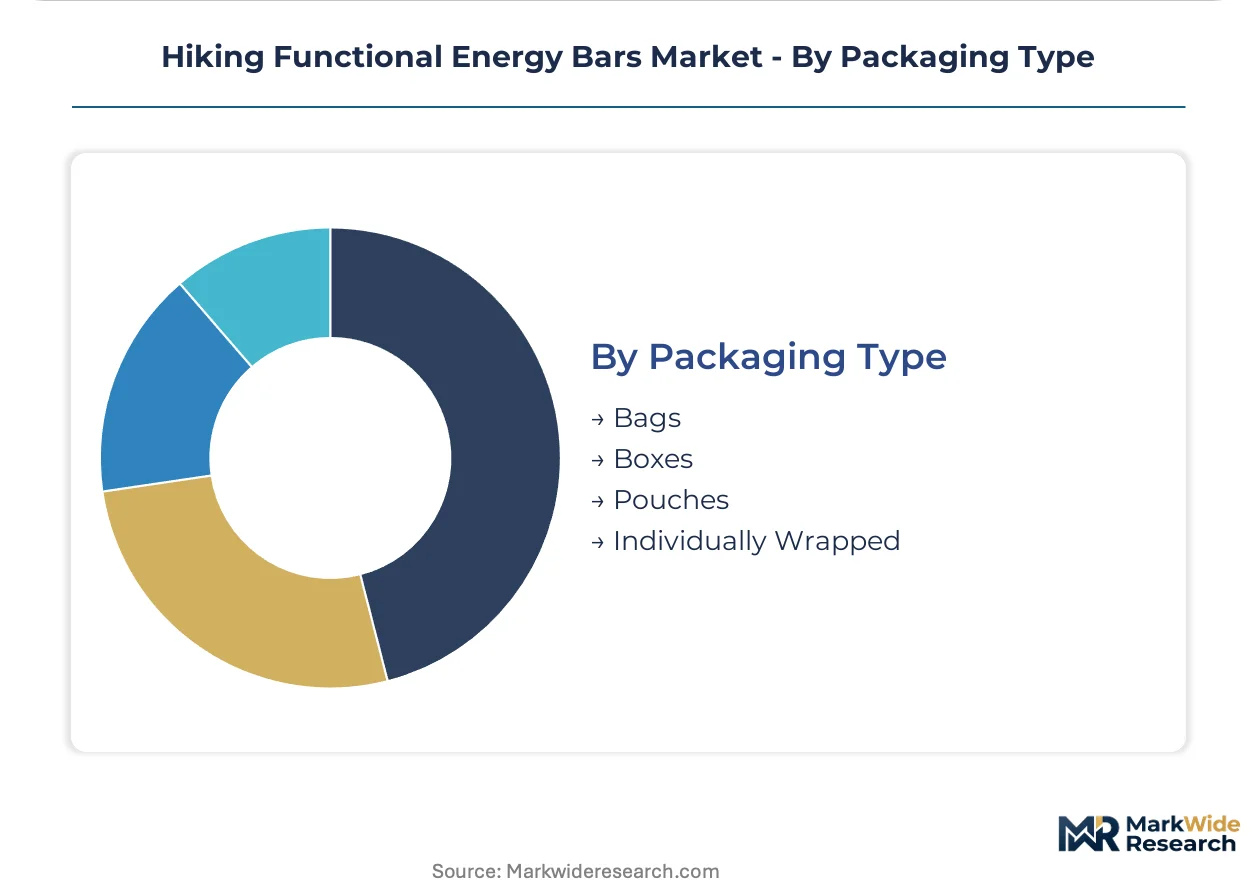
- Individually Wrapped:Single-serve films dominate trail-ready convenience despite rising sustainability scrutiny. California and Oregon extended producer responsibility laws compress redesign timelines to 12-18 months for ASTM D6400 or BPI certification compliance.
- Bags:Multi-serve resealable formats reduce per-unit packaging cost for basecamp and group consumption scenarios.
- Boxes:Retail-ready secondary packaging enables shelf placement in outdoor specialty and mass-market channels simultaneously.
- Pouches:Flexible stand-up formats balance portability with reduced material weight for ultralight applications.
Individually wrapped formats handle the majority of unit throughput; pouches are expanding most quickly on sustainability-driven material reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient sourcing and brand headquarters concentrate in the United States, with manufacturing clusters in California and Colorado serving Pacific Northwest trail networks. Distribution networks extend into Canada and select European markets where outdoor recreation participation rates support premium positioning.
United States
Trail running participation surges in Colorado and the Pacific Northwest, driving concentrated demand for electrolyte-replenishment formulations. The FDA's updated nutrition labeling requirements for packaged foods compress reformulation timelines for manufacturers. Outdoor specialty retailers in Seattle and Denver prioritize USDA organic certification for shelf placement.
Canada
British Columbia and Alberta sustain elevated outdoor recreation participation rates comparable to the US Pacific Northwest. Health Canada governs nutrition fact panel accuracy and health claim substantiation for all bars sold domestically. Vancouver-based distribution hubs serve cross-border demand from Washington State hikers.
Germany
Alpine climbing communities in Bavaria generate specialized demand for caloric-dense portable nutrition rated for temperature stability. EFSA governs health claim substantiation and novel food ingredient approvals across the European Union. Munich outdoor retailers stock premium organic formulations targeting Leave No Trace practitioners.
Switzerland
Swiss Alpine Club membership drives sustained demand for high-altitude performance nutrition. Swissmedic oversees food supplement classification and border compliance for imported functional bars. Zurich and Geneva outdoor specialty channels emphasize clean-label certification over mass-market branding.
United Kingdom
Trail running participation accelerates in the Lake District and Scottish Highlands, expanding the athlete segment beyond traditional hiking demographics. The Food Standards Agency enforces nutrition labeling and allergen declaration requirements. London-based specialty retailers curate organic and vegan formulations for urban outdoor enthusiasts.
Hiking Functional Energy Bars Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hiking functional energy bars category. Cold-press manufacturing specialists command premium positioning through enzyme-preservation claims, while high-heat processing operators sustain volume leadership through granola bar economies of scale. Three archetypes dominate: organic supply chain integrators, whole-food formulation specialists, and mass-market scale operators. Competitive intensity centers on backward integration into certified ingredient sourcing and compostable packaging certification races.
Within the organic supply chain tier, Clif Bar exemplifies captive sourcing structures that command retail price separation. PROBAR occupies a position among whole-food formulation specialists targeting ultralight backpackers. Nature Valley anchors the mass-market scale tier through high-volume granola bar production. These three players represent the structural segmentation between premium certification-driven positioning and convenience-oriented volume capture.
| Leading Market Players |
|---|
| Clif Bar |
| Nature Valley |
| Luna Bar |
| PROBAR |
| Kate's Real Food |
| TAOS Bakes |
| Bobo's Oat Bars |
| General Mills |
| Chia Charge |
| Others |
Pricing and Supply Chain Analysis
Ninety-day ingredient certification cycles compress procurement calendars for organic protein isolates and tie shelf-stable pricing power directly to backward integration depth. Cold-press manufacturers with captive nut butter supply chains command 15-20% premiums over high-heat operators dependent on spot-market oat futures.
Pricing Analysis
The FDA's updated nutrition labeling requirements dictate the pricing tier structure across protein, nut, granola, and vegan bar categories. Three-tier pricing structure across premium organic, standard clean-label, and economy granola levels separates Clif Bar's certified supply chain from Nature Valley's scale-driven positioning. Cost compression in the protein bar tier is intensifying because whey and plant isolate prices fluctuate with agricultural commodity cycles. Students and campus retail buyers exhibit the highest price sensitivity, while alpine climbers and Leave No Trace practitioners in the Pacific Northwest accept premium positioning for USDA-certified formulations.
Supply Chain Analysis
Sixty-day packaging redesign timelines for ASTM D6400 certification compress supplier qualification windows and force early mover advantages in compostable film partnerships. Raw material sourcing draws from United States organic oat and nut butter clusters, Canadian prairie pea protein operations, and Mexican dried fruit processing facilities. Single-source vulnerability concentrates in California cold-press equipment manufacturing and Oregon compostable film extrusion. Distribution runs through REI's Pacific Northwest hub network, independent gear shops in Colorado, and mass-market retail consolidation into Walmart and Target center-store sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Granola bar substitution from Nature Valley's economies-of-scale positioning threatens margin compression across mid-tier protein formulations, forcing incumbents to defend through certification differentiation rather than price competition.
For Market Incumbents: Compound defensive positioning through backward integration into certified organic ingredient sourcing and accelerated ASTM D6400 packaging certification to preempt California extended producer responsibility compliance deadlines. Clif Bar's captive supply chain demonstrates the capital requirements; mid-tier players must secure BPI-certified film partnerships before 12-18 month redesign windows close. Channel control through REI exclusive placement agreements protects premium tier access against mass-market private label encroachment. For New Entrants and Emerging Players: Anchor in ultralight backpacker white space where caloric density per ounce specifications remain underdeveloped relative to protein bar saturation. The Pacific Northwest and Colorado Front Range offer the most penetrable geography for whole-food cold-press positioning. Direct-to-consumer launch through Strava and AllTrails digital communities bypasses incumbent shelf placement advantages while building Leave No Trace practitioner loyalty before retail expansion. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underperforming outdoor nutrition divisions lacking organic certification infrastructure. Five-to-ten year viability hinges on compostable packaging compliance rather than formulation innovation. The signal to watch is EPA guidance finalization on federal land access permits, which will trigger immediate packaging redesign mandates and separate compliant from non-compliant asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Supply | Captive sourcing of USDA-certified ingredients commands REI shelf placement premiums. |
| Compostable Packaging Certification | ASTM D6400 compliance unlocks Pacific Northwest national park retail access. |
| Cold-Press Manufacturing Scale-Up | Low-temperature dehydration preserves enzyme activity for clean-label differentiation. |
| Ultralight Backpacker Segment Targeting | Caloric density per ounce specifications address unmet demand in current portfolios. |
| Direct-to-Consumer Channel Launch | Digital communities bypass incumbent mass-market distribution advantages. |
Research Methodology
The analysis maps protein bar, nut bar, granola bar, and vegan bar sub-sectors, each validated through brand managers at outdoor specialty retailers, category buyers at REI and Dick's Sporting Goods, supply planners at cold-press manufacturing facilities, and regulatory affairs leads navigating FDA labeling requirements. Primary interview insights combined with secondary validation from USDA organic certification databases, EPA emerging guidance documents, SEC 10-K filings from diversified food conglomerates, and Nielsen retail audit data for the Pacific Northwest and Colorado markets. Bottom-up production capacity modeling and top-down consumer expenditure triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated analytical outputs across the projection horizon. Segmentation dimensions modeled include product type, ingredient certification tier, target consumer activity intensity, and packaging format compliance status. CAGRs derived from historical growth trajectory analysis and forward-looking participation rate projections for trail running and alpine climbing. Industry-specific forecast inputs incorporated whey and plant protein commodity price cycles and state-level extended producer responsibility legislative tracking.
Decision-makers should treat outputs as directional under sustained Pacific Northwest outdoor recreation participation and stable FDA regulatory frameworks; material deviation in protein input costs or accelerated EPA compliance timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Zero-Fat Protein Market