
 Probiotic Drink Market | 2026-2036
Probiotic Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Drink Market Intelligence
Expertise in microbial strain development and fermentation science is rotating toward creating products with specific health outcomes, moving beyond general wellness. Yakult Honsha Co., Ltd. leverages its long-standing research on the Shirota strain to maintain brand loyalty. Danone competes through its broad portfolio of dairy-based options like Activia and Actimel. Meanwhile, PepsiCo positions its Kevita brand to capture the dairy-free and kombucha-adjacent segments.
Probiotic drinks are beverages containing live microorganisms intended to provide health benefits. Efficacy requires delivering a clinically validated dose, measured in Colony Forming Units (CFUs), to support the gut microbiome. While fermented milk products command the largest market share, dairy-free drinks are expanding rapidly among wellness enthusiasts. Supermarkets remain the primary distribution channel, with online retail capturing niche, high-margin sales.
Regulatory frameworks from bodies like the United States' FDA and the European Union's EFSA strictly scrutinize health claims on product labels. In India, the FSSAI sets standards for food safety and labeling, influencing market entry and formulation strategies. Navigating the patchwork of national regulations for strain-specific health claims remains a critical challenge for manufacturers seeking to differentiate their products.
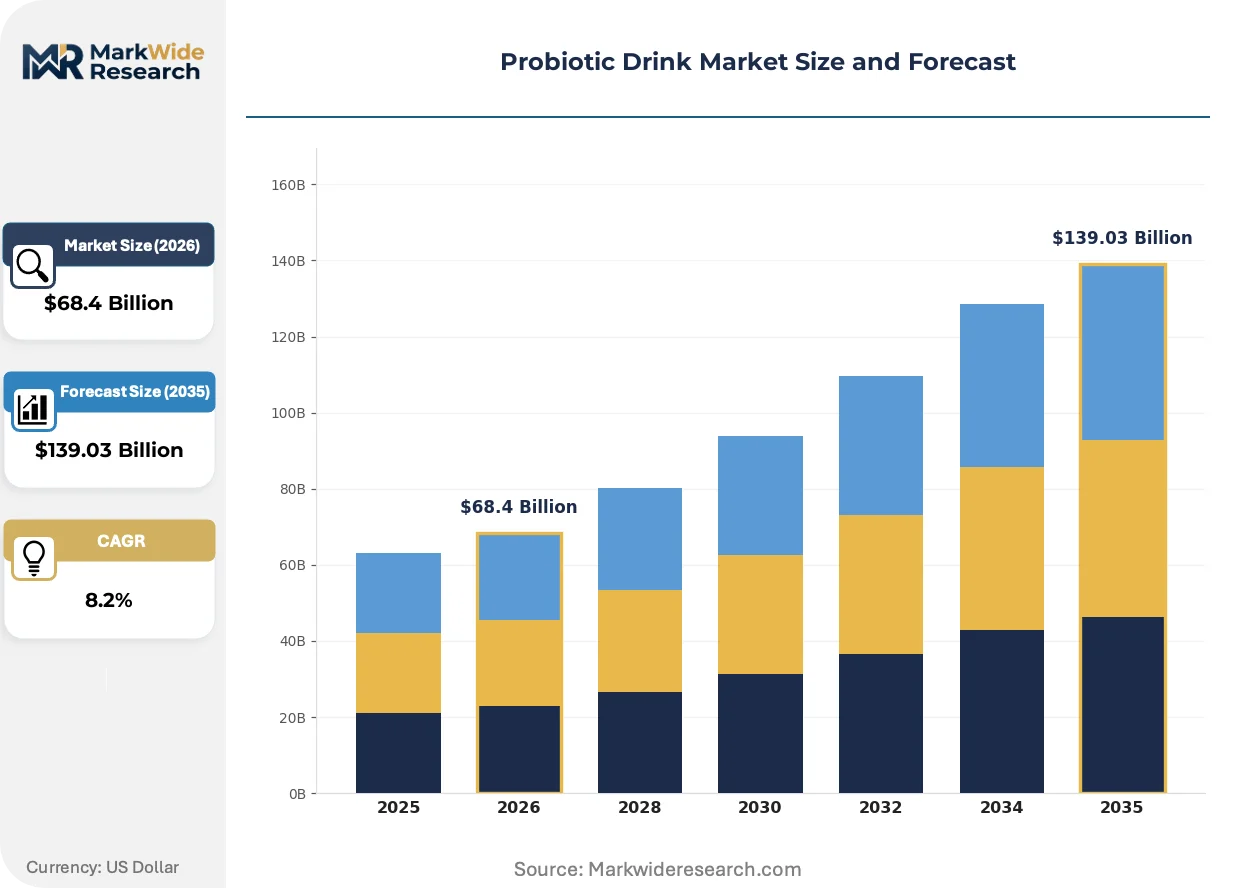
Market Dynamics
The probiotic drink market's central dynamic is the shift from general wellness claims to scientifically validated, outcome-specific health benefits. This transition is driven by advances in microbial strain development and increasing consumer demand for products targeting precise digestive and immune functions.
Growth Catalysts
- Precision Fermentation:This technology enables the cultivation of novel probiotic strains with enhanced stability and targeted functionalities, moving product development beyond generic gut health to address specific conditions.
- Consumer Health Awareness:A rising focus on preventative healthcare and digestive wellness, particularly within the expanding middle-class in countries like India and China, fuels demand for functional beverages.
- Gut-Brain Axis Research:An expanding body of scientific evidence linking gut microbiome health to mental well-being encourages formulators to explore new product categories targeting mood and cognitive function.
Market Restraints
- Strain Viability:Ensuring the required dose of live cultures, measured in Colony Forming Units (CFUs), survives manufacturing, storage, and digestion to confer a health benefit remains a significant technical and cost barrier.
- Regulatory Scrutiny:Health claim substantiation is a major hurdle, with bodies like the United States' FDA and the EU's EFSA enforcing strict evidence requirements that vary significantly by jurisdiction.
- High R&D Investment:Developing and clinically validating proprietary probiotic strains requires substantial upfront capital investment with long timelines and uncertain commercial outcomes, limiting new market entrants.
Strategic Opportunities
- Geographic Expansion:Significant white space exists in markets with nascent functional food sectors, such as in Latin America and Eastern Europe, where consumer awareness of probiotics is growing.
- Category Diversification:There is an opportunity to incorporate clinically-backed probiotic strains into adjacent beverage categories, including functional waters, cold-brew coffees, and plant-based smoothies.
- Personalized Nutrition Models:Direct-to-consumer (DTC) platforms can offer customized probiotic drink subscriptions based on individual health assessments, capturing a high-margin segment of the market.
Industry Challenges
- Complex Compliance Pathways:Navigating the patchwork of international regulations for strain-specific health claims, such as the EFSA's rigorous novel food application process, creates significant delays and costs for manufacturers.
- Cold Chain Dependency:Maintaining an uninterrupted cold chain to preserve the viability of live cultures adds logistical complexity and cost, particularly for distribution in emerging markets with less developed infrastructure.
- Consumer Education Burden:Differentiating products based on scientific evidence requires significant marketing expenditure to educate consumers on concepts like CFUs, specific strains, and clinical validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Drink Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $139.03 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented Milk, Fruit Juice, Carbonated Beverage, Dairy-Free Drink, Nutritional Supplement Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Pharmacies, Health Food Stores Application: Digestive Health, Immune Support, Weight Management, Mental Wellness, Skin Health Customer Type: Children, Adults, Seniors, Athletes, Wellness Enthusiasts |
| Companies Covered | PepsiCo, Fonterra Co-operative Group Limited, Nestlé, Kerry Group, General Mills, Danone, Lifeway Foods, Amul, Yakult Honsha Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Drink Market Strategic Shifts & Innovations
Personalization and scientific validation are transforming the market, pushing it from a category of generally healthy fermented beverages toward one of targeted, functional drinks. This evolution is driven by technological advancements in strain development and a more discerning consumer base demanding proven efficacy.
Targeted Strain Development
Precision fermentation technology enables the design of probiotic strains that produce specific metabolites for targeted health effects. Wellness-focused consumers and advanced food formulators are increasingly adopting these bespoke ingredients for new product lines. This advanced methodology is supplanting the use of generic, less-characterized bacterial cultures in premium and therapeutic-grade probiotic beverages.
Stringent Health Claim Regulation
The European Food Safety Authority (EFSA) continues to enforce a strict framework for approving health claims, requiring extensive, strain-specific clinical data. This regulatory posture compels manufacturers to fund human trials to substantiate any marketing language linking their product to a health benefit. Dairy-based products with long histories of use face particular challenges, pushing R&D toward generating the robust evidence needed for market access.
Rise of Subscription Models
A notable shift in consumer behavior toward personalized wellness solutions is fostering new distribution strategies. Direct-to-consumer subscription services, offering customized probiotic drink regimens, are beginning to disrupt the sales dominance of traditional supermarkets. This trend is most visible in the United States and Western Europe, where consumers demonstrate a higher willingness to pay for tailored health products.
Probiotic Drink Market Segmentation
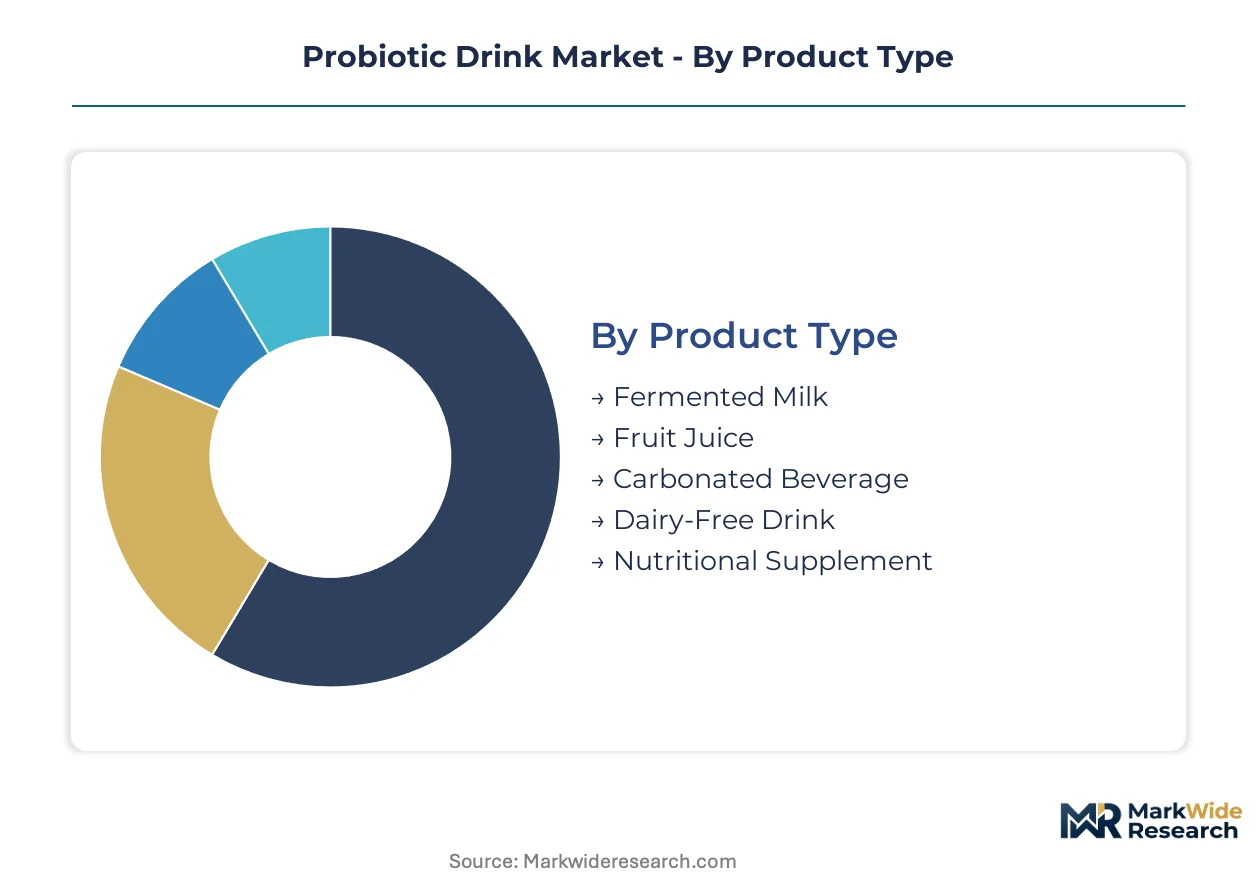
Market segmentation for probiotic drinks reveals the diverse consumer needs and strategic pathways manufacturers employ to capture share. Understanding these distinct segments allows for targeted product development, optimized distribution strategies, and precise marketing efforts.
Product Type:
The channel mix for probiotic drinks varies significantly by product type, influencing retail shelf space and consumer accessibility.
- Fermented Milk:These products typically contain live bacterial cultures like Lactobacillus and Bifidobacterium, often within a dairy base. Demand concentrates in established markets like Japan and Europe, driven by long-standing consumer trust in traditional dairy fermentation.
- Dairy-Free Drink:Formulations include plant-based milks such as almond, oat, or soy, providing alternatives for lactose-intolerant or vegan consumers. Wellness enthusiasts in the United States and Western Europe increasingly seek these options, driven by dietary preferences and perceived health benefits.
- Fruit Juice:These beverages integrate probiotic strains into fruit-based liquids, offering a palatable option for broader consumer appeal.
- Nutritional Supplement:Concentrated probiotic doses are delivered in smaller formats, often targeting specific health outcomes under a supplement classification.
- Carbonated Beverage:These innovative products infuse live cultures into sparkling waters or sodas, appealing to consumers seeking functional refreshment.
By volume, Fermented Milk products lead the market. By growth pace, Dairy-Free Drinks are expanding most quickly.
Distribution Channel:
Customer purchasing habits dictate the primary distribution pathways for probiotic beverages, influencing brand visibility and market penetration.
- Supermarkets:Large retail chains provide extensive shelf space and broad geographic reach, serving as the primary point of purchase for most consumers. Mainstream consumers in urban centers worldwide rely on supermarkets for convenient access to a wide range of probiotic drink brands.
- Online Retailers:E-commerce platforms facilitate direct-to-consumer sales and subscription models, often catering to niche or specialized product offerings. Wellness enthusiasts in North America and Western Europe increasingly use online channels for personalized and specialized probiotic product delivery.
- Convenience Stores:These outlets offer quick grab-and-go options for probiotic drinks, catering to immediate consumption needs.
- Pharmacies:Pharmacies provide a trusted retail environment for probiotic products, often positioning them alongside health and wellness supplements.
- Health Food Stores:Specialized retailers cater to health-conscious consumers seeking organic, natural, or premium probiotic beverage selections.
Supermarkets capture the largest share of overall sales, while online retailers are experiencing significant expansion.
Application:
The specific health outcomes targeted by probiotic drinks drive product formulation and consumer purchasing decisions.
- Digestive Health:Products in this segment contain strains like Lactobacillus and Bifidobacterium, known for supporting gut flora balance and regularity. A broad consumer base globally prioritizes digestive wellness, making this the foundational application for probiotic drinks.
- Immune Support:These formulations often include specific strains like Lactobacillus rhamnosus GG or Bifidobacterium animalis subsp. lactis BB-12, linked to immune modulation. Consumers in the United States and Europe increasingly seek immune-boosting products, particularly following heightened health awareness.
- Mental Wellness:Emerging products explore the gut-brain axis, aiming to influence mood and cognitive function through specific probiotic interventions.
- Weight Management:Some probiotic drinks incorporate strains investigated for their potential role in metabolism and body composition regulation.
- Skin Health:This niche application focuses on the gut-skin axis, with products designed to improve skin conditions through microbiome modulation.
Digestive Health applications remain paramount, while Immune Support is quickly gaining traction among health-conscious consumers.
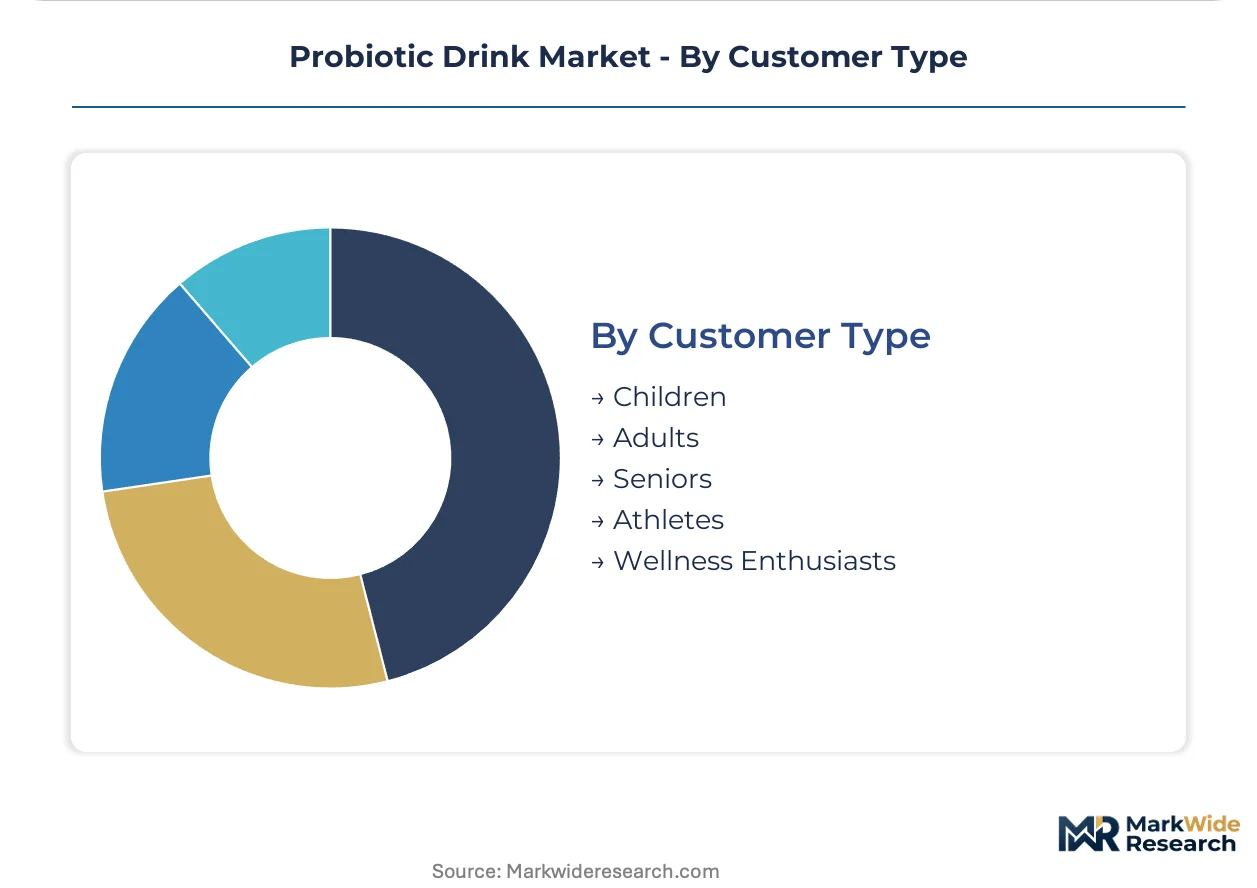
Customer Type:
Product development and marketing strategies often differentiate based on the specific needs and preferences of distinct customer demographics.
- Adults:This segment encompasses a wide range of individuals seeking general wellness, targeted health benefits, or digestive support. The largest consumer demographic across all regions drives significant volume, with a growing focus on preventative health in mature markets.
- Wellness Enthusiasts:These consumers actively seek out premium, scientifically-backed, and often personalized probiotic solutions, including novel strains and delivery methods. High-income individuals in Western economies are early adopters of advanced probiotic products, prioritizing efficacy and natural ingredients.
- Children:Products for children focus on milder formulations and palatable flavors, often targeting digestive comfort and immune development.
- Seniors:This demographic seeks probiotic drinks to address age-related digestive issues and support overall health and vitality.
- Athletes:Athletes consume probiotic beverages for gut health, immune function, and potential performance benefits, often integrated into recovery regimens.
Adults represent the largest consumer base, while Wellness Enthusiasts drive innovation and premium segment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI in India plays a critical role in shaping the probiotic drink market. This regulatory body influences product formulation and market entry strategies for manufacturers. Expanding consumer awareness and an increasing middle-class population drive significant product demand across the country.
India
India's expanding middle-class consumer base drives product demand for digestive wellness. The FSSAI sets food safety and labeling standards, influencing market entry for new formulations. Major food processing hubs like Pune and Bengaluru are seeing increased investment in probiotic beverage production.
United States
Wellness enthusiasts in the United States increasingly seek dairy-free and specialized probiotic options. The FDA scrutinizes health claims on product labels, ensuring consumer protection. California's food tech sector is a hotspot for innovative plant-based probiotic drink development.
Japan
Established consumer trust in traditional dairy fermentation underpins Japan's probiotic drink market. Japan's Ministry of Health, Labour and Welfare (MHLW) oversees food with function claims, including probiotics. Tokyo remains a center for advanced research into novel probiotic strains by companies like Yakult Honsha.
Germany
European consumers prioritize scientifically validated health benefits in their functional beverages. The EFSA's strict health claim framework influences product development for the German market. Bavaria, with its strong dairy industry, is a key region for fermented milk probiotic production.
China
Rising health awareness among China's urban population fuels demand for functional foods. China's National Health Commission (NHC) regulates health food registration, impacting probiotic product approval. Shanghai and Guangzhou are emerging as centers for new probiotic drink launches targeting a discerning consumer base.
Probiotic Drink Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the probiotic drink market. The market structure exhibits a tiered consolidation, with large multinational food and beverage corporations competing alongside specialized probiotic developers. Strategic archetypes include diversified giants leveraging extensive distribution networks for mass appeal and niche innovators focusing on precision fermentation for targeted health outcomes. Dominant competitive moves involve portfolio diversification into dairy-free options and strategic partnerships for scientific validation and market access.
Scale-driven global food and beverage conglomerates like PepsiCo and Danone occupy a significant position, leveraging their established brand portfolios and extensive distribution channels. Yakult Honsha Co., Ltd. represents a specialized archetype, anchoring its market presence on long-standing research into proprietary probiotic strains and maintaining strong brand loyalty. These companies exemplify the diverse approaches to market penetration and brand loyalty in the functional beverage space, from broad appeal to targeted scientific efficacy.
| Leading Market Players |
|---|
| PepsiCo |
| Fonterra Co-operative Group Limited |
| Nestlé |
| Kerry Group |
| General Mills |
| Danone |
| Lifeway Foods |
| Amul |
| Yakult Honsha Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The European Food Safety Authority's (EFSA) stringent health claim framework gates supply qualification for probiotic drinks, simultaneously enabling premium price differentiation for clinically validated products. This regulatory scrutiny ensures product integrity and influences market entry strategies.
Pricing Analysis
Probiotic drink prices exhibit a notable geographic spread, with premium offerings in Western Europe and the United States commanding higher values. Pricing stratifies across premium, standard, and economy tiers, driven by factors like clinical validation of specific strains and brand recognition. Pricing pressure stems from the proliferation of generic gut health products, particularly in the standard segment. Wellness enthusiasts demonstrate lower price sensitivity for specialized formulations, while mainstream consumers prioritize affordability.
Supply Chain Analysis
Maintaining stable inventory levels for probiotic drinks presents challenges due to the perishable nature of live cultures and cold chain requirements. Production concentrates in established dairy regions such as Bavaria, Germany, and Japan, with India also emerging as a significant source. The supply chain relies heavily on specialized microbial strains, dairy or plant-based milks, and advanced packaging to ensure viability. Cold chain dependency introduces significant logistical complexity and cost, particularly for distribution in less developed markets, where supermarkets serve as the primary channel alongside niche online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The probiotic drink market is experiencing a cyclical recovery, driven by renewed consumer focus on preventative health and digestive wellness. This shift encourages investment in scientifically validated formulations and targeted product development.
For Market Incumbents: Fortify market positions by investing heavily in precision fermentation technology to develop proprietary, clinically validated strains. Expand dairy-free portfolios to mitigate the competitive threat from specialized wellness brands and capture broader consumer segments. Leverage R&D into the gut-brain axis to differentiate products beyond general digestive health, addressing increasing regulatory scrutiny on broad health claims.
For New Entrants and Emerging Players: Expedited FSSAI approval pathways in India offer a fast-track for novel probiotic formulations targeting the expanding middle-class. Target underpenetrated geographic white spaces in Latin America and Eastern Europe with culturally relevant product formats. Focus on personalized nutrition models through direct-to-consumer subscription services, appealing to wellness enthusiasts seeking tailored health solutions in niche beverage categories like functional waters.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the precision fermentation sub-segment, indicating higher barriers to entry but also stronger defensibility. Long-term viability hinges on acquiring companies with robust intellectual property in novel probiotic strain development and strong regulatory compliance records. Target niche innovators demonstrating proven efficacy through clinical trials. The signal to watch is a sustained increase in venture capital funding for biotech firms specializing in microbiome research and targeted strain development.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Investment | Enables development of stable, targeted probiotic strains for specific health outcomes. |
| Dairy-Free Portfolio Expansion | Captures wellness enthusiasts and consumers with dietary restrictions, broadening market reach. |
| Clinical Trial Sponsorship | Provides scientific validation for health claims, securing regulatory approval and consumer trust. |
| Direct-to-Consumer Platform Launch | Establishes personalized subscription models, fostering brand loyalty and higher-margin sales. |
| Geographic Market Entry (India/LatAm) | Accesses expanding middle-class populations with rising health awareness in underserved regions. |
Research Approach
Initial hypotheses were tested against primary input from microbiome scientists, food formulators, regulatory affairs specialists, and retail category managers, and refined. This primary research was validated through extensive secondary data analysis, including regulatory body publications from EFSA and FSSAI, academic journals on gut health, and company annual reports. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and comprehensive market understanding.
Variance decomposition identified key drivers impacting growth across the probiotic drink market over the projection horizon. The analytical framework modeled dimensions such as product type, distribution channel, application, customer type, and regional regulatory environment. Compound annual growth rates were derived from historical trends, demand projections, and technology adoption curves. Consumer health awareness indices and precision fermentation advancements served as critical forecast inputs.
Decision-makers should treat outputs as directional under base assumptions regarding current regulatory frameworks and consumer health trends; material deviation would warrant model refresh. Unforeseen shifts in regulatory policy or major scientific breakthroughs in strain development represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Soluble Beta Glucan Market