
 Emergency Hangover Product Market | 2026-2036
Emergency Hangover Product Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Hangover Product Market Insights
Subscription-based replenishment models is consolidating how consumers access emergency hangover products, shifting one-time purchases into recurring revenue streams. Rally Labs LLC leverages direct-to-consumer automation to sustain repeat engagement. Bayer AG anchors pharmacy shelf presence through established OTC distribution networks. Cheers Health differentiates via bundled lifestyle branding that extends beyond single-use recovery occasions.
Emergency hangover products comprise formulated consumables designed to mitigate alcohol-induced dehydration, electrolyte depletion, and oxidative stress through rapid-delivery mechanisms such as effervescent tablets or isotonic drink mixes containing precise ratios of sodium, potassium, and B-complex vitamins. Their commercial purpose centers on reducing symptom severity within a compressed post-consumption window, typically targeting restoration within thirty to sixty minutes. Drink mix formats command the dominant volume position due to palatability and hydration dual-functionality, while tablet segments attract traveler and athlete subgroups prioritizing portability. Electrolyte-dominant ingredient compositions capture the widest margin pools, whereas amino acid formulations occupy a premium niche with higher per-unit pricing.
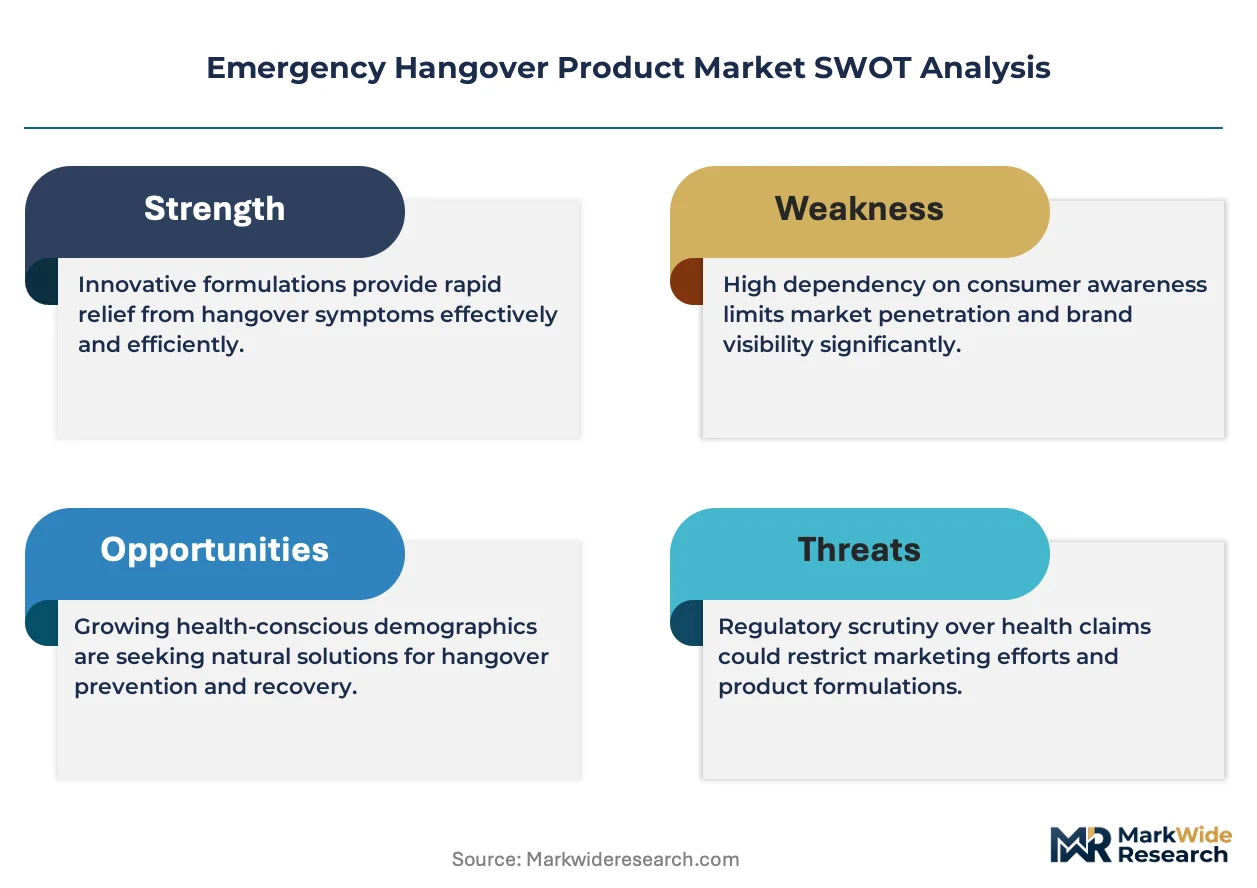
FDA oversees dietary supplement labeling and adverse event reporting under DSHEA, while FTC monitors advertising claims for hangover remediation efficacy, collectively elevating compliance costs for market entrants. State-level alcohol beverage control boards in California, New York, and Texas increasingly scrutinize co-marketing between recovery products and licensed drinking establishments. Stakeholders must monitor evolving substantiation requirements for structure-function claims as regulatory thresholds tighten.
Market Dynamics
Subscription-based replenishment models are consolidating consumer access patterns, compressing one-time purchases into recurring revenue streams that reshape manufacturer cash flow structures and inventory planning horizons.
Growth Catalysts
- DSHEA substantiation requirements:FDA dietary supplement labeling mandates are elevating ingredient disclosure standards, forcing formulation transparency that builds consumer trust and category legitimacy.
- Metropolitan nightlife corridors:Dense urban entertainment districts in the United States concentrate demand through on-premise placement at licensed drinking establishments.
- Effervescent rapid-delivery mechanisms:Bioavailability-optimized tablet formats accelerate electrolyte absorption kinetics, shortening symptom relief windows and driving repeat purchase intent.
Market Restraints
- FTC advertising scrutiny:The Federal Trade Commission's monitoring of hangover remediation efficacy claims elevates legal review costs and slows marketing velocity for new entrants.
- Ingredient supply concentration:Pharmaceutical-grade B-complex vitamin sourcing clusters among three dominant suppliers, creating input vulnerability during demand spikes.
- Functional beverage substitution:Mainstream sports hydration brands with electrolyte portfolios capture price-sensitive consumers seeking generic recovery solutions.
Strategic Opportunities
- Travel retail channels:Airport duty-free and hotel minibar placement targets business traveler subsegments prioritizing portable tablet formats over liquid alternatives.
- State alcohol beverage control co-marketing frameworks:California, New York, and Texas regulatory boards are piloting approved partnership protocols between recovery products and licensed venues.
- Amino acid premium tier expansion:N-acetylcysteine and dihydromyricetin formulations command higher per-unit margins while serving oxidative stress mitigation demand.
Industry Challenges
- GMP certification timelines:FDA current Good Manufacturing Practice audits for new production facilities extend 14-18 months, delaying market entry for capitalized challengers.
- Adverse event reporting infrastructure:Mandatory MedWatch compliance requires pharmacovigilance systems that strain mid-tier manufacturer operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Hangover Product Market |
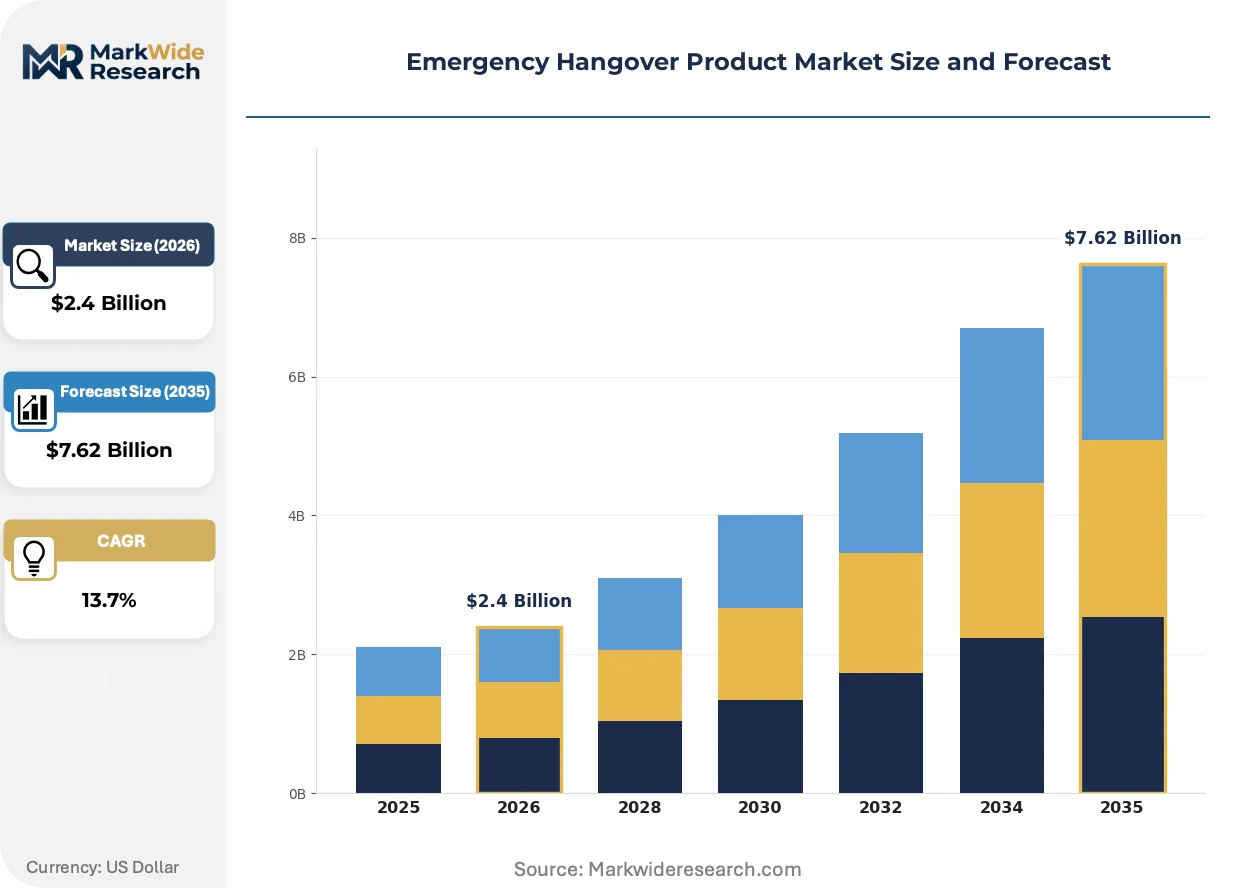
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drink Mix, Tablet, Powder, Herbal Supplement Ingredient Type: Electrolytes, Vitamins, Amino Acids, Herbs Packaging Type: Single Serve, Bulk, Sachet, Bottle Target Audience: Party-Goers, Athletes, Travelers, Health-Conscious Consumers |
| Companies Covered | Rally Labs LLC (Blowfish), Liquid I.V., Inc., Abbott, Bayer AG, Cheers Health, More Labs, The Himalaya Drug Company, Flyby, Drinkwel, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Hangover Product Market Trends and Innovations
Formulation science and distribution architecture are undergoing parallel transformation, with bioavailability engineering and channel disintermediation compressing traditional go-to-market timelines.
Microencapsulation technology is decentralizing nutrient delivery architecture by embedding electrolytes and botanical extracts in lipid-shell matrices that bypass gastric degradation. Hospitality procurement teams at casino resorts and nightclub groups are adopting these formats for back-bar placement. This decentralization enables on-premise manufacturing partnerships that shorten supply chains from centralized co-packing facilities to venue-specific production pods.
California's SB 389 alcohol delivery regulations are tightening co-marketing compliance frameworks between hangover products and licensed drinking establishments. The state's Department of Alcoholic Beverage Control now requires explicit separation of promotional materials, forcing brands to redesign point-of-sale displays. Hospitality groups operating across Los Angeles, San Francisco, and San Diego metropolitan corridors are consolidating vendor relationships to simplify multi-jurisdiction compliance.
B2B bulk purchasing contracts are displacing individual consumer transactions as the dominant revenue architecture. Nightlife venue operators in Miami, Las Vegas, and Austin are negotiating annual supply agreements that bundle recovery products with beverage alcohol procurement. This concentration shift is most visible in the Sun Belt metropolitan corridor, where hospitality REITs centralize purchasing decisions across portfolio properties.
Emergency Hangover Product Market Segmentation
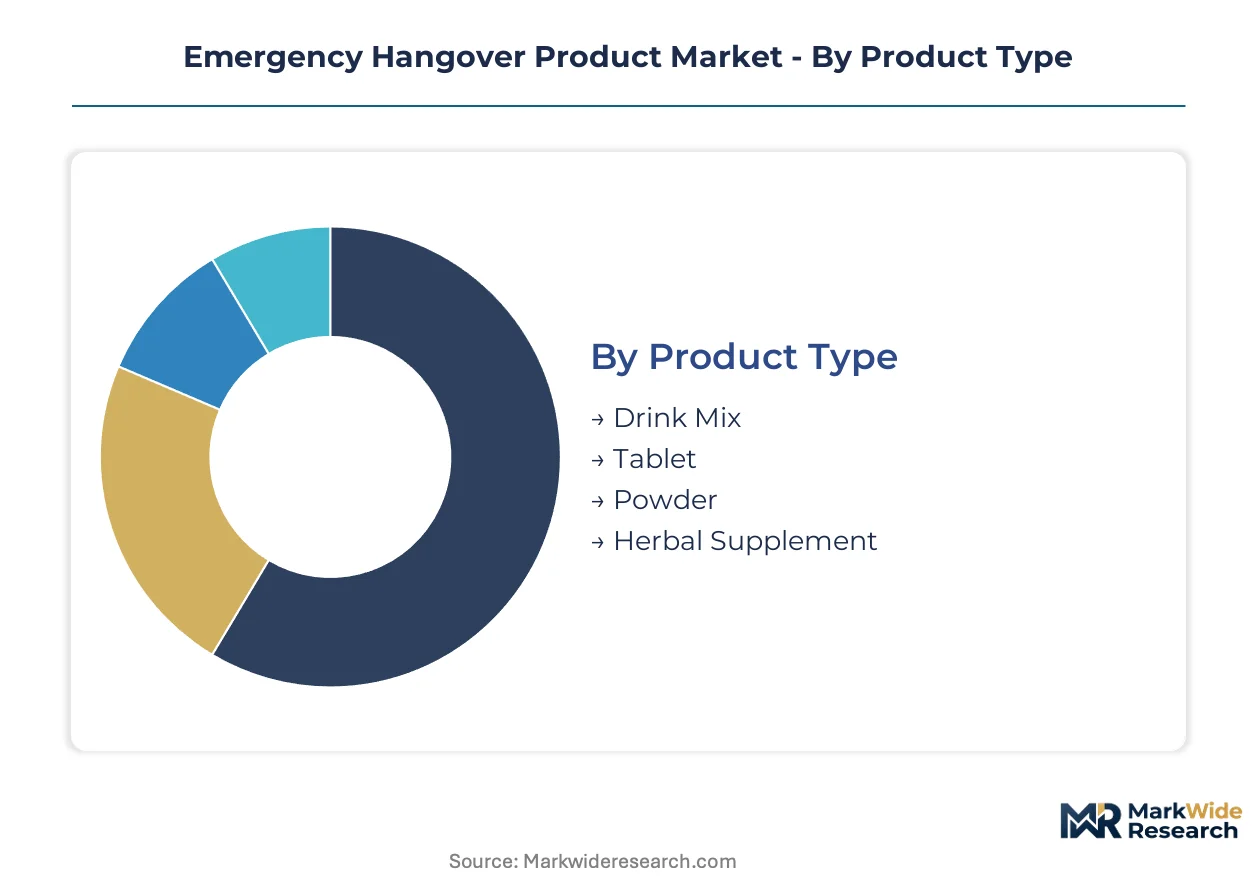
Segmentation in emergency hangover products reveals how formulation chemistry, delivery mechanics, and consumption context shape procurement decisions across hospitality, retail, and direct-to-consumer channels. Manufacturers optimize production lines around specific format-performance combinations rather than pursuing universal SKUs.
Product Type:
Upgrade cycles in this category accelerate when bioavailability improvements or flavor engineering reset consumer expectations for speed of relief.
- Drink Mix:Isotonic powder formulations dissolve in water to deliver simultaneous hydration and nutrient loading through rapid gastric emptying. Demand concentrates in United States metropolitan nightlife corridors where licensed venues stock back-bar dispensers for immediate guest service. Dual-functionality as palatable beverage and therapeutic delivery mechanism sustains volume leadership despite higher shipping weights.
- Tablet:Effervescent and swallowable formats embed precise electrolyte ratios in compressed matrices optimized for sublingual or enteric absorption. Athletes and business travelers in airport lounges and hotel minibars prioritize pocket-sized portability over hydration volume, creating premium pricing tolerance for rapid-delivery engineering.
- Powder:Loose granular formulations offer bulk preparation flexibility for hospitality batch service or home mixing protocols. Casino resort procurement teams in Las Vegas and Atlantic City specify multi-dose canisters for VIP suite amenities.
- Herbal Supplement:Botanical extract concentrates targeting oxidative stress pathways through dihydromyricetin and milk thistle compounds. Niche positioning in natural products retail channels attracts supplement-category shoppers seeking plant-derived alternatives.
Drink Mix sits at the top of the volume ranking, with Tablet climbing the fastest.
Ingredient Type:
Cost tier separation in raw material sourcing directly determines margin architecture and regulatory compliance burden across formulation strategies.
- Electrolytes:Sodium-potassium-magnesium blends in pharmaceutical-grade ratios address dehydration-driven symptomology through osmotic gradient restoration. Hospitality groups in Miami and Austin negotiate annual supply contracts bundling electrolyte-dominant SKUs with beverage alcohol procurement, capturing widest margin pools through volume concentration.
- Vitamins:B-complex and vitamin C formulations targeting metabolic cofactor depletion from alcohol metabolism. Pharmacy shelf placement through established OTC networks in the United States leverages familiar nutrient positioning for consumer trust transfer.
- Amino Acids:N-acetylcysteine and L-cysteine precursors for glutathione synthesis support oxidative stress mitigation at premium per-unit pricing. Wellness-focused subsegments in California metropolitan markets absorb higher ingredient costs for perceived efficacy differentiation.
- Herbs:Standardized botanical extracts including prickly pear and ginseng compounds positioned for traditional medicine alignment. Natural products retailers in Colorado and Oregon metropolitan clusters stock these formulations for category adjacency with broader supplement portfolios.
Electrolytes command the dominant revenue share, with Amino Acids gaining share fastest.
Packaging Type:
Application context dictates format selection, with consumption setting determining portability requirements, portion control needs, and brand visibility opportunities.
- Single Serve:Pre-portioned stick packs and vials eliminate measurement error for immediate consumption scenarios. Nightclub back-bar placement in New York and Los Angeles requires tamper-evident single units for regulatory compliance with alcohol beverage control board protocols.
- Bulk:Multi-dose canisters and jars serving hospitality procurement for venue-controlled dispensing or residential heavy-use households. Sun Belt casino resort operators centralize purchasing decisions across portfolio properties through annual bulk agreements.
- Sachet:Flat foil pouches optimizing shipping cube efficiency for e-commerce replenishment and travel retail. Airport duty-free operators in Dallas and Atlanta hubs specify sachet formats for passenger carry-on convenience.
- Bottle:Rigid containers for ready-to-drink liquid formulations requiring no preparation step. Convenience store distribution in Texas and Florida metropolitan corridors targets impulse purchase occasions.
Single Serve leads by unit volume, with Sachet expanding most quickly in travel retail channels.
Target Audience:
Customer type segmentation aligns product development with distinct usage rituals, recovery timelines, and willingness-to-pay thresholds across demographic and psychographic clusters.
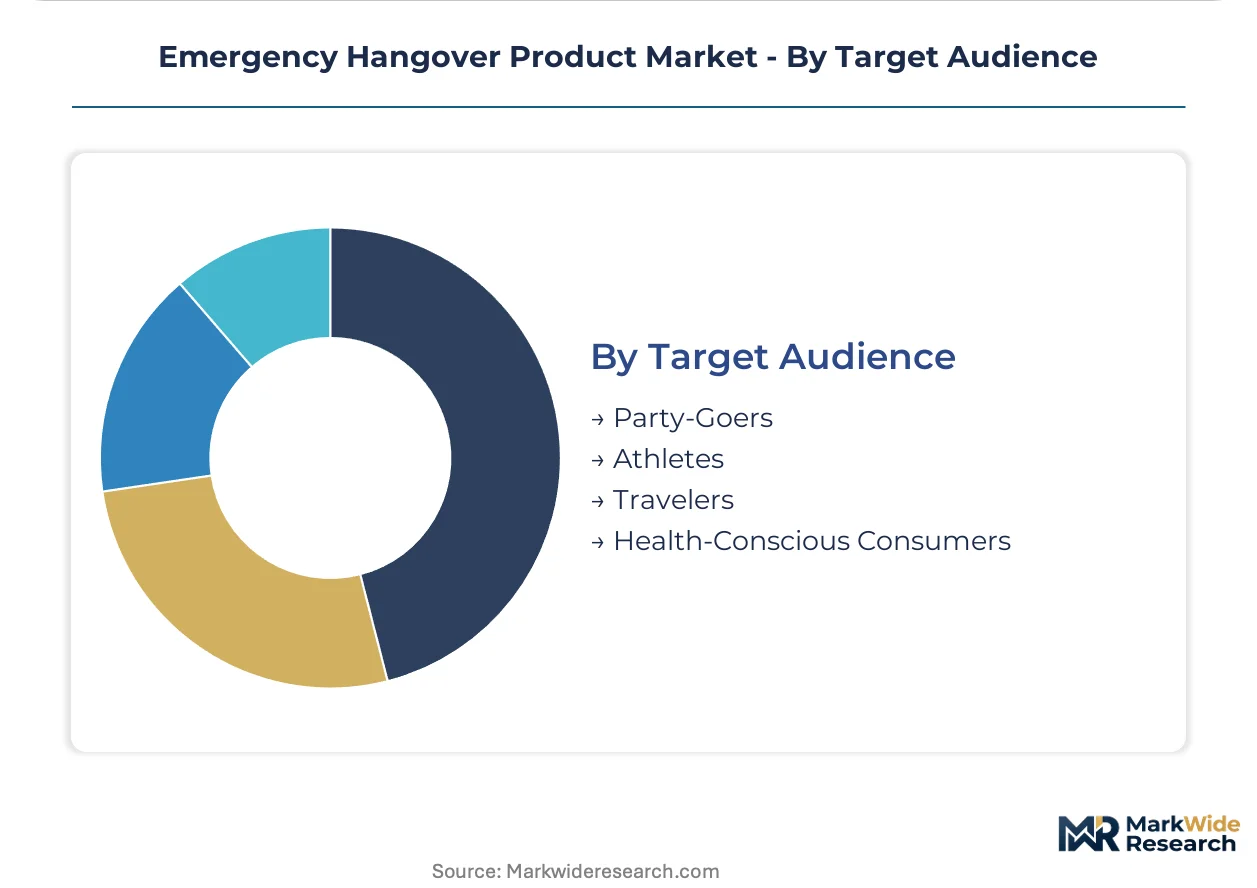
- Party-Goers:Young adult consumers in dense urban entertainment districts seeking rapid symptom suppression before next-day obligations. Subscription automation from direct-to-consumer platforms captures recurring engagement through replenishment timing aligned with weekend consumption patterns.
- Athletes:Fitness-oriented users treating alcohol recovery as extension of training regimen discipline. Sports hydration brand substitution threat concentrates in this segment, with electrolyte portfolio overlap from mainstream functional beverages.
- Travelers:Business and leisure passengers requiring portable formats for transit recovery in airports, hotels, and ride-share contexts. Tablet preference dominates for TSA compliance and minibar placement in Marriott and Hilton portfolio properties.
- Health-Conscious Consumers:Wellness-category shoppers evaluating ingredient transparency and clean-label positioning as purchase prerequisites. FDA dietary supplement labeling mandates under DSHEA substantiation requirements resonate with this segment's disclosure expectations.
Party-Goers generate the highest absolute transaction volume, with Health-Conscious Consumers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates emergency hangover product demand through metropolitan nightlife corridors, while Germany's pharmacy-centric distribution channels favor tablet formats with stricter efficacy documentation.
United States
California, New York, and Texas dominate procurement through licensed venue co-marketing pilots. The FDA's DSHEA substantiation requirements elevate ingredient disclosure standards for dietary supplement labeling. Miami, Las Vegas, and Austin hospitality groups negotiate annual supply agreements bundling recovery products with beverage alcohol procurement.
Germany
Pharmacy shelf placement through established OTC networks concentrates demand for effervescent tablet formats. The country's national pharmaceutical regulator enforces strict adverse event reporting through pharmacovigilance systems. Berlin and Munich metropolitan clusters show preference for B-complex vitamin formulations targeting metabolic cofactor depletion.
United Kingdom
Subscription-based direct-to-consumer platforms capture recurring engagement from young adult urban consumers. The Advertising Standards Authority scrutinizes hangover remediation efficacy claims alongside general consumer protection frameworks. London's dense entertainment districts drive on-premise placement at licensed drinking establishments.
Japan
Business traveler subsegments in airport lounges and hotel minibars prioritize portable tablet formats for transit recovery. The country's national pharmaceutical regulator oversees dietary supplement labeling with emphasis on structure-function claim substantiation. Tokyo and Osaka metropolitan corridors concentrate demand through convenience store distribution networks.
Australia
Wellness-focused consumers evaluate ingredient transparency and clean-label positioning as purchase prerequisites. The Therapeutic Goods Administration monitors advertising claims for hangover remediation efficacy. Sydney and Melbourne natural products retail channels stock herbal supplement formulations for category adjacency with broader supplement portfolios.
Emergency Hangover Product Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer platforms capturing recurring revenue streams while pharmacy networks sustain volume through established OTC distribution. The vendor base clusters around three strategic archetypes: lifestyle-brand bundlers, rapid-delivery formulation specialists, and hospitality procurement aggregators. Dominant competitive moves include backward integration into pharmaceutical-grade ingredient sourcing and strategic partnerships with casino resort operators for back-bar placement exclusivity.
Within the lifestyle-brand tier, Cheers Health and Flyby exemplify bundled positioning that extends beyond single-use recovery occasions. Bayer AG anchors pharmacy shelf presence through established OTC distribution networks. Rally Labs LLC occupies a position within the direct-to-consumer automation segment, sustaining repeat engagement through subscription-based replenishment models.
| Leading Market Players |
|---|
| Rally Labs LLC (Blowfish) |
| Liquid I.V., Inc. |
| Abbott |
| Bayer AG |
| Cheers Health |
| More Labs |
| The Himalaya Drug Company |
| Flyby |
| Drinkwel, LLC |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade formulation chemists concentrated in New Jersey and North Carolina command wage premiums that compress margin spreads between premium amino acid tiers and standard electrolyte formulations. Labor-cost differentials between these specialized hubs and generic supplement manufacturing zones in Utah and Florida directly shape three-tier pricing stratification across the category.
Pricing Analysis
Capacity additions in Florida and Texas are reshaping price floors for electrolyte-dominant SKUs as new GMP-certified facilities expand batch production throughput. Pricing stratifies across premium, standard, and economy tiers based on bioavailability engineering complexity and FDA substantiation documentation depth. Cost compression in the standard tier is intensifying because hospitality procurement aggregators negotiate annual volume commitments that strip out brand premiums. Party-goers through direct-to-consumer channels show highest price sensitivity, while casino resort operators absorbing bundled amenity costs demonstrate lowest sensitivity.
Supply Chain Analysis
FDA current Good Manufacturing Practice certification serves as the primary gating mechanism for ingredient suppliers seeking entry into branded formulation networks. Pharmaceutical-grade B-complex vitamin sourcing draws from India, China, and Switzerland, with N-acetylcysteine precursors anchored in Japanese and South Korean chemical synthesis clusters. Single-source vulnerability concentrates in pharmaceutical-grade electrolyte mineral refining, where three dominant suppliers control osmotic-grade sodium and potassium processing. Distribution runs through centralized co-packing facilities in Nevada and New Jersey before final-mile deployment to hospitality venues and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA substantiation requirements in the United States create compliance cost barriers that shelter domestic incumbents from low-cost Asian private-label competition.
For Market Incumbents: Acquire microencapsulation technology patents to secure bioavailability differentiation against generic electrolyte substitutes. Consolidate backward integration into pharmaceutical-grade B-complex vitamin sourcing to mitigate input cost volatility from Indian and Chinese supplier concentration. Channel control through exclusive casino resort back-bar placement agreements locks out challenger brands from highest-margin hospitality procurement decisions.
For New Entrants and Emerging Players: Begin with travel retail white-space in airport duty-free channels where tablet format portability commands premium pricing tolerance absent from saturated direct-to-consumer subscription markets. Target business traveler subsegments in Dallas and Atlanta hub corridors with TSA-compliant sachet formats. Go-to-market execution should leverage hotel minibar placement partnerships bypassing established pharmacy shelf dominance.
For Investors and Strategic Acquirers: Hospitality REITs are the most active acquirer in this space, consolidating vendor relationships across Sun Belt portfolio properties to capture procurement scale efficiencies. Long-term viability hinges on regulatory moat durability as FDA and FTC substantiation thresholds escalate compliance costs beyond mid-tier manufacturer operational bandwidth. Watch for California Department of Alcoholic Beverage Control co-marketing framework expansion as signal for on-premise channel legalization tailwinds.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Lipid-shell matrices bypass gastric degradation, accelerating electrolyte absorption kinetics for hospitality back-bar placement. |
| GMP Certification Investment | FDA audit compliance extends 14-18 month timelines, creating defensive barriers against undercapitalized challengers. |
| Hospitality Procurement Aggregation | Annual supply agreements bundling recovery products with beverage alcohol capture margin concentration in Miami and Las Vegas. |
| Travel Retail Channel Expansion | Airport duty-free and hotel minibar placement targets business travelers prioritizing portable tablet formats. |
| Subscription Platform Automation | Direct-to-consumer replenishment timing aligned with weekend consumption patterns sustains recurring revenue streams. |
Research Methodology
Direct dialogue with formulation chemists, hospitality procurement directors, regulatory affairs specialists at dietary supplement manufacturers, and pharmacy category managers grounded qualitative insights. Secondary validation drew from FDA MedWatch adverse event databases, FTC advertising enforcement actions, state alcohol beverage control board filings, and hospitality REIT procurement disclosures. Bottom-up demand modeling triangulated against top-down market sizing from trade customs data and ingredient supplier shipment records.
Bottom-up unit economics across product type, ingredient composition, packaging format, and target audience segments fed into value aggregation over the projection horizon. Modeled dimensions included delivery mechanism bioavailability tier, electrolyte versus amino acid formulation chemistry, single-serve versus bulk packaging economics, and metropolitan nightlife corridor density indices. CAGRs derived from segment-level growth rate distributions weighted by hospitality procurement contract visibility and direct-to-consumer subscription retention curves.
Several conditions sit outside the modeled scope, including novel pharmaceutical interventions receiving FDA drug approval, federal scheduling changes affecting dihydromyricetin regulatory status, and hospitality sector demand destruction from alcohol consumption pattern shifts. Deviation in California SB 389 co-marketing framework adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Natural Functional Food Market