
 Protein Water Market | 2026-2036
Protein Water Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Water Market Outlook
The split between premium functional positioning and commodity hydration is hardening in the protein water category. Protein2o Inc. leverages its established RTD infrastructure to dominate mainstream retail placement, while Agropur Inc. anchors its competitive stance through dairy-protein supply chain control. Muscle Nation differentiates via fitness-community brand equity and direct-to-consumer channel intensity.
Protein water is a ready-to-drink or reconstituted beverage containing isolated or hydrolyzed protein, typically delivering 15–20 grams per serving with sub-100-calorie profiles, formulated for post-workout recovery and convenient protein supplementation. Whey-based RTD formats occupy the largest volume share due to superior bioavailability and established taste masking, while pea protein concentrates are gaining structural momentum as vegan formulation capabilities improve and allergen-free positioning commands shelf-space premiums. Distribution through gyms and health stores captures the highest margin pools by attaching subscription models to membership ecosystems.
The FDA oversees protein content claims and GRAS status for novel protein isolates, while EFSA governs health claim substantiation across European markets, directly shaping permissible marketing language and reformulation costs. ISO 22000 and HACCP frameworks govern manufacturing consistency, with audit stringency rising as private-label entrants proliferate. Stakeholders must monitor evolving protein-source sustainability certifications and anticipate how clean-label thresholds will redefine acceptable additive portfolios.
Market Dynamics
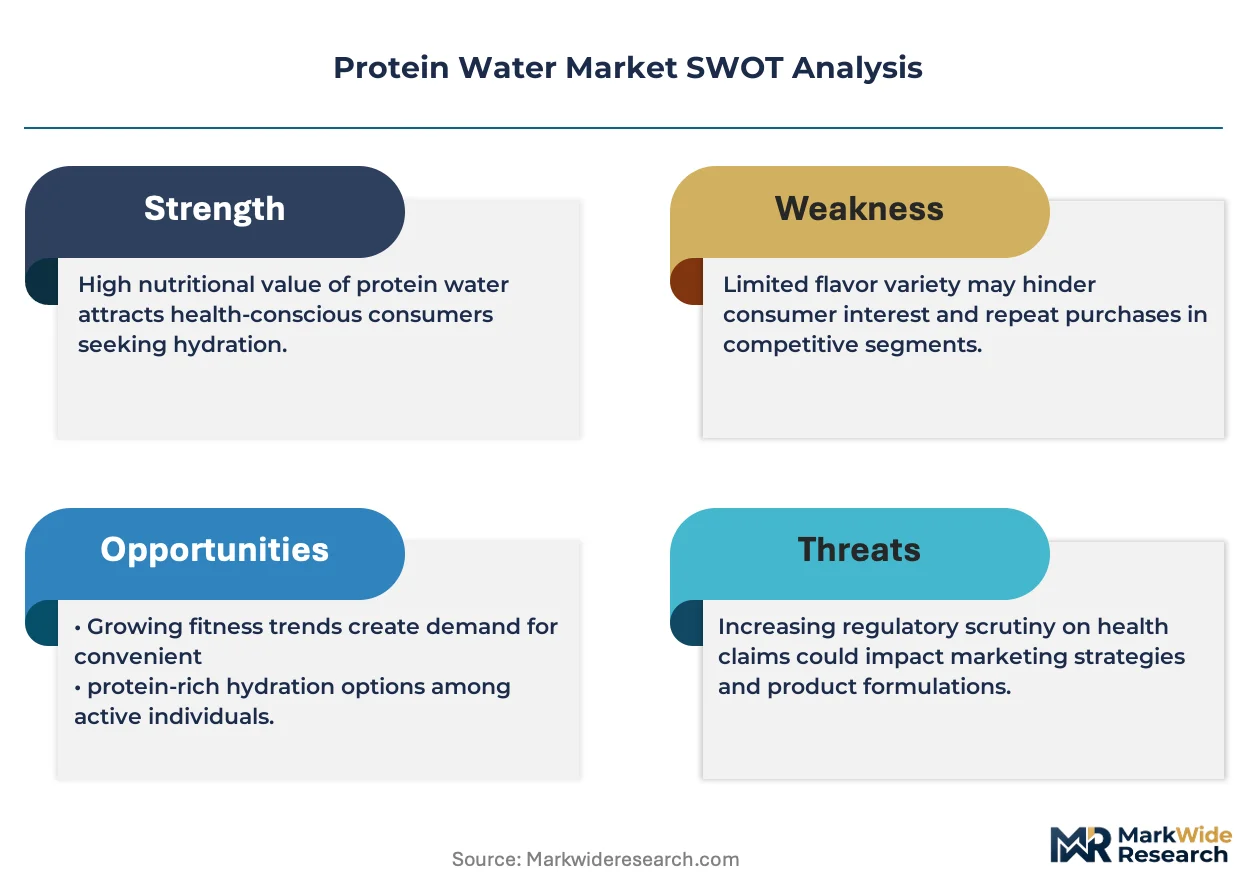
Clean-label formulation mandates from the FDA and EFSA are compressing acceptable additive portfolios while fitness-community demand concentrates around transparent sourcing claims, forcing reformulation cycles that favor vertically integrated protein suppliers.
Growth Catalysts
- EFSA Health Claim Substantiation:Permissible marketing language for recovery benefits is expanding as clinical evidence standards mature, enabling premium positioning in European retail channels.
- Whey Protein Bioavailability:Superior leucine kinetics versus plant alternatives sustain post-workout recovery demand among performance-oriented consumers.
- Gym Subscription Integration:Health club membership ecosystems attach recurring beverage purchases to fitness programming, locking in predictable offtake volumes.
Market Restraints
- Dairy Protein Supply Concentration:Whey isolate production clusters in Upper Midwest dairy processing corridors, creating geographic vulnerability to feed cost volatility and climate disruption.
- Pea Protein Taste Masking Costs:Bitter off-note remediation requires expensive encapsulation technologies that compress margins on vegan-positioned SKUs.
- FDA GRAS Timeline Friction:Novel protein isolate approvals extend 18-24 months, delaying product launches for emerging sources like duckweed or microbial fermentation.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Fitness influencers bypass traditional retail slotting fees through owned digital channels, capturing lifetime value data unavailable to brick-and-mortar competitors.
- ISO 22000 Certification Arbitrage:Private-label entrants lacking manufacturing audit depth create acquisition targets for quality-forward brands seeking capacity expansion.
- Collagen-Protein Hybrid Formulations:Converging beauty-from-within and sports recovery positioning opens shelf space in cosmetics retail adjacent to traditional nutrition channels.
Industry Challenges
- Flavor Chemist Talent Scarcity:Protein hydrolysate bitterness suppression requires specialized sensory science expertise concentrated at legacy beverage conglomerates.
- Cold Chain Capex Intensity:RTD preservation without chemical stabilizers demands refrigerated distribution infrastructure that strains working capital for regional entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Water Market |
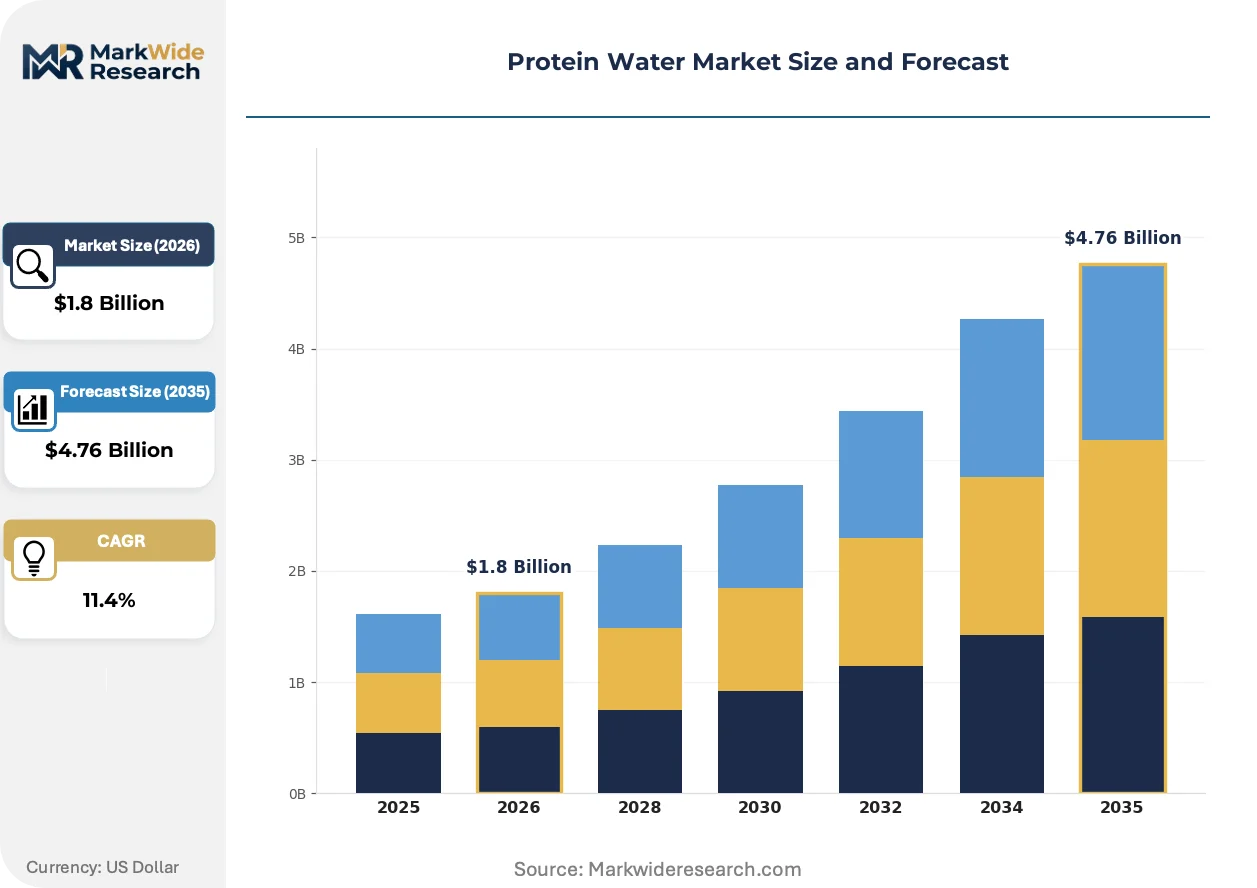
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RTD, Powder, Concentrate, Flavored Ingredient Source: Whey, Casein, Pea, Soy Distribution Channel: Online, Supermarkets, Health Stores, Gyms Target Consumer: Athletes, Fitness Enthusiasts, Health-Conscious Individuals, Busy Professionals |
| Companies Covered | Protein2o Inc., Aquatein, Muscle Nation, Musashi Nutrition, Protein Water Co., NZ Muscle, Nexus Sports Nutrition, BODIE*Z, Agropur Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Water Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel transformation as protein water migrates from niche sports nutrition toward mainstream functional beverage shelves.
Microencapsulation technology for plant protein isolates is modularizing production workflows. Vegan formulation specialists adopt lipid-shell encapsulation systems at accelerating pace to mask pea and rice protein off-notes. This modularizing capability collapses the taste gap with dairy alternatives, compressing the premium pricing window for whey-dominant portfolios.
EFSA's evolving position on sustainability-linked health claims is tightening substantiation requirements for environmental marketing. Manufacturers must now document supply chain carbon intensity to support climate-related product positioning. European brands with ISO 14001-certified operations gain preferential retail placement as ESG-driven assortment decisions harden across supermarket buyers.
Recovery beverage procurement is fragmenting across occasion-specific occasions rather than consolidating around single daily consumption. Gym-goers now segment pre-workout, intra-workout, and post-workout hydration into distinct purchase decisions. This behavioral shift is most visible in United States metropolitan fitness studio density, where refrigerated grab-and-go cases stock occasion-optimized SKUs with differentiated electrolyte and caffeine profiles.
Protein Water Market Segmentation
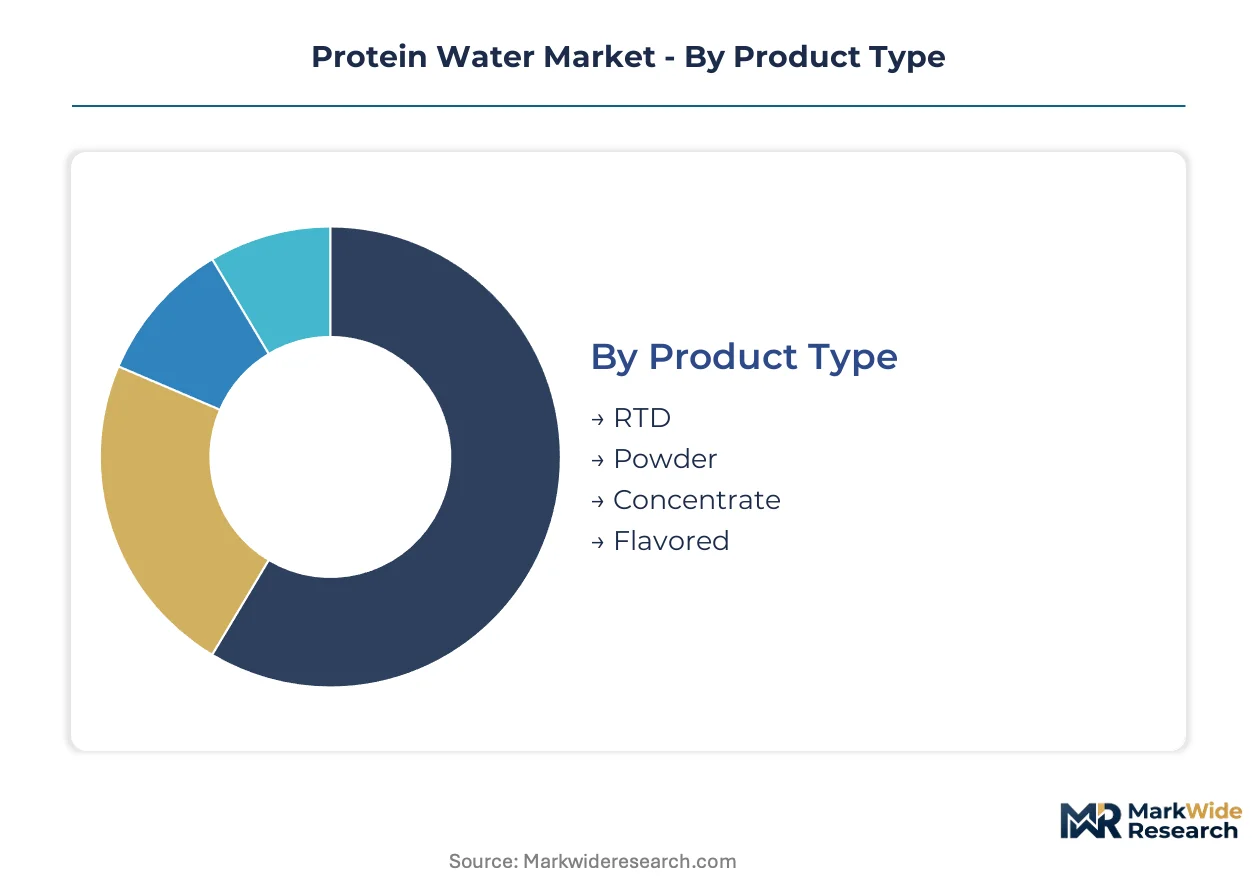
Protein water segmentation reveals divergent technical requirements across consumption occasions and protein sourcing philosophies. Manufacturers must balance bioavailability optimization against clean-label positioning while navigating channel-specific margin structures and regulatory claim substantiation.
Product Type:
Standardization dominates mainstream retail RTD formats while powder and concentrate segments accommodate customization through dosing flexibility and flavor adjacencies.
- RTD:Pre-formulated beverages in shelf-stable or refrigerated formats delivering 15–20 grams protein per 500ml serving. Demand clusters in United States metropolitan fitness studio corridors where refrigerated grab-and-go infrastructure supports premium placement and subscription bundling with gym memberships.
- Powder:Reconstitutable protein isolates requiring consumer preparation, enabling dose modulation and flavor stacking. Adoption accelerates among home-gym practitioners in Germany and United Kingdom seeking cost-per-serving efficiency without cold-chain dependency.
- Concentrate:Higher protein density formulations (25–30 grams per serving) targeting bodybuilding and strength-training cohorts. Compact shipping profiles favor direct-to-consumer channels with lower freight cost burdens.
- Flavored:Taste-masked variants using natural flavor systems and stevia or monk fruit sweeteners to mask protein hydrolysate bitterness.
Leading the category by volume: RTD. Growing fastest: Powder.
Ingredient Source:
Cost tiers separate dairy-derived isolates from plant alternatives, with allergen positioning and sustainability claims driving premium stratification.
- Whey:Rapid-absorption dairy protein isolate with superior leucine content triggering muscle protein synthesis. FDA GRAS status and established supply chains sustain dominance in United States sports nutrition retail.
- Casein:Slow-digesting micellar protein delivering sustained amino acid release over 4–6 hours. Overnight recovery positioning captures premium pricing in Japanese functional beverage markets.
- Pea:Hypoallergenic legume protein gaining formulation sophistication through microencapsulation advances. EFSA sustainability-linked claim frameworks favor carbon-documented supply chains in Netherlands and Denmark.
- Soy:Complete amino acid profile plant protein with established Asian supply infrastructure and isoflavone-associated health positioning.
Volume leadership: Whey. Steepest expansion trajectory: Pea.
Distribution Channel:
Margin capture varies sharply across channel archetypes, with physical fitness ecosystems attaching recurring revenue models unavailable to traditional retail.
- Online:Direct-to-consumer and marketplace platforms enabling subscription mechanics and influencer-driven discovery. Fitness-community brand equity converts most efficiently through owned digital properties.
- Supermarkets:Mass-market penetration requiring slotting fee absorption and shelf-stable formulation compromises. Clean-label thresholds determine assortment acceptance.
- Health Stores:Specialty retail with educated staff enabling premium positioning and cross-selling with supplement portfolios.
- Gyms:Proximity-to-occasion placement with membership-linked procurement and refrigerated fixture investment.
Highest margin capture: Gyms. Fastest channel expansion: Online.
Target Consumer:
Application intensity separates performance-driven segments from convenience-oriented cohorts, with occasion fragmentation reshaping SKU proliferation strategies.
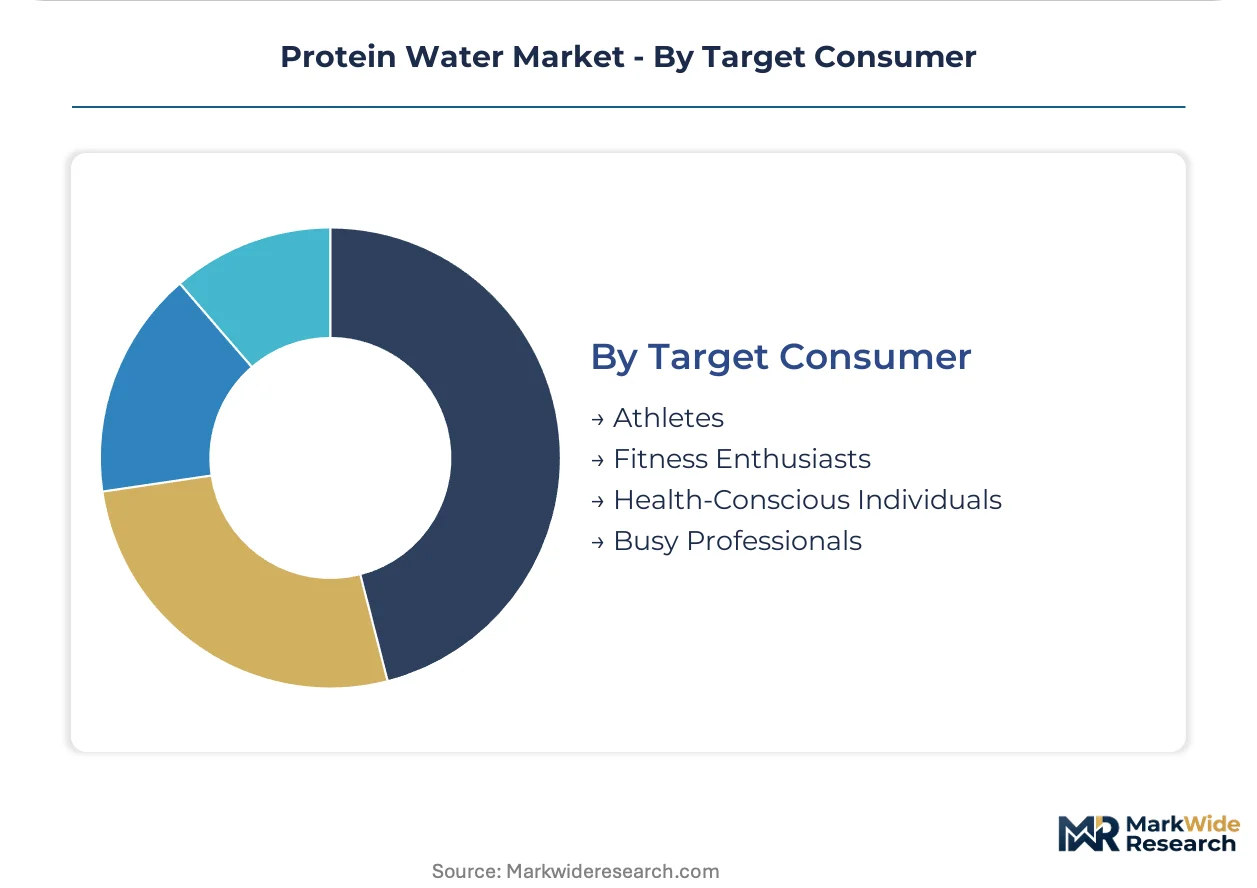
- Athletes:Competitive and recreational performers prioritizing recovery kinetics and batch-tested certification. Demand concentrates in institutional procurement through collegiate and professional sports programs.
- Fitness Enthusiasts:Regular gym attendees segmenting pre-workout, intra-workout, and post-workout hydration into distinct purchase decisions. United States studio density supports occasion-optimized product lines.
- Health-Conscious Individuals:Wellness-oriented consumers seeking protein fortification without caloric density of traditional shakes.
- Busy Professionals:Convenience-driven purchasers prioritizing portable nutrition and workplace-appropriate consumption formats.
Core revenue base: Fitness Enthusiasts. Fastest-growing cohort: Busy Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American protein water manufacturing through its Upper Midwest dairy processing corridor, where whey isolate production clusters feed RTD bottling operations and refrigerated distribution networks radiate toward coastal metropolitan fitness markets.
United States
Fitness studio density in Los Angeles and New York metropolitan areas drives occasion-specific SKU proliferation across pre-workout, intra-workout, and post-workout consumption moments. FDA GRAS status requirements for novel protein isolates extend approval timelines, compressing launch windows for emerging brands. Dallas-Fort Worth cold-chain logistics hubs enable national refrigerated distribution coverage for premium RTD formats.
Germany
Home-gym practitioner adoption accelerates powder segment demand in Berlin and Munich, where consumers prioritize cost-per-serving efficiency over convenience premiums. EFSA health claim substantiation frameworks govern permissible recovery benefit marketing, forcing clinical evidence investments. Hamburg beverage formulation clusters specialize in natural flavor systems and stevia-based taste masking for clean-label positioning.
United Kingdom
London health-conscious professionals segment hydration occasions into workplace-appropriate portable nutrition purchases distinct from gym-linked recovery consumption. EFSA sustainability-linked claim substantiation tightens environmental marketing requirements, favoring ISO 14001-certified operations. Manchester direct-to-consumer fulfillment infrastructure supports subscription model expansion for fitness-community brands.
Netherlands
Carbon-documented pea protein supply chains concentrate in Rotterdam port-adjacent processing facilities, leveraging ESG-driven supermarket buyer preferences for climate-transparent sourcing. EFSA evolving sustainability claim frameworks reward supply chain carbon intensity documentation. Eindhoven microencapsulation technology clusters advance lipid-shell systems for plant protein off-note remediation.
Australia
Sydney and Melbourne gym subscription integration models attach recurring beverage procurement to membership ecosystems, locking in predictable offtake volumes. TGA therapeutic goods frameworks overlap with food regulation for recovery-positioned products, creating compliance complexity. Brisbane direct-to-consumer influencer marketing infrastructure converts fitness-community brand equity through owned digital channels.
Protein Water Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation sophistication and cold-chain infrastructure investment, with the vendor base consolidating around three functional tiers. Vertically integrated dairy processors control input costs through captive whey supply, while fitness-community specialists monetize direct relationships through subscription mechanics. Strategic moves concentrate on refrigerated distribution capacity expansion and microencapsulation technology licensing for plant protein taste parity.
Within the established RTD infrastructure tier, Protein2o Inc. and Agropur Inc. occupy positions reflecting dairy-protein supply chain integration and mainstream retail placement scale. Muscle Nation exemplifies the fitness-community specialist archetype, anchoring direct-to-consumer channel intensity and influencer-driven discovery models. Aquatein represents emerging plant-protein formulation capabilities, sitting within the vegan-positioned growth vector where microencapsulation advances compress taste premiums against dairy alternatives.
| Leading Market Players |
|---|
| Protein2o Inc. |
| Aquatein |
| Muscle Nation |
| Musashi Nutrition |
| Protein Water Co. |
| NZ Muscle |
| Nexus Sports Nutrition |
| BODIE*Z |
| Agropur Inc. |
| Others |
Value Chain & Pricing Dynamics
Whey isolate feedstock costs cascade through three distinct pricing tiers as Upper Midwest dairy processing corridors anchor input supply for RTD bottlers while pea protein microencapsulation expenses compress vegan-positioned margins. Cold-chain logistics intensity separates refrigerated premium placement from shelf-stable economy alternatives, with gym subscription bundling capturing lifetime value unavailable to supermarket slotting-fee competitors.
Pricing Analysis
Outcome-based pricing anchored to post-workout recovery efficacy stratifies across premium, standard, and economy tiers. FDA GRAS certification investment and ISO 22000 audit depth differentiate price floors, while flavor chemist talent scarcity at legacy beverage conglomerates concentrates premium pricing power among established players. Pricing pressure stems from pea protein taste masking cost inflation as vegan formulation capabilities mature. Fitness enthusiasts demonstrate lowest price sensitivity through subscription lock-in, whereas busy professionals in workplace portable nutrition segments drive volume through promotional elasticity.
Supply Chain Analysis
Return flows of expired refrigerated inventory and subscription box consolidation create reverse-logistics complexity that favors national distributors with temperature-controlled consolidation hubs. Whey isolate production clusters in the United States, Netherlands, and Germany, while pea protein processing concentrates in Canada and France. Supply chains draw from dairy cooperatives, legume processors, and natural flavor system suppliers. Single-source vulnerability to Upper Midwest climate disruption threatens input continuity. Distribution runs through refrigerated logistics networks radiating from Dallas-Fort Worth and Chicago toward coastal metropolitan fitness markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protein water capacity bottlenecks at qualified cold-chain infrastructure prop pricing premiums, as refrigerated distribution asset scarcity limits RTD expansion for emerging brands.
For Market Incumbents: Extend refrigerated fixture penetration through exclusive gym partnership agreements before microencapsulation technology licensing erodes whey taste premiums. Acquire ISO 22000-certified private-label manufacturers to consolidate quality-forward capacity. Neutralize plant-protein entrants by accelerating collagen-protein hybrid formulation pipelines that capture adjacent cosmetics retail shelf space. For New Entrants and Emerging Players: The mid-tier price gap between premium refrigerated RTD and economy powder formats offers white-space entry through direct-to-consumer subscription mechanics bypassing slotting fees. Target home-gym practitioners in Germany and United Kingdom with cost-per-serving efficiency messaging. Leverage fitness influencer discovery models to build brand equity before retail scale investment. For Investors and Strategic Acquirers: EFSA sustainability-linked claim framework finalization is the leading indicator that carbon-documented supply chains will command retail assortment preference. Position acquisition screening around ISO 14001-certified operations with Rotterdam port-adjacent pea protein processing assets. Monitor microencapsulation technology licensing deal velocity as inflection signal for plant-protein taste parity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Distribution Expansion | Dallas-Fort Worth hub investment enables national coverage for premium RTD formats. |
| Microencapsulation Technology Licensing | Eindhoven lipid-shell systems acquisition collapses pea protein taste gap with dairy. |
| Gym Subscription Integration | Membership ecosystem attachment locks predictable offtake volumes in Sydney and Melbourne. |
| ISO 22000 Certification Investment | Audit depth creates acquisition currency for quality-forward brand consolidation. |
| Collagen-Protein Hybrid Launch | Beauty-from-within positioning opens cosmetics retail adjacent to nutrition channels. |
Study Parameters
Document review covered FDA GRAS filings, EFSA health claim substantiation records, and ISO certification databases, complemented by interviews with protein water brand managers, refrigerated logistics operators, gym procurement directors, and dairy cooperative supply planners. Secondary validation drew from customs trade data, Nielsen retail audit figures, and sports nutrition industry association reports. Bottom-up volume modeling triangulated against top-down category spend analysis.
Cross-referencing historical consumption patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, protein source philosophy, distribution channel archetype, and target consumer occasion intensity. CAGRs were derived from demand elasticity coefficients and supply capacity expansion schedules. Forecast inputs incorporated EFSA regulatory evolution timelines and microencapsulation technology adoption curves.
Inputs from gym subscription platforms and refrigerated logistics providers were available through the study window; gaps in emerging protein isolate GRAS approval timelines introduce uncertainty bands around novel source launch projections. Forecasts reflect documented assumptions regarding clean-label threshold evolution and sustainability certification penetration. Practitioners should monitor EFSA carbon intensity documentation requirements and FDA novel protein approval velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market