
 Europe Medical Foods Market | 2026-2036
Europe Medical Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Foods Market Intelligence
Homecare settings for chronic disease management is rebalancing demand away from acute hospital nutrition toward outpatient metabolic support. Danone leverages its specialized nutrition division to anchor R&D intensity in rare disease formulations. Nestlé Health Science competes through geographic dominance across Western European reimbursement channels. Abbott differentiates via technology leadership in disease-specific enteral delivery systems.
Medical foods are specially formulated products intended for dietary management of diseases with distinctive nutritional requirements, manufactured under pharmaceutical-grade conditions with precise macronutrient and micronutrient profiles. These products serve primarily to address metabolic disorders, malabsorption conditions, and organ-specific diseases where standard diet modification proves insufficient. Enteral nutrition leads product type margins due to higher clinical validation barriers and institutional procurement contracts. Gastrointestinal disorder applications represent the fastest-growing segment as Crohn's disease and short bowel syndrome protocols expand. Powder formulations occupy the largest volume share though ready-to-drink formats are gaining share in homecare settings.
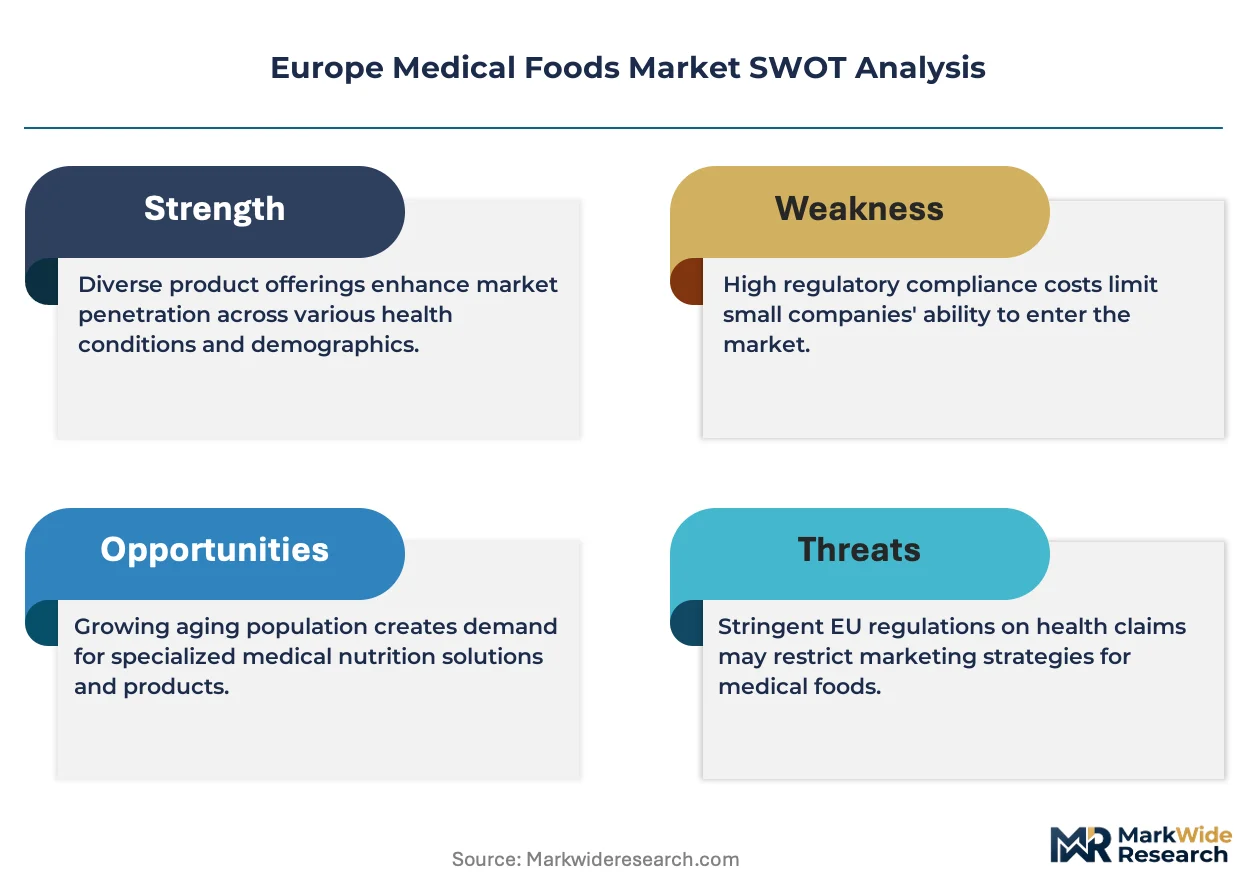
EFSA health claims authorization and EU Medical Device Regulation classification determine market access and reimbursement eligibility for medical food manufacturers. CE marking requirements under MDR intensify quality system documentation burdens while creating compliance moats for established producers. The EU AI Act introduces emerging oversight for algorithmic nutritional personalization tools entering clinical workflows. Stakeholders must monitor evolving member state reimbursement harmonization and health technology assessment integration for medical foods.
Market Dynamics
The EU Medical Device Regulation is compressing market entry timelines while elevating documentation burdens, forcing manufacturers to consolidate quality systems or exit. CE marking under MDR now requires clinical evidence portfolios that favor established pharmaceutical-grade producers with existing notified body relationships.
Growth Catalysts
- MDR compliance infrastructure:Stricter CE marking requirements under the EU Medical Device Regulation create compliance moats that protect incumbent manufacturers from commoditization.
- Geriatric homecare expansion:Germany's centralized hospital procurement reforms and France's outpatient reimbursement protocols accelerate enteral nutrition demand outside institutional settings.
- Metabolic disorder protocols:Pediatric rare disease management programs in the United Kingdom drive specialized formulation requirements for inherited metabolic conditions.
Market Restraints
- Notified body capacity:Limited EU-authorized conformity assessment organizations under MDR extend certification timelines for new market entrants.
- Reimbursement fragmentation:Member state-level health technology assessment divergence creates pricing arbitrage constraints across Germany, France, and the United Kingdom.
- Active pharmaceutical ingredient concentration:Pharmaceutical-grade micronutrient supply concentrates among three specialized European chemical manufacturers.
Strategic Opportunities
- Eastern European hospital networks:Poland and Romania's underdeveloped medical food procurement channels offer first-mover positioning for compliant Western European producers.
- EU AI Act algorithmic nutrition:Personalized enteral dosing algorithms qualify for streamlined clinical workflow integration under emerging artificial intelligence oversight frameworks.
- Ready-to-drink homecare formats:Shelf-stable liquid formulations displace powder mixing in outpatient Crohn's disease and short bowel syndrome protocols.
Industry Challenges
- Clinical nutrition specialist shortage:Registered dietitian credentialing gaps in metabolic disease management limit protocol expansion in tertiary care centers.
- Legacy ERP integration:Pharmaceutical-grade batch tracking requirements strain manufacturing execution systems originally designed for conventional food production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Foods Market |
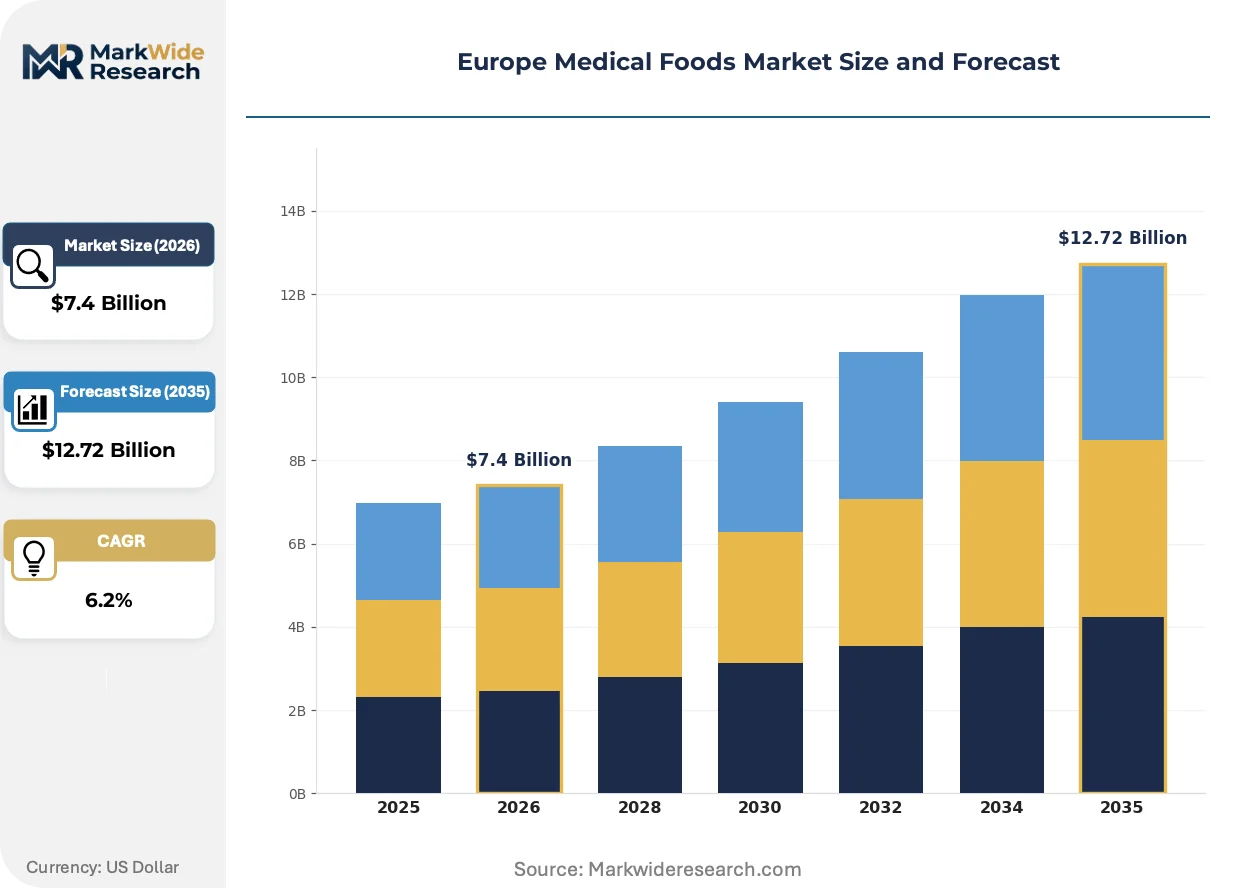
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Food, Nutritional Supplement, Adult Nutritional Formula, Enteral Nutrition Application: Inborn Errors of Metabolism, Malnutrition, Chronic Kidney Disease, Gastrointestinal Disorders End User: Hospitals, Homecare Settings, Clinics, Long-term Care Facilities Formulation: Powder, Liquid, Ready-to-Drink, Tablets |
| Companies Covered | Danone, Nestlé, Abbott, Fresenius Kabi AG, Nutricia, Nestlé Health Science, Mead Johnson & Company, Targeted Medical Pharma, Primus Pharmaceuticals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Foods Market Strategic Shifts & Innovations
Digital health convergence is reshaping how medical food protocols integrate with electronic health records and remote patient monitoring. Three distinct vectors are compressing development cycles and redrawing competitive boundaries across the European market.
Precision fermentation-derived bioactive peptides are absorbing amino acid sourcing functions previously served by hydrolyzed protein isolates. Pediatric metabolic disorder specialists in German university hospitals are piloting these ingredients for phenylketonemia formulations. The technology is absorbing margin pressure from volatile dairy protein commodity markets while enabling cleaner-label positioning.
EFSA's evolving health claims authorization framework is tightening evidentiary standards for disease-specific nutritional interventions. Manufacturers must now submit human intervention studies rather than relying on compositional equivalence. Gastrointestinal disorder applications face the steepest compliance ramp as Crohn's disease protocols require prospective clinical data.
Homecare reimbursement parity is collapsing the traditional hospital-centric distribution model. French and British insurance funds now cover enteral delivery systems for outpatient use, redirecting volume toward specialized pharmacy networks. Germany's ambulatory care reform accelerates this shift by bundling medical food costs into capitated chronic disease management contracts.
Europe Medical Foods Market Segmentation
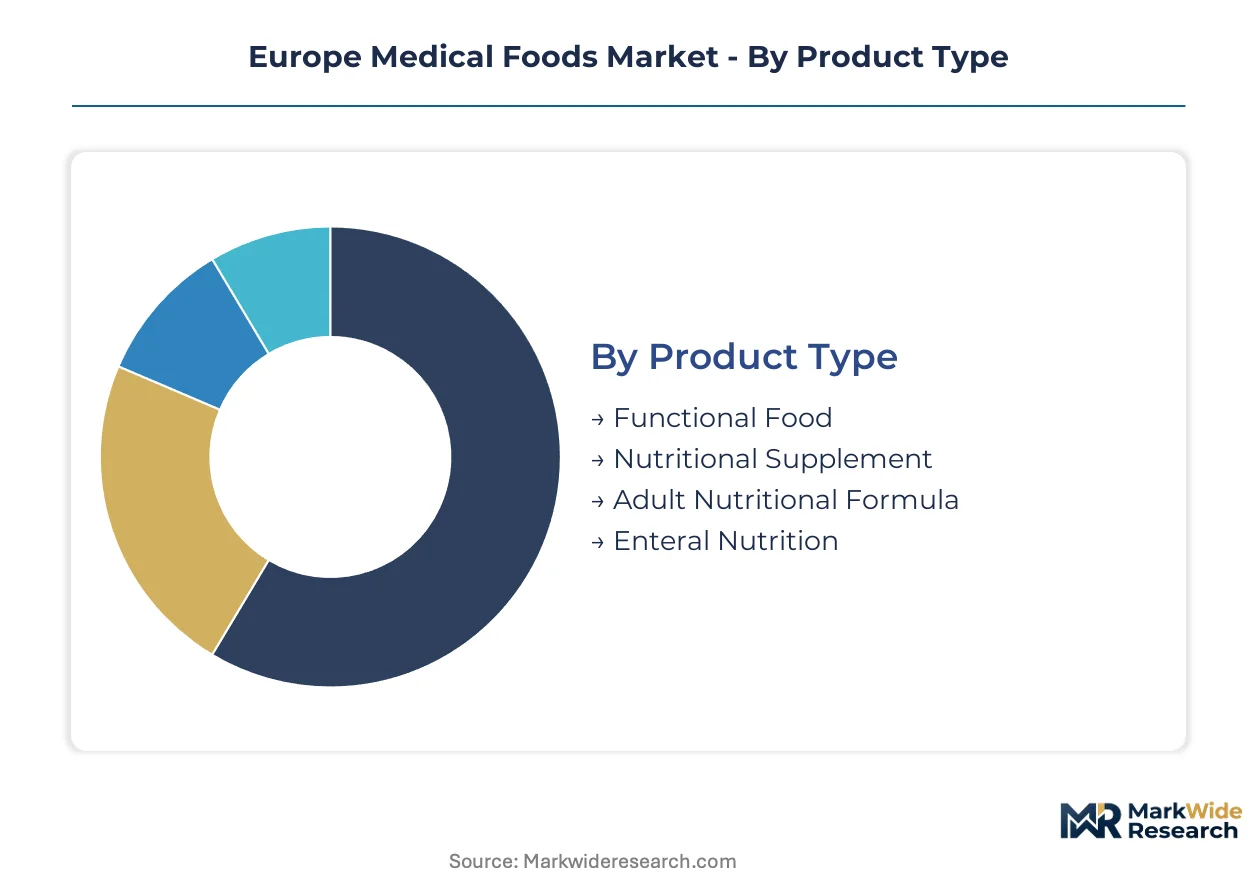
Medical food segmentation in Europe reflects divergent capital requirements across pharmaceutical-grade manufacturing and clinical validation pathways. Product type and formulation categories demand specialized production infrastructure, while application and end-user segments determine reimbursement complexity and distribution economics.
Product Type:
Capital intensity peaks in enteral nutrition, where sterile manufacturing suites and clinical evidence portfolios require the heaviest upfront investment. Functional food carries lighter regulatory burdens but faces commoditization pressure from conventional nutrition products.
- Enteral Nutrition:Tube-delivered formulations manufactured under aseptic conditions with disease-specific macronutrient density profiles. German hospital procurement centralization and French homecare reimbursement expansion concentrate demand for institutional-grade enteral systems.
- Adult Nutritional Formula:Oral formulations targeting geriatric malabsorption and post-surgical recovery with pharmaceutical-grade micronutrient fortification. United Kingdom NHS chronic disease management contracts and German ambulatory care reforms accelerate outpatient volume.
- Nutritional Supplement:Adjunct products bridging dietary gaps in metabolic disorder protocols with targeted amino acid or vitamin profiles.
- Functional Food:Medical-grade food products with modified textures or compositions for dysphagia and digestive intolerance management.
Most installed capacity flows through Enteral Nutrition. Expansion is steepest in Adult Nutritional Formula.
Application:
Application segmentation tracks the divergence between rare disease protocols requiring specialized formulations and high-volume chronic conditions driving economies of scale. Gastrointestinal disorders absorb the steepest R&D investment as EFSA tightens evidentiary standards.
- Gastrointestinal Disorders:Crohn's disease and short bowel syndrome formulations with elemental peptide profiles and reduced osmolarity. French and British outpatient reimbursement parity redirects volume from hospital infusion centers toward home enteral delivery.
- Inborn Errors of Metabolism:Phenylketonemia and maple syrup urine disease formulations with precisely restricted amino acid content. United Kingdom pediatric rare disease programs and German university hospital metabolic centers concentrate specialized demand.
- Chronic Kidney Disease:Protein-restricted formulations with adjusted electrolyte profiles for dialysis and pre-dialysis patients.
- Malnutrition:High-calorie density products for cancer cachexia and geriatric sarcopenia with optimized protein-to-energy ratios.
Volume concentrates in Malnutrition applications. Steepest expansion trajectory belongs to Gastrointestinal Disorders.
End User:
End-user segmentation captures the structural shift from institutional procurement toward reimbursed homecare channels. Hospital contracts retain volume concentration while homecare settings command premium pricing for delivery system integration.
- Hospitals:Acute care and tertiary metabolic centers with centralized procurement and formulary committees. Germany's hospital procurement reform consolidates purchasing power across state-level networks.
- Homecare Settings:Outpatient enteral and oral nutrition with remote monitoring integration. French insurance fund reimbursement parity and British NHS community care contracts accelerate channel migration.
- Long-term Care Facilities:Geriatric institutions with standardized protocols for dysphagia and dementia-related nutritional support.
- Clinics:Outpatient metabolic and gastroenterology practices with specialized dietitian oversight.
Hospital procurement retains the largest volume share. Homecare Settings are climbing the fastest.
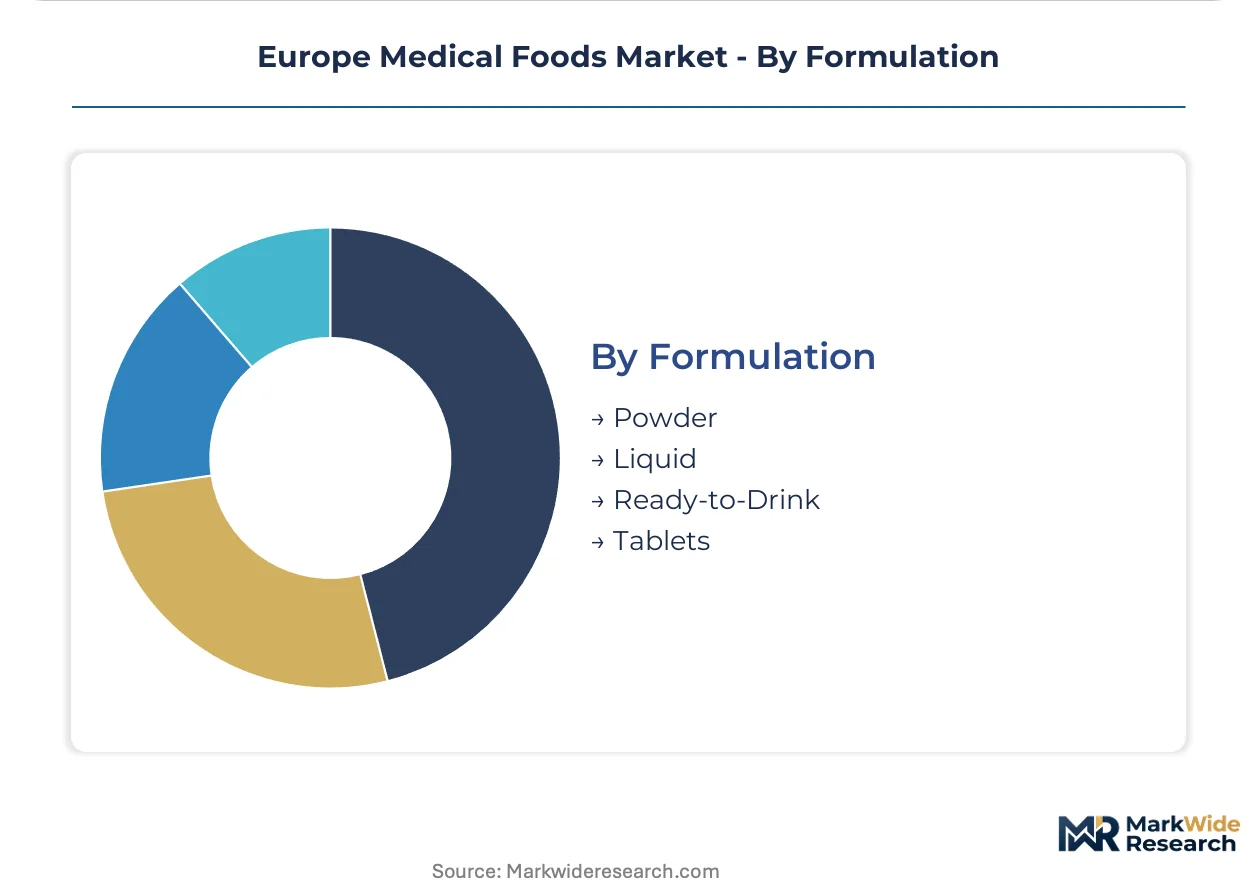
Formulation:
Formulation segmentation reflects manufacturing capital allocation between powder processing infrastructure and aseptic liquid production. Ready-to-drink formats absorb the steepest equipment investment for shelf-stable emulsion technology.
- Powder:Reconstituted formulations with extended stability and lower logistics costs. German and British hospital bulk purchasing favors powder economics for high-volume malnutrition protocols.
- Ready-to-Drink:Pre-mixed liquid products with sterile filling and tamper-evident packaging. French homecare reimbursement and outpatient Crohn's protocols in the United Kingdom drive format premiumization.
- Liquid:Concentrated or ready-to-use formulations requiring refrigeration with shorter shelf stability.
- Tablets:Compressed nutritional supplements for metabolic disorder adjunct therapy with precise micronutrient dosing.
Powder formulations dominate installed production capacity. Ready-to-Drink formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing production capacity toward jurisdictions with streamlined CE marking pathways under MDR. Manufacturers are relocating formulation facilities to exploit notified body concentration and reimbursement harmonization gaps across member states.
Germany
Hospital procurement centralization and ambulatory care reform drive enteral nutrition demand toward outpatient channels. The Federal Institute for Drugs and Medical Devices (BfArM) enforces MDR compliance timelines that favor established pharmaceutical-grade producers. North Rhine-Westphalia's metabolic centers in Cologne and Düsseldorf anchor pediatric rare disease formulation development.
France
Homecare reimbursement parity for enteral delivery systems accelerates volume migration from hospital infusion centers. ANSM oversight of medical device vigilance creates compliance moats for notified body-certified manufacturers. The Paris-Saclay cluster concentrates R&D activity for Crohn's disease and short bowel syndrome protocols.
United Kingdom
NHS chronic disease management contracts and pediatric rare disease programs concentrate demand for specialized metabolic formulations. MHRA post-Brexit regulatory divergence introduces parallel authorization requirements alongside retained EU MDR alignment. London's tertiary metabolic centers and Manchester's specialized pharmacy networks drive protocol innovation.
Italy
Geriatric malnutrition protocols and regional health system procurement integration expand adult nutritional formula volume. AIFA pricing negotiations and health technology assessment regionalization create reimbursement complexity across northern and southern markets. Lombardy's pharmaceutical manufacturing corridor near Milan hosts sterile enteral production infrastructure.
Netherlands
Centralized health technology assessment through ZIN and hospital procurement collaboration reduce pricing arbitrage opportunities. The Dutch Medicines Evaluation Board (CBG) coordinates MDR implementation with EMA alignment for borderline nutritional products. The Randstad's logistics infrastructure supports just-in-time distribution to Belgian and German border regions.
Europe Medical Foods Market Key Industry Players
MDR compliance infrastructure investments dominate the current landscape as manufacturers consolidate quality systems or exit. The market structures around three tiers: multinational nutrition conglomerates with pharmaceutical-grade manufacturing networks, specialized medical food divisions of broader healthcare groups, and regional compounding pharmacies serving metabolic disorder protocols. Strategic archetypes include vertically integrated formula developers, technology-licensing delivery system specialists, and reimbursement-channel optimizers. Capacity expansion in sterile liquid production and M&A targeting rare disease formulation pipelines represent the dominant competitive vectors.
Within the multinational conglomerate tier, Danone S.A. and Nestlé S.A. occupy positions anchored by specialized nutrition divisions with established notified body relationships. Abbott Laboratories exemplifies the technology-specialist archetype through disease-specific enteral delivery system development. These three entities represent the compliance-moat beneficiaries as MDR documentation burdens intensify.
| Leading Market Players |
|---|
| Danone |
| Nestlé |
| Abbott |
| Fresenius Kabi AG |
| Nutricia |
| Nestlé Health Science |
| Mead Johnson & Company |
| Targeted Medical Pharma |
| Primus Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Specialized pharmaceutical-grade manufacturing workforce concentration in Germany's North Rhine-Westphalia and Bavaria regions widens pricing-tier spreads between CE-marked premium formulations and standard nutritional products. Labor-cost differentials between these certified production clusters and emerging Eastern European compounding facilities feed into three-tier pricing stratification across hospital procurement, homecare reimbursement, and direct-pay outpatient channels.
Pricing Analysis
Distributor margin layers absorb 18-25 percentage points between sterile enteral manufacturers and hospital procurement committees, compressing net realized prices for volume contract holders. Three-tier pricing structure across premium, standard, and economy levels separates MDR-validated rare disease formulations from adult nutritional formulas and commodity malnutrition supplements. Pricing pressure stems from centralized German hospital procurement reforms bundling medical food costs into capitated chronic disease contracts. Homecare settings exhibit lowest price sensitivity due to reimbursement parity, while long-term care facilities face acute budget constraints driving generic substitution.
Supply Chain Analysis
Direct-to-hospital channels handle institutional-grade enteral demand through Germany's centralized procurement networks, while specialized pharmacy networks manage reimbursed homecare distribution across France and the United Kingdom. Pharmaceutical-grade micronutrient supply concentrates in Germany, Switzerland, and the Netherlands, with amino acid premixes and vitamin microencapsulation inputs drawing from these specialized chemical manufacturers. Single-source vulnerability in pharmaceutical-grade protein isolates creates supply chain risk given limited European fermentation capacity for hypoallergenic peptide production. Distribution runs through dual-track logistics: cold-chain liquid formulations for homecare and ambient-stable powder bulk for hospital central kitchens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Medical Foods Market functions as a regulatory compounder where MDR compliance timelines and EFSA health claims authorization create escalating barriers that concentrate returns among notified body-certified manufacturers. The EU Medical Device Regulation's clinical evidence requirements represent the dominant regulatory milestone reshaping competitive economics and acquisition premiums across the forecast window.
For Market Incumbents: Deploy MDR quality system infrastructure as a consolidation lever against regional compounding pharmacies lacking notified body relationships. Acquire specialized rare disease formulation pipelines in the United Kingdom and Germany to anchor pediatric metabolic disorder protocols before EFSA tightens evidentiary standards for inborn errors of metabolism. Capacity expansion in sterile liquid production addresses the format premiumization running through French and British homecare reimbursement channels. For New Entrants and Emerging Players: Capture Eastern European white-space in Poland and Romania where hospital procurement centralization lags Western European reimbursement harmonization. Target gastrointestinal disorder applications in outpatient Crohn's disease protocols as the fastest-expanding segment with lower incumbent concentration than metabolic rare diseases. Pursue technology-licensing partnerships with established enteral delivery system developers rather than building pharmaceutical-grade manufacturing de novo. For Investors and Strategic Acquirers: Specialized nutrition divisions of multinational healthcare conglomerates are the most active acquirer in this space, seeking MDR-compliant manufacturing assets and rare disease formulation pipelines. Long-term viability centers on 5-10 year regulatory moat sustainability rather than volume growth, given reimbursement parity constraints and health technology assessment integration across member states. Monitor notified body capacity expansion as the critical inflection signal for new entrant viability and acquisition multiple compression.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | CE marking under EU Medical Device Regulation creates compliance moats protecting incumbent manufacturers from price erosion. |
| Hospital System Partnership | German procurement centralization and French reimbursement parity favor manufacturers with formulary committee relationships. |
| Reimbursement Strategy | EFSA health claims authorization and member state HTA integration determine market access economics for disease-specific formulations. |
| Software Companion Development | EU AI Act oversight for algorithmic nutritional personalization tools enables clinical workflow integration premiums. |
| Manufacturing Scale-Up | Sterile liquid production capacity expansion addresses ready-to-drink format demand in British and French homecare settings. |
Research Approach
Coverage spans Germany, France, the United Kingdom, Italy, and the Netherlands, with primary inputs from each market's regulatory and reimbursement stakeholders. Primary interviews with hospital procurement managers, specialized dietitians in metabolic centers, notified body certification officers, and pharmaceutical-grade manufacturing executives combined with secondary validation from EFSA health claims registers, BfArM medical device databases, NHS formulary records, and ANSM vigilance reports. Bottom-up enteral and oral nutrition volume estimates triangulated against top-down reimbursement expenditure data from national health insurance funds.
Rate-of-change decomposition separates volume drivers from pricing dynamics across the projection horizon. Segmentation modeling incorporates product type, application, end-user channel, and formulation format dimensions alongside MDR compliance status tiers. CAGRs derived from fitted trend analysis of historical reimbursement expenditure patterns and projected health technology assessment integration timelines. Forecast inputs include pediatric rare disease program expansion rates in the United Kingdom and ambulatory care reform implementation velocity in Germany.
Regulatory timeline delays, notified body capacity constraints, and reimbursement harmonization setbacks are the dominant revision risks for forecast trajectories. Forecasts reflect assumptions regarding EFSA evidentiary standard evolution and member state HTA convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Low Fat Protein Market