
 Asia-Pacific Functional Water Market | 2026-2036
Asia-Pacific Functional Water Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Functional Water Market Outlook
Chinese and Japanese bottling infrastructure is broadening across the Asia-Pacific functional water supply base. Nongfu Spring Co., Ltd. leverages its deep well-spring access and domestic distribution density to anchor premium mineral water lines. Suntory Beverage & Food Limited sustains formulation leadership in electrolyte and vitamin-fortified variants across East Asian markets. PepsiCo, Inc. competes through its expansive convenience store and supermarket channel control in Southeast Asian growth corridors.
Asia-Pacific functional water comprises non-alcoholic beverages enhanced with vitamins, minerals, electrolytes, or herbal extracts, typically formulated to specific osmolality and pH parameters for hydration efficacy. These products serve targeted physiological outcomes including athletic recovery, metabolic support, and daily micronutrient supplementation beyond conventional hydration. Electrolyte water and vitamin water command the largest current volume positions, though herbal infused water generates disproportionate margin expansion as traditional medicine positioning resonates with aging demographics. Mineral water retains structural importance in Japan and South Korea where natural source certification commands price premiums, while pouch and tetra pack formats gain traction in India's price-sensitive urban markets.
China's SAMR enforces stringent additive disclosure and health claim substantiation under national food safety standards, directly shaping product development timelines and label architectures. Japan's METI and Consumer Affairs Agency coordinate functional food labeling systems that permit qualified health claims only after clinical dossier review, creating barrier-to-entry effects for new entrants. India's FSSAI progressively harmonizes with Codex Alimentarius frameworks for fortified beverages, influencing import compliance costs. Stakeholders must monitor evolving cross-border e-commerce regulations as online retail channels become the primary discovery mechanism for health-conscious consumers across the region.
Market Dynamics
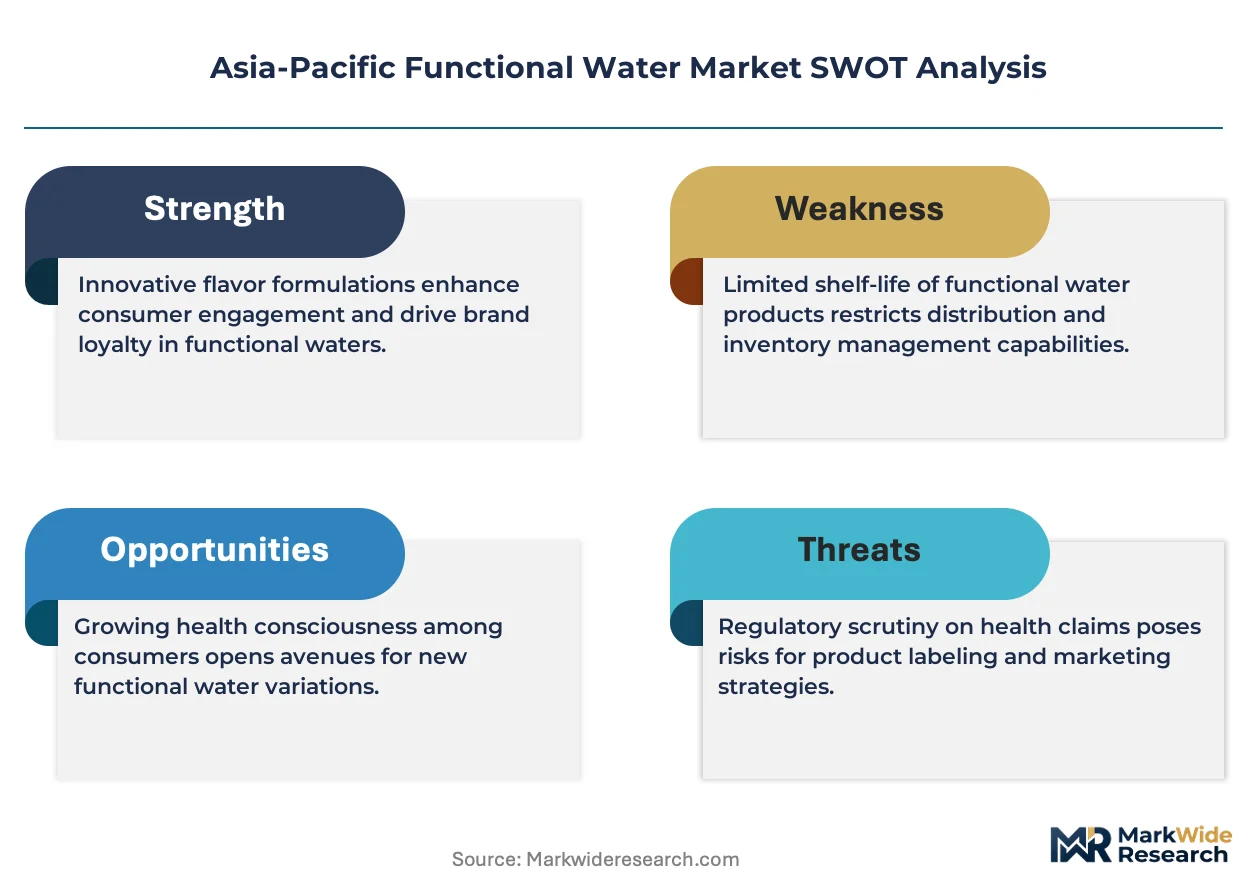
China's SAMR additive disclosure mandates and Japan's METI clinical dossier requirements are compressing product development timelines across the Asia-Pacific functional water sector, forcing reformulation investments and label architecture redesigns.
Growth Catalysts
- Fitness Enthusiast Expansion:India's metropolitan corridors and China's tier-one cities are witnessing surging demand for electrolyte-fortified variants among urban exercise communities.
- SAMR Food Safety Standards:China's stringent health claim substantiation rules are elevating quality benchmarks and accelerating premium product differentiation.
- Herbal Extract Integration:Traditional medicine positioning in aging Japanese and South Korean demographics is driving margin expansion for botanical-infused functional waters.
Market Restraints
- Natural Source Certification Costs:Japan and South Korea's mineral water certification requirements impose capital-intensive spring access and testing protocols on new entrants.
- Import Compliance Burden:India's FSSAI harmonization with Codex Alimentarius frameworks elevates cross-border e-commerce costs for foreign brands.
- Packaging Input Volatility:Pouch and tetra pack format adoption in price-sensitive Indian urban markets exposes manufacturers to polymer and aluminum supply fluctuations.
Strategic Opportunities
- Southeast Asian Convenience Channels:Vietnam, Thailand, and Indonesia's underserviced supermarket and convenience store networks offer whitespace for electrolyte water penetration.
- Dual Carbon Alignment:China's MEE environmental targets and carbon neutrality mandates create regulatory tailwinds for low-carbon bottling infrastructure investments.
- Aging Demographic Targeting:Metabolic support formulations addressing diabetes and cardiovascular health concerns resonate with Japan's expanding senior consumer base.
Industry Challenges
- Clinical Dossier Compilation:Japan's Consumer Affairs Agency qualified health claim reviews demand 12-18 month substantiation timelines, delaying product launches.
- Legacy Distribution Integration:Tetra pack and pouch format adoption requires reconfiguration of India's established ambient supply chain for glass and PET dominance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Functional Water Market |
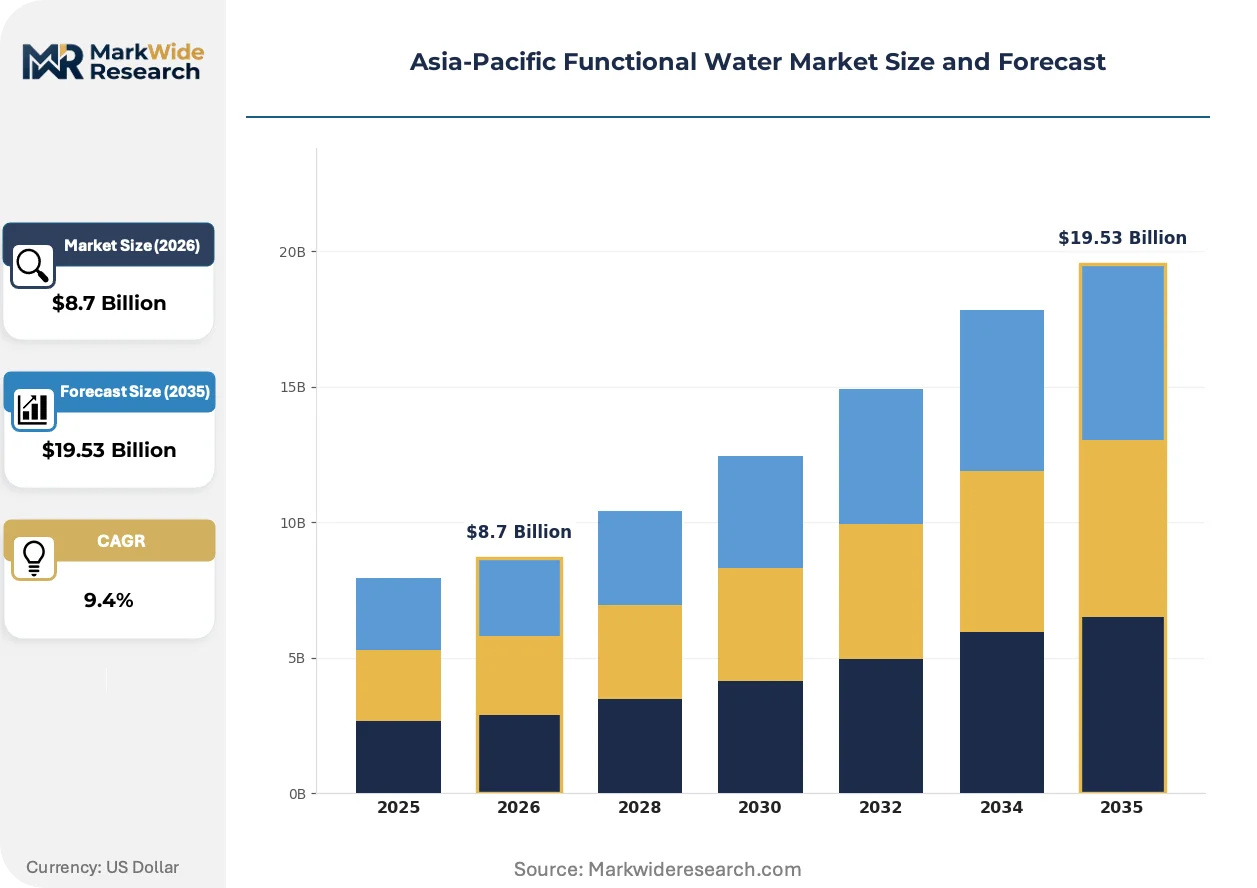
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin Water, Mineral Water, Electrolyte Water, Herbal Infused Water End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, Casual Drinkers Distribution Channel: Supermarkets, Health Stores, Online Retail, Convenience Stores Packaging Type: Bottles, Cans, Pouches, Tetra Packs |
| Companies Covered | The Coca-Cola Company, PepsiCo, Inc., Danone SA, Nestle SA, Suntory Beverage & Food Limited, Nongfu Spring Co., Ltd., Hangzhou Wahaha Group Co., Ltd., Veda Beverages Private Limited, BODIEZ, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Functional Water Market Strategic Shifts
Formulation science and packaging technology are converging to reshape competitive positioning across Asia-Pacific functional water, with osmolality optimization and sustainable materials emerging as primary vectors of differentiation.
Electrolyte osmolality tuning technology is integrating into premium product lines to enhance cellular absorption rates during athletic recovery. Japanese and South Korean fitness beverage manufacturers are deploying isotonic and hypotonic formulations at accelerated development cycles. This precision hydration engineering is integrating with wearable biometric data to enable personalized consumption recommendations.
China's SAMR is tightening additive disclosure thresholds under revised national food safety standards, compelling manufacturers to reformulate synthetic preservative dependencies. The industrial consequence is a pivot toward clean-label positioning and natural shelf-life extension methods. Premium mineral water lines in tier-one Chinese cities are responding with accelerated spring-source certification and minimal-processing claims.
Discovery patterns among health-conscious consumers are rotating toward cross-border e-commerce platforms, displacing traditional retail-first brand building. Southeast Asian urban millennials are purchasing vitamin-fortified variants through direct-to-consumer channels before supermarket availability. This channel inversion is most visible in Thailand and Vietnam, where social commerce integration precedes brick-and-mortar distribution negotiations.
Asia-Pacific Functional Water Market Segmentation
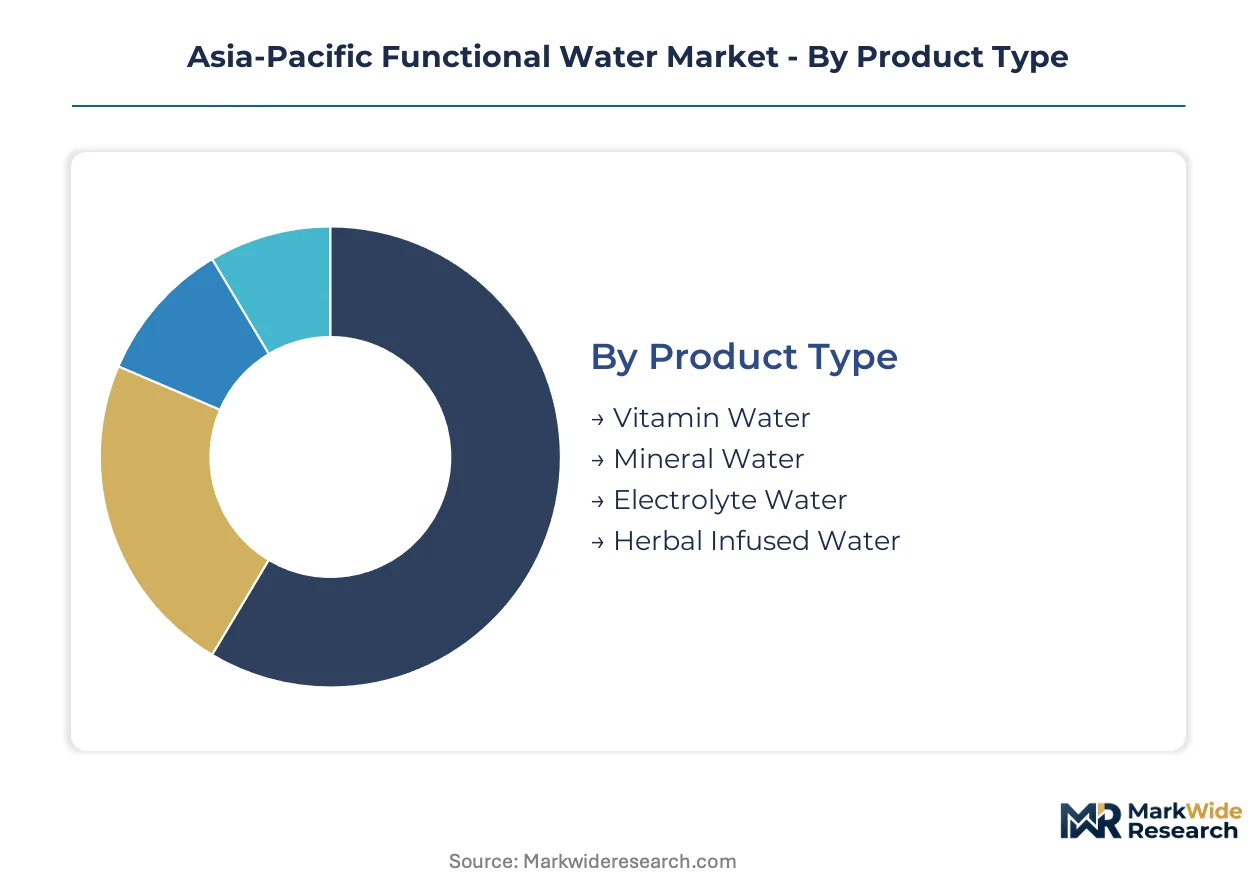
Functional water segmentation in Asia-Pacific reflects divergent supply chain configurations and regulatory compliance burdens across product formulations and channel structures. Understanding these divisions reveals where capital deployment encounters friction versus acceleration.
Product Type:
Supply concentration varies sharply by source certification requirements and formulation complexity, with natural mineral extraction rights creating bottlenecks in Japan and South Korea while fortified variants face additive scrutiny under China's SAMR.
- Electrolyte Water:Isotonic and hypotonic formulations engineered for cellular absorption during athletic recovery. Demand concentrates in China's tier-one city fitness communities and India's metropolitan corridors where urban exercise culture expands fastest.
- Mineral Water:Naturally sourced products requiring capital-intensive spring access and certification protocols. Japan and South Korea's aging populations pay premiums for source-authenticated variants, though extraction permits limit new entrant supply.
- Vitamin Water:Fortified beverages with micronutrient profiles targeting daily supplementation needs.
- Herbal Infused Water:Botanical extracts positioned within traditional medicine frameworks, gaining margin expansion in aging East Asian demographics.
Today's leader: Electrolyte Water. Tomorrow's challenger: Herbal Infused Water.
End User:
Cost tier differentiation separates premium-positioned metabolic support formulations from mass-market hydration, with clinical substantiation investments determining which user segments manufacturers can legally target.
- Fitness Enthusiasts:Urban exercise communities seeking recovery-optimized hydration with biometric-informed consumption patterns. This segment commands premium pricing in China's Beijing-Shanghai corridor and India's Mumbai-Delhi axis where gym penetration climbs fastest.
- Health-Conscious Consumers:Broad demographic pursuing clean-label positioning and additive transparency. China's SAMR disclosure mandates and Japan's METI labeling systems shape product accessibility for this cohort.
- Athletes:Performance-focused users requiring precise osmolality specifications for competition hydration protocols.
- Casual Drinkers:Price-sensitive mass market consumers driving volume in Southeast Asian convenience channels.
Fitness Enthusiasts absorb the steepest price premiums. Health-Conscious Consumers are expanding most quickly.
Distribution Channel:
Volume flows disproportionately through channels with cold chain reliability and impulse purchase visibility, though discovery patterns are inverting as e-commerce platforms precede brick-and-mortar availability.
- Online Retail:Cross-border e-commerce platforms enabling direct-to-consumer discovery before supermarket negotiations. Thailand and Vietnam's urban millennials purchase vitamin-fortified variants through social commerce integration.
- Convenience Stores:High-frequency impulse channel dominating Southeast Asian urban corridors. PepsiCo's channel control in Vietnam, Thailand, and Indonesia creates whitespace for electrolyte water penetration.
- Supermarkets:Traditional mass-market volume channel requiring slotting fee investments and shelf space negotiations.
- Health Stores:Specialty retail targeting supplement-adjacent positioning with educated staff recommendations.
Online Retail gains share fastest. Convenience Stores defend the volume base.
Packaging Type:
Maturity gradients separate established PET bottling infrastructure from experimental formats requiring supply chain reconfiguration, with environmental compliance costs accelerating format transitions.
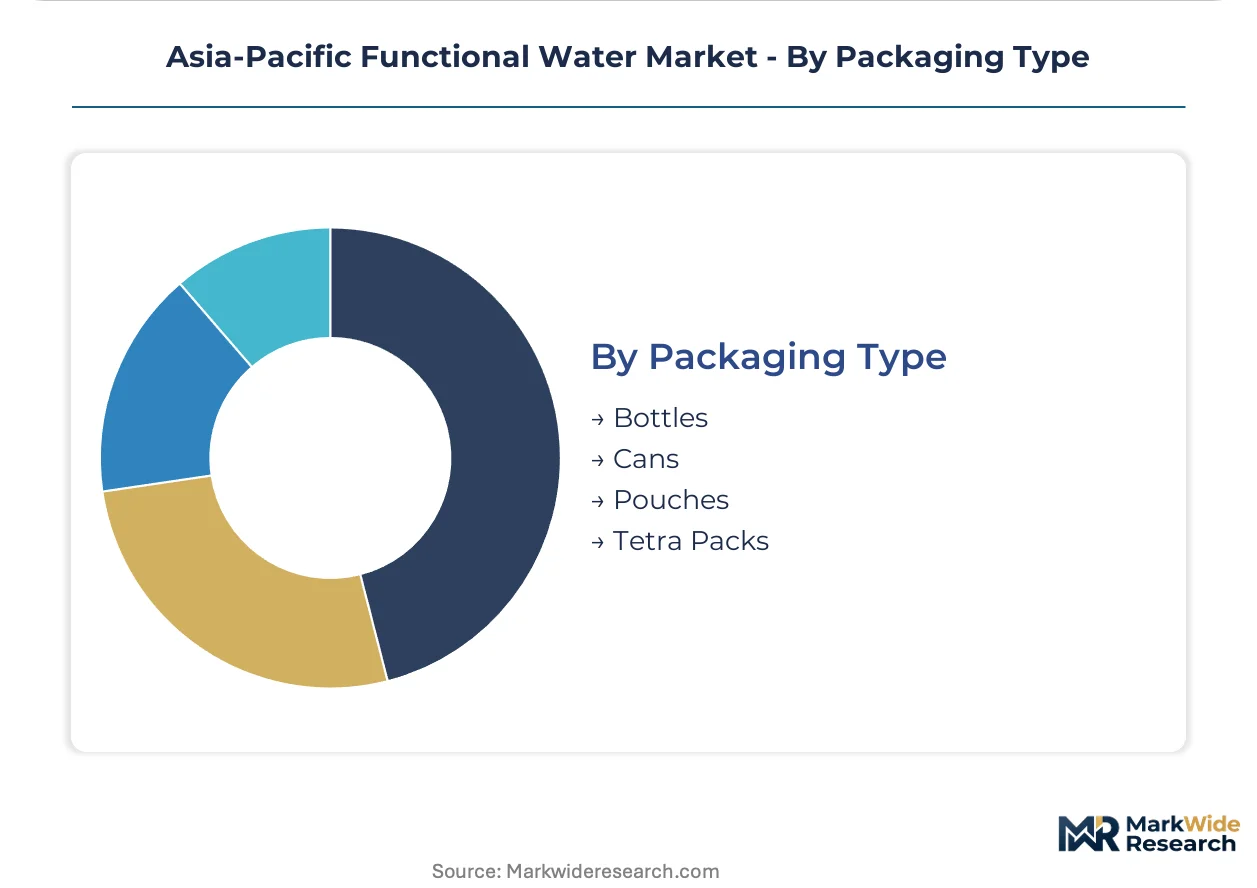
- Bottles:Dominant PET and glass formats supported by legacy filling infrastructure across China and Japan. China's MEE environmental targets and carbon neutrality mandates pressure manufacturers toward lightweighting and recycled content integration.
- Tetra Packs:Aseptic carton formats gaining traction in India's price-sensitive urban markets. Adoption requires reconfiguration of ambient supply chains historically dominated by glass and PET.
- Pouches:Flexible format adoption exposing manufacturers to polymer supply fluctuations in South Asian markets.
- Cans:Aluminum beverage can formats with established recycling loops in developed East Asian markets.
Bottles retain structural dominance. Tetra Packs represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints across Asia-Pacific functional water, as manufacturers relocate bottling capacity toward jurisdictions with streamlined additive approval pathways and lower certification burdens for fortified variants.
China
Urban fitness communities in Beijing, Shanghai, and Shenzhen are absorbing electrolyte-fortified volumes at accelerated rates, while SAMR disclosure mandates force reformulation investments. China's MEE carbon neutrality targets pressure bottlers toward lightweight PET and recycled content integration. The Yangtze River Delta anchors premium mineral water extraction and aseptic filling infrastructure expansion.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas pay premiums for source-authenticated mineral variants and metabolic support formulations. METI and the Consumer Affairs Agency enforce 12-18 month clinical dossier reviews for qualified health claims, creating barrier-to-entry effects. The Kansai region concentrates traditional medicine-positioned herbal infusion R&D and precision osmolality engineering capabilities.
India
Mumbai-Delhi corridor gym penetration and marathon culture are driving electrolyte water demand among urban exercise communities. FSSAI harmonization with Codex Alimentarius elevates import compliance costs for cross-border e-commerce entrants. Tetra pack and pouch format adoption accelerates in Bangalore and Hyderabad's price-sensitive urban markets, requiring ambient supply chain reconfiguration.
South Korea
Seoul's fitness beverage manufacturers deploy isotonic and hypotonic formulations with wearable biometric integration for personalized hydration recommendations. MFDS natural source certification requirements impose capital-intensive spring access protocols on new mineral water entrants. The Busan-Ulsan industrial corridor supports aseptic bottling technology and sustainable packaging material innovation.
Vietnam
Ho Chi Minh City and Hanoi urban millennials discover vitamin-fortified variants through social commerce platforms before supermarket availability. Underserviced convenience store networks create whitespace for electrolyte water penetration by channel-savvy entrants. The country's central coast region attracts bottling infrastructure investment targeting ASEAN export compliance.
Asia-Pacific Functional Water Market Competitive Environment
Chinese producers anchor one tier with domestic distribution density and deep well-spring access; Japanese specialists hold formulation leadership in precision hydration engineering. The market structure fragments across four competitive tiers: multinational beverage conglomerates with channel control, regional mineral water purveyors with source certification, functional formulation specialists, and private-label entrants exploiting e-commerce discovery patterns. Dominant competitive moves include portfolio diversification into metabolic support variants and strategic partnerships with fitness platform operators for biometric-informed consumption recommendations.
Within the multinational tier, The Coca-Cola Company and PepsiCo, Inc. occupy positions defined by convenience store and supermarket channel dominance across Southeast Asian growth corridors. Among Asia-Pacific specialists, Suntory Beverage & Food Limited and Nongfu Spring Co., Ltd. exemplify divergent archetypes—Japanese precision formulation leadership versus Chinese domestic distribution scale. Danone SA and Nestle SA represent European-headquartered players navigating regional regulatory complexity through localized sourcing partnerships.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo, Inc. |
| Danone SA |
| Nestle SA |
| Suntory Beverage & Food Limited |
| Nongfu Spring Co., Ltd. |
| Hangzhou Wahaha Group Co., Ltd. |
| Veda Beverages Private Limited |
| BODIEZ |
| Others |
Value Chain & Pricing Dynamics
Aseptic filling technology adoption across China's Yangtze River Delta and India's Maharashtra corridor is simultaneously compressing per-unit production costs and concentrating supply ownership among bottlers with capital-scale sterilization infrastructure. This technology shift rewards incumbents with legacy PET capacity while forcing price discipline on new entrants facing amortization pressure from imported European filling lines.
Pricing Analysis
Distributor margin layers in Southeast Asian convenience channels absorb 18-25 points before retail markup, compressing manufacturer net realization. Three-tier pricing structure across premium, standard, and economy levels separates source-certified mineral variants from fortified functional waters and private-label hydration. Pricing pressure stems from polymer input volatility affecting pouch and tetra pack formats in Indian urban markets. Casual drinkers in Vietnam and Indonesia exhibit highest price sensitivity, while Japan's aging demographic absorbs premiums for metabolic support formulations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese PET resin production and South Korean aseptic packaging film supply. Concentrated extraction rights in Japan's Kansai region and South Korea's Gangwon province restrict premium mineral water feedstock availability. Raw material dependencies include food-grade PET, aluminum can sheet, and aseptic carton board. Tariff exposure runs through ASEAN cross-border e-commerce channels serving Thai and Vietnamese millennial discovery patterns. Distribution runs through PepsiCo-controlled convenience networks in Southeast Asian growth corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific functional water has entered late-cycle quality phase as urban fitness communities in Beijing, Shanghai, and Mumbai pivot toward osmolality-optimized recovery formulations over commodity hydration. This demand shift toward premium specifications rewards clinical substantiation investments and source-authenticated positioning.
For Market Incumbents: Anchor mineral water portfolios through exclusive spring access negotiations in Japan's Kansai and South Korea's Gangwon regions before extraction permit scarcity hardens. Accelerate backward integration into food-grade PET recycling infrastructure to meet China's MEE carbon neutrality mandates and neutralize polymer cost volatility threatening pouch format margins.
For New Entrants and Emerging Players: Enter via Vietnam's underserviced convenience store networks where channel control remains fragmented and electrolyte water penetration lags Chinese tier-one saturation. Target Ho Chi Minh City and Hanoi's urban millennials through social commerce discovery preceding brick-and-mortar negotiations, leveraging cross-border e-commerce regulatory gaps before FSSAI-equivalent harmonization closes arbitrage windows.
For Investors and Strategic Acquirers: Roll-up economics work for regional mineral water purveyors with source certification because Japan's METI clinical dossier requirements and China's SAMR additive disclosure mandates create barrier-to-entry effects that protect acquired cash flows. Monitor wearable biometric integration adoption rates among Seoul fitness manufacturers as inflection indicator for precision hydration category viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Spring Source Certification Investment | Japan's METI requirements and South Korea's MFDS protocols create defensible supply moats for certified extractors. |
| Aseptic Filling Capacity Expansion | China's Yangtze River Delta bottlers gain cost advantage over imported European line competitors. |
| Biometric Platform Partnership | Seoul fitness app integrations enable personalized osmolality recommendations for recovery-optimized consumption. |
| Tetra Pack Format Adoption | India's FSSAI-harmonized import rules favor domestic aseptic carton supply chain reconfiguration. |
| Social Commerce Channel Launch | Thailand and Vietnam's urban millennials discover vitamin-fortified variants before supermarket availability. |
Study Parameters
Coverage spans China, Japan, India, South Korea, and Vietnam, with primary inputs from each market's bottling executives, regulatory affairs leads at SAMR and METI, convenience store category buyers, and fitness platform operators. Secondary validation drew from customs records, FSSAI harmonization filings, SEC beverage division disclosures, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Rate-of-change decomposition separated volume growth drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product formulation type, end-user fitness intensity, distribution channel structure, and packaging format compliance with regional environmental mandates. CAGRs derived from weighted average of historical trajectory and regulatory-adjusted penetration curves. Forecast inputs incorporated SAMR disclosure timeline delays and METI clinical dossier review durations.
Inputs from bottler capacity announcements and regulatory filing databases were available through the study window; gaps in private-label e-commerce transaction data introduce uncertainty bands around cross-border channel estimates. Forecasts reflect documented assumptions regarding fitness community expansion rates and polymer supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Functional Chewing Gums Market