
 Microparticulated Egg White Protein Market | 2026-2036
Microparticulated Egg White Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Microparticulated Egg White Protein Market Insights
The capital-intensity gap between integrated egg processors and ingredient traders is collapsing as spray-drying and microparticulation equipment costs fall. Rembrandt Foods leverages captive egg supply from Iowa and Minnesota farms to control raw material flow. Michael Foods anchors institutional channel relationships through its prepared-egg distribution network. Glanbia Nutritionals differentiates via nutritional science partnerships with sports brands seeking amino acid optimization.
Microparticulated egg white protein denotes egg albumen processed through controlled thermal or enzymatic treatment to reduce particle size below 50 microns, yielding enhanced emulsification, foaming stability, and water-binding capacity for industrial food systems. The isolate segment leads value capture due to higher protein purity and premium pricing in clinical nutrition applications, while hydrolysate variants are gaining fastest in post-workout formulations where rapid amino acid absorption is prioritized. Sports nutrition dominates volume offtake as protein fortification spreads from powders into ready-to-drink beverages and bars, with dairy alternatives emerging as a structural growth pocket where egg white replaces dairy-derived foaming agents in plant-based whipped products.
FDA GRAS status and USDA organic certification govern US market access for egg-derived ingredients, while EFSA novel food assessments and EU hygiene regulations shape European commercialization pathways. Japan's Food Sanitation Act and positive list system for food additives create additional compliance layers for imported microparticulated proteins. Stakeholders must monitor evolving allergen labeling mandates and alternative protein taxonomies that could reclassify egg white ingredients in blended formulations.
Market Dynamics
Enzymatic processing technologies are compressing production costs for microparticulated egg white protein, eroding the historical capital barrier that protected integrated processors and forcing ingredient traders to acquire spray-drying capabilities or exit.
Growth Catalysts
- Clean-label mandates:EFSA novel food assessments and EU hygiene regulations are accelerating substitution of synthetic emulsifiers with egg-derived alternatives in European functional food formulations.
- Sports nutrition fortification:Protein enrichment is spreading from powders into ready-to-drink beverages and bars, pulling volume demand for microparticulated isolates with superior amino acid profiles.
- Plant-based dairy expansion:Egg white proteins are replacing dairy-derived foaming agents in whipped plant-based creams and desserts, opening structural growth in dairy alternatives.
Market Restraints
- Feed cost volatility:Corn and soybean meal prices drive raw egg cost swings, compressing margins for processors without captive layer farms.
- Allergen labeling complexity:Japan's Food Sanitation Act and positive list system for food additives create compliance layers that delay import commercialization.
- Enzyme supply concentration:Protease suppliers cluster in Denmark and the Netherlands, creating input bottlenecks for hydrolysate production.
Strategic Opportunities
- Clinical nutrition penetration:Higher-purity isolates command premium pricing in medical foods and enteral nutrition, a segment underdeveloped relative to sports applications.
- Enzyme-thermal hybrid processing:Converging enzymatic hydrolysis with controlled thermal microparticulation yields novel texture profiles for confectionery and bakery.
- Direct-to-manufacturer platforms:Digital procurement channels are disintermediating traditional ingredient distributors for mid-size functional food brands.
Industry Challenges
- Process engineer scarcity:Specialized expertise in spray-drying parameter optimization for heat-sensitive proteins commands premium compensation and limits capacity expansion.
- GRAS self-determination risks:FDA enforcement discretion on novel enzymatic treatments creates regulatory uncertainty that delays customer adoption.
- Legacy equipment retrofit costs:Existing egg powder facilities require substantial capex to add microparticulation capabilities without compromising throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microparticulated Egg White Protein Market |
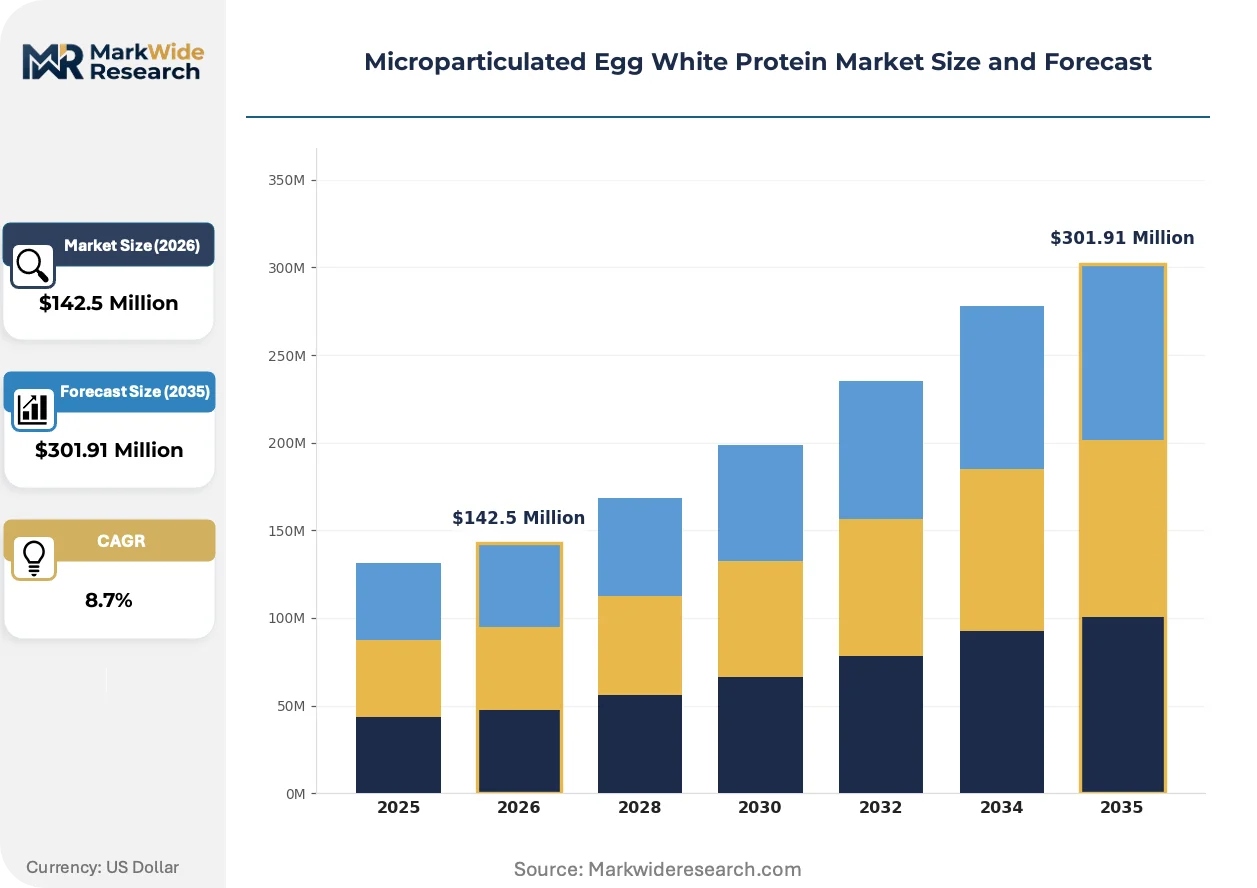
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Powder Application: Sports Nutrition, Dairy Alternatives, Baked Goods, Meat Products End User: Food Manufacturers, Nutritional Supplement Companies, Health Food Stores, Restaurants Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Rembrandt Foods, Michael Foods, Fonterra, Arla Foods Ingredients, CP Kelco, Glanbia Nutritionals, Ingredion Incorporated, Groupe Limagne, Kewpie Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microparticulated Egg White Protein Market Trends and Innovations
Processing technology convergence and regulatory reclassification of egg-derived ingredients are redrawing competitive boundaries between integrated processors, ingredient specialists, and enzymology houses.
Low-temperature enzymatic hydrolysis is decomposing the traditional trade-off between protein functionality and nutritional integrity. Sports nutrition formulators in the United States are adopting these variants at accelerating pace for post-workout applications. This shift is compressing demand for standard heat-treated isolates in premium formulations while expanding addressable volume in rapid-absorption segments.
EFSA novel food assessments are tightening evidentiary requirements for enzymatically modified egg proteins entering European commerce. Manufacturers must now submit comprehensive toxicology and allergenicity data before market authorization. German and Dutch ingredient houses are responding by front-loading clinical validation investments to secure first-mover positioning under evolving EU hygiene regulations.
Functional food brands are consolidating supplier relationships around processors offering bundled certification packages spanning USDA organic, FDA GRAS, and EU organic equivalency. This behavior concentrates procurement among integrated players with in-house regulatory affairs capabilities. The pattern is most visible in North American supply chains, where clean-label commitments from CPG brands demand multi-jurisdiction compliance documentation.
Microparticulated Egg White Protein Market Segmentation
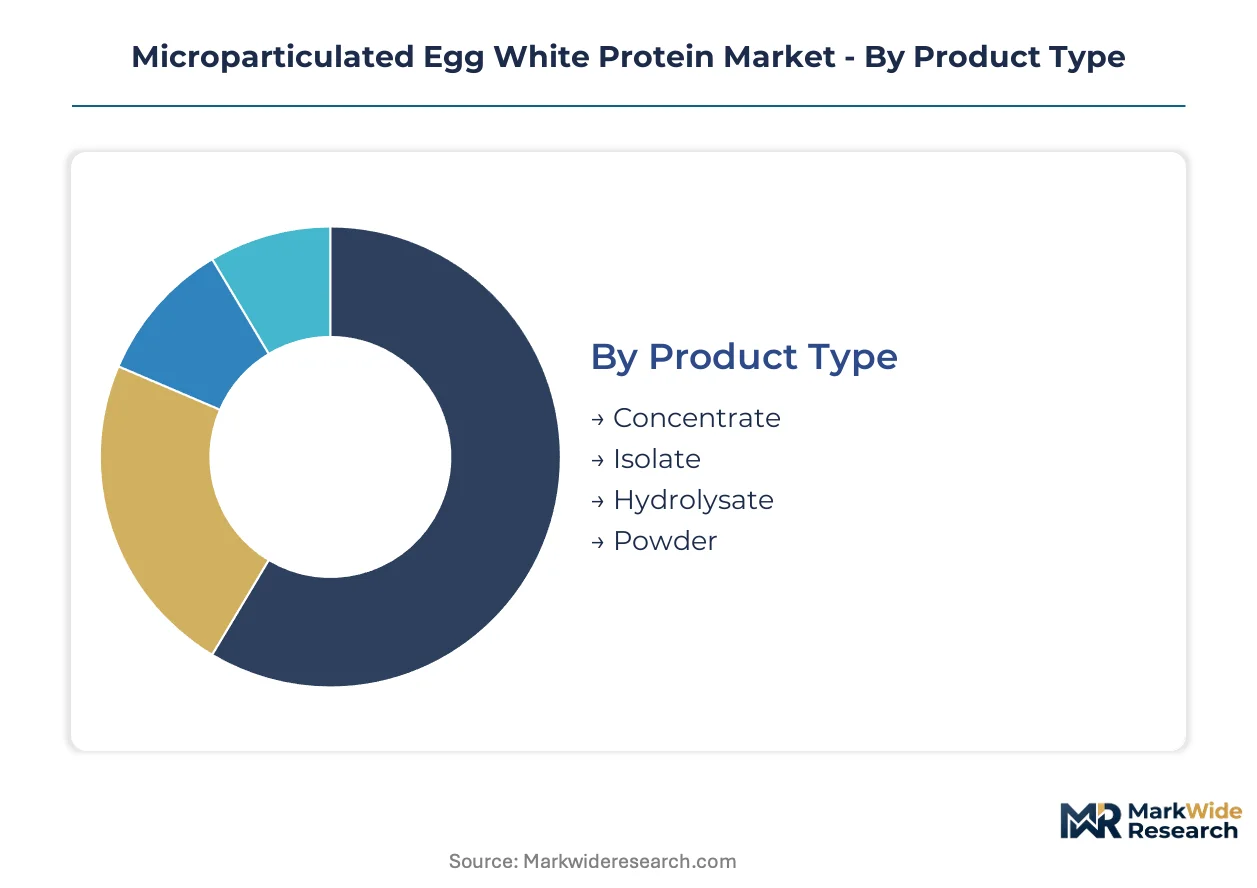
Microparticulated egg white protein serves divergent functional requirements across nutrition, bakery, and alternative dairy systems. Segmentation reveals where formulation premiums concentrate and which purity grades command procurement priority.
Product Type:
Margin pools concentrate in higher-purity grades where clinical and performance nutrition specifications justify price premiums.
- Isolate:Delivers protein purity above 90% with minimal lipid and carbohydrate contamination. Sports nutrition brands in the United States specify isolates for amino acid-optimized powders where leucine content drives formulation decisions. EFSA novel food assessments and USDA organic certification requirements filter supplier eligibility, concentrating procurement among integrated processors with captive regulatory affairs capabilities.
- Hydrolysate:Pre-digested through enzymatic hydrolysis into peptide fractions under 10 kilodaltons for rapid gastric emptying. Post-workout beverage formulators prioritize hydrolysates where absorption velocity outweighs taste compromise. Protease supply concentration in Denmark and the Netherlands creates input bottlenecks that constrain capacity expansion for hydrolysate-dominant processors.
- Concentrate:Retains native protein structure with 70-85% purity and functional foaming properties intact. Cost-sensitive bakery applications specify concentrates where emulsification performance matters more than protein density per serving.
- Powder:Standard spray-dried egg albumen without microparticulation treatment serves commodity foodservice channels. Institutional egg replacement applications absorb volume where texture specifications tolerate larger particle distributions.
The dominant share belongs to Isolate, while Hydrolysate is closing the gap fastest.
Application:
Volume concentration tracks protein fortification expansion beyond legacy powder formats into beverage and bar matrices.
- Sports Nutrition:Protein powders, ready-to-drink beverages, and nutrition bars incorporate microparticulated isolates for solubility and mouthfeel control. Formulators in Germany and Japan are expanding procurement as amino acid profiling becomes standard specification. FDA GRAS self-determination requirements create adoption friction for novel enzymatic variants that delay customer trials.
- Dairy Alternatives:Plant-based whipped creams and desserts substitute egg white proteins for dairy-derived foaming agents. Japanese functional food manufacturers lead adoption where clean-label positioning commands retail price premiums. The structural growth pocket sits in oat and coconut-based dessert systems where foam stability determines product acceptance.
- Baked Goods:Angel food cakes, meringues, and macarons leverage microparticulated egg white for aeration and crumb structure. Artisan and industrial bakeries specify particle size distributions below 50 microns for consistent volume yield.
- Meat Products:Surimi, poultry injections, and restructured meats utilize water-binding capacity for yield enhancement and texture modification. Processors without captive layer farms face margin compression when feed cost volatility spikes.
Sports Nutrition retains the largest volume position, though Dairy Alternatives is expanding most quickly.
End User:
Procurement sophistication varies sharply between formulation-science-driven buyers and distribution-focused intermediaries.
- Food Manufacturers:Industrial bakeries, confectionery houses, and prepared-food processors specify functional performance metrics including foam overrun and gel strength. Direct technical service relationships with ingredient suppliers determine contract renewal rates.
- Nutritional Supplement Companies:Sports nutrition and clinical nutrition brands conduct amino acid assay validation and allergen threshold testing. These buyers consolidate supplier relationships around processors offering bundled USDA organic, FDA GRAS, and EU organic equivalency documentation.
- Health Food Stores:Private-label and branded supplement retailers stock consumer-packaged egg white protein with clean-label positioning. SKU proliferation in this channel pressures inventory turns and supplier minimum order quantities.
- Restaurants:Foodservice operators utilize liquid and powdered egg white for menu items requiring stable foam or protein enrichment. Operational simplicity favors pre-hydrated formats over powder requiring reconstitution protocols.
Food Manufacturers command the dominant procurement volume, while Nutritional Supplement Companies are climbing the fastest.
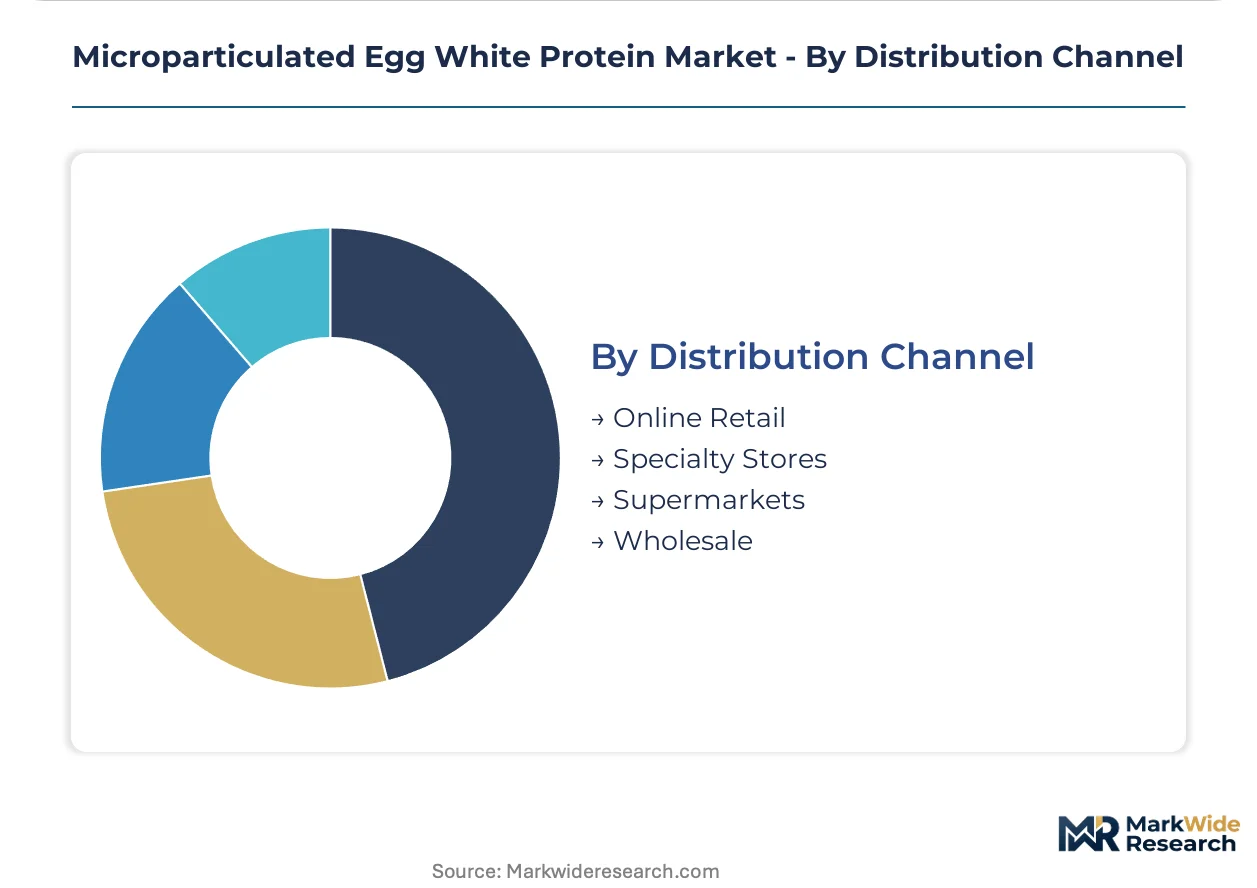
Distribution Channel:
Channel economics reflect handling requirements for temperature-sensitive and allergen-classified ingredients.
- Wholesale:Ingredient distributors aggregate volume from multiple processors for mid-size food manufacturers lacking direct procurement scale. Margin compression in this channel accelerates disintermediation as digital platforms enable manufacturer-direct relationships.
- Online Retail:E-commerce platforms serve small-batch formulators and regional supplement brands with lower minimum order thresholds. Specialty microparticulated grades with organic or enzymatic differentiation command price premiums in this channel.
- Specialty Stores:Nutrition and baking supply retailers stock consumer-packaged formats with formulation guidance and technical support. Staff expertise influences brand selection for hobbyist and small commercial bakers.
- Supermarkets:Mass retail placement requires national distribution infrastructure and slotting fee capacity accessible only to integrated processors with prepared-egg network leverage.
Wholesale maintains the dominant position, while Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German and Japanese buyers absorb premiums for enzymatic hydrolysates with rapid absorption profiles. United States procurement concentrates on cost-efficient isolates for mass-market sports nutrition. Brazilian and Indian markets remain underdeveloped due to import tariff structures and limited local spray-drying infrastructure.
United States
Sports nutrition brands drive volume procurement of microparticulated isolates for amino acid-optimized powders. FDA GRAS self-determination requirements create adoption friction for novel enzymatic variants that delay customer trials. Iowa and Minnesota host integrated egg processors with captive layer farm networks controlling raw material flow.
Germany
Clean-label mandates from EFSA novel food assessments accelerate substitution of synthetic emulsifiers with egg-derived alternatives. EU hygiene regulations filter supplier eligibility, concentrating procurement among processors with bundled organic certification packages. Bavarian ingredient houses front-load clinical validation investments to secure first-mover positioning.
Japan
Functional food manufacturers lead adoption of egg white proteins in plant-based whipped creams where clean-label positioning commands retail premiums. The Food Sanitation Act and positive list system for food additives create compliance layers that delay import commercialization. Tokyo-based formulators specify particle size distributions below 50 microns for consistent foam stability in dessert applications.
Netherlands
Protease supply concentration creates input bottlenecks for hydrolysate production, with enzyme suppliers clustering in Danish and Dutch biotechnology corridors. REACH compliance documentation requirements shape procurement relationships for sports nutrition brands seeking rapid-absorption formulations. Rotterdam serves as the primary distribution hub for egg-derived ingredients entering European commerce.
Brazil
Feed cost volatility from corn and soybean price swings compresses margins for processors without captive supply chains. Import tariff structures on specialized food ingredients limit penetration of premium microparticulated grades. São Paulo-based food manufacturers rely on commodity egg powder for cost-sensitive bakery applications.
Microparticulated Egg White Protein Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. Integrated processors with captive egg supply dominate cost-efficient isolate production, while enzymology houses command premium positioning in hydrolysate segments. The market structure reflects a tiered competitive map with three strategic archetypes: vertically integrated egg processors, specialized ingredient traders acquiring spray-drying capabilities, and nutrition science partners serving sports brands. Dominant competitive moves include backward integration into layer farm operations and strategic partnerships for amino acid optimization research.
Among North American integrated processors, Rembrandt Foods and Michael Foods occupy positions anchored by captive supply networks across Midwest agricultural corridors. Glanbia Nutritionals represents the nutrition science partnership archetype, sitting within the premium-tier vector where amino acid profiling drives procurement decisions. These three companies exemplify how geographic concentration of egg production and regulatory affairs capabilities determine competitive positioning in multi-jurisdiction markets.
| Leading Market Players |
|---|
| Rembrandt Foods |
| Michael Foods |
| Fonterra |
| Arla Foods Ingredients |
| CP Kelco |
| Glanbia Nutritionals |
| Ingredion Incorporated |
| Groupe Limagne |
| Kewpie Corporation |
| Others |
Pricing and Supply Chain Analysis
USDA organic certification and FDA GRAS status operate as dual gates that simultaneously filter supplier eligibility and stratify price premiums across procurement tiers. Buyers seeking bundled multi-jurisdiction documentation absorb substantial markups over commodity egg powder, while processors lacking captive regulatory affairs capabilities face exclusion from premium contract pools.
Pricing Analysis
Technical service contracts and amino acid assay validation drive lifetime value for nutritional supplement buyers. Three-tier pricing structure across premium, standard, and economy levels separates enzymatic hydrolysates with rapid absorption profiles from heat-treated isolates and commodity concentrates. Pricing pressure stems from feed cost volatility in corn and soybean markets, compressing margins for processors without captive layer farms. Clinical nutrition brands exhibit lowest price sensitivity due to medical food reimbursement structures, while institutional bakery channels prioritize cost-efficient concentrates.
Supply Chain Analysis
The United States and Germany anchor integrated egg processing with captive layer farm networks and bundled certification capabilities. Denmark and the Netherlands feed protease enzymes for hydrolysate production, while Japan and the Netherlands handle distribution hub functions for Asian and European commerce. Raw material flows draw from Iowa and Minnesota agricultural corridors, Rotterdam port infrastructure, and Danish biotechnology enzyme clusters. Single-source vulnerability concentrates in protease supply, where two countries control enzymatic input for rapid-absorption formulations. Distribution runs through wholesale ingredient distributors facing disintermediation pressure from digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microparticulated egg white protein sits in early-cycle expansion as sports nutrition fortification spreads from legacy powders into beverage and bar matrices, pulling volume demand through reformulation cycles.
For Market Incumbents: Shield market position by deepening backward integration into Iowa and Minnesota layer farm operations to neutralize feed cost volatility. Prioritize in-house regulatory affairs capabilities spanning USDA organic, FDA GRAS, and EU organic equivalency to defend against emerging ingredient traders acquiring spray-drying equipment. For New Entrants and Emerging Players: Anchor in clinical nutrition penetration where higher-purity isolates command premium pricing and supplier consolidation remains underdeveloped relative to saturated sports applications. Target direct-to-manufacturer digital procurement channels for mid-size functional food brands seeking technical service relationships outside legacy distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underutilized egg processing assets and dormant regulatory filings. Long-term viability hinges on enzymatic processing technology ownership and multi-jurisdiction certification infrastructure. Watch for inflection signals in EFSA novel food assessment timelines that could accelerate or delay European market access for hydrolysate variants.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme-Thermal Hybrid Processing Investment | Converging technologies yield novel texture profiles for confectionery and bakery applications. |
| Captive Layer Farm Acquisition | Backward integration into Iowa and Minnesota agricultural corridors neutralizes feed cost volatility exposure. |
| Clinical Validation Partnership | Front-loaded toxicology investments secure first-mover positioning under tightening EFSA novel food assessments. |
| Digital Procurement Platform Launch | Direct-to-manufacturer channels disintermediate wholesale distributors for mid-size functional food brands. |
| Multi-Jurisdiction Certification Bundle | USDA organic, FDA GRAS, and EU organic equivalency documentation concentrates procurement relationships. |
Research Methodology
A spread of perspectives from sports nutrition formulators, clinical nutrition procurement managers, egg processing plant engineers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA GRAS filings, EFSA novel food assessment databases, USDA organic certification records, and customs trade data for egg-derived ingredient flows. Bottom-up volume modeling triangulated against top-down value estimates across isolate, hydrolysate, concentrate, and powder grades.
Segmentation dimensions modeled include product purity tier, application matrix, end-user procurement sophistication, and distribution channel structure across the analysis window. CAGRs derived from trajectory fitting to historical volume patterns and elasticity assumptions around protein fortification adoption. Forecast inputs incorporated spray-drying capacity expansion timelines, enzymatic processing technology diffusion curves, and regulatory assessment pipeline visibility.
Underlying assumptions cover sports nutrition formulation stability, protease enzyme supply continuity, and clean-label regulatory enforcement intensity, with deviation risk concentrated in feed commodity price swings and allergen labeling mandate revisions. Recalibration cycles align with material shifts in EFSA assessment timelines, FDA enforcement discretion patterns, and enzymatic processing equipment cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Potato Fiber Market
Ingredients
Food Botanicals Market
Ingredients
European Brewing Enzymes Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Hops Derivative Market
Ingredients
Cognitive Ingredients Market
Ingredients
US Vegetable Oil Market
Ingredients
China Cane Sugar Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Functional Flours Market
Ingredients
Shortening Powder Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Cosmetic Ingredients Market
Ingredients
North America Soybean Oil Market
Ingredients
Vegan Baking Ingredients Market