
 North America Functional Beverage Market | 2026-2036
North America Functional Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Functional Beverage Market Analytics
Health-conscious consumers is collapsing the historical dominance of casual refreshment buyers across North America. PepsiCo Inc. leverages its Gatorade portfolio and direct-store-delivery infrastructure to sustain shelf presence in convenience channels. The Coca-Cola Company anchors its position through BodyArmor and Costa Coffee functional extensions, while Monster Beverage Corporation dominates energy drink specialization with sugar-free line expansions.
Functional beverages are non-alcoholic drinks fortified with bioactive ingredients such as vitamins, herbal extracts, amino acids, or probiotics to deliver targeted physiological benefits beyond basic hydration. Manufacturers employ cold-aseptic filling and high-pressure processing to preserve nutrient stability without thermal degradation. Energy drinks lead volume contribution due to entrenched consumption rituals, though nutraceuticals represent the fastest-growing category as probiotic and adaptogenic formulations gain traction. E-commerce channels capture expanding margin pools through subscription models and direct-to-consumer personalization.
The FDA governs health claim substantiation and GRAS ingredient approvals, while the USDA Organic certification shapes premium positioning and pricing power. Health Canada and PMRA coordinate cross-border ingredient standards that influence formulation decisions for brands operating in both the United States and Canada. Stakeholders must monitor evolving positions on caffeine content limits and novel cannabinoid ingredient pathways across federal and provincial jurisdictions.
Market Dynamics
Clean-label ingredient innovation is forcing reformulation across North American functional beverage portfolios as FDA nutrition disclosure rules tighten and consumer scrutiny of synthetic additives intensifies. Cold-aseptic filling infrastructure expansion is compressing production timelines for probiotic and adaptogenic lines.
Growth Catalysts
- FDA GRAS pathway acceleration:Novel bioactive ingredient approvals are expanding permissible fortification claims for immunity and cognitive function products.
- California metro corridor premiumization:Health-conscious buyer density in Los Angeles and San Francisco sustains pricing power for organic-certified functional SKUs.
- Cold-aseptic filling adoption:High-pressure processing equipment deployment is preserving nutrient stability without thermal degradation in probiotic formulations.
Market Restraints
- Aluminum can input cost volatility:Beverage packaging material prices fluctuate with energy and bauxite supply chain pressures.
- Caffeine content regulatory friction:Health Canada and FDA coordinated scrutiny limits formulation flexibility for energy drink extensions.
- Supply concentration in corn-derived sweeteners:Midwest agricultural processing dominance creates single-source vulnerability for conventional functional beverage formulations.
Strategic Opportunities
- Texas and Florida underpenetration:Sun Belt population growth corridors offer whitespace for premium functional beverage distribution network expansion.
- Subscription e-commerce channel innovation:Direct-to-consumer personalization models capture recurring revenue pools outside traditional retail slotting.
- USDA Organic certification tailwind:Premium positioning through certified clean-label supply chains commands shelf price multiples in coastal metro markets.
Industry Challenges
- Formulation talent scarcity:Food science PhD recruitment competition with pharmaceutical and biotech sectors constrains R&D pipeline velocity.
- High-pressure processing capex intensity:Cold-aseptic line installation demands significant capital deployment with extended payback periods.
- Cross-border compliance complexity:Health Canada and PMRA ingredient standard coordination creates formulation versioning costs for US-Canada operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Functional Beverage Market |
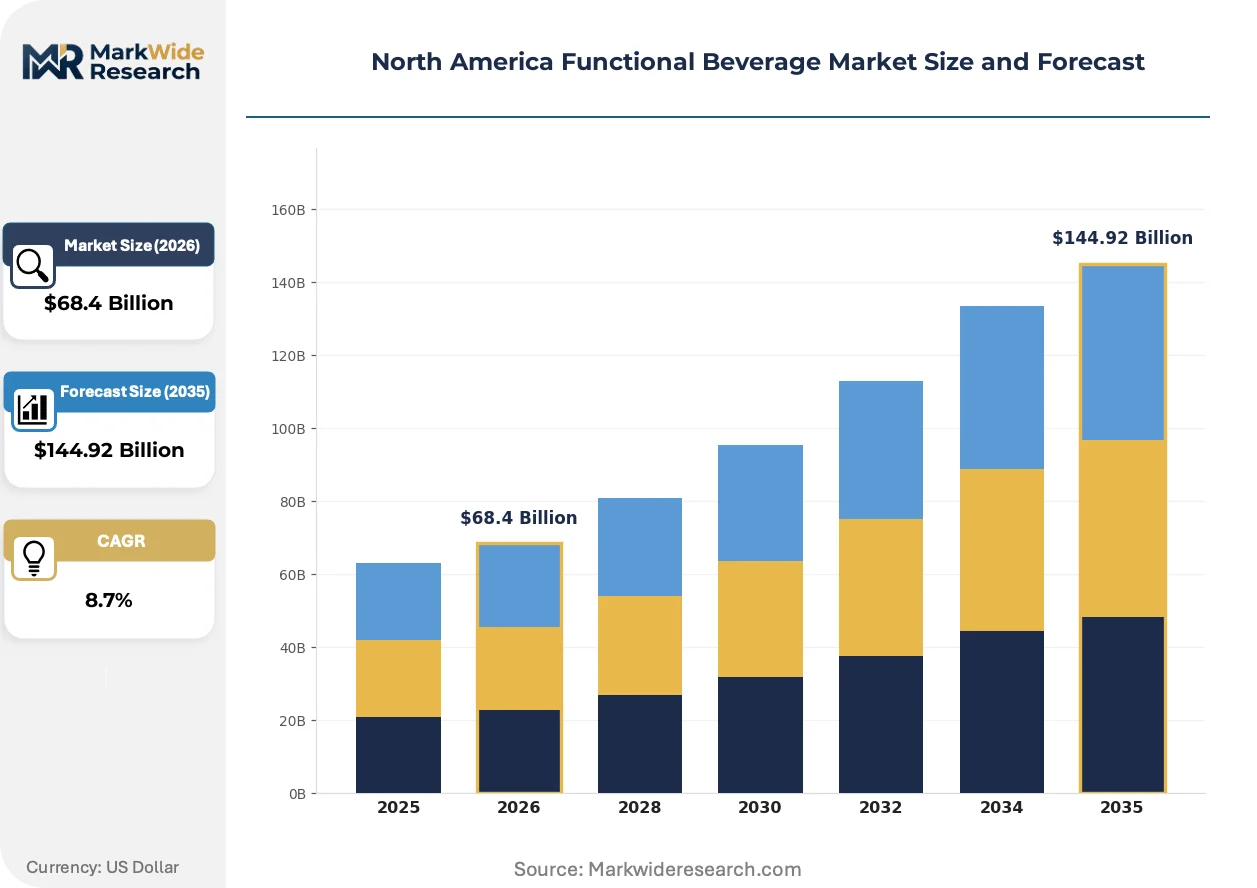
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Drinks, Energy Drinks, Nutraceuticals, Enhanced Water End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, Busy Professionals Distribution Channel: Supermarkets, Health Stores, E-commerce, Convenience Stores Ingredients: Vitamins, Herbal Extracts, Amino Acids, Probiotics |
| Companies Covered | PepsiCo Inc., The Coca-Cola Company, Monster Beverage Corporation, Danone S.A., Nestlé S.A., Red Bull GmbH, Keurig Dr Pepper Inc., Celsius Holdings Inc., Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Functional Beverage Market Evolving Landscape
Biotechnology-enabled ingredient sourcing is compressing development cycles for novel functional compounds. Regulatory disclosure requirements are tightening across federal and provincial jurisdictions. Channel fragmentation is redistributing margin capture away from conventional retail.
Precision fermentation for bioactive peptide production is miniaturizing manufacturing footprints for adaptogenic ingredient supply. Small-batch functional beverage startups in Brooklyn and Austin are adopting distributed production models. This technology is miniaturizing the economies of scale that historically advantaged mass-market brands with centralized processing infrastructure.
FDA updated Nutrition Facts labeling requirements are mandating added sugar disclosure granularity. Reformulation costs are accelerating across legacy functional portfolios with legacy sweetener systems. Energy drink and sports nutrition categories are responding with stevia and monk fruit substitution programs to maintain shelf positioning.
Direct-to-consumer subscription purchasing is displacing convenience channel impulse buying among health-conscious millennials. E-commerce platforms with personalization algorithms are capturing trial and repeat purchase cycles previously owned by grocery and gas station retail. This behavioral pivot concentrates most visibly in California and New York metro corridors where premium functional beverage penetration already runs deepest.
North America Functional Beverage Market Segmentation
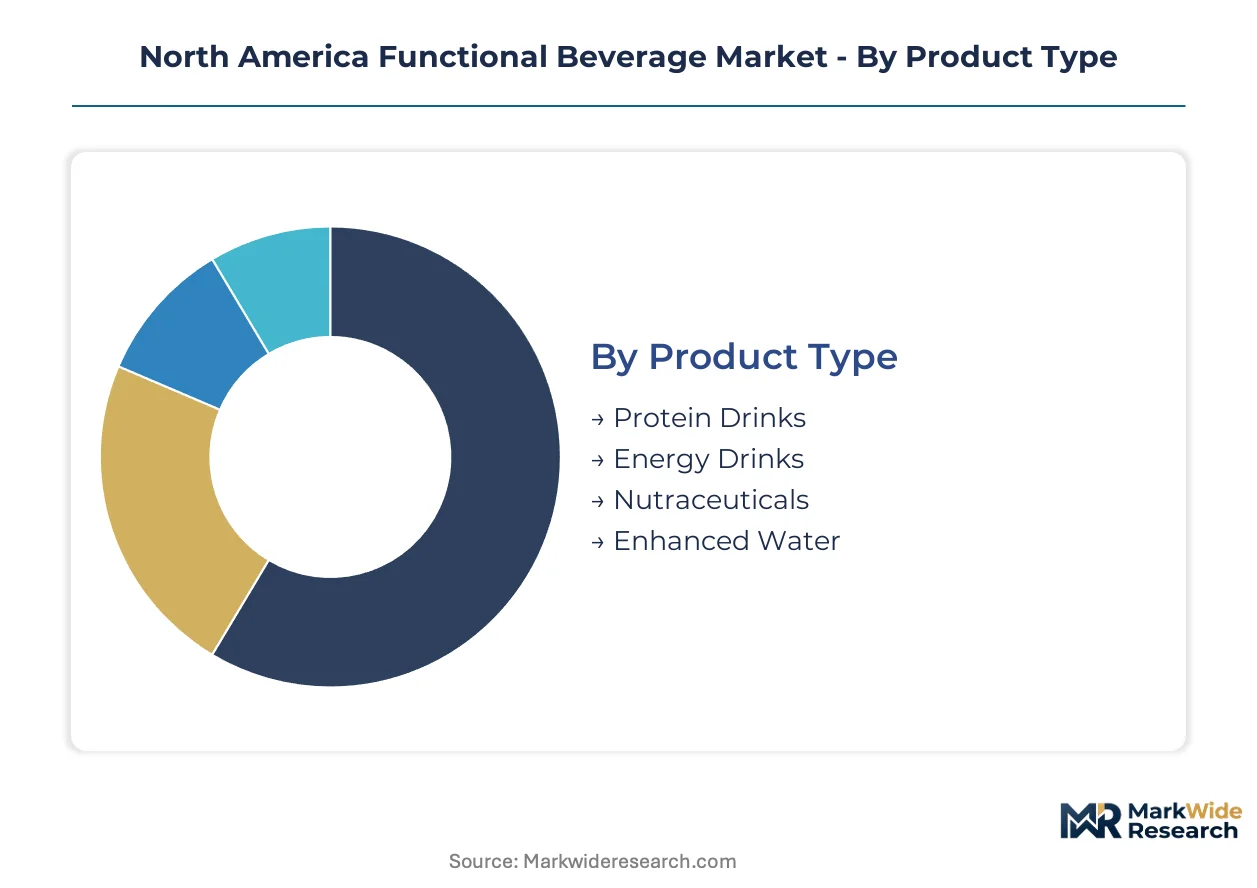
Segmentation reveals where substitution pressure concentrates most acutely. Energy drinks face erosion from nutraceutical alternatives, while distribution channels fragment as e-commerce captures recurring revenue pools from conventional retail.
Product Type:
Energy drinks confront the most intense substitution threat as consumers migrate toward cleaner-label alternatives with comparable functional benefits.
- Energy Drinks:Caffeine-forward formulations with taurine and B-vitamin matrices dominate convenience channel velocity. Fitness enthusiasts in Texas and Florida metro corridors sustain volume despite regulatory scrutiny on caffeine content limits from the FDA and Health Canada.
- Nutraceuticals:Probiotic, adaptogenic, and nootropic formulations deliver targeted physiological benefits through bioactive compounds. California and New York health-conscious buyer density commands premium shelf price multiples for organic-certified SKUs with cold-aseptic processing.
- Protein Drinks:Whey and plant-based protein isolates serve post-workout recovery rituals.
- Enhanced Water:Electrolyte and vitamin-fortified still or sparkling variants compete with conventional bottled water.
Energy drinks retain volume leadership; nutraceuticals hold the steepest expansion curve.
End User:
Cost tier stratification separates premium organic purchasers from mass-market conventional buyers across metropolitan corridors.
- Health-Conscious Consumers:Buyers prioritizing clean-label ingredient transparency and USDA Organic certification drive reformulation investment. Brooklyn and Austin small-batch startups target this segment with distributed precision fermentation production models.
- Fitness Enthusiasts:Gym-attached consumption rituals sustain protein drink and pre-workout energy demand. Los Angeles and San Francisco metro penetration runs deepest for premium functional SKUs with subscription e-commerce capture.
- Athletes:Competitive and recreational performers seeking performance-optimized hydration and recovery formulations.
- Busy Professionals:Time-constrained buyers favoring grab-and-go convenience with cognitive or energy support claims.
Health-conscious consumers command margin expansion; fitness enthusiasts anchor volume throughput.
Distribution Channel:
Channel margin capture is shifting as direct-to-consumer models displace traditional slotting fee structures.
- E-commerce:Subscription algorithms personalize trial and repeat cycles outside retail gatekeeper control. California and New York corridors concentrate this behavioral pivot among millennials abandoning impulse convenience purchases.
- Supermarkets:Mass-market volume concentration depends on trade promotion spending and shelf placement negotiation. Midwest agricultural processing corridors supply conventional formulations through established distributor relationships.
- Convenience Stores:Impulse-driven energy drink velocity faces erosion from channel-switching behavior.
- Health Stores:Specialty retailers curate premium and emerging brand access for ingredient-discerning buyers.
Supermarkets retain absolute volume; e-commerce climbs the fastest on margin capture.
Ingredients:
Supply concentration in corn-derived sweeteners creates formulation vulnerability as clean-label migration accelerates.
- Probiotics:Live culture stability demands cold-aseptic filling infrastructure with extended capital payback periods. High-pressure processing equipment deployment preserves viability without thermal degradation in premium coastal markets.
- Herbal Extracts:Adaptogenic botanicals from ashwagandha to ginseng require GRAS substantiation for health claim permissibility. FDA pathway acceleration for novel bioactives expands immunity and cognitive function positioning opportunities.
- Vitamins:Synthetic and natural-source B-complex, C, and D fortification faces added sugar disclosure pressure under updated Nutrition Facts labeling.
- Amino Acids:Branched-chain and essential amino acid fortification targets sports nutrition applications with established efficacy claims.
Probiotics gain share fastest on premium positioning; vitamins retain formulation ubiquity across mass-market portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles container complex underwrites California's dominance in functional beverage import velocity and cold-chain distribution reach across the Pacific corridor.
United States
Health-conscious buyer density in Los Angeles and San Francisco sustains premium pricing for organic-certified SKUs. FDA GRAS pathway acceleration expands permissible fortification claims for immunity and cognitive function products. Brooklyn and Austin startups deploy distributed precision fermentation models targeting clean-label demand.
Canada
Cross-border formulation versioning creates compliance costs for US-Canada operators serving Toronto and Vancouver metro corridors. Health Canada and PMRA coordinate caffeine content scrutiny that limits energy drink formulation flexibility. Montreal and Calgary distribution hubs concentrate cold-aseptic processing infrastructure for probiotic lines.
Mexico
Mexico City Metro and Monterrey manufacturing clusters supply corn-derived sweetener inputs for conventional functional beverage formulations. SAMR-aligned import standards influence GRAS substantiation requirements for US-exported nutraceuticals. Guadalajara corridor beverage processors expand high-pressure processing capacity for regional brands.
North America Functional Beverage Market Competitive Landscape
Concentration sits with multinational beverage conglomerates commanding direct-store-delivery infrastructure and shelf placement negotiation leverage. Tiered competition separates mass-market volume players from premium organic specialists and emerging precision fermentation startups. Dominant competitive moves include portfolio diversification into sugar-free line extensions and strategic partnerships with biotechnology ingredient suppliers.
Within the multinational tier, PepsiCo Inc., The Coca-Cola Company, and Monster Beverage Corporation exemplify scale-driven archetypes occupying positions across energy drink and sports nutrition categories. These entities anchor shelf presence through established distributor relationships while representing consolidation pressure on mid-tier regional brands.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| The Coca-Cola Company |
| Monster Beverage Corporation |
| Danone S.A. |
| Nestlé S.A. |
| Red Bull GmbH |
| Keurig Dr Pepper Inc. |
| Celsius Holdings Inc. |
| Glanbia plc |
| Others |
Value Network & Pricing Analysis
Centralized cold-aseptic filling capacity in California and New York metro corridors generates scale economies that compress unit costs for probiotic and adaptogenic lines while establishing regional price floors that smaller distributed producers in Texas and Florida cannot match without USDA Organic certification premiums.
Pricing Analysis
Volume-discount tiering structures separate mass-market conventional formulations from premium organic-certified SKUs and emerging precision fermentation startups. Three-tier pricing stratification across premium USDA Organic, standard clean-label, and economy conventional levels reflects certification grade and cold-aseptic processing investment. Pricing pressure intensifies in the standard tier as legacy brands reformulate away from corn-derived sweeteners under FDA added sugar disclosure rules. Health-conscious consumers in coastal metros exhibit lowest price sensitivity; mass-market buyers in Sun Belt corridors demonstrate highest elasticity.
Supply Chain Analysis
Inventory lead times for high-pressure processing equipment extend capital deployment cycles and constrain rapid capacity scaling for probiotic formulations. Supply concentration rests on Midwest agricultural processing for corn-derived sweeteners, Pacific Northwest botanical sourcing for adaptogenic extracts, and California cold-chain distribution infrastructure. Single-source vulnerability in aluminum can packaging exposes margins to energy and bauxite commodity volatility. Distribution runs through direct-store-delivery networks anchored by multinational beverage conglomerates, with e-commerce subscription models capturing recurring revenue outside traditional retail slotting structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characteristics define this market as health-conscious buyer archetypes displace casual refreshment consumption and FDA GRAS pathway acceleration opens novel bioactive ingredient positioning.
For Market Incumbents: Compound shelf presence through cold-aseptic line capacity additions in California and Texas corridors to defend against precision fermentation startup erosion. Secure backward integration into organic-certified botanical supply chains to lock in premium tier raw material access. Accelerate sugar-free line extensions using stevia and monk fruit substitution ahead of full FDA Nutrition Facts labeling enforcement.
For New Entrants and Emerging Players: Differentiate on distributed precision fermentation production models targeting Brooklyn and Austin health-conscious buyer density with small-batch adaptogenic formulations. Exploit underpenetrated whitespace in Florida and Texas metro corridors where premium functional beverage distribution networks remain sparse. Deploy direct-to-consumer subscription algorithms to bypass incumbent-controlled retail slotting gatekeepers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-enabled ingredient suppliers with GRAS-substantiated bioactive pipelines over conventional formulation houses. Long-term viability hinges on cold-aseptic processing infrastructure ownership and USDA Organic certification capabilities. Acquisition target archetypes include precision fermentation startups with validated adaptogenic peptide production and established Health Canada-PMRA cross-border compliance frameworks. Monitor FDA novel ingredient approval velocity as inflection indicator for premium tier expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Aseptic Line Expansion | High-pressure processing capacity in California preserves probiotic viability without thermal degradation. |
| USDA Organic Certification Investment | Clean-label supply chain validation commands shelf price multiples in Los Angeles and San Francisco metros. |
| Direct-to-Consumer Channel Launch | Subscription algorithms capture recurring revenue pools outside convenience store impulse purchasing. |
| Precision Fermentation Partnership | Biotechnology-enabled bioactive peptide sourcing compresses adaptogenic ingredient development cycles. |
| Sugar-Free Reformulation Program | Stevia and monk fruit substitution maintains shelf positioning under tightened FDA added sugar disclosure. |
Research Methodology
Initial hypotheses were tested against primary input from beverage brand managers, category buyers at supermarket and convenience chains, cold-chain logistics operators, and food science R&D directors, then refined through secondary validation against FDA GRAS notification filings, USDA Organic certification databases, Nielsen retail audit data, and SEC 10-K disclosures from publicly traded beverage conglomerates. Bottom-up volume modeling triangulated with top-down category spend analysis.
Variance-decomposition across the projection horizon isolates volume drivers by product type, end-user archetype, distribution channel, and ingredient technology tier. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic consumption indicators and regulatory timeline assumptions. Forecast inputs incorporated cold-aseptic infrastructure deployment schedules, FDA novel ingredient approval trajectories, and e-commerce subscription penetration curves.
Forecasts assume regulatory continuity in FDA nutrition labeling and Health Canada-PMRA caffeine content coordination; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Yeast Beta Glucan Market