
 Protein Crisps Market | 2026-2036
Protein Crisps Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Crisps Market Intelligence
Canadian investment in new pea protein processing facilities is tilting the raw material supply chain for protein crisps. This shift benefits companies like Post Holdings, Inc., which leverages its extensive distribution network to reach diet-conscious consumers across North America. General Mills Inc. competes by integrating protein-fortified snacks into its mainstream product lines, capitalizing on brand recognition. Meanwhile, Quest Nutrition specializes in formulations with very high protein content specifically targeting dedicated fitness enthusiasts.
Protein crisps are lightweight, texturized food ingredients produced through high-pressure extrusion of protein isolates or concentrates. These products function as inclusions in bars, cereals, and snacks to boost protein content and add a crunchy texture. While soy and whey protein sources remain foundational, pea protein represents the fastest-growing product type due to allergen concerns. The sports nutrition application commands a significant share, but the healthy snacking segment is expanding rapidly among mainstream consumers.
In the United States, the FDA's labeling regulations for protein content claims and allergen declarations directly influence product formulation. Similarly, the European Food Safety Authority (EFSA) scrutinizes novel food ingredients and health claims, affecting market access in the EU. Future success for manufacturers depends on navigating disparate international food safety standards while managing volatile raw material costs.
Market Dynamics
The fundamental market dynamic is the tension between the rising consumer demand for plant-based, allergen-free ingredients and the established, cost-effective supply chains for traditional soy and whey proteins. This conflict shapes formulation strategies, raw material procurement, and investment in new processing technologies.
Growth Catalysts
- Mainstream Snacking:The integration of protein crisps into everyday snacks, beyond niche sports nutrition, is expanding the consumer base, particularly among health-conscious urban populations in Germany and the United Kingdom.
- Extraction Technology:Advances in plant protein extraction and fractionation are improving the taste, texture, and functionality of crisps made from sources like peas and chickpeas, overcoming previous formulation barriers.
- Favorable Labeling Regulations:Food labeling rules, such as those from the FDA that permit prominent protein content claims, incentivize manufacturers to fortify products, making protein crisps a valuable inclusion ingredient.
Market Restraints
- Raw Material Volatility:Prices for protein isolates, especially for trending sources like pea protein, are subject to significant fluctuations based on crop yields, agricultural policy, and competing demand from other food sectors.
- Regulatory Scrutiny:Novel food ingredient regulations, particularly the European Food Safety Authority's (EFSA) stringent evaluation process, can create lengthy and costly barriers to market entry for new protein sources or processing methods.
- Texture and Flavor Challenges:High concentrations of certain plant-based proteins can impart undesirable "off-notes" or a gritty texture, posing a technical challenge that limits their application in delicately flavored products.
Strategic Opportunities
- Geographic Expansion:Untapped demand exists in Asia-Pacific and Latin American markets where a growing middle class is adopting Western-style snacking habits and seeking out functional food products.
- Geriatric Nutrition:Formulating protein crisps for inclusion in foods targeted at older adults represents a significant opportunity, addressing age-related muscle loss (sarcopenia) with texturally appropriate products.
- Savory Applications:Moving beyond sweet applications in bars and cereals, there is an opportunity to incorporate protein crisps into savory snacks, meal toppers like salad croutons, and soup inclusions.
Industry Challenges
- Compliance Across Borders:Manufacturers face the operational burden of reformulating and relabeling products to meet disparate international food safety standards and allergen declaration requirements between the EU, US, and other regions.
- Capital Investment:The high-pressure extrusion equipment required to produce high-quality, texturized protein crisps necessitates significant upfront capital expenditure, creating a barrier to entry for smaller firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Crisps Market |
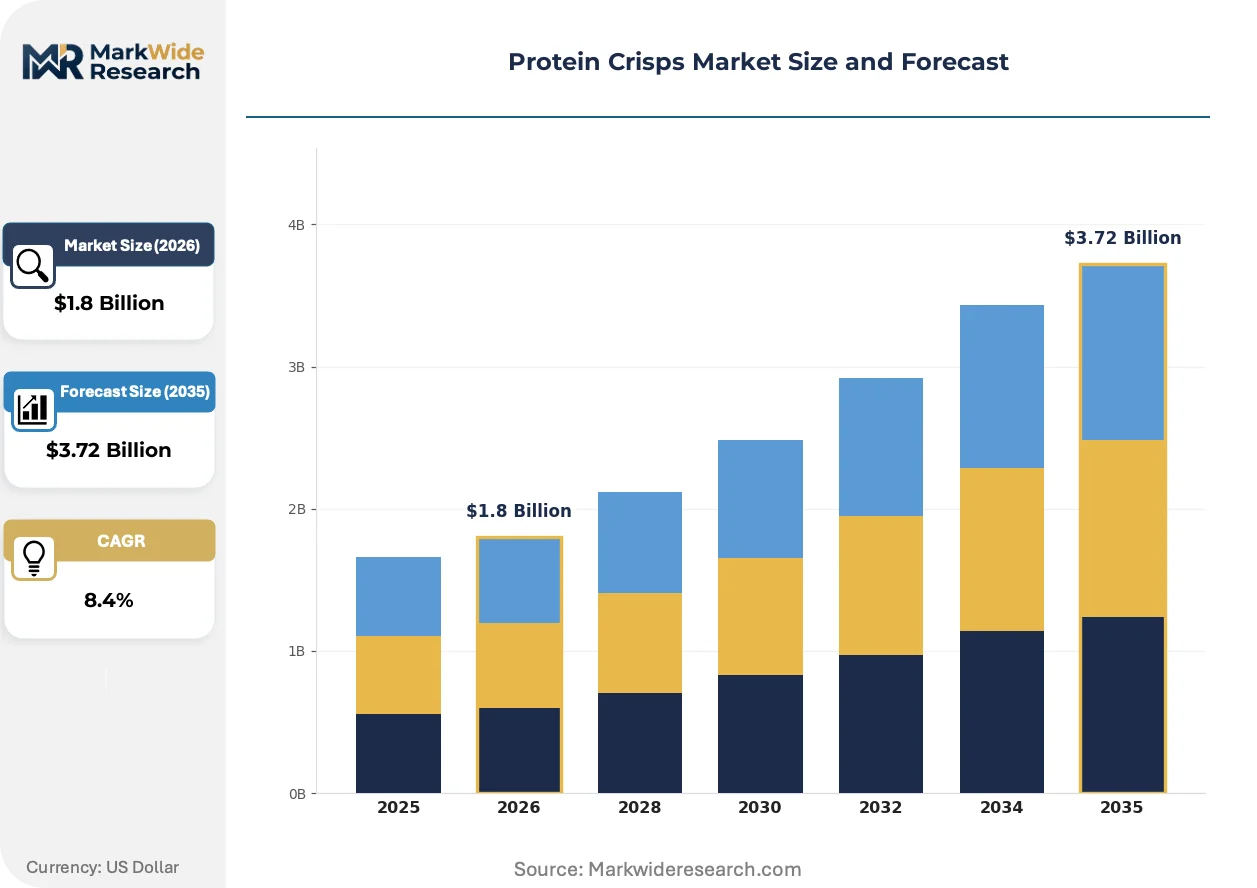
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Whey Protein, Soy Protein, Rice Protein, Almond Protein Application: Sports Nutrition, Weight Management, Healthy Snacking, Meal Replacement, Functional Foods End User: Fitness Enthusiasts, Diet-conscious Consumers, Outdoor Adventurers, Office Workers, Students Packaging Type: Stand-up Pouches, Resealable Bags, Flow Wraps, Boxes, Multi-pack Cartons |
| Companies Covered | Post Holdings, Inc., ProtiDiet, General Mills Inc., Premier Nutrition Company, LLC, Power Crunch, WK Kellogg Co, Quest Nutrition, MYPROTEIN (The Hut Group), PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Crisps Market Strategic Shifts & Innovations
Formulation science is advancing rapidly to meet dual consumer demands for both clean-label ingredients and specific, validated nutritional outcomes. This evolution is pushing manufacturers toward more sophisticated protein sources and processing methods that deliver on texture, taste, and function.
Advanced twin-screw extrusion technology allows for precise control over the shear, temperature, and pressure applied during crisp production. Food manufacturers in the bar, cereal, and snack sectors are adopting this equipment to create novel textures and shapes. This superior process control is rendering obsolete older single-screw extrusion methods, which offer limited flexibility in managing final product density and crunchiness.
The FDA's regulations governing protein content claims on food labels are influencing product development across the United States. These rules compel manufacturers to use high-quality protein sources to substantiate marketing claims, impacting sourcing and formulation costs. The sports nutrition and weight management segments are most affected, as brands must ensure their protein content and quality align with federal guidelines.
A notable behavioral change is the consumer pivot towards products making explicit claims about sourcing ethics and environmental impact. This disrupts the traditional procurement focus on pure cost and functionality, forcing ingredient buyers to consider factors like water usage and regenerative agriculture practices. This trend is most visible in the European market, especially for products targeting environmentally conscious millennials and Gen Z consumers.
Protein Crisps Market Segmentation
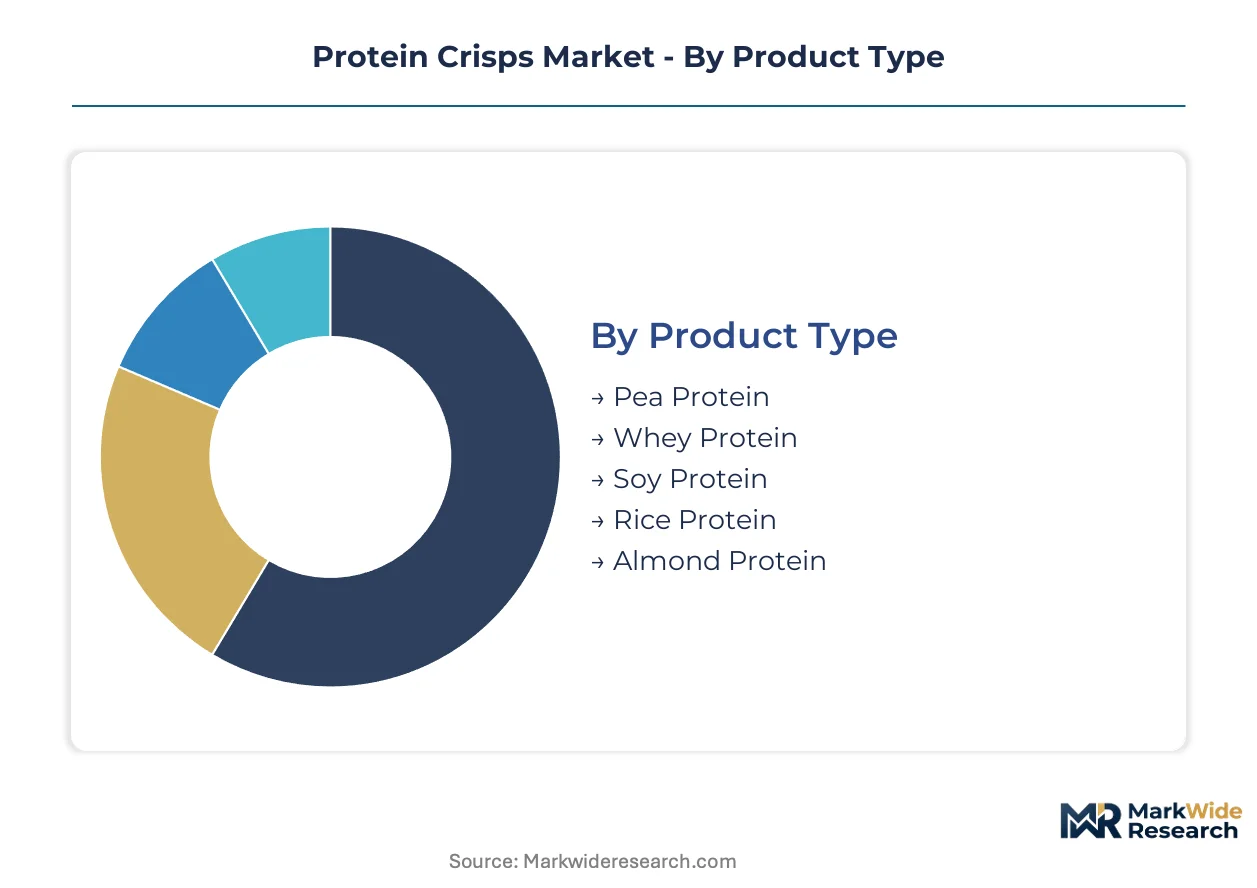
The Protein Crisps Market exhibits diverse segmentation across product types, applications, end-users, and packaging formats. Understanding these categories allows manufacturers to tailor product development and market strategies for specific consumer needs. Each segment reflects distinct preferences and purchasing behaviors within the broader functional food landscape.
Product Type:
The composition of protein crisps significantly influences their nutritional profile and suitability for various dietary requirements.
- Pea Protein:This plant-based protein isolate is gaining substantial market share due to its allergen-friendly nature and sustainable sourcing. Demand concentrates in European and North American markets as consumers actively seek non-dairy and gluten-free options.
- Whey Protein:Derived from milk, whey protein crisps provide a complete amino acid profile and are highly valued for muscle repair and growth. This type remains a foundational ingredient in sports nutrition products across the United States.
- Soy Protein:An economical and widely available plant-based option, soy protein crisps offer a versatile ingredient for various food applications. Its use is prevalent in general healthy snacking products globally.
- Rice Protein:This hypoallergenic plant protein source caters to consumers with multiple food sensitivities. Rice protein crisps find application in specialized dietary products.
- Almond Protein:Derived from almonds, this protein source provides a mild flavor and is used in premium, clean-label protein crisp formulations.
Whey Protein holds installed capacity. Pea Protein is rotating up the share rankings.
Application:
The functional utility of protein crisps determines their integration into diverse food and beverage categories.
- Healthy Snacking:Protein crisps are increasingly incorporated into everyday snack items, providing a convenient and nutritious option for mainstream consumers. This segment's expansion is particularly visible in urban centers across Germany and the United Kingdom.
- Sports Nutrition:This application utilizes protein crisps to boost protein content in bars, shakes, and other products designed for athletes and active individuals. The segment commands a significant share in the United States, driven by dedicated fitness enthusiasts.
- Weight Management:Protein crisps contribute to satiety and muscle preservation in products formulated for weight loss and maintenance programs. These products target consumers seeking controlled calorie intake.
- Meal Replacement:Protein crisps enhance the nutritional value and texture of meal replacement powders and ready-to-eat products. This application serves busy individuals requiring balanced nutrition.
- Functional Foods:Protein crisps are integrated into a broader range of foods to enhance their nutritional benefits beyond basic sustenance. This category includes fortified cereals and baked goods.
The Sports Nutrition application maintains market dominance. Healthy Snacking shows the steepest expansion trajectory.
End User:
Consumer profiles for protein crisps vary based on lifestyle, dietary goals, and purchasing habits.
- Diet-conscious Consumers:This broad group seeks products that align with specific dietary preferences, including low-carb, high-protein, or plant-based diets. Their demand concentrates in developed markets like the United States and Europe.
- Fitness Enthusiasts:Individuals engaged in regular physical activity prioritize protein intake for muscle recovery and performance. Quest Nutrition specifically targets this group with high-protein formulations.
- Outdoor Adventurers:These consumers require lightweight, nutrient-dense, and portable food options for sustained energy during activities. Protein crisps offer a convenient solution for this segment.
- Office Workers:Seeking quick, healthy, and convenient snack options during busy workdays, office workers represent a growing demographic for protein crisp products. This trend is notable in major urban centers.
- Students:Students often look for affordable, easy-to-consume, and energizing snacks to support their academic and extracurricular demands. Protein crisps fit this need as a functional food.
The Fitness Enthusiasts demographic represents a foundational consumer base. The Diet-conscious Consumers group is expanding its consumption frequency.
Packaging Type:
The delivery format for protein crisps influences consumer convenience, product shelf-life, and brand visibility at retail.
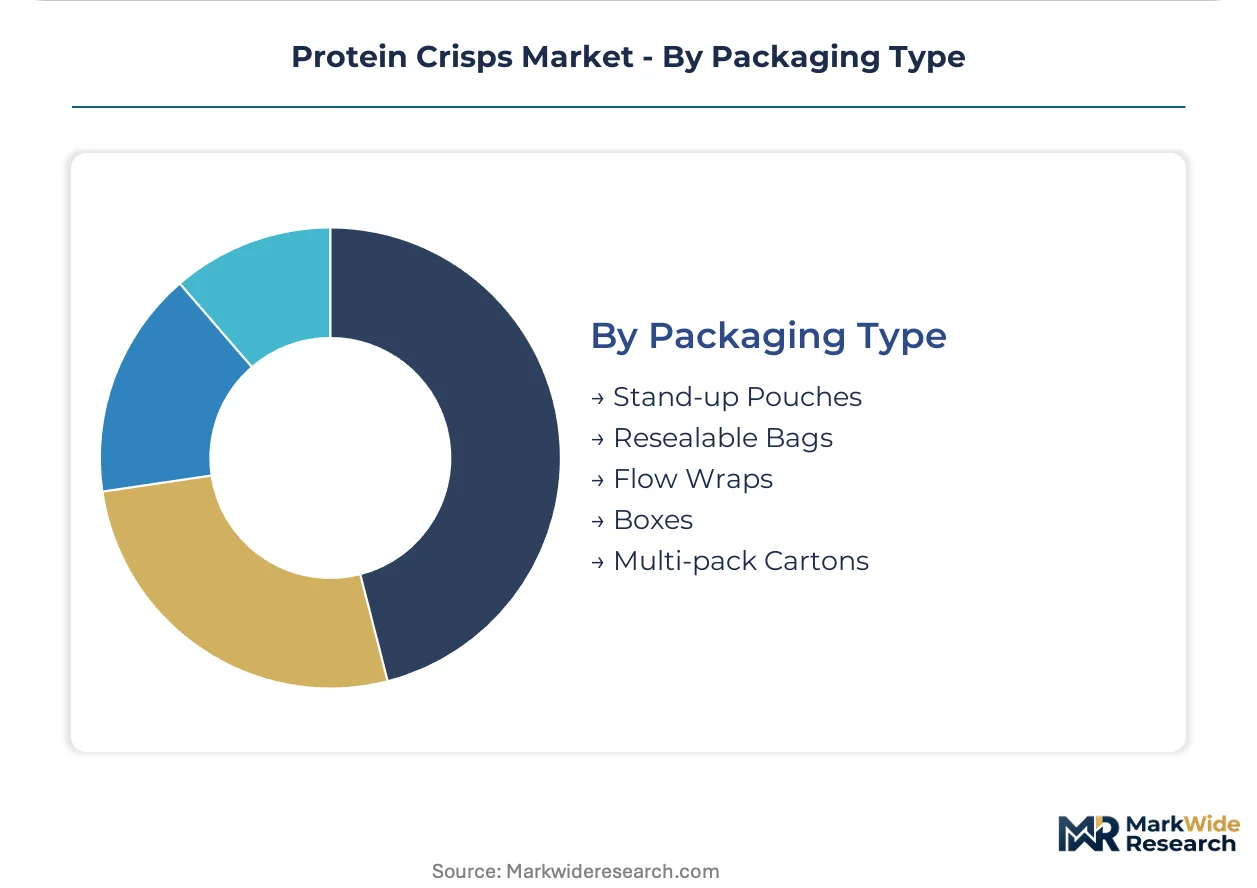
- Stand-up Pouches:These flexible packaging solutions offer excellent shelf presence, reclosability, and portability, making them popular for larger formats of protein crisps. This type is common in grocery and health food stores.
- Resealable Bags:Providing convenience for portion control and maintaining freshness, resealable bags are widely used for multi-serving protein crisp products. Consumers value the ability to save unused portions.
- Flow Wraps:Often used for individual servings, flow wraps provide a cost-effective and hygienic packaging solution for single-serve protein crisp bars or small snack packs. This format is prevalent in vending machines.
- Boxes:Used for multi-pack assortments or premium protein crisp products, boxes offer structural integrity and ample space for branding and nutritional information. This packaging type targets bulk buyers.
- Multi-pack Cartons:These cartons consolidate several individually wrapped protein crisp portions, catering to consumers who purchase in larger quantities for household consumption.
The Stand-up Pouches format dominates retail shelves. Resealable Bags are seeing increased adoption for specific product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Food and Drug Administration (FDA) regulations heavily influence protein crisp product development across North America. These regulations impact labeling claims and allergen declarations for manufacturers. Demand for protein crisps concentrates in major urban centers across Germany and the United Kingdom, driven by health-conscious consumers.
United States
Demand for protein crisps in the United States is fueled by fitness enthusiasts and diet-conscious consumers seeking high-protein options. The FDA's stringent labeling regulations for protein content claims directly shape product formulation and marketing. Major metropolitan areas like Los Angeles and New York City show high consumption of sports nutrition and healthy snacking products.
Germany
Germany's protein crisp market is expanding rapidly due to mainstream healthy snacking trends among urban populations. The European Food Safety Authority (EFSA) scrutinizes novel food ingredients and health claims, affecting market access for new formulations. Cities such as Berlin and Munich represent key consumption hubs for plant-based and functional snack products.
United Kingdom
The United Kingdom exhibits strong consumer demand for convenient, high-protein snacks, particularly in its major cities. EFSA guidelines, alongside UK Food Standards Agency requirements, govern product safety and ingredient approvals. London and Manchester are significant markets where health-conscious consumers actively seek protein-fortified food options.
Canada
Canadian investment in new pea protein processing facilities is reshaping the raw material supply chain for protein crisps. Health Canada regulations influence nutritional labeling and ingredient approvals for protein crisp products sold domestically. Urban centers like Toronto and Vancouver are key areas for diet-conscious consumers and plant-based protein adoption.
France
France is seeing a rise in demand for protein crisps, driven by a growing interest in plant-based and functional foods among health-aware consumers. The Agence nationale de sécurité sanitaire de l'alimentation, de l'environnement et du travail (ANSES) works with EFSA to ensure food safety and evaluate nutritional claims. Paris and Lyon represent important markets for novel protein formulations and healthy snack innovations.
Protein Crisps Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the protein crisps market. The market structure is tiered, featuring large food conglomerates alongside specialized nutrition brands. Strategic archetypes include diversified food manufacturers, dedicated sports nutrition providers, and ingredient technology specialists. Capacity expansion and strategic partnerships represent dominant competitive moves.
Among the established brands, Post Holdings, Inc. and General Mills Inc. exemplify large food manufacturers leveraging extensive distribution networks to integrate protein-fortified snacks into mainstream product lines. Quest Nutrition represents a specialized entity, focusing on formulations with very high protein content specifically targeting dedicated fitness enthusiasts. These entities navigate raw material volatility and regulatory complexities while expanding product portfolios.
| Leading Market Players |
|---|
| Post Holdings, Inc. |
| ProtiDiet |
| General Mills Inc. |
| Premier Nutrition Company, LLC |
| Power Crunch |
| WK Kellogg Co |
| Quest Nutrition |
| MYPROTEIN (The Hut Group) |
| PepsiCo |
| Others |
Cost & Logistics Intelligence
Canadian investment in new pea protein processing facilities is tilting the raw material supply chain, directly influencing where margin pools sit for plant-based protein crisp manufacturers. This shift impacts product formulation costs and ultimately consumer pricing strategies across North American and European markets. Managing these upstream dynamics is crucial for sustainable profitability.
Pricing Analysis
Geographic price spreads for protein crisps reflect regional raw material availability and regulatory compliance costs. The dominant pricing model for B2B ingredient sales is contract-based long-term offtake, ensuring supply stability for large food manufacturers. Price differentiation stems from protein purity levels and specialized allergen-free certifications. Upward pricing pressure arises from volatile raw material costs, particularly for trending pea protein. Healthy snacking consumers exhibit higher price sensitivity compared to dedicated fitness enthusiasts.
Supply Chain Analysis
Contract manufacturing capacity for protein crisps is concentrated among specialized ingredient processors in North America and Europe. The supply chain draws heavily from key raw material sources: pea protein from Canada, whey protein from the United States, and soy protein globally. Raw material price volatility represents a significant structural risk, impacting procurement strategies. Distribution for protein crisps primarily runs through specialized ingredient distributors and direct sales channels to large food and beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Protein Crisps Market is an early-cycle expansion story, driven by the accelerating mainstream adoption of healthy snacking habits among urban populations globally.
For Market Incumbents: Entrench existing market share by investing in advanced twin-screw extrusion technology to improve texture and flavor profiles. Secure long-term, multi-year supply contracts for preferred protein sources like pea protein to mitigate raw material volatility. Counter emerging plant-based protein threats through continuous R&D in novel protein sources and processing methods. Reinforce channel control through strategic partnerships with major retail and food service chains.
For New Entrants and Emerging Players: Build out specialized product lines targeting white-space opportunities in geriatric nutrition or savory applications. Asia-Pacific urban centers represent a highly penetrable geographic segment for functional snacking products. A compelling go-to-market angle involves explicit clean-label claims, ethical sourcing narratives, and innovative protein blends for unique nutritional benefits.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across plant-based protein processing, indicating significant future growth potential. Long-term viability over the next 5-10 years remains strong due to sustained consumer health and wellness trends. Acquisition targets should include ingredient technology specialists with proprietary extraction methods or unique plant-based protein portfolios. Regulatory approvals for novel protein sources in key markets serve as a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Pea Protein Processing | Secures raw material supply and reduces reliance on volatile commodity markets. |
| Product Innovation in Savory Applications | Expands market reach beyond traditional sweet snacks into new consumption occasions. |
| Strategic Partnership with Functional Food Brands | Accelerates market penetration and co-development of new protein-fortified products. |
| Geographic Expansion into Asia-Pacific Markets | Captures untapped demand from a growing middle class adopting Western snacking habits. |
| Sustainability Repositioning of Protein Sources | Addresses consumer demand for ethical sourcing and environmental impact considerations. |
Research Approach
Operator-level perspectives from food technologists, procurement managers, brand marketing directors, and regulatory affairs specialists anchored the qualitative base of this analysis. This primary research was rigorously combined with secondary validation from sources including FDA filings, EFSA opinions, food industry trade publications, and company annual reports. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy and comprehensive market understanding.
Scenario-bracketing framed the analytical framework, modeling market evolution across the analysis window under various economic and technological conditions. Segmentation dimensions modeled included product type, application, end-user, packaging type, and protein source origin. Compound annual growth rates were derived by extrapolating historical growth trends and integrating projected shifts in market dynamics. Key forecast inputs included raw material price forecasts and consumer health trend adoption rates.
Stress conditions across global economic downturns, unforeseen agricultural policy changes, and rapid shifts in dietary preferences were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Quarterly review of protein crisp ingredient prices and consumer preference shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Energy Balls Market
Snacks
United States Snack Bar Market
Snacks
Seafood Snacks Market
Snacks
Kids Snacks Market
Snacks
UK Snack Market
Snacks
Snack Food Packaging Market
Snacks
Extruded Snacks Market
Snacks
South America Cereal Bar Market
Snacks
North America Energy Bar Market
Snacks
Italy Snack Bar Market
Snacks
Sweet Potato Fries Market
Snacks
South Africa Snack Bar Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Europe Snack Pellets Market
Snacks
Cheese Snacks Market
Snacks
Marshmallow Market