
 Functional Powdered Lipids Market | 2026-2036
Functional Powdered Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Powdered Lipids Market Analytics
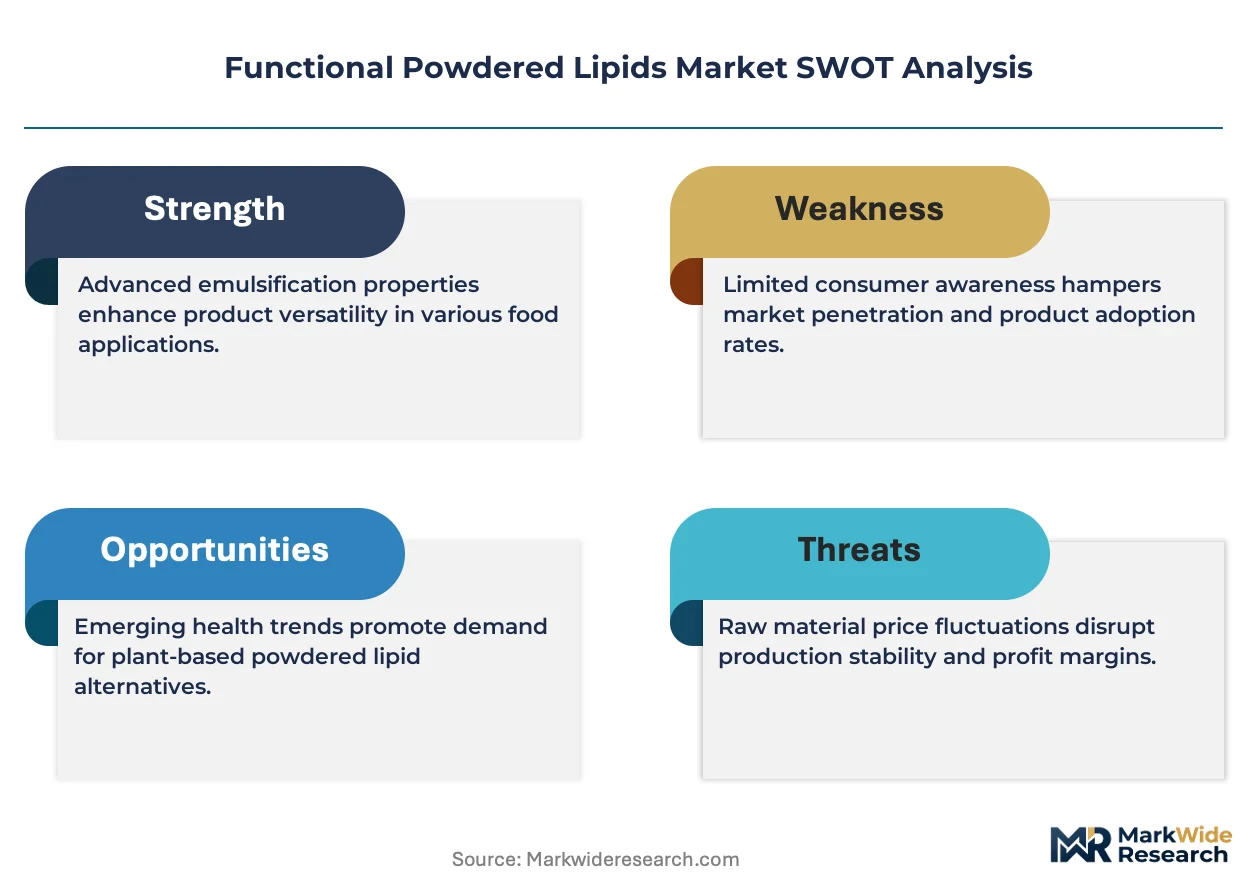
European specialty chemical producers is repositioning capacity toward pharmaceutical-grade powdered lipids as clean-label demand intensifies. BASF SE leverages its integrated lecithin and phospholipid platforms to serve European nutraceutical formulators. Cargill Inc. anchors North American supply through its extensive oilseed processing infrastructure. Kerry Group differentiates via customized lipid premix solutions for infant nutrition and clinical applications.
Functional powdered lipids are lipid-based ingredients converted into free-flowing particulate form through spray-drying, microencapsulation, or fluid-bed agglomeration, typically containing 50-95% lipid content with carrier matrices such as maltodextrin or modified starch, designed to enhance dispersibility, oxidative stability, and controlled release in finished products. Phospholipids dominate value contribution due to their emulsification performance and premium positioning in pharmaceuticals and infant formula. Medium-chain triglycerides represent the fastest-expanding product category as ketogenic diets and medical nutrition applications multiply. The food and beverages application segment occupies the largest volume share, though nutraceuticals and pharmaceuticals command superior margin pools through specification-grade requirements.
The FDA's Food Safety Modernization Act and the European Food Safety Authority's novel food assessments shape ingredient approval timelines and purity benchmarks for lipid suppliers seeking market access. China's National Health Commission and SAMR enforce GB standards for food-grade lipids that foreign producers must satisfy for import clearance. India's FSSAI has tightened contaminant limits for lipid ingredients used in fortified foods and infant nutrition. Stakeholders must monitor evolving novel food classifications and regional purity standards to secure formulation partnerships and avoid regulatory delays in high-growth nutrition markets.
Market Dynamics
Phospholipid-rich powdered lipid procurement by infant formula manufacturers is concentrating supply relationships around Asia-Pacific processing hubs, forcing European and North American producers to recalibrate capacity toward specification-grade pharmaceutical applications.
Growth Catalysts
- China's GB Standards Enforcement:SAMR import clearance requirements for food-grade lipids are compelling domestic fortification programs in infant nutrition and clinical applications.
- Medium-Chain Triglyceride Formulation:Ketogenic diet protocols and medical nutrition pipelines are expanding pharmaceutical-grade lipid demand across hospital and homecare channels.
- India:FSSAI contaminant limit tightening for fortified foods is accelerating domestic phospholipid purification investments and import substitution programs.
Market Restraints
- Phospholipid Input Volatility:Lecithin feedstock costs fluctuate with soybean and sunflower oil commodity cycles, compressing margin predictability for spray-drying operators.
- EU Novel Food Assessment Timelines:EFSA's extended safety evaluation periods for new lipid sources delay product launches by 18-36 months versus conventional approval pathways.
- Encapsulation Technology Substitution:Liposome and solid-lipid nanoparticle delivery systems threaten powdered lipid relevance in high-value pharmaceutical applications.
Strategic Opportunities
- Clinical Nutrition White Space:Underpenetrated geriatric and oncology nutrition segments in Brazil and Mexico offer expansion corridors for MCT-based medical formulas.
- US FSMA Traceability Mandates:FDA's enhanced record-keeping rules favor suppliers with integrated oilseed-to-powder documentation systems, creating compliance-based differentiation.
- Microencapsulation-Fluid Bed Convergence:Hybrid processing technologies enabling 95%+ lipid payloads with enhanced oxidative stability are opening premium positioning in nutraceuticals.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:cGMP and EXCiPACT qualification processes require 12-18 month validation cycles that strain working capital for mid-scale processors.
- Specialized Talent Scarcity:Lipid oxidation chemistry and spray-drying process engineering expertise concentrates among retiring cohorts in European and Japanese technical centers.
- Legacy ERP Integration:Batch-level traceability requirements under evolving FSMA and EU regulations force costly MES upgrades at established oilseed processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Powdered Lipids Market |
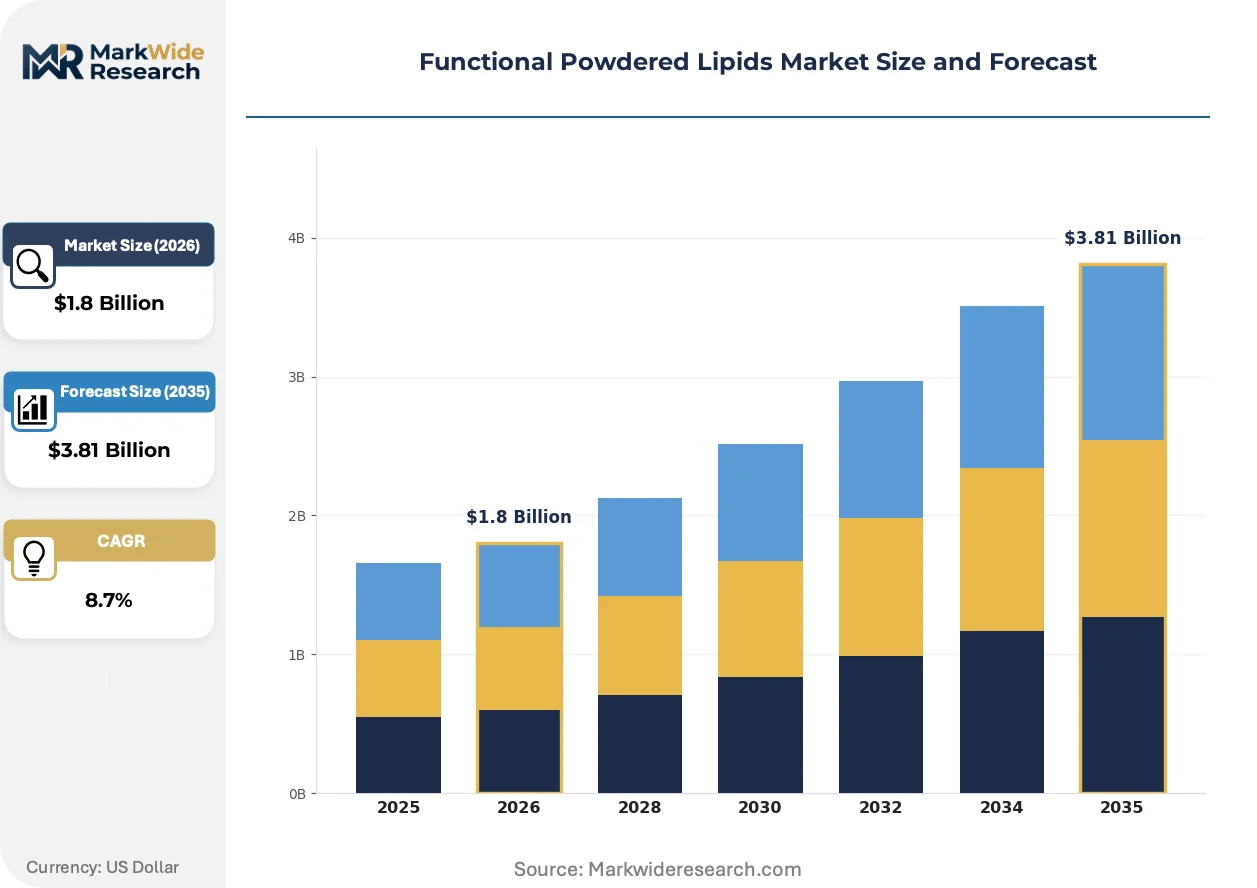
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phospholipids, Medium-Chain Triglycerides, Lecithin, Other Application: Food & Beverages, Nutraceuticals, Pharmaceuticals, Personal Care Delivery Mode: Powder, Liquid, Granular, Other Customer Type: Manufacturers, Retailers, Wholesalers, End Users |
| Companies Covered | BASF SE, Cargill Inc., Archer Daniels Midland, DSM-Firmenich, Kerry Group, ABITEC Corporation, Stepan Company, Croda International Plc, Royal FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Powdered Lipids Market Evolving Landscape
Microencapsulation technology maturation is compressing cost curves for high-payload lipid powders while regulatory traceability mandates are rewiring supplier-buyer contracting structures across nutrition and pharmaceutical verticals.
Spray-drying with modified starch carriers is consolidating as the dominant production pathway for 70-85% lipid content powders in infant formula applications. Major dairy processors in China and Southeast Asia are standardizing on this platform to achieve GB standard compliance with minimal capital retrofit. The technology is consolidating supplier tiers by favoring integrated oilseed processors with captive maltodextrin supply over standalone toll manufacturers.
EFSA's novel food assessments for algae-derived and microbial phospholipid sources are extending approval timelines and forcing reformulation strategies. European nutraceutical formulators are pivoting toward established lecithin sources to avoid regulatory uncertainty. Clinical nutrition segments are most affected, with several pipeline products stalled in pre-submission phases pending toxicology data requirements.
Specification-grade procurement contracts are displacing spot-market purchasing for pharmaceutical and infant nutrition lipids. Tier-one formulators in Germany, Switzerland, and Japan are locking multi-year supply agreements with documented provenance chains. This pattern is most visible in ketogenic diet product lines, where MCT powder suppliers face audit requirements spanning seed origin through final agglomeration.
Functional Powdered Lipids Market Segmentation
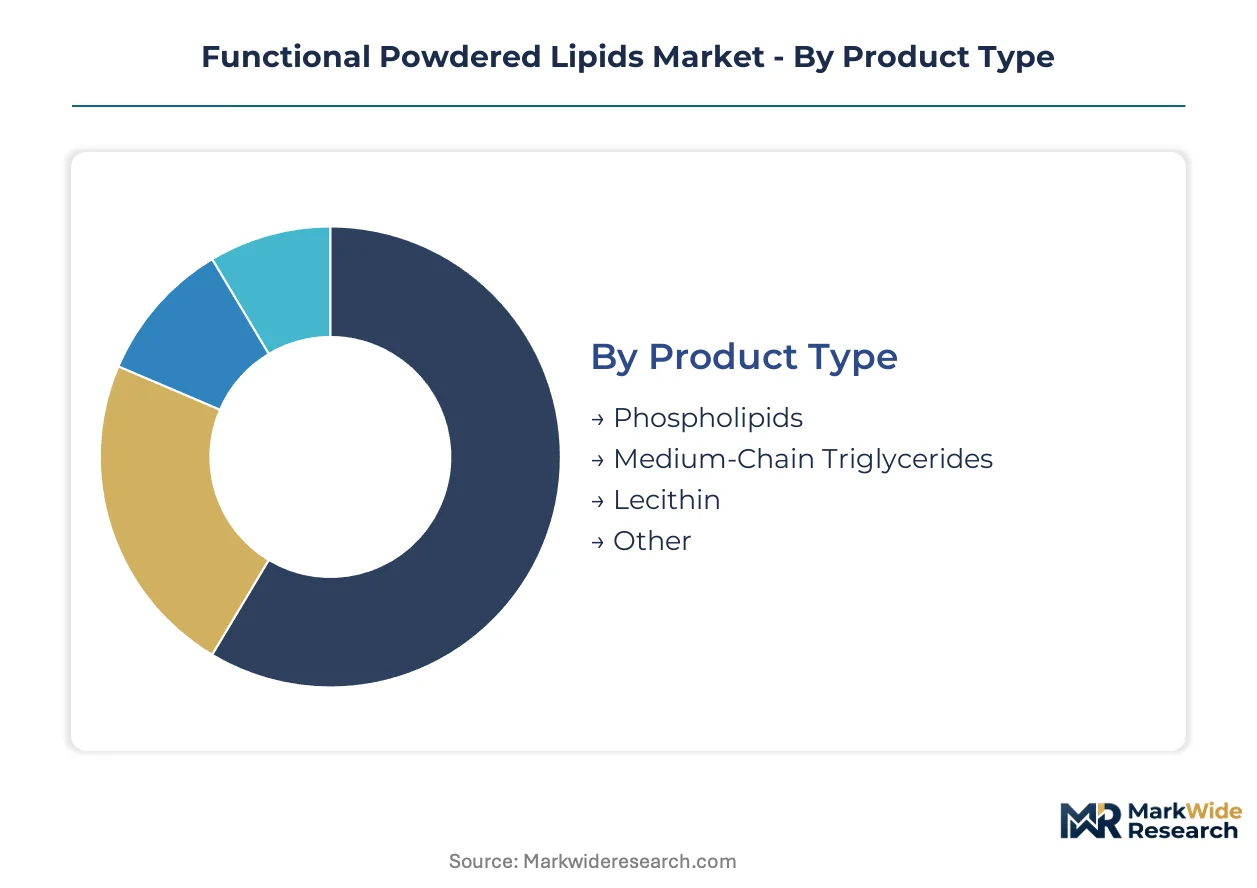
Segmentation in functional powdered lipids reveals how processing specifications and end-use requirements partition margin pools across the value chain. Formulators select lipid payloads, carrier matrices, and delivery formats based on oxidative stability needs, dispersibility thresholds, and regulatory clearance timelines in target markets.
Product Type:
Upgrade cycles in lipid purification and microencapsulation are pushing formulators toward higher-specification grades that command premium positioning in infant nutrition and clinical applications.
- Phospholipids:These amphiphilic molecules deliver emulsification performance critical to infant formula stability and pharmaceutical liposome construction. Demand concentrates among Asia-Pacific dairy processors seeking GB standard compliance for fortification programs, though EFSA novel food assessments for alternative sources extend reformulation timelines.
- Medium-Chain Triglycerides:Rapidly metabolized C8-C10 fatty acid esters enable ketogenic diet protocols and medical nutrition for metabolic disorders. Hospital and homecare channels in Brazil and Mexico are expanding procurement as geriatric nutrition segments mature, creating specification-grade volume corridors.
- Lecithin:Soy-derived and sunflower-sourced phospholipid complexes serve as natural emulsifiers across food processing and feed applications.
- Other:Omega-3 concentrates, structured triglycerides, and plant sterol esters address niche cardiovascular and cognitive health formulations.
Phospholipids sit at the top of the volume ranking, with medium-chain triglycerides climbing the fastest.
Application:
Margin concentration follows regulatory stringency, with pharmaceutical and infant nutrition specifications extracting value premiums that food processing applications cannot match.
- Food & Beverages:Powdered lipids fortify dairy alternatives, bakery emulsions, and convenience nutrition with enhanced shelf stability. China and India are scaling domestic production lines for fortified milk powders and meal replacements, though FSSAI contaminant limits and GB standards enforcement raise qualification barriers for imported ingredients.
- Nutraceuticals:Sports nutrition and cognitive health supplements drive demand for high-payload MCT powders and phospholipid complexes. European formulators pivot toward established lecithin sources to circumvent EFSA novel food uncertainty, compressing pipeline timelines for algae-derived alternatives.
- Pharmaceuticals:cGMP-certified lipid excipients serve parenteral emulsions, oral drug delivery, and clinical nutrition formulations.
- Personal Care:Cosmetic-grade lecithin and lipid powders enable skin barrier formulations and hair conditioning applications.
Food and beverages captures the largest absolute volume, with pharmaceuticals generating the steepest margin expansion trajectory.
Delivery Mode:
Processing technology selection hinges on lipid payload targets, oxidative sensitivity, and finished-product dispersibility requirements across customer specifications.
- Powder:Spray-dried and agglomerated formats dominate infant formula and clinical nutrition for free-flowing handling and rapid reconstitution. Hybrid microencapsulation-fluid bed systems enabling 95%+ lipid payloads are opening premium nutraceutical positioning.
- Liquid:Unencapsulated oil suspensions serve cost-sensitive food processing where oxidative stability is managed through packaging and distribution controls.
- Granular:Agglomerated particles improve flowability and reduce dusting in high-speed manufacturing environments.
- Other:Paste and semi-solid formats address specialized bakery and confectionery processing needs.
Powder formats command the dominant share, with granular systems gaining adoption fastest in automated processing lines.
Customer Type:
Procurement sophistication varies sharply across the buyer base, with tier-one manufacturers extracting supply-chain documentation requirements that strain mid-scale processors.
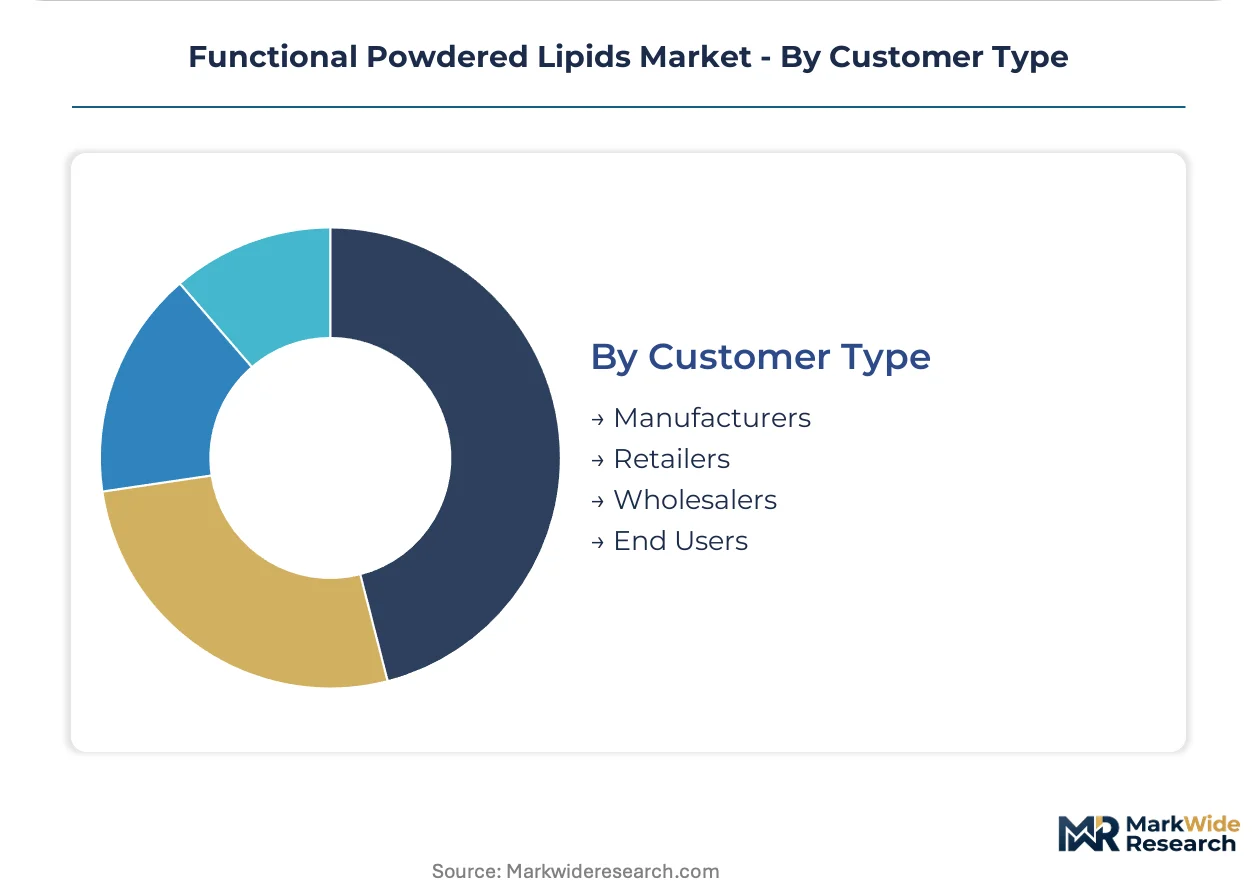
- Manufacturers:Infant formula producers, pharmaceutical formulators, and dairy processors drive specification-grade demand with multi-year supply agreements and audit requirements spanning seed origin through final agglomeration. FSMA traceability mandates favor suppliers with integrated oilseed-to-powder documentation systems.
- Retailers:Private-label nutrition brands and specialty health stores source finished powdered lipid products for direct consumer distribution.
- Wholesalers:Ingredient distributors aggregate volumes across smaller formulators lacking direct supplier relationships.
- End Users:Research institutions and small-scale food entrepreneurs purchase through distributor channels.
Manufacturers represent the primary value concentration point, with retailer direct sourcing expanding fastest as clean-label brands consolidate supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate capacity to jurisdictions with streamlined novel-food pathways and lower certification burdens. Cost-of-compliance gaps between major markets are accelerating investment clustering in Asia-Pacific processing hubs while European facilities pivot toward premium pharmaceutical grades.
China
Infant formula fortification programs and expanding domestic dairy processing are driving phospholipid-rich lipid procurement. SAMR enforces GB standards for food-grade lipid imports that foreign producers must satisfy for clearance. Yangtze River Delta dairy processors are standardizing on spray-dried lipid platforms to achieve compliance with minimal capital retrofit.
Germany
Pharmaceutical-grade lipid excipient demand from parenteral emulsion formulators anchors regional production. EFSA novel food assessments for alternative phospholipid sources extend approval timelines, forcing reliance on established lecithin supply chains. North Rhine-Westphalia chemical clusters are repositioning capacity toward cGMP-certified medical nutrition applications.
United States
Ketogenic diet protocols and medical nutrition pipelines are expanding MCT powder demand across hospital and homecare channels. FDA FSMA traceability mandates favor suppliers with integrated oilseed-to-powder documentation systems. Midwest oilseed processing corridors are upgrading MES systems to meet batch-level record-keeping requirements.
India
FSSAI contaminant limit tightening for fortified foods is accelerating domestic phospholipid purification investments and import substitution programs. Maharashtra and Gujarat dairy cooperatives are scaling fortified milk powder production lines with specification-grade lipid inputs. Domestic toll manufacturers are capturing share from European suppliers facing extended clearance timelines.
Brazil
Underpenetrated geriatric and oncology nutrition segments are creating expansion corridors for MCT-based medical formulas. ANVISA pharmaceutical-grade certification requirements shape procurement standards for clinical lipid excipients. São Paulo pharmaceutical formulators are locking multi-year supply agreements with documented provenance chains.
Functional Powdered Lipids Market Competitive Landscape
European specialty chemical producers anchor one tier; Asia-Pacific oilseed processors hold volume-scale positions. The vendor base stratifies across integrated multinationals with captive raw material supply, mid-scale toll manufacturers serving regional formulators, and niche specialists in microencapsulation technology. Strategic archetypes include backward-integrated oilseed processors, pharmaceutical-grade certification specialists, and hybrid technology providers converging fluid-bed and spray-drying platforms. Dominant competitive moves encompass multi-year supply agreement locking with tier-one formulators and MES upgrade investments to satisfy evolving traceability mandates.
Within the integrated multinational tier, BASF SE and Cargill Inc. exemplify divergent geographic anchoring strategies. BASF SE occupies a position serving European nutraceutical formulators through established lecithin and phospholipid platforms. Cargill Inc. represents the North American supply anchor, leveraging extensive oilseed processing infrastructure. Kerry Group sits within the customized solutions archetype, differentiating via lipid premix capabilities for infant nutrition and clinical applications. These three companies collectively illustrate how scale, geographic concentration, and application specialization partition competitive positioning across the value chain.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Inc. |
| Archer Daniels Midland |
| DSM-Firmenich |
| Kerry Group |
| ABITEC Corporation |
| Stepan Company |
| Croda International Plc |
| Royal FrieslandCampina |
| Others |
Value Network & Pricing Analysis
Infant formula manufacturers in China and India concentrate procurement power around specification-grade phospholipid suppliers, driving a contract-based long-term offtake model that rewards documented provenance chains with price premiums and volume guarantees.
Pricing Analysis
Distributor margins compress as tier-one formulators in Germany, Switzerland, and Japan lock direct supply agreements with integrated oilseed processors. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels separates cGMP-certified excipients from standard fortification ingredients. Cost compression in food-grade lecithin intensifies because soybean and sunflower oil commodity cycles feed directly into spray-drying operator margins. Pharmaceutical formulators exhibit the lowest price sensitivity due to regulatory substitution barriers, while bakery and confectionery processors negotiate aggressively on volume.
Supply Chain Analysis
Single-source vulnerability sits with European lecithin purification capacity, where retiring process engineering expertise concentrates in North Rhine-Westphalia chemical clusters. Manufacturing gravity draws from China, India, and Germany as Asia-Pacific dairy processors scale domestic spray-drying platforms and European facilities pivot toward pharmaceutical certification. Soybean and sunflower oil feedstocks, maltodextrin carriers, and modified starch encapsulants anchor raw material dependencies. Regulatory restriction risk runs through EFSA novel food assessment timelines that extend approval cycles for alternative phospholipid sources. Distribution runs through integrated oilseed processors with captive maltodextrin supply, displacing standalone toll manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional powdered lipids function as a stable compounder anchored by clinical nutrition and infant formula fortification programs that generate recurring specification-grade demand across economic cycles.
For Market Incumbents: Deepen backward integration into oilseed crushing and maltodextrin production to capture margin pools currently leaking to commodity suppliers. Expand cGMP-certified capacity in Germany and Switzerland to defend against emerging Asian pharmaceutical-grade competitors. Liposome and solid-lipid nanoparticle delivery systems threaten powdered lipid relevance in high-value applications, demanding accelerated microencapsulation R&D investment. For New Entrants and Emerging Players: Hybrid microencapsulation-fluid bed convergence offers entry into premium nutraceutical positioning where 95%+ lipid payloads command specification-grade margins. Target underpenetrated geriatric and oncology nutrition segments in Brazil and Mexico with MCT-based medical formulas. Pursue white-label partnerships with Brazilian pharmaceutical formulators seeking ANVISA-compliant supply alternatives to European incumbents. For Investors and Strategic Acquirers: Pharmaceutical formulators are the most active acquirer in this space, seeking captive lipid excipient supply to secure parenteral emulsion pipelines. Mid-scale toll manufacturers with SAMR clearance and FSSAI registration represent priority acquisition targets. Watch for EFSA novel food approval acceleration as the inflection signal that would unlock algae-derived phospholipid valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks multi-year volume commitments with tier-one infant formula manufacturers facing GB standard compliance deadlines. |
| Backward Integration | Captures oilseed crushing and maltodextrin production margins currently extracted by commodity suppliers. |
| cGMP Certification Investment | Opens pharmaceutical excipient markets where EMA and FDA purity requirements create substitution barriers. |
| Hybrid Processing Technology | Enables 95%+ lipid payload powders with enhanced oxidative stability for premium nutraceutical positioning. |
| MES System Upgrade | Satisfies FSMA traceability mandates and EU batch-level documentation requirements for integrated processors. |
Research Methodology
Direct dialogue with spray-drying plant managers, infant formula procurement leads, pharmaceutical regulatory affairs directors, and lipid oxidation chemistry specialists grounded qualitative findings. Secondary validation drew from SAMR GB standard filings, EFSA novel food assessment databases, FSSAI contaminant limit notifications, and SEC 10-K disclosures from integrated oilseed processors. Bottom-up and top-down triangulation reconciled capacity utilization data with end-use demand segmentation.
Bottom-up modeling projected volume and value across the analysis window by disaggregating phospholipid, MCT, lecithin, and omega-3 product categories against food and beverage, nutraceutical, pharmaceutical, and personal care applications. Modeled variables included lipid payload percentages, carrier matrix compositions, certification grade tiers, and regional regulatory cluster adoption curves. CAGRs derived from historical capacity expansion patterns correlated with infant formula fortification program announcements and ketogenic diet protocol expansion in hospital channels.
The model holds under stable regulatory clearance timelines and commodity feedstock availability; deviation in EFSA novel food assessment duration or soybean oil price volatility would shift trajectory. Forecasts reflect documented assumptions about SAMR enforcement intensity and FSSAI contaminant limit implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market