
 Low Fat Smoothies Market | 2026-2036
Low Fat Smoothies Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Smoothies Market Analytics
The EU Green Deal is broadening demand for low-fat smoothies with reformulated recipes and recyclable packaging commitments. Bolthouse Farms leverages its captive agricultural supply chain to control ingredient quality and cost across North American retail. Innocent Drinks anchors its European position through transparent sourcing narratives and carbon-neutral production claims. Jamba Juice competes in the foodservice channel with made-to-order formats that emphasize fresh fruit visibility and customizable macronutrient profiles.
Low-fat smoothies are blended beverages containing reduced lipid content, typically achieved through skimmed dairy bases, water-diluted fruit purees, or plant-derived emulsifiers, with fat content generally held below two grams per serving to meet nutritional labeling thresholds. Fruit-based formulations dominate volume due to established consumer palatability and year-round ingredient availability, while dairy-free variants represent the fastest-growing product type as oat and almond protein bases displace traditional yogurt blends. The distribution channel structure tilts toward supermarkets for packaged retail velocity, though online retail captures expanding margin pools through subscription models and direct-to-consumer flavor customization.
FDA nutrition labeling rules and the USDA organic certification program govern product claims and ingredient disclosures in the United States, while the EU Green Deal and REACH chemical safety standards shape packaging material selection and additive permissibility across European markets. Health Canada and PMRA guidelines extend these frameworks to North American cross-border trade, creating compliance complexity for multinational brands. Stakeholders must monitor evolving front-of-pack warning label requirements and sugar taxation proposals that threaten to reclassify formerly permissible smoothie formulations into restricted beverage categories.
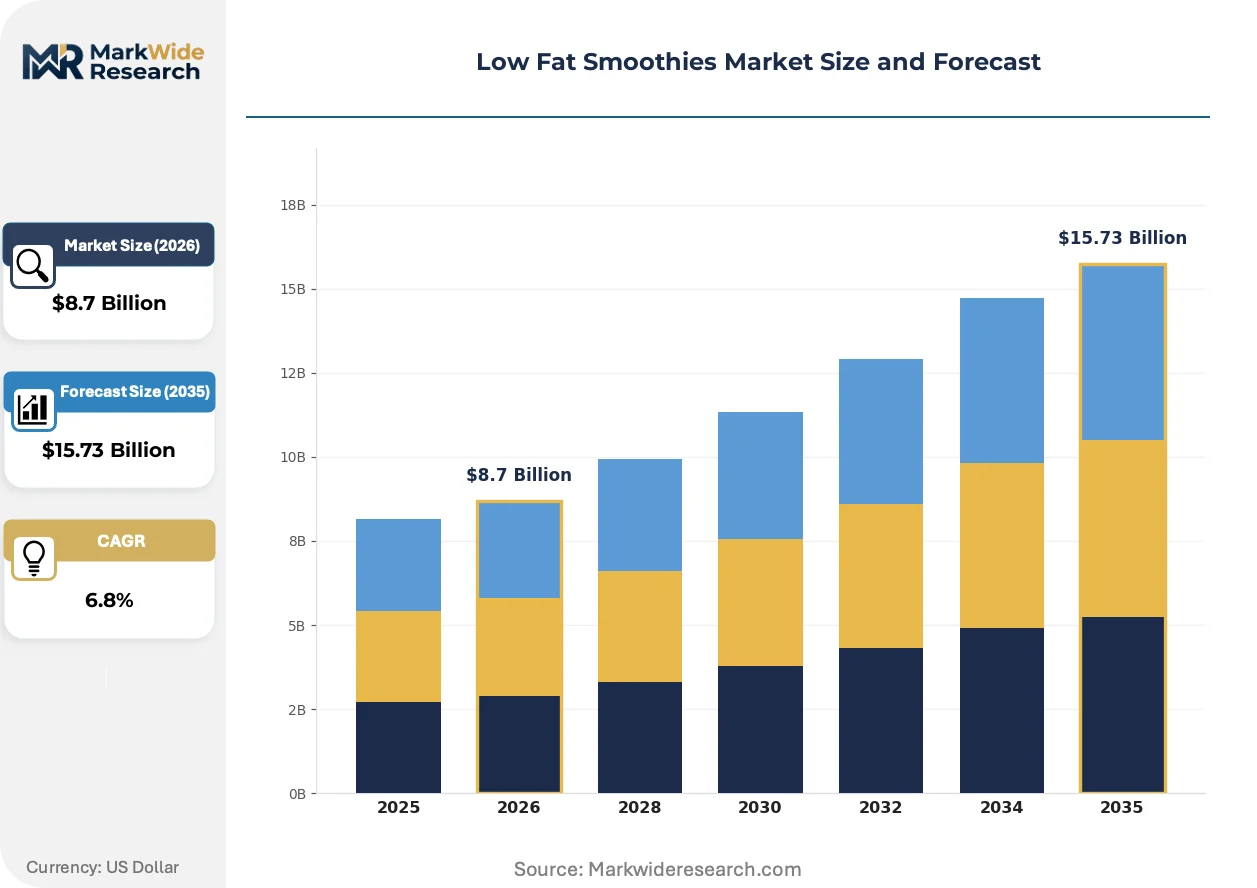
Market Dynamics
Clean-label mandates and sugar taxation proposals are forcing reformulation across packaged smoothie portfolios, compressing permissible ingredient palettes while elevating compliance costs for multinational brands.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclable container requirements are accelerating material innovation and opening premium positioning for brands with verified circular supply chains.
- Health-conscious foodservice procurement:Corporate cafeterias and university dining systems are adding low-fat smoothie stations to meet wellness program targets.
- Oat protein extraction advances:Enzymatic processing breakthroughs are improving mouthfeel in dairy-free bases without lipid additives.
Market Restraints
- Frozen fruit concentrate volatility:Weather-driven supply disruptions in Latin American growing regions create input cost instability for fruit-puree formulations.
- FDA front-of-pack warning label proposals:Draft regulations threatening added-sugar disclosures could reclassify many existing smoothie products into restricted beverage categories.
- Almond milk water intensity:California drought conditions and groundwater regulations are constraining supply scalability for nut-based dairy alternatives.
Strategic Opportunities
- USDA organic certification tailwinds:Federal procurement preferences and retailer slotting fee reductions for organic SKUs create margin expansion potential.
- Direct-to-subscription channel development:Personalized flavor profiling and flexible delivery cadences are capturing higher lifetime value than conventional retail.
- Functional ingredient convergence:Probiotic and adaptogenic additive integration is opening clinical wellness positioning beyond basic nutrition claims.
Industry Challenges
- Clean-label preservative gap:Elimination of potassium sorbate and benzoates without viable natural alternatives is compressing shelf-life targets.
- Cross-border formulation complexity:Divergent additive permissibility between FDA, EFSA, and Health Canada standards fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Smoothies Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit-Based, Vegetable-Based, Mixed, Dairy-Free End User: Health Enthusiasts, Fitness Centers, Cafés, Retail Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Bottles, Pouches, Tetra Packs, Cartons |
| Companies Covered | Bolthouse Farms, Smoothie King, Jamba Juice, Tropical Smoothie Café, Ella's Kitchen Ltd., Barfresh Food Group, Maui Wowi Hawaiian Coffees & Smoothies, Innocent Drinks, Naked Juice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Smoothies Market Evolving Landscape
Formulation science and packaging engineering are converging to solve the shelf-stability versus clean-label paradox that has constrained refrigerated smoothie distribution economics.
High-pressure processing technology is automating cold-pasteurization workflows for perishable smoothie formats. Regional dairy cooperatives and mid-size juice processors are adopting HPP lines to extend refrigerated shelf life without thermal degradation of heat-sensitive vitamins. This automation is compressing the capital barrier between ambient-stable and fresh-positioned product tiers.
REACH chemical safety standards are tightening emulsifier and stabilizer permissibility across European manufacturing. The ECHA authorization list expansion is forcing substitution of polysorbate-based texture modifiers with lecithin or plant-gum alternatives. Dairy-free formulations with simpler ingredient decks are capturing disproportionate shelf space in German and French retail as compliance complexity rises.
Subscription-based replenishment models are displacing impulse-driven supermarket purchasing among core health-enthusiast demographics. Direct-to-consumer platforms with algorithmic flavor rotation are capturing pantry-space commitment that conventional retail cannot match. This behavioral pivot is most pronounced in United States metropolitan markets with high delivery-logistics density and wellness-app ecosystem penetration.
Low Fat Smoothies Market Segmentation
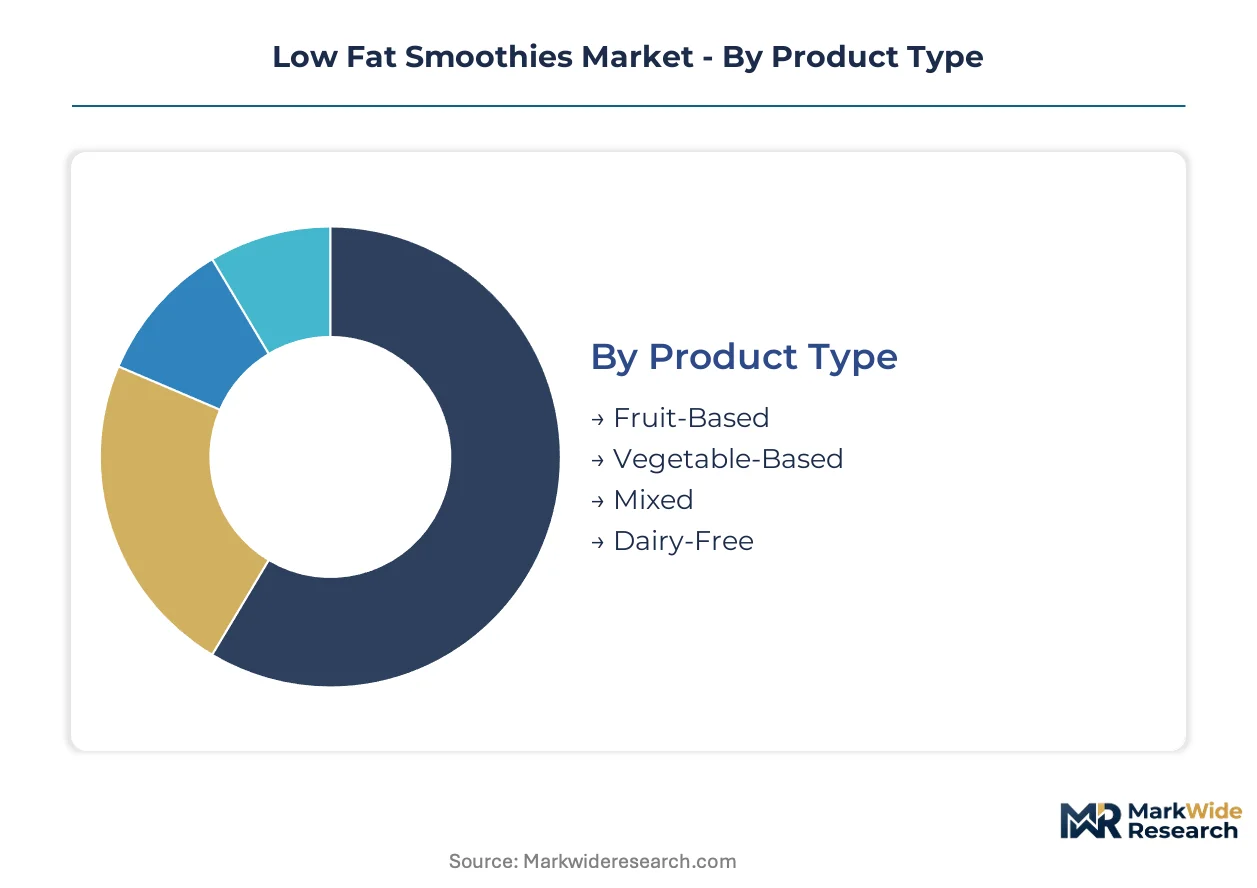
Segmentation in the low-fat smoothies market determines formulation priorities, shelf-life engineering, and channel economics. Product architecture and packaging specifications diverge sharply across health-enthusiast versus mass-retail demand clusters.
Product Type:
Supply concentration in fruit processing infrastructure tilts manufacturing capacity toward established puree supply chains, though enzymatic advances are redistributing investment.
- Fruit-Based:Formulations rely on apple, berry, and tropical purees diluted to sub-two-gram fat thresholds through water or juice extension. United States retail velocity concentrates in strawberry-banana and mixed-berry SKUs where Bolthouse Farms and private-label programs compete on seasonal fruit procurement contracts.
- Dairy-Free:Oat and almond protein bases displace yogurt blends through enzymatic mouthfeel engineering that eliminates lipid additives. German and French retail are expanding shelf space for these simpler-ingredient formats as ECHA authorization lists tighten emulsifier permissibility.
- Vegetable-Based:Spinach, kale, and carrot purees target nutrient-density positioning with chlorophyll-stabilized color systems.
- Mixed:Hybrid fruit-vegetable formulations balance palatability with micronutrient claims for corporate cafeteria procurement.
Fruit-based formats absorb the bulk of installed capacity; dairy-free variants are expanding most quickly.
End User:
Application-specific procurement standards create divergent margin structures across institutional and direct-to-consumer channels.
- Health Enthusiasts:Algorithmic subscription platforms with personalized flavor rotation capture pantry-space commitment unavailable through conventional retail. United States metropolitan markets with high wellness-app penetration show the steepest adoption curves for direct-to-consumer replenishment models.
- Fitness Centers:Post-workout protein-fortified formats require ambient-stable packaging for vending machine distribution with extended shelf-life targets.
- Cafés:Made-to-order visibility and customizable macronutrient profiles drive equipment investment in high-throughput blending stations.
- Retail Consumers:Impulse-driven supermarket purchasing concentrates in grab-and-go refrigerated cases with front-of-pack labeling compliance.
Retail consumers command the largest volume footprint; health enthusiasts generate the highest lifetime value per account.
Distribution Channel:
Margin capture varies systematically across logistics-intensive versus relationship-driven channel architectures.
- Supermarkets:Private-label velocity and slotting-fee economics dominate packaged retail with clean-label innovation driving category expansion. United States grocery chains are reducing organic SKU fees under federal procurement preferences.
- Online Retail:Subscription models with flexible delivery cadences and algorithmic flavor profiling achieve customer retention rates unmatched by physical retail.
- Specialty Stores:Curated assortments emphasize transparent sourcing narratives and carbon-neutral production claims for premium positioning.
- Direct Sales:Foodservice contracts with corporate cafeterias and university dining systems support wellness program procurement targets.
Supermarkets move the highest absolute volume; online retail is climbing the fastest on margin expansion.
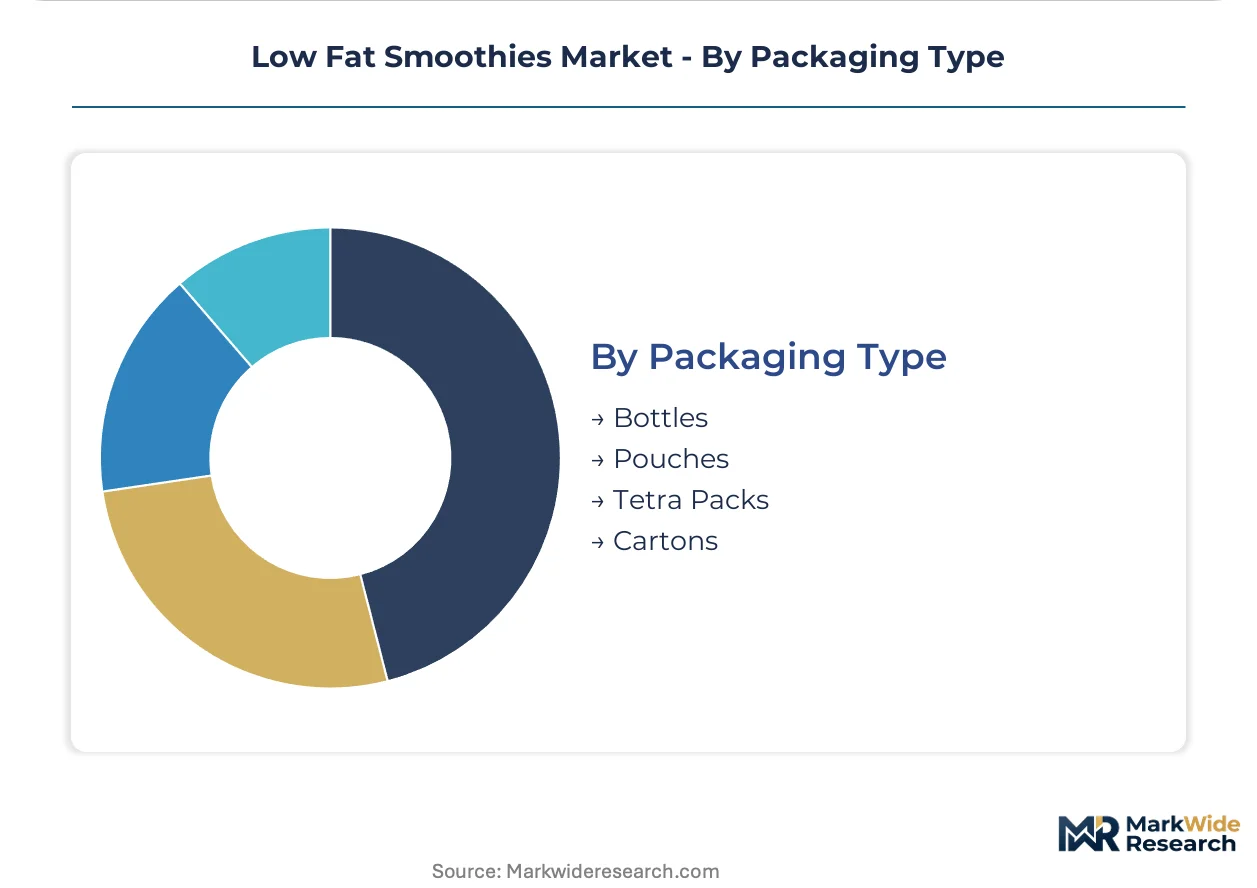
Packaging Type:
Material selection now hinges on EU Green Deal recyclable mandates and REACH chemical safety standards rather than cost minimization alone.
- Bottles:Recycled PET and rHDPE formats with verified circular supply chains command premium positioning as EFSA-compliant alternatives to virgin plastic.
- Pouches:Flexible formats reduce shipping cube and material weight but face limited curbside recyclability in United States municipal systems.
- Tetra Packs:Aseptic carton technology extends ambient shelf life for distribution economics in lower-refrigeration-capacity retail environments.
- Cartons:Gable-top refrigerated formats dominate fresh-positioned SKUs with high-pressure processing compatibility.
Bottles retain the largest installed base; pouches are gaining share fastest on logistics efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors North American smoothie innovation through Bolthouse Farms' vertical integration and the dense concentration of health-conscious consumers driving premium private-label expansion.
United States
Corporate cafeteria procurement and university wellness programs are expanding low-fat smoothie station installations across metropolitan markets. FDA front-of-pack warning label proposals threaten to reclassify existing formulations, forcing reformulation investments. Chicago's foodservice distribution corridor processes bulk frozen fruit concentrates for Midwest retail chains.
Germany
REACH chemical safety standards and ECHA authorization list expansions are tightening emulsifier permissibility for texture-modified beverages. The EU Green Deal's recyclable packaging mandates are accelerating rPET adoption across Berlin and Hamburg manufacturing zones. Bavarian dairy cooperatives are retrofitting high-pressure processing lines for clean-label shelf-life extension.
France
Carbon-neutral production claims and transparent sourcing narratives are capturing premium shelf space in Parisian retail. ANSM oversight of food additive safety is converging with EFSA standards to limit preservative palettes. The Île-de-France region hosts formulation R&D clusters serving pan-European private-label programs.
United Kingdom
Subscription-based replenishment models with algorithmic flavor rotation are displacing supermarket impulse purchasing in London and Manchester wellness-app ecosystems. Health Canada-aligned import standards create cross-border formulation complexity for Irish Sea trade routes. Scottish berry processing infrastructure supplies puree concentrates for reduced-fat formulations.
Canada
Health Canada and PMRA guidelines extend USDA organic certification frameworks to North American cross-border private-label manufacturing. Toronto's foodservice distribution network supports corporate wellness program procurement targets. British Columbia's fruit processing cooperatives supply concentrated purees for Pacific Northwest retail chains.
Low Fat Smoothies Market Competitive Landscape
The competitive structure tilts toward diversified beverage conglomerates with captive agricultural supply chains and regional smoothie chains with made-to-order formats. Three archetypes dominate: vertically integrated farm-to-bottle operators, foodservice-focused franchise networks, and clean-label specialists with subscription direct-to-consumer platforms. Capacity expansion in high-pressure processing equipment and strategic partnerships for sustainable packaging sourcing represent the dominant competitive moves.
Within the farm-to-bottle tier, Bolthouse Farms exemplifies vertical integration through its captive California agricultural operations. Innocent Drinks anchors European positioning through carbon-neutral production claims. Jamba Juice occupies the foodservice channel with customizable macronutrient profiles and fresh-fruit visibility. These three entities represent distinct strategic archetypes rather than direct substitutes, with divergent margin structures tied to retail velocity, subscription retention, and equipment-based throughput respectively.
| Leading Market Players |
|---|
| Bolthouse Farms |
| Smoothie King |
| Jamba Juice |
| Tropical Smoothie Café |
| Ella's Kitchen Ltd. |
| Barfresh Food Group |
| Maui Wowi Hawaiian Coffees & Smoothies |
| Innocent Drinks |
| Naked Juice |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's recyclable packaging mandates gate qualified supply access and premium-tier pricing power, as brands with verified circular supply chains capture shelf-space premiums while laggards absorb reformulation cost penalties across member-state retail networks.
Pricing Analysis
Subscription retention rates anchor value-based pricing for health-enthusiast segments, with algorithmic flavor rotation commanding pantry-space premiums unavailable through conventional retail velocity. Three-tier pricing structure across premium organic, standard clean-label, and economy private-label levels stratifies by certification grade and sourcing transparency depth. Pricing pressure stems from frozen fruit concentrate volatility in Latin American growing regions, compressing margins for fruit-puree-dependent portfolios. Retail consumers exhibit highest price sensitivity, while direct-to-subscription health enthusiasts accept sustained premium positioning.
Supply Chain Analysis
Reverse-logistics flows for recyclable rPET and rHDPE containers are reshaping procurement economics as EU Green Deal mandates require verified circular supply chain documentation for premium shelf access. Raw material sourcing concentrates in California agricultural operations for captive berry and leafy green supply, Latin American tropical fruit processing zones, and German oat protein extraction facilities. Supply chain risk centers on California drought-driven almond milk supply constraints and groundwater regulation tightening. Distribution runs through Chicago foodservice corridors for bulk concentrate, Los Angeles retail velocity hubs, and Berlin-Hamburg manufacturing zones for European compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive agricultural supply chains determine ingredient quality control and cost positioning across retail and foodservice channels.
For Market Incumbents: Extend high-pressure processing equipment footprints to compress shelf-life economics for refrigerated clean-label formats, defending against ambient-stable private-label erosion. Deepen backward integration into California berry and leafy green operations to offset frozen concentrate price volatility. Secure rPET supply agreements under EU Green Deal verification standards before competitor lock-in. For New Entrants and Emerging Players: Enzymatic oat protein mouthfeel engineering offers a technology-first wedge into German and French retail where ECHA authorization list tightening favors simpler-ingredient dairy-free formats. Target corporate cafeteria procurement channels with hybrid fruit-vegetable wellness program SKUs. Deploy direct-to-subscription platforms with algorithmic flavor rotation to bypass supermarket slotting-fee barriers. For Investors and Strategic Acquirers: USDA organic certification fee reductions at major US grocery chains is the leading indicator that federal procurement preferences will structurally favor certified supply chains over conventional portfolios. Acquisition focus should center on mid-size juice processors with HPP line capacity and established organic certification pathways. Watch FDA front-of-pack warning label proposal advancement as the signal for reformulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Line Deployment | Extends refrigerated shelf life without thermal degradation, enabling clean-label positioning against ambient competitors. |
| Captive Agricultural Supply Integration | Controls berry and leafy green input quality and cost volatility across North American retail networks. |
| EU Green Deal Packaging Compliance | Unlocks premium shelf positioning through verified rPET circular supply chains in German and French retail. |
| Direct-to-Subscription Platform Launch | Captures algorithmic flavor rotation retention rates exceeding conventional supermarket impulse economics. |
| USDA Organic Certification Investment | Qualifies for federal procurement preferences and retailer slotting fee reductions across US grocery channels. |
Research Methodology
Multi-period observation of frozen fruit concentrate pricing, HPP equipment deployment rates, and subscription platform retention metrics anchored the trend analysis, supplemented by interviews with smoothie brand R&D directors, grocery category buyers, foodservice procurement managers, and packaging material suppliers. Secondary validation drew from FDA labeling guidance documents, ECHA authorization list updates, USDA organic certification databases, and EU Green Deal implementation trackers. Bottom-up SKU-level velocity data triangulated against top-down category expenditure estimates.
Segment-weighting across product type, end-user application, distribution channel, and packaging material dimensions shaped the analytical framework across the projection horizon. CAGRs derived from elasticity-adjusted volume projections and price-level assumptions indexed to input cost trajectories. Forecast inputs incorporated REACH chemical safety standard evolution, sugar taxation proposal legislative tracking, and oat protein extraction yield improvement curves.
Several conditions sit outside the modeled scope, including abrupt FDA front-of-pack warning label reclassification, extreme weather disruptions in Latin American fruit growing regions, and California groundwater regulation enforcement acceleration. Forecasts reflect documented assumptions about regulatory implementation timing and consumer substitution elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market