
 Protease Enzyme Market | 2026-2036
Protease Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Protease Enzyme Market Intelligence
Specialized protein biochemists and fermentation engineers is unwinding capacity constraints across commercial-scale protease manufacturing. Novonesis leverages its integrated strain development and downstream processing capabilities to dominate microbial-derived supply. BASF sustains broad geographic coverage through multi-site enzyme production networks. Amano Enzyme specializes in high-purity pharmaceutical-grade proteases for narrow therapeutic applications.
Protease enzymes are peptide-bond-cleaving biocatalysts typically characterized by optimal activity across pH ranges from 2 to 11 and temperature stabilities up to 60°C, produced via submerged fermentation or recombinant expression in bacterial and fungal hosts for protein hydrolysis, peptide synthesis, and process intensification. Microbial-derived proteases occupy the largest volume position due to scalable fermentation economics and GRAS status for food applications, while recombinant proteases command premium positioning in pharmaceutical and biotechnology segments where batch consistency and defined impurity profiles determine regulatory acceptance. The food processing application anchors mature demand through dairy, baking, and brewing sectors, though pharmaceutical applications are expanding fastest as oral and injectable biologic formulations multiply.
FDA enforces stringent purity and host-cell protein limits for therapeutic proteases under biologic licensing pathways, while EPA monitors industrial discharge from fermentation facilities, and ISO 9001 and ISO 13485 certifications govern quality management for pharmaceutical and medical device-grade enzyme supply. EMA's MDR and REACH frameworks in Europe impose additional substance registration and clinical evidence requirements that filter market participants by compliance capability. Stakeholders must monitor evolving regulatory divergence between FDA and EMA biologic standards while calibrating manufacturing investments toward recombinant platforms that satisfy both jurisdictions.
Market Dynamics
Recombinant expression platforms are fragmenting competitive positioning between microbial fermentation incumbents and cell-culture specialists, as pharmaceutical-grade purity requirements harden under divergent FDA and EMA biologic standards.
Growth Catalysts
- Biologic formulation expansion:Oral and injectable therapeutic pipelines are multiplying demand for high-specificity proteases with defined impurity profiles.
- EU Green Deal compliance:REACH substance registration frameworks are redirecting European manufacturers toward microbial-derived production pathways with lower environmental discharge footprints.
- Contract research infrastructure:United States-based CRO capacity is compressing development timelines for novel protease applications across diagnostics and targeted therapeutics.
Market Restraints
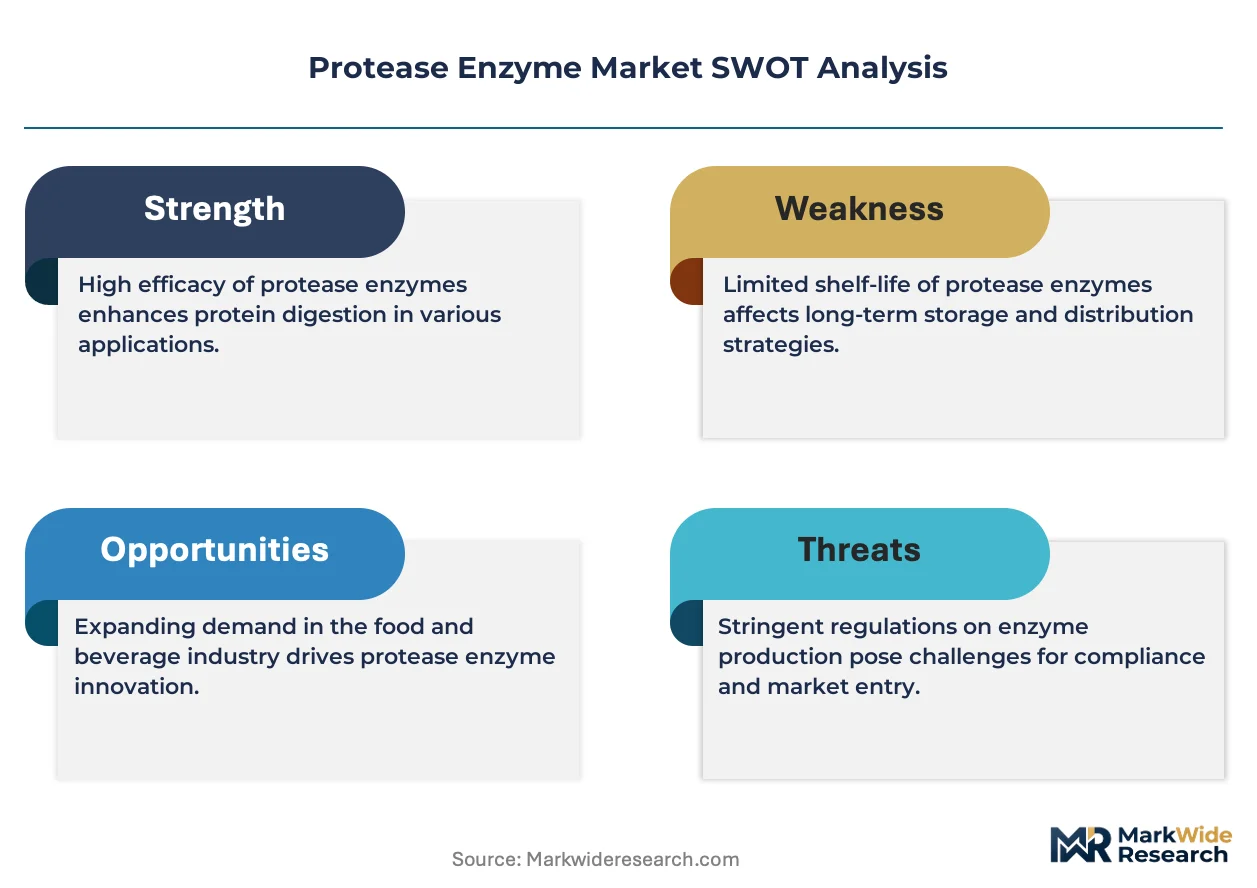
- Host-cell protein clearance costs:Downstream processing to meet FDA biologic purity limits adds 15-25% to unit production economics.
- Fermentation facility concentration:Commercial-scale capacity clusters in Denmark and Germany, creating geographic supply vulnerability.
- Protein engineering skill scarcity:Specialized strain development expertise concentrates at a handful of academic and industrial centers.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO and PLI scheme incentives are attracting protease suppliers to serve domestic biologic production.
- Continuous processing adoption:Integration of perfusion bioreactors with in-situ product removal is enabling real-time peptide synthesis applications.
- Japan regenerative medicine:PMDA accelerated approval pathways for cell-culture media components are opening premium positioning for recombinant proteases.
Industry Challenges
- ISO 13485 certification timelines:Medical device-grade enzyme qualification requires 18-24 month validation cycles that delay market entry.
- Legacy batch record systems:Pharmaceutical manufacturers face integration friction when connecting continuous bioprocessing data streams to established quality management infrastructure.
- Cross-jurisdictional regulatory divergence:EMA MDR clinical evidence requirements for therapeutic enzymes exceed FDA biologic licensing thresholds, complicating dual-market submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protease Enzyme Market |
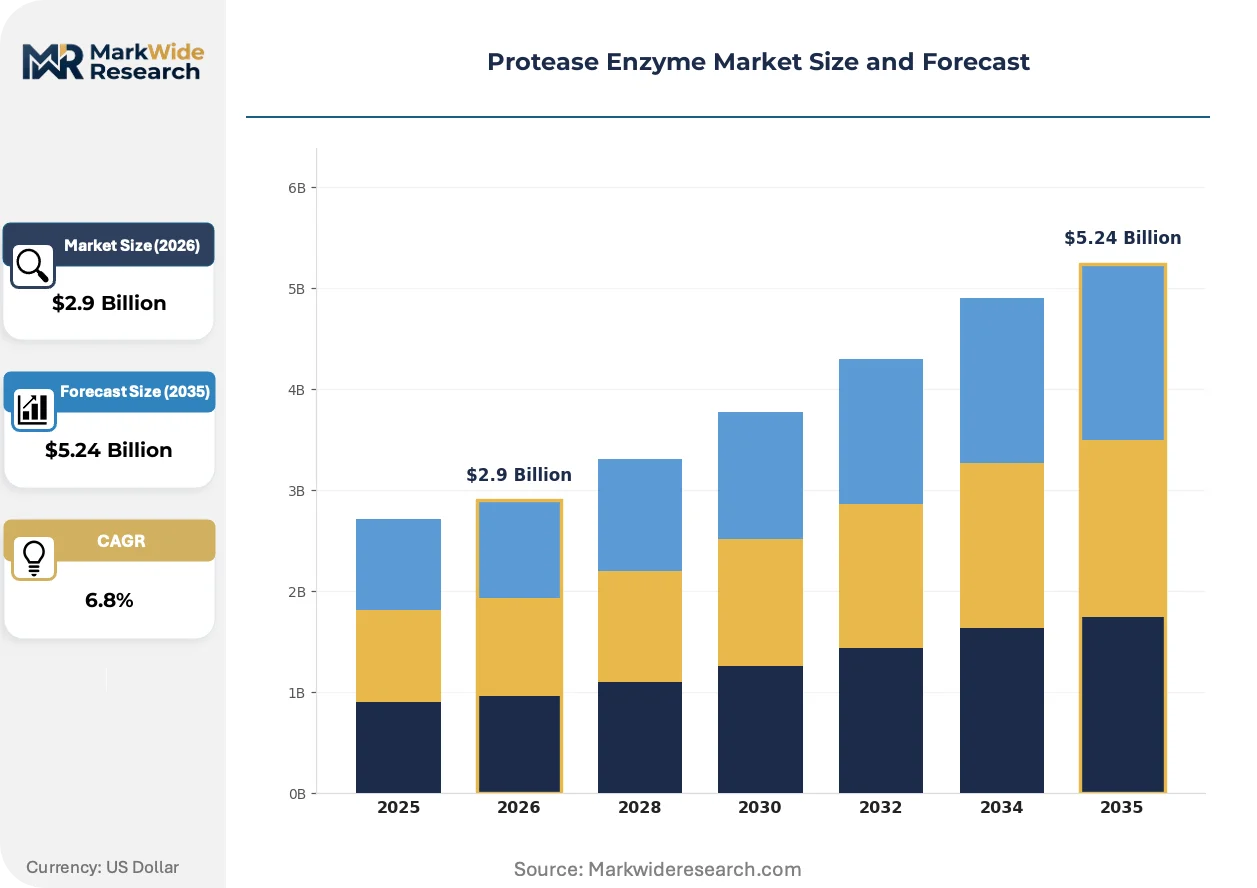
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal-Derived, Plant-Derived, Microbial-Derived, Recombinant Application: Food Processing, Pharmaceutical, Biotechnology, Animal Feed End User: Beverage Industry, Healthcare Providers, Agricultural Sector, Research Institutes Form: Liquid, Powder, Granular, Tablet |
| Companies Covered | Novonesis, International Flavors & Fragrances, DSM-Firmenich, BASF, Amano Enzyme, AB Enzymes, Advanced Enzyme Technologies, Enzyme Development Corporation, Biocatalysts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protease Enzyme Market Strategic Shifts & Innovations
Process intensification technologies and synthetic biology tools are compressing development cycles while hardening purity benchmarks, reshaping how protease suppliers compete on speed-to-regulatory-approval versus manufacturing scale.
CRISPR-guided strain engineering is bifurcating the supplier base between precision-edited microbial platforms and conventional mutagenesis-derived lines. Pharmaceutical formulators are adopting edited strains for orphan drug applications where batch consistency determines regulatory acceptance. This technology is compressing the premium tier to recombinant products while standard food-grade supply consolidates around legacy fermentation economics.
EMA's MDR implementation is tightening clinical evidence requirements for enzyme-containing medical devices across Europe. Manufacturers must now generate patient-outcome data that exceeds prior bench-validation standards. Wound care and diagnostic segments are responding by consolidating supplier relationships toward partners with dedicated regulatory affairs capabilities.
Biopharma procurement teams are unbundling enzyme supply from bundled media formulations, forcing standalone protease suppliers to compete on unit economics rather than integrated portfolio pricing. CDMOs and emerging biotechs are driving this disintermediation through direct sourcing mandates. The shift is most visible in United States coastal clusters where venture-backed biologics startups prioritize cost transparency over incumbent relationships.
Protease Enzyme Market Segmentation
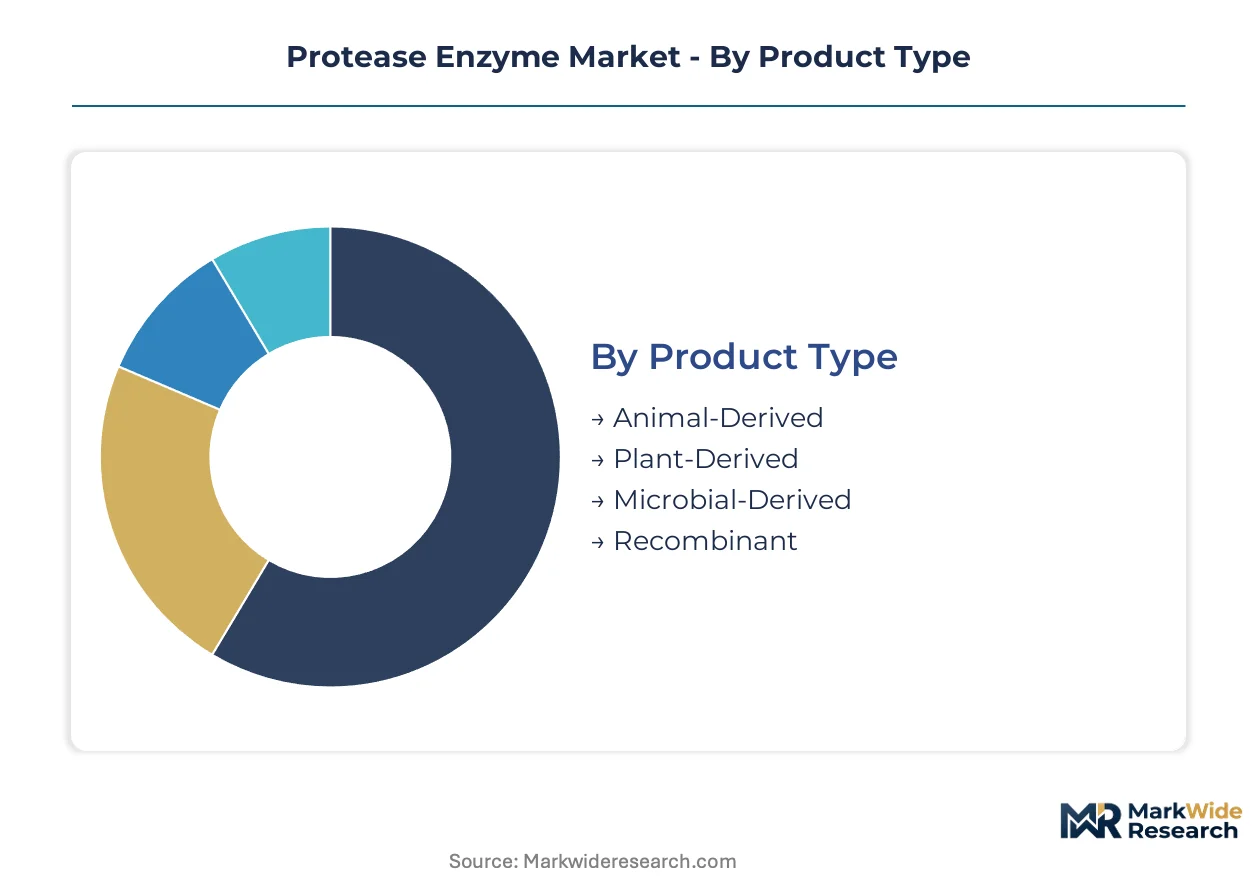
Protease enzyme procurement channels bifurcate sharply between commodity fermentation supply and regulated pharmaceutical pathways. Each segment carries distinct certification burdens, pricing tiers, and customer qualification requirements that reshape competitive positioning across the value chain.
Product Type:
Channel distribution varies dramatically by production biology, with fermentation-derived supply flowing through industrial distributors while recombinant lines require direct pharmaceutical contracting.
- Animal-Derived:Extracted from pancreatic tissues and glandular sources, these proteases retain complex glycosylation patterns that complicate regulatory documentation. Demand concentrates in legacy pharmaceutical formulations across Western European markets where EMA's TSE/BSE guidance demands extensive sourcing traceability, constraining supplier flexibility.
- Microbial-Derived:Submerged fermentation of Bacillus and Aspergillus strains delivers scalable neutral and alkaline proteases with GRAS status for food applications. Dairy and baking manufacturers in the United States source these through bulk chemical distributors, with FDA food additive compliance enabling rapid formulation integration without premarket approval burdens.
- Plant-Derived:Papain from Carica papaya latex and bromelain from Ananas comosus stems serve niche tenderizing and nutraceutical applications. Latin American extraction facilities supply North American meat processors through specialized enzyme houses.
- Recombinant:Precision-engineered microbial hosts produce defined-sequence proteases with batch-to-batch consistency mandatory for biologic drug manufacturing. Contract manufacturers in Denmark and Germany dominate supply to FDA-approved facilities.
By volume, Microbial-Derived leads. By growth pace, Recombinant is ahead.
Application:
End-use economics separate mature process industries from emerging therapeutic segments on margin structure and technical service intensity.
- Food Processing:Dairy coagulation, baking dough conditioning, and brewing filtration consume bulk alkaline and neutral proteases. United States cheese manufacturers represent the largest single demand concentration, with Wisconsin and California processing clusters driving regional supply contracts.
- Pharmaceutical:Oral digestive aids, wound debridement, and injectable biologic processing require pharmaceutical-grade certification under FDA biologic licensing or EMA MDR pathways. Parenteral applications command the steepest purity premiums.
- Biotechnology:Cell-culture media supplementation and protein characterization reagents demand recombinant proteases with documented absence of adventitious agents. Academic core facilities and CDMOs in Boston and San Francisco anchor demand.
- Animal Feed:Exogenous protease supplementation improves amino acid digestibility in poultry and swine rations. Brazilian integrated protein producers represent expanding demand as ANVISA feed enzyme registration pathways mature.
Food Processing generates the greatest tonnage. Pharmaceutical applications deliver the steepest margin expansion.
End User:
Customer scale and technical sophistication determine whether supply flows through distribution or direct manufacturer relationships.
- Beverage Industry:Brewing and juice clarification applications favor liquid protease concentrates delivered in bulk totes. Major multinational brewers negotiate frame contracts directly with Novonesis and BASF.
- Healthcare Providers:Hospital pharmacies and wound care clinics source medical device-grade proteases through specialized distributors with cold-chain capabilities. EMA MDR implementation has consolidated supplier panels toward ISO 13485-certified manufacturers.
- Agricultural Sector:Feed mills and integrated livestock operations purchase proteases as premix components. Indian poultry integrators under PLI scheme incentives are expanding domestic enzyme procurement.
- Research Institutes:Academic and government laboratories procure small-volume, high-activity proteases through scientific distributors. NIH-funded facilities in Maryland and California represent concentrated demand for sequencing-grade products.
Beverage Industry procurement runs largest by volume. Healthcare Providers are climbing fastest on therapeutic biologic expansion.
Form:
Physical presentation dictates packaging, stability requirements, and downstream handling economics across customer segments.
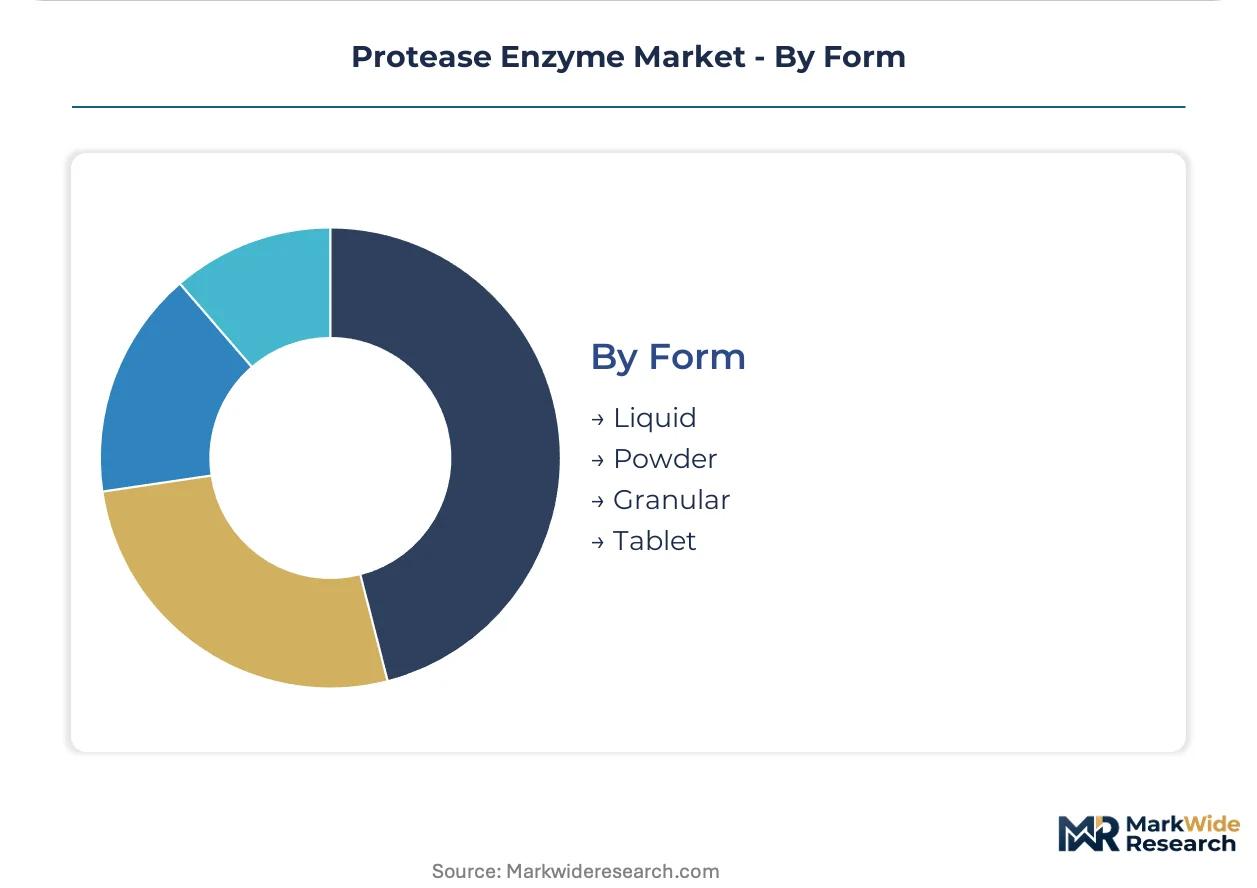
- Liquid:Standardized activity concentrates in stabilized aqueous solutions serve continuous manufacturing processes. Dairy and beverage applications favor this format for automated dosing integration.
- Powder:Spray-dried formulations with carbohydrate carriers enable extended ambient storage. Baking premix manufacturers prefer powders for dry-blend compatibility.
- Granular:Dust-free, free-flowing granules reduce occupational exposure and improve dispersion in feed applications. Pelleting stability requirements favor this form for animal nutrition.
- Tablet:Enteric-coated and immediate-release oral dosage forms deliver defined activity units for digestive health and systemic enzyme therapy. FDA OTC monograph compliance governs United States retail distribution.
Powder dominates by shipment volume. Tablet formulations are gaining share fastest on nutraceutical and therapeutic oral delivery expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumption tilts toward pharmaceutical-grade recombinant proteases, while India and Brazil concentrate demand in food processing and animal feed applications. This demand-mix differential shapes regulatory priorities and supplier certification requirements across major markets.
United States
FDA-approved biologic manufacturing and contract research infrastructure drive pharmaceutical protease procurement. The agency enforces stringent host-cell protein limits under biologic licensing pathways. Boston and San Francisco biotechnology clusters anchor demand for sequencing-grade recombinant products.
Germany
Industrial enzyme production networks and REACH compliance frameworks redirect manufacturers toward microbial-derived pathways. EMA's MDR implementation tightens clinical evidence requirements for therapeutic applications. Bavarian fermentation facilities concentrate commercial-scale supply capacity.
India
Domestic biologic production expansion and poultry integrator growth under PLI scheme incentives attract protease suppliers. CDSCO registration pathways govern pharmaceutical-grade imports. Maharashtra and Gujarat processing clusters drive regional procurement concentration.
Japan
Regenerative medicine advancement and cell-culture media component demand open premium positioning for recombinant proteases. PMDA accelerated approval pathways reduce time-to-market for qualifying products. Kanto region biotechnology infrastructure anchors specialized supply relationships.
Brazil
Integrated protein producers and feed enzyme registration maturation expand exogenous protease supplementation in poultry and swine rations. ANVISA regulatory pathways formalize import quality standards. São Paulo state agricultural processing concentration drives volume procurement.
Protease Enzyme Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in protease enzyme supply. Novonesis and BASF occupy positions with multi-site production networks and strain development capabilities. The specialist tier comprises regional fermentation houses and application-focused formulators. Consolidation pressures intensify as pharmaceutical purity requirements harden and food-grade margins compress. Strategic moves center on recombinant platform licensing and geographic expansion into Indian pharmaceutical manufacturing.
Among Denmark-based integrated suppliers, Novonesis exemplifies the vertically positioned archetype spanning microbial fermentation through downstream processing. German chemical conglomerate BASF occupies a position emphasizing broad geographic coverage and industrial-scale supply security. Japanese specialist Amano Enzyme represents the high-purity pharmaceutical-grade tier focused on narrow therapeutic applications. These three anchors illustrate how competitive positioning fragments between scale-driven fermentation economics and premium recombinant precision.
| Leading Market Players |
|---|
| Novonesis |
| International Flavors & Fragrances |
| DSM-Firmenich |
| BASF |
| Amano Enzyme |
| AB Enzymes |
| Advanced Enzyme Technologies |
| Enzyme Development Corporation |
| Biocatalysts |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Danish fermentation houses and United States biologic manufacturers lock in multi-year supply access while capping price visibility for downstream pharmaceutical formulators facing FDA purity mandates.
Pricing Analysis
Contract-based long-term offtake dominates pharmaceutical-grade procurement, with three-tier pricing structure across premium, standard, and economy levels separating recombinant biologic-grade from microbial food-grade and feed-grade supply. Price differentiation hinges on ISO 13485 certification tier and volume scale, with parenteral applications commanding substantial premiums over oral formulations. Cost compression in standard-grade microbial supply is intensifying because Brazilian and Indian integrators are consolidating procurement volumes. Animal feed manufacturers exhibit highest price sensitivity, while biotechnology CDMOs prioritize batch consistency over unit economics.
Supply Chain Analysis
Six-to-nine month lead times for pharmaceutical-grade recombinant proteases reflect fermentation campaign scheduling and downstream validation bottlenecks at Danish and German production hubs. Supply concentrates in Denmark, Germany, and the United States, with raw material dependencies on defined yeast extract, soy peptone, and chromatography resin inputs. Single-source vulnerability runs through specialized strain banks held by integrated incumbents. Distribution runs through direct manufacturer relationships for pharmaceutical tiers and bulk chemical distributors for food-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as biopharma procurement teams disaggregate enzyme supply from bundled media formulations, creating niches for standalone suppliers with regulatory documentation capabilities.
For Market Incumbents: Compound defensive positioning through backward integration into precision strain engineering capabilities and capacity addition in Maharashtra to capture Indian pharmaceutical manufacturing expansion. Novonesis and BASF face emerging pressure from recombinant specialists targeting orphan drug applications with CRISPR-edited platforms. For New Entrants and Emerging Players: Anchor in Japan's regenerative medicine segment, where PMDA accelerated approval pathways reduce qualification timelines for cell-culture media components. White-space exists in continuous processing enzyme supply for real-time peptide synthesis applications, with go-to-market through Boston and San Francisco biotechnology cluster direct sourcing mandates. For Investors and Strategic Acquirers: Capital is best deployed toward recombinant platform specialists with existing ISO 13485 certification and documented regulatory affairs capabilities across both FDA and EMA jurisdictions. Long-term viability centers on dual-jurisdiction compliance infrastructure as biologic formulation pipelines expand. Signal to watch is consolidation of supplier panels by wound care and diagnostic device manufacturers responding to EMA MDR clinical evidence requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Platform Licensing | Enables rapid FDA biologic licensing pathway access for emerging therapeutic applications. |
| ISO 13485 Certification Investment | Qualifies supply for EMA MDR medical device-grade procurement panels consolidating relationships. |
| Continuous Processing Integration | Supports perfusion bioreactor adoption with in-situ product removal for real-time synthesis. |
| Geographic Expansion into India | Captures CDSCO-registered pharmaceutical manufacturing growth under PLI scheme incentives. |
| CRISPR Strain Engineering Acquisition | Accelerates precision-edited microbial platform development for orphan drug consistency requirements. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with fermentation engineers, pharmaceutical procurement directors, regulatory affairs specialists, and biotechnology CDMO supply chain managers; and secondary validation through FDA biologic licensing databases, EMA MDR submission records, CDSCO registration filings, and SEC 10-K disclosures from enzyme manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across production biology, application, and geographic concentration dimensions.
Across the analysis window, the analytical framework modeled segmentation by product type, application, end user, and physical form, with CAGRs derived from production capacity expansion announcements and therapeutic pipeline advancement rates. Forecast inputs incorporated strain development cycle compression from synthetic biology tool adoption and regulatory divergence patterns between FDA and EMA biologic standards.
Material uncertainties — regulatory timeline acceleration, host-cell protein clearance technology breakthroughs, and geographic supply concentration disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions on fermentation yield improvements and pharmaceutical formulation pipeline maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
White Biotechnology Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Xylanase Market