
 Japan Biocatalyst Market | 2026-2036
Japan Biocatalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Biocatalyst Market Intelligence
JIS K 7253 certification for industrial enzyme characterization is rotating supplier qualification toward laboratories with validated assay capabilities. Amano Enzyme leverages decades of fermentation expertise to dominate specialty hydrolase supply. Kaneka anchors its position through backward integration into microbial strain development. Nagase ChemteX competes across food-grade and pharmaceutical-grade enzyme segments with differentiated immobilization platforms.
Biocatalysts comprise enzymes, whole cells, or engineered biological systems that accelerate chemical transformations under mild conditions, typically operating at temperatures below 60°C and near-neutral pH to preserve substrate integrity. Their primary industrial purpose is replacing metal-catalyzed or high-pressure processes in pharmaceutical intermediate synthesis, agricultural active ingredient production, and food modification. Enzymes command the largest product share due to established supply chains and predictable scale-up pathways, while engineered biocatalysts capture expanding margin pools as directed evolution platforms shorten development cycles. Pharmaceutical applications lead absolute demand, though biofuels represent the fastest-growing application segment as refiners seek enzymatic routes to meet METI renewable fuel mandates.
PMDA quality guidelines for biocatalytic pharmaceutical processes, METI's sustainable chemistry roadmap, and JIS industrial enzyme standards collectively shape product registration timelines and manufacturing site qualification requirements. Compliance with PMDA biocatalytic step validation protocols now determines market access for API suppliers, while METI incentives reward facilities achieving enzymatic process substitution thresholds. Stakeholders must monitor evolving PMDA guidance on continuous biocatalytic manufacturing and assess whether Kanto-based production assets can absorb demand from Osaka's expanding pharmaceutical cluster without capacity bottlenecks.
Market Dynamics
METI's sustainable chemistry roadmap is compressing process substitution timelines, forcing pharmaceutical and fine chemical manufacturers to accelerate enzymatic route validation ahead of regulatory deadlines. This policy pressure is restructuring supplier qualification priorities across Japan's production clusters.
Growth Catalysts
- Green chemistry mandates:METI's enzymatic process substitution incentives reward facilities achieving threshold conversion rates, redirecting capital toward biocatalytic infrastructure.
- API synthesis demand:Pharmaceutical manufacturers in the Kanto region are expanding biocatalyst adoption for complex intermediate production to reduce solvent waste.
- JIS K 7253 standardization:Validated industrial enzyme characterization protocols are consolidating supplier qualification around certified testing capabilities.
Market Restraints
- Fermentation input volatility:Specialty media component costs fluctuate with agricultural commodity markets, squeezing margin predictability for hydrolase producers.
- Strain development concentration:Proprietary microbial platform ownership concentrates among integrated manufacturers, limiting contract biocatalyst access.
- Thermal stability limitations:Wild-type enzymes degrade above 60°C, restricting application in high-temperature process streams without costly engineering.
Strategic Opportunities
- Osaka pharmaceutical expansion:The Kansai region's growing API manufacturing base lacks local biocatalyst production capacity, creating supply gap capture potential.
- Continuous manufacturing convergence:Integration of flow chemistry with immobilized enzyme systems enables real-time quality control and reduced batch variability.
- Biofuel mandate acceleration:METI renewable fuel targets are driving refiner demand for enzymatic transesterification catalysts in coastal processing facilities.
Industry Challenges
- PMDA validation timelines:Biocatalytic step change control protocols require 18-24 month qualification cycles, delaying process transfer to commercial scale.
- Directed evolution expertise scarcity:Protein engineering talent pools concentrate in university-corporate partnerships, constraining mid-tier developer access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Biocatalyst Market |
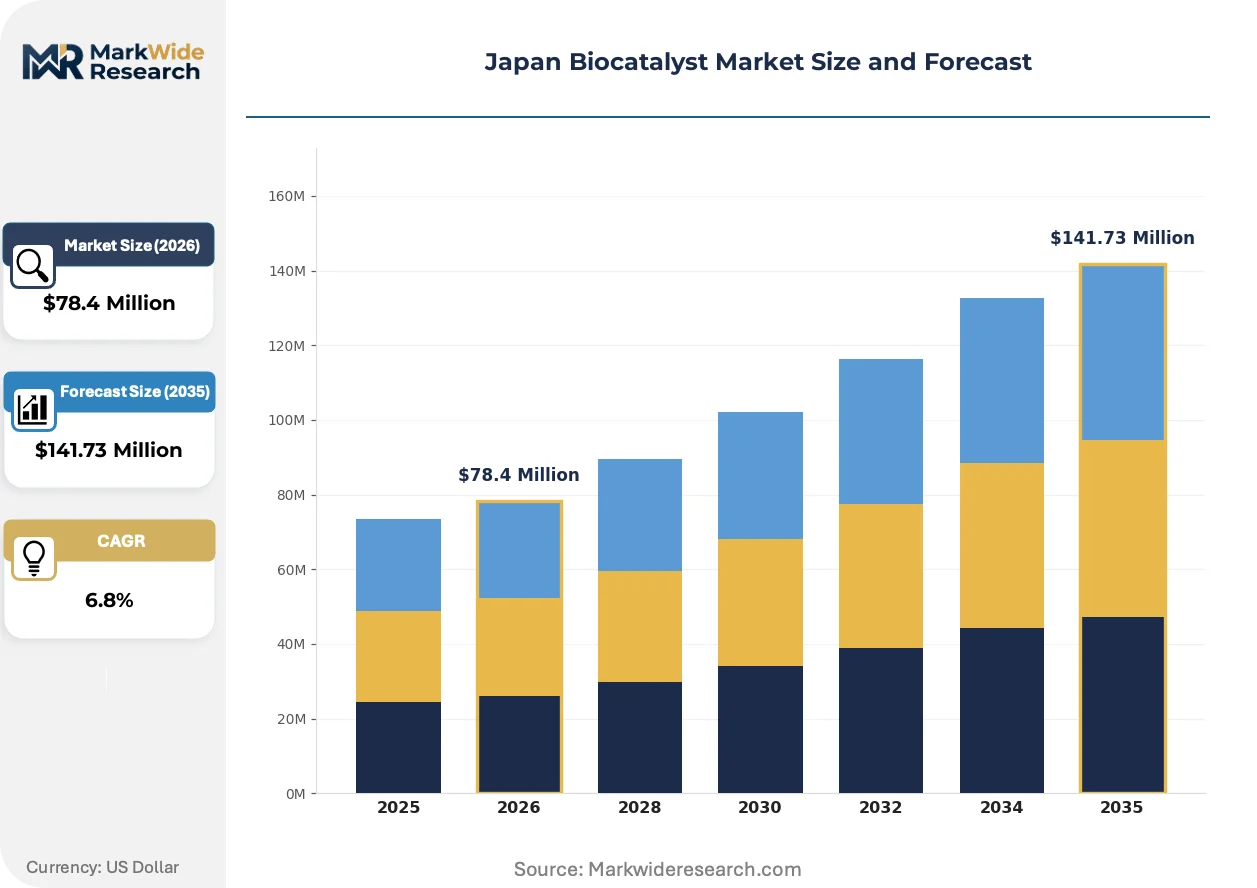
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Whole Cells, Natural Biocatalysts, Engineered Biocatalysts Application: Pharmaceuticals, Agriculture, Food Processing, Biofuels Technology: Biotransformation, Fermentation, Immobilization, Screening End User: Pharmaceutical Companies, Research Institutions, Agricultural Firms, Food Manufacturers |
| Companies Covered | Sumitomo Chemical, Kaneka, Amano Enzyme, FIMECS, PeptiDream, Nagase ChemteX, Chugai Pharmaceutical, Metagen Therapeutics, Mitsubishi Chemical Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Biocatalyst Market Strategic Shifts & Innovations
Process intensification technologies are compressing development cycles, while regulatory validation frameworks evolve to accommodate continuous biocatalytic manufacturing. These shifts are redrawing competitive boundaries between established enzyme suppliers and technology-integrated pharmaceutical contractors.
Directed evolution platforms are fragmenting the traditional enzyme development hierarchy. These systems enable rapid generation of thermostable and solvent-tolerant variants previously requiring years of screening. Pharmaceutical process development groups are adopting in-house evolution capabilities to protect proprietary route intellectual property. The technology is fragmenting supplier relationships as manufacturers internalize strain optimization rather than purchasing off-catalog biocatalysts.
PMDA guidance on continuous biocatalytic manufacturing is reshaping facility qualification requirements. The regulator's draft protocols for real-time release testing reduce reliance on end-point batch analysis. API manufacturers in the Kanto cluster are reconfiguring quality systems to accommodate in-process analytical technology integration. This regulatory evolution favors suppliers capable of delivering consistent immobilized enzyme performance over extended operational windows.
Certification-driven procurement is consolidating purchasing authority around JIS-compliant testing laboratories. Pharmaceutical quality departments now require documented assay validation for enzyme activity and impurity profiles before supplier approval. This behavioral shift displaces informal technical relationships with formalized qualification pathways. The pattern is most pronounced among Osaka-based generic API producers seeking export market access.
Japan Biocatalyst Market Segmentation
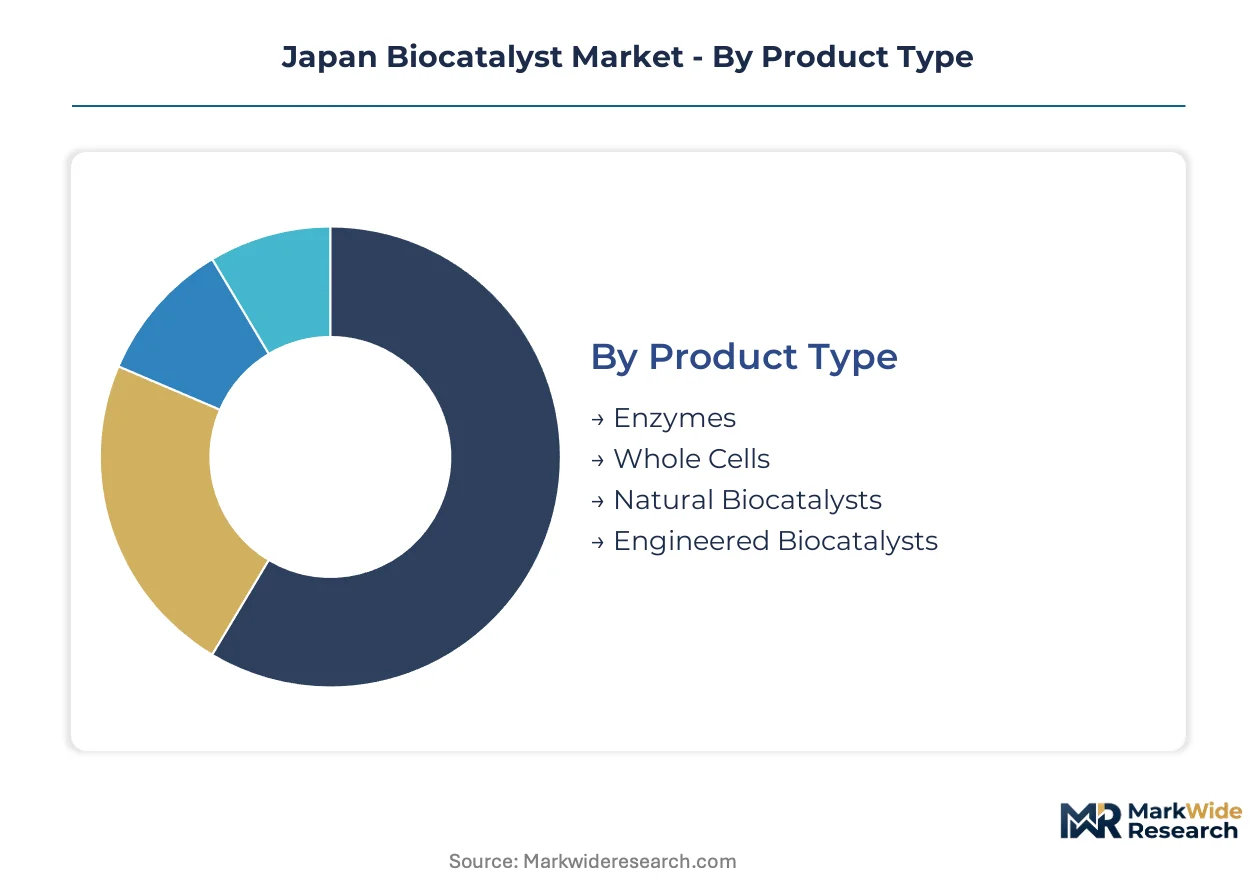
Japan's biocatalyst market segments along technical, application, and customer dimensions that determine procurement authority and margin capture. Understanding where value concentrates across these categories reveals which supplier capabilities command pricing power versus commodity competition.
Product Type:
Margin pools concentrate in engineered variants and specialty enzymes where proprietary strain development creates supply scarcity.
- Enzymes:Isolated proteins catalyzing specific biochemical reactions with established characterization protocols under JIS K 7253. Demand concentrates in Kanto pharmaceutical clusters where API manufacturers seek validated hydrolase supply for intermediate synthesis amid METI green chemistry compliance deadlines.
- Engineered Biocatalysts:Directed evolution and rational design platforms produce thermostable, solvent-tolerant variants with tailored substrate specificity. Osaka-based generic API producers are rotating procurement toward these capabilities to access export markets requiring documented biocatalytic step validation.
- Whole Cells:Intact microbial systems performing multi-step transformations without enzyme isolation.
- Natural Biocatalysts:Unmodified biological catalysts sourced from environmental isolates and traditional fermentation.
Enzymes hold installed capacity. Engineered Biocatalysts is rotating up the share rankings.
Application:
Revenue concentration tracks regulatory pressure intensity across end-use sectors.
- Pharmaceuticals:Biocatalytic routes for chiral intermediate and API synthesis under PMDA quality guidelines. Kanto-region manufacturers dominate demand as solvent waste reduction targets and continuous manufacturing adoption compress process validation timelines.
- Biofuels:Enzymatic transesterification and cellulosic ethanol processing to meet METI renewable fuel mandates. Coastal refiners in Chiba and Yokkaichi are expanding capacity fastest as mandate acceleration creates supply gap capture potential.
- Agriculture:Biocatalytic production of crop protection actives and growth regulators.
- Food Processing:Enzyme-based modification for texture, flavor, and nutritional enhancement.
Pharmaceuticals anchors revenue concentration. Biofuels is expanding most quickly as mandate pressure intensifies.
Technology:
Process control capabilities differentiate supplier positioning across the technology stack.
- Fermentation:Upstream microbial cultivation and enzyme production at scale with strain optimization. Amano Enzyme and Kaneka concentrate proprietary platform ownership here, limiting contract access for mid-tier developers.
- Immobilization:Enzyme stabilization on solid supports for continuous operation and reusability. Nagase ChemteX competes through differentiated platform architectures that enable extended operational windows for flow chemistry integration.
- Biotransformation:Single-step or cascade enzymatic conversions of target substrates.
- Screening:High-throughput identification of catalytic activity from diverse biological libraries.
Fermentation commands upstream value capture. Immobilization is climbing the fastest as continuous manufacturing adoption accelerates.
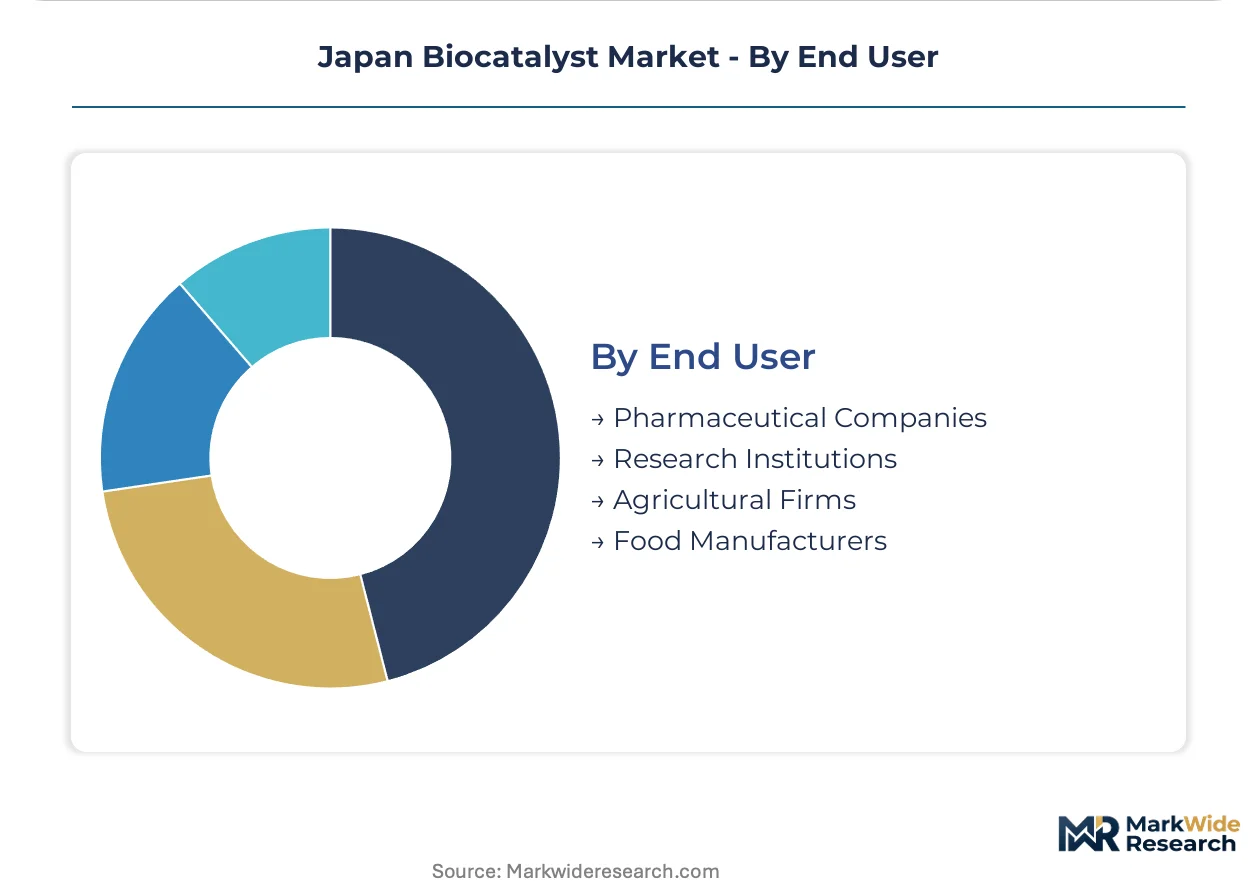
End User:
Procurement sophistication and validation requirements segment customer value tiers.
- Pharmaceutical Companies:Integrated API manufacturers and CDMOs requiring PMDA-compliant biocatalytic process validation. Quality departments in Tokyo and Osaka clusters now mandate JIS-certified assay documentation before supplier approval, displacing informal technical relationships.
- Research Institutions:Universities and national laboratories conducting directed evolution and pathway engineering. Protein engineering talent scarcity concentrates in university-corporate partnerships, constraining independent mid-tier developer access.
- Agricultural Firms:Crop science companies seeking biocatalytic routes to active ingredients.
- Food Manufacturers:Processors deploying enzymes for product modification and quality control.
Pharmaceutical Companies dominate procurement volume. Research Institutions are gaining influence fastest as in-house evolution capabilities fragment traditional supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality departments in Japan's two major production clusters drive biocatalyst procurement authority. Kanto-region API manufacturers dominate current demand volume, while Osaka's expanding generic sector is rotating qualification priorities toward JIS-certified suppliers.
Kanto/Tokyo
Specialty hydrolase demand concentrates in Chiba and Kanagawa pharmaceutical corridors where solvent waste reduction targets compress process validation timelines. METI's green chemistry roadmap rewards enzymatic substitution thresholds with facility certification advantages. Tokyo's fine chemical cluster is absorbing expanded biocatalytic capacity for complex chiral intermediate production.
Kansai/Osaka
Generic API producers are rotating procurement toward engineered biocatalysts to access export markets requiring PMDA-compliant step documentation. The region lacks captive fermentation capacity, creating supply gap exposure for contract biocatalyst access. Osaka-based quality departments now mandate JIS K 7253 assay validation before supplier approval, displacing informal technical relationships.
Chubu/Nagoya
Automotive and industrial chemical manufacturers anchor steady demand for immobilized enzyme systems in specialty polymer modification. Regional production assets are reconfiguring for continuous manufacturing integration as PMDA draft guidance on real-time release testing matures. Nagoya's materials science cluster is piloting flow chemistry-enzyme hybrid platforms for process intensification.
Kyushu
Coastal biofuel refiners in Fukuoka and Oita prefectures are expanding enzymatic transesterification capacity to meet METI renewable fuel mandate acceleration. Agricultural commodity proximity reduces specialty media input volatility for regional fermentation operations. Kyushu's industrial biotech base is capturing mandate-driven demand as coastal processing facilities seek enzymatic route qualification.
Japan Biocatalyst Market Key Industry Players
Player mix skews toward integrated chemical conglomerates with proprietary microbial platforms and specialized enzyme houses with decades of fermentation heritage. Market structure concentrates upstream value capture among three domestic incumbents controlling strain development and industrial-scale production. Two strategic archetypes dominate: backward-integrated chemical majors leveraging captive biotech capacity, and focused enzyme specialists competing through differentiated immobilization architectures. Competitive dynamics center on JIS certification acquisition and directed evolution capability internalization.
Within the integrated chemical tier, Kaneka and Sumitomo Chemical occupy positions anchored by decades of microbial platform ownership. Amano Enzyme exemplifies the specialist archetype, competing through validated hydrolase supply relationships with Kanto-region pharmaceutical manufacturers. Nagase ChemteX sits within a hybrid position, spanning food-grade and pharmaceutical-grade segments with platform differentiation. These three anchors represent the supplier qualification consolidation that JIS K 7253 standardization is accelerating across procurement departments.
| Leading Market Players |
|---|
| Sumitomo Chemical |
| Kaneka |
| Amano Enzyme |
| FIMECS |
| PeptiDream |
| Nagase ChemteX |
| Chugai Pharmaceutical |
| Metagen Therapeutics |
| Mitsubishi Chemical Group |
| Others |
Cost & Logistics Intelligence
Fermentation scale economies at Amano Enzyme and Kaneka facilities anchor supply concentration in the Kanto corridor, compressing unit economics for specialty hydrolases while elevating price floors for mid-tier contract manufacturers lacking captive strain platforms. METI green chemistry compliance deadlines intensify buyer competition for JIS K 7253 certified supply, amplifying pricing power among integrated producers with validated assay capabilities.
Pricing Analysis
Cost-plus contracts indexed to agricultural commodity benchmarks dominate long-term supply agreements between Kanto pharmaceutical manufacturers and domestic enzyme houses. Three-tier pricing structure across premium, standard, and economy levels stratifies by JIS certification grade and immobilization platform sophistication. Pricing pressure stems from Osaka generic API producers negotiating volume discounts to offset PMDA validation cost burdens. Contract biocatalyst buyers exhibit highest price sensitivity, while integrated pharmaceutical manufacturers prioritize supply security over unit cost optimization.
Supply Chain Analysis
Specialty media component sourcing through the Tsugaru Strait shipping lane concentrates input vulnerability for Kanto fermentation operations, with soy-derived peptone and yeast extract shipments drawing from Chinese and Southeast Asian agricultural processors. Proprietary microbial strain ownership rests with Kaneka, Amano Enzyme, and Sumitomo Chemical, creating single-source dependency for thermostable variant supply. Tariff exposure on imported fermentation feedstocks threatens margin stability for non-integrated producers. Distribution runs through direct technical sales relationships with pharmaceutical quality departments, displacing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Osaka-based generic API producers consolidating procurement authority around JIS-certified suppliers, fragmenting informal technical relationships that previously sustained mid-tier enzyme houses.
For Market Incumbents: Compound defensive positioning through backward integration into directed evolution platforms and JIS K 7253 assay certification investment. Emerging contract biocatalyst developers threaten margin pools in standard-grade hydrolase supply. Priority leverage rests on immobilization platform differentiation for continuous manufacturing integration. For New Entrants and Emerging Players: Anchor in the Kansai supply gap for engineered biocatalysts serving export-oriented generic API producers. White-space concentrates in thermostable lipase supply for biofuel transesterification at Kyushu coastal refiners. Go-to-market execution should emphasize PMDA step validation documentation bundled with technical transfer services. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-integrated specialists with proprietary strain libraries over commodity fermentation operators. Five-to-ten year viability hinges on continuous manufacturing adoption trajectories. Acquisition targets should display immobilization architecture IP and established pharmaceutical quality relationships. Monitor PMDA draft guidance finalization as inflection signal for facility reconfiguration spending.| Strategic Initiative | Industry Significance |
|---|---|
| JIS K 7253 Certification Investment | Validates assay capabilities for pharmaceutical quality department procurement approval. |
| Directed Evolution Platform Integration | Accelerates thermostable variant development for METI process substitution mandates. |
| Osaka Technical Sales Office Establishment | Captures Kansai generic API producer demand lacking local biocatalyst production. |
| Continuous Manufacturing Partnership | Aligns immobilized enzyme supply with PMDA real-time release testing protocols. |
| Biofuel Refiner Supply Agreement | Secures long-term offtake from Kyushu coastal facilities under METI renewable fuel targets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fermentation process engineers, pharmaceutical quality directors, PMDA regulatory consultants, and METI policy officers; and secondary validation through JIS standard documentation, PMDA guidance releases, METI sustainable chemistry roadmap filings, and customs trade data for industrial enzyme imports. Bottom-up demand modeling triangulated against top-down capacity estimates from domestic fermentation facility disclosures.
Across the analysis window, forecasts employed segmented modeling across product type, application, technology tier, and end-user sophistication dimensions. CAGRs derived from regression analysis of historical substitution rates against METI policy intensity metrics. Industry-specific inputs incorporated PMDA validation timeline distributions and directed evolution platform adoption curves among Kanto pharmaceutical manufacturers.
Underlying assumptions cover METI mandate enforcement continuity and PMDA guidance stability, with deviation risk concentrated in agricultural commodity price volatility affecting fermentation input costs. Practitioners should keep alternative scenarios live as renewable fuel mandate acceleration timelines and continuous manufacturing regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Beta-Glucanase Market