
 Marine Enzymes Market | 2026-2036
Marine Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Enzymes Market Foresight
Norway's Arctic bioprospecting infrastructure is narrowing the supply gap for psychrophilic enzymes. Novozymes A/S leverages its Danish fermentation platform to sustain commercial-scale lipase output. BASF SE anchors European distribution through specialized biocatalysis partnerships. ArcticZymes Technologies ASA differentiates via proprietary cold-water sourcing protocols from Tromsø-based operations.
Marine enzymes comprise biocatalysts extracted from extremophile organisms inhabiting oceanic environments, typically functioning at sub-ambient temperatures or elevated salinity with specific activity thresholds measured in international units per milligram. These proteins catalyze industrial transformations where terrestrial equivalents denature, particularly in food processing and pharmaceutical intermediate manufacturing. Proteases command the largest revenue pool due to established meat tenderization and dairy applications, while lipases exhibit the fastest trajectory as biodiesel producers adopt enzymatic transesterification to replace alkaline catalysts. Healthcare applications concentrate margin capture among contract manufacturers serving FDA-regulated drug substance programs.
EMA guidelines on biocatalytic process validation and REACH registration requirements for novel protein isolates jointly determine market access timelines for European suppliers. EPA bioprospecting permits and FDA Generally Recognized As Safe notifications shape US commercialization pathways for marine-derived food enzymes. Stakeholders must weigh Arctic access agreements against cell-free synthesis alternatives as sourcing constraints intensify.
Market Dynamics
Arctic bioprospecting access agreements are tightening as territorial waters face competing claims from research consortia and commercial harvesters. This jurisdictional friction concentrates extraction rights among entities with established Tromsø and Svalbard logistics networks.
Growth Catalysts
- REACH Green Chemistry Mandates:ECHA registration pathways favor enzymatic processes over petrochemical catalysts in pharmaceutical intermediate manufacturing. European API producers now specify marine biocatalysts in tender documents.
- Biodiesel Transesterification Switch:Enzymatic processing eliminates alkaline wastewater streams. Nordic and Baltic refiners retrofit continuous-flow reactors for cold-adapted lipase feeds.
- Japan:METI biomanufacturing roadmaps designate extremophile enzymes as strategic inputs for precision fermentation platforms. Domestic biotech firms secure exclusive Arctic sourcing partnerships.
Market Restraints
- Arctic Harvest Volatility:Sea ice retreat alters sampling site accessibility. Seasonal extraction windows compress to 90-120 days for psychrophile collection.
- Cell-Free Synthesis Competition:In vitro protein production bypasses organism-dependent supply chains. Synthetic biology platforms achieve comparable specific activity at laboratory scale.
- EMA Novel Protein Validation:Biocatalytic process qualification requires 18-24 month stability dossiers. Small-batch enzyme suppliers lack resources for full pharmaceutical-grade documentation.
Strategic Opportunities
- India:CDSCO fast-track pathways for enzymatic APIs attract contract manufacturers. PLI scheme subsidies offset fermentation infrastructure capex for marine enzyme production.
- CRISPR-Enhanced Enzyme Engineering:Directed evolution platforms accelerate thermostability improvements. Hybrid natural-synthetic biocatalysts access industrial temperature ranges.
- Direct-to-Brewery Distribution:Food-grade lipase and protease sales bypass traditional chemical distributor markups. Craft brewing clusters in Scandinavia and Pacific Northwest establish captive supply relationships.
Industry Challenges
- Cryopreservation Logistics:Maintaining enzyme activity through cold-chain transport requires liquid nitrogen infrastructure. Remote Arctic collection points lack reliable cryogenic shipping corridors.
- Bioprospecting Permit Backlogs:EPA and national Arctic research authorities process sampling applications through 8-14 month queues. Expedited commercial licenses carry 300-400% fee premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Enzymes Market |
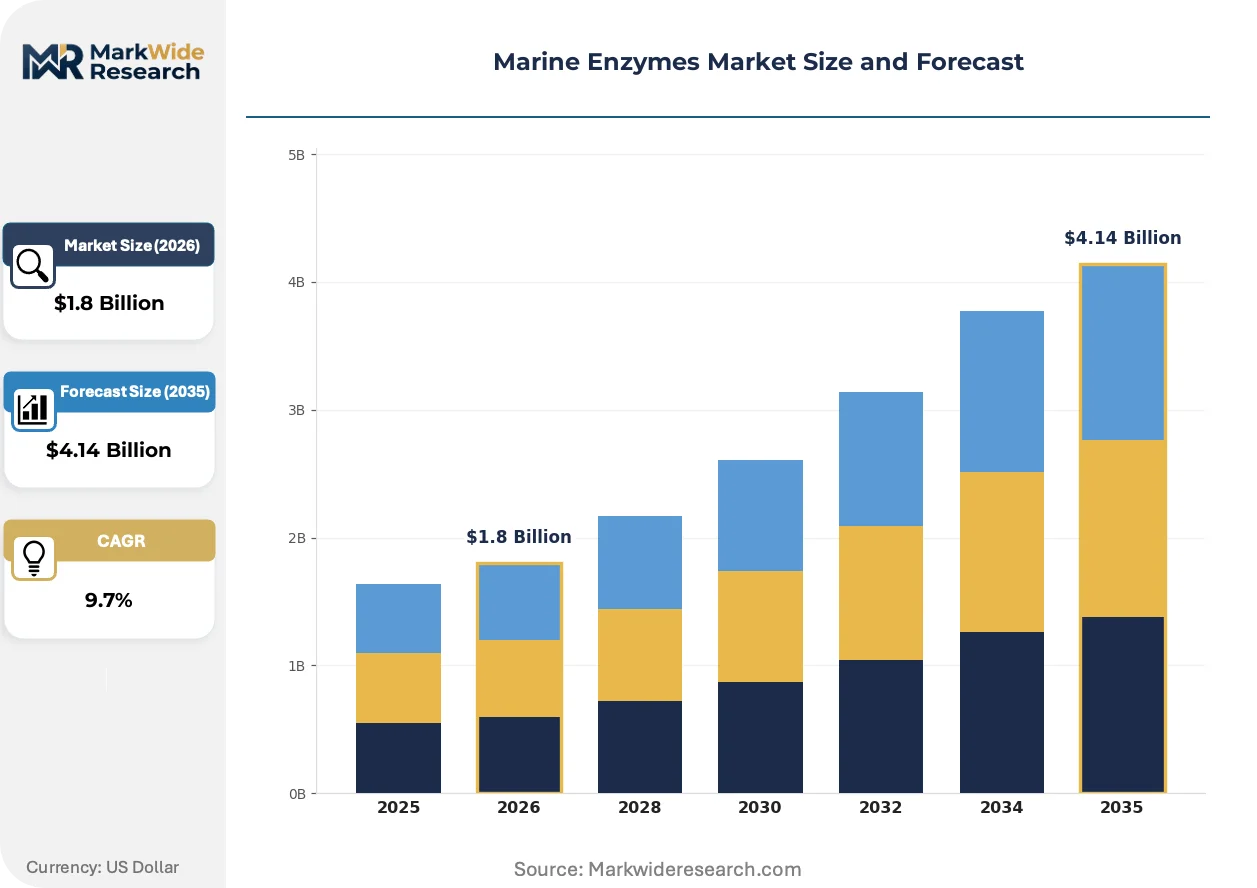
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Biodiesel Production, Food Processing, Aquaculture, Healthcare End User: Food Industry, Pharmaceutical Industry, Biofuel Industry, Cosmetic Industry Source: Algae, Marine Bacteria, Marine Fungi, Fish |
| Companies Covered | Novozymes A/S, BASF SE, Koninklijke DSM N.V., DuPont Nutrition & Biosciences, Biocon Limited, ArcticZymes Technologies ASA, Amano Enzyme Inc., Advanced Enzyme Technologies Ltd., Codexis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Enzymes Market Shifts & Advancements
Digital specimen cataloging and AI-driven protein structure prediction are compressing enzyme discovery timelines from years to months. These capabilities reshape how biocatalyst developers prioritize candidates for scale-up.
High-throughput metagenomic sequencing is digitizing the enzyme discovery pipeline. Pharmaceutical biocatalysis teams in Switzerland and Germany now screen in silico libraries before committing to wet-lab validation. This computational prioritization reduces Arctic sampling frequency by 40-60% for established enzyme classes.
EU Green Deal industrial emissions targets are accelerating REACH-registered enzyme substitutions. Chemical manufacturers in Belgium and the Netherlands face 2030 reduction deadlines for solvent-intensive processes. Marine-derived biocatalysts qualify for streamlined hazard classification under ECHA guidance.
Brewery procurement teams now specify enzyme origin and extraction method in supplier scorecards. Scandinavian craft producers reject terrestrial-sourced alternatives for marketing differentiation. This preference shift concentrates premium pricing power among Arctic-credentialed suppliers serving beverage verticals.
Marine Enzymes Market Segmentation
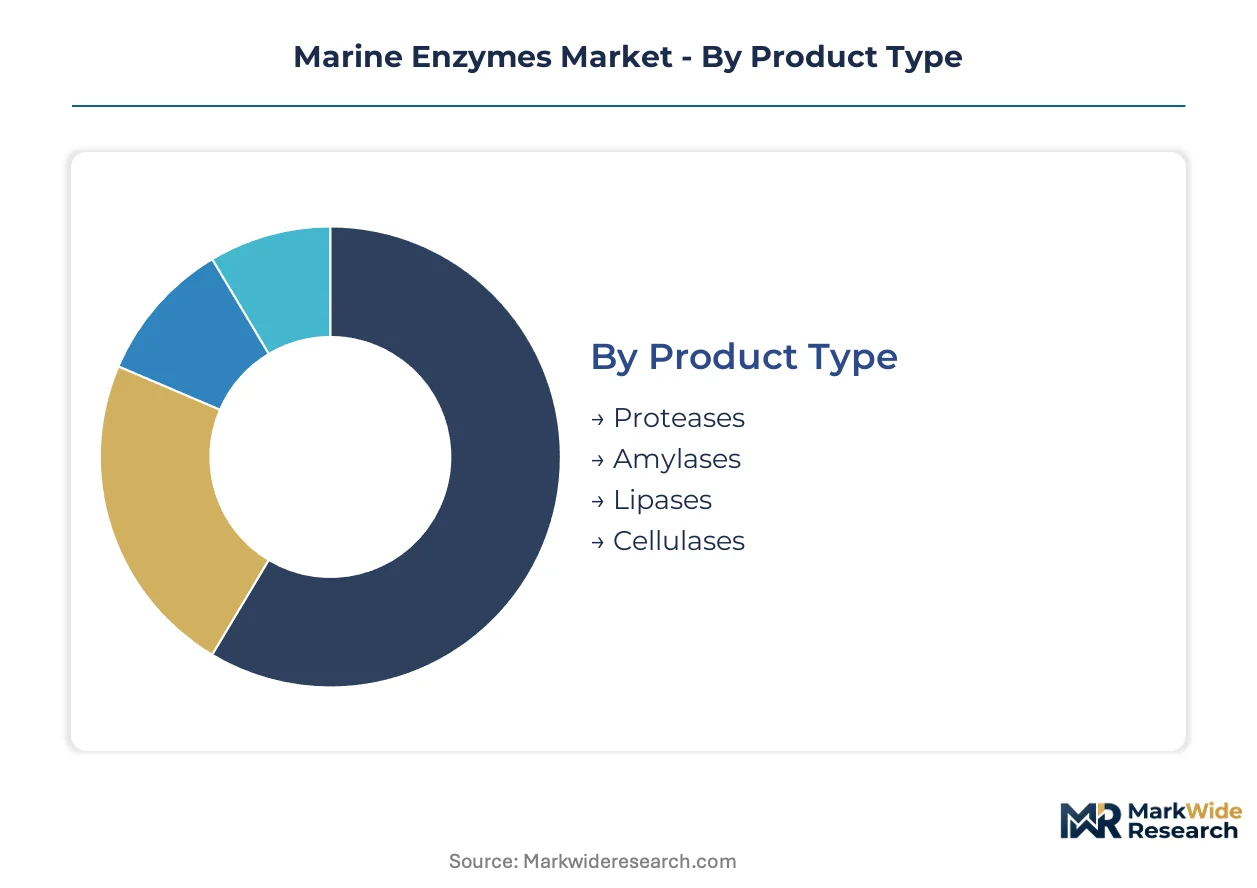
Marine enzyme segmentation reflects divergent technical requirements across temperature sensitivity, substrate specificity, and regulatory compliance burdens. Product type selection determines extraction complexity and cold-chain logistics investment. Application verticals impose distinct validation standards that reshape supplier economics.
Product Type:
Cycle times vary dramatically — lipases turn over fastest in biodiesel retrofit projects, while proteases sustain decade-long supply contracts in food processing.
- Proteases:Cold-adapted proteolytic enzymes hydrolyze peptide bonds at sub-ambient temperatures with specific activity thresholds exceeding terrestrial counterparts. Meat tenderization and dairy coagulation applications in Norway and Denmark sustain long-term procurement agreements with Arctic extraction facilities.
- Lipases:These triglyceride-cleaving biocatalysts enable enzymatic transesterification without alkaline wastewater generation. Nordic and Baltic biodiesel refiners specify cold-adapted lipase feeds for continuous-flow reactor retrofits, displacing chemical catalysts under REACH mandates.
- Amylases:Starch-degrading enzymes from psychrophilic bacteria serve brewing and textile desizing applications with reduced thermal energy input.
- Cellulases:Cellulose-hydrolyzing enzymes from deep-sea fungi target second-generation biofuel feedstock processing at moderate temperatures.
Proteases dominate installed base. Lipases are where expansion concentrates.
Application:
Cost tier stratification separates validated pharmaceutical-grade supply from commodity food-grade distribution.
- Biodiesel Production:Enzymatic transesterification eliminates caustic waste streams and reduces water consumption versus alkaline catalysis. Nordic refiners in Sweden and Finland retrofit existing infrastructure for cold-adapted lipase integration.
- Food Processing:Dairy coagulation, meat tenderization, and baking applications specify enzyme origin for marketing differentiation. Scandinavian craft producers reject terrestrial alternatives.
- Aquaculture:Feed enzyme supplementation improves nutrient digestibility in salmon and shrimp farming operations.
- Healthcare:Active pharmaceutical ingredient synthesis requires EMA-validated biocatalytic processes with 18-24 month stability dossiers. Contract manufacturers in Switzerland and Germany capture premium margins.
Food Processing anchors volume throughput. Healthcare commands margin concentration.
End User:
Customer type determines procurement sophistication — pharmaceutical buyers enforce batch documentation while biofuel operators prioritize unit economics.
- Food Industry:Brewery and dairy procurement teams now specify enzyme extraction method and Arctic provenance in supplier scorecards.
- Pharmaceutical Industry:FDA-regulated drug substance programs require biocatalytic process validation with extensive stability data. Small-batch suppliers face resource constraints for full documentation.
- Biofuel Industry:Nordic refiners adopt continuous-flow lipase reactors to meet EU Green Deal industrial emissions targets.
- Cosmetic Industry:Marine-derived enzymes support preservative-free formulation claims in premium skincare.
Food Industry sustains broadest supplier relationships. Pharmaceutical Industry filters for documentation-capable providers.
Source:
Supply concentration varies by extraction logistics — Tromsø-based operations control psychrophile access while metagenomic alternatives bypass organism dependency.
- Marine Bacteria:Psychrophilic bacterial strains from Arctic sediments yield proteases and lipases with industrial-relevant specific activity. Norwegian bioprospecting permits concentrate extraction rights among established logistics networks.
- Algae:Photosynthetic marine organisms provide thermostable enzymes with distinct glycosylation patterns for specialty applications.
- Marine Fungi:Deep-sea fungal isolates produce cellulases and xylanases for lignocellulosic biomass conversion.
- Fish:Digestive enzymes from cold-water species serve traditional food processing applications with established regulatory pathways.
Marine Bacteria dominates psychrophile supply. Algae is gaining share fastest in cosmetic and specialty chemical verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA biocatalytic process validation anchors European market access for marine enzyme suppliers. REACH green chemistry mandates accelerate enzymatic substitution across pharmaceutical and biofuel verticals. Norway's Arctic bioprospecting corridor concentrates extraction rights among established logistics networks.
Norway
Arctic psychrophile collection drives specialized enzyme supply for cold-adapted biocatalysis. The Norwegian Environment Agency processes bioprospecting permits through Tromsø-based coordination hubs. Svalbard logistics networks enable seasonal extraction windows for marine bacterial strains serving Nordic biodiesel refiners.
Germany
Pharmaceutical biocatalysis teams in Basel-adjacent facilities screen in silico enzyme libraries before wet-lab validation. EMA stability dossier requirements filter small-batch suppliers from contract manufacturing partnerships. Bavarian and Baden-Württemberg chemical clusters retrofit solvent-intensive processes with REACH-registered marine biocatalysts.
United States
FDA Generally Recognized As Safe notifications shape commercialization pathways for marine-derived food enzymes. EPA bioprospecting permit backlogs extend application queues to 8-14 months with expedited fee premiums. Pacific Northwest craft brewing clusters specify Arctic enzyme provenance in procurement scorecards.
Japan
METI biomanufacturing roadmaps designate extremophile enzymes as strategic inputs for precision fermentation platforms. Domestic biotech firms secure exclusive Arctic sourcing partnerships through technology licensing frameworks. Osaka and Tokyo-based pharmaceutical manufacturers validate biocatalytic processes for active pharmaceutical ingredient synthesis.
India
CDSCO fast-track pathways for enzymatic APIs attract contract manufacturers to marine enzyme production. PLI scheme subsidies offset fermentation infrastructure capital expenditure for domestic suppliers. Maharashtra and Gujarat pharmaceutical clusters integrate cold-adapted biocatalysts into generic drug substance programs.
Marine Enzymes Market Competitive Landscape
Capability concentration sits with specialized Arctic extraction firms; scale advantage sits with diversified fermentation platforms. The market structures around a tiered supplier base where documentation-capable providers capture pharmaceutical margins while commodity distributors serve food processing volume. Three archetypes dominate: Nordic bioprospecting specialists with territorial access rights, pan-European biocatalysis platforms with REACH registration capabilities, and Asian fermentation houses with cost-optimized production. Competitive moves center on Arctic logistics network control and EMA/FDA validation dossier accumulation.
Within the Nordic specialist tier, ArcticZymes Technologies ASA exemplifies territorial sourcing advantage through Tromsø-based operations. Novozymes A/S and BASF SE anchor the scale-driven European tier with integrated fermentation and distribution infrastructure. These three entities represent distinct competitive positions: territorial access, manufacturing scale, and regulatory navigation capability respectively.
| Leading Market Players |
|---|
| Novozymes A/S |
| BASF SE |
| Koninklijke DSM N.V. |
| DuPont Nutrition & Biosciences |
| Biocon Limited |
| ArcticZymes Technologies ASA |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies Ltd. |
| Codexis Inc. |
| Others |
Supply & Pricing Matrix
Tromsø-based extraction facilities anchor global psychrophile enzyme supply, with seasonal collection windows compressing availability and amplifying price premiums for documented Arctic-provenance biocatalysts. REACH-registered pharmaceutical-grade enzymes command substantial markups over commodity food-grade alternatives, while biodiesel refinery procurement teams negotiate volume-driven contract structures.
Pricing Analysis
Geographic price spreads widen between Nordic-sourced psychrophile enzymes and cell-free synthesis alternatives, with Arctic-provenance premiums reflecting bioprospecting permit costs and cryogenic logistics investment. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade certification levels segments buyer access, with EMA-validated batches capturing highest returns. Cost compression in technical-grade segments intensifies as synthetic biology platforms achieve comparable specific activity. Pharmaceutical manufacturers exhibit lowest price sensitivity due to biocatalytic process validation lock-in, while craft brewing procurement teams drive hard bargaining on food-grade lipase contracts.
Supply Chain Analysis
Extended payment terms from Nordic biodiesel refiners strain working capital for small-batch Arctic extraction operations, pushing suppliers toward supply-chain finance facilities anchored by pharmaceutical offtake agreements. Norway, Denmark, and Germany concentrate upstream psychrophile collection and downstream fermentation capacity. Raw material dependencies center on liquid nitrogen cryopreservation infrastructure, specialized marine bacterial culture media, and ECHA-registered protein stabilization formulations. Single-source vulnerability runs through Tromsø logistics networks during seasonal ice retreat. Distribution runs through specialized biochemical distributors serving pharmaceutical contract manufacturers and direct-to-brewery channels for food-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are opening as brewery procurement teams disaggregate from traditional chemical distributors and pharmaceutical buyers splinter between documentation-heavy and cost-optimized supplier tiers.
For Market Incumbents: Harden territorial access advantages by securing multi-year Arctic bioprospecting permits before regulatory backlogs extend further. Deepen backward integration into cryogenic logistics infrastructure to defend against cell-free synthesis platforms achieving scale. Lock in pharmaceutical contract manufacturers with exclusive EMA validation dossier partnerships that emerging competitors cannot replicate. For New Entrants and Emerging Players: Pursue direct-to-brewery distribution relationships in Scandinavia and the Pacific Northwest, bypassing established chemical distributor markups. The craft beverage segment offers lowest barrier to entry with origin-story marketing differentiation driving premium acceptance. Lead with Arctic-provenance certification and transparent extraction method documentation rather than competing on unit economics. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EMA and FDA validation timelines create durable moats around documentation-capable suppliers. Target acquisition profiles should emphasize firms with accumulated stability dossiers and established Arctic logistics networks rather than pure technology plays. The signal to watch is CDSCO fast-track pathway utilization rates, indicating whether Indian contract manufacturers can bypass traditional validation bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Arctic Bioprospecting Permit Accumulation | Multi-year extraction rights in Norwegian waters secure psychrophile supply against seasonal access constraints. |
| EMA Validation Dossier Investment | Pharmaceutical-grade documentation opens contract manufacturing partnerships with Swiss and German API producers. |
| Cryogenic Logistics Infrastructure Buildout | Liquid nitrogen cold-chain capabilities preserve enzyme activity from Tromsø collection points to downstream fermentation facilities. |
| Direct-to-Brewery Channel Development | Bypassing chemical distributor markups captures margin in Scandinavian craft beverage procurement. |
| Cell-Free Synthesis Platform Licensing | In vitro protein production hedges against Arctic harvest volatility and bioprospecting permit delays. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation platform engineers, pharmaceutical biocatalysis directors, biodiesel refinery procurement leads, and Arctic logistics coordinators and refined through secondary validation against ECHA registration databases, EPA bioprospecting permit filings, and REACH compliance guidance documents. Bottom-up enzyme production estimates triangulated against top-down pharmaceutical intermediate demand projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application vertical, end-user industry, and geographic regulatory cluster. CAGRs were derived from enzyme-specific adoption curves in biodiesel retrofit projects and pharmaceutical process validation pipelines. Forecast inputs incorporated METI biomanufacturing roadmap targets and EU Green Deal industrial emissions reduction deadlines.
Macroeconomic conditions sit as an overlay; deviation in energy costs affecting cryogenic logistics or biotechnology capital availability would shift the trajectory. Forecasts reflect documented assumptions around Arctic access continuity and regulatory validation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Americas Enzymes Market