
 Coagulation Factor IX Market | 2026-2036
Coagulation Factor IX Market Size, Share, and Industry Trends Forecast 2026-2036
Coagulation Factor IX Market Analytics
Recombinant protein expression platforms are realigning manufacturing economics away from plasma-dependent sourcing. CSL Behring leverages captive plasma collection networks across multiple geographies to sustain cost advantages in plasma-derived supply. Novo Nordisk specializes in extended half-life recombinant engineering, while Takeda anchors its position through integrated rare disease commercial infrastructure.
Coagulation Factor IX denotes a vitamin K-dependent serine protease synthesized in the liver, functioning as a zymogen that activates Factor X in the intrinsic coagulation cascade when converted to Factor IXa; recombinant variants now achieve specific activity exceeding 200 IU per milligram of protein. Plasma-derived Factor IX retains substantial share in emerging markets where cold-chain limitations and reimbursement constraints favor established fractionation products. Long-acting recombinant formulations represent the fastest-expanding segment, with subcutaneous delivery modes drawing development investment as hemophilia B management shifts toward home-based prophylaxis regimens.
FDA orphan drug designations and EMA priority medicines pathways shape clinical trial investment and label expansion strategies for developers. The EU MDR and FDA current good manufacturing practice standards enforce comparability protocols that elevate barrier costs for new recombinant entrants. Stakeholders must monitor biosimilar filing activity and gene therapy readouts, as these modalities threaten to displace chronic replacement therapy paradigms.
Market Dynamics
Gene therapy candidates for hemophilia B are compressing the addressable patient pool for chronic Factor IX replacement, forcing incumbent manufacturers to defend prophylaxis regimens through dosing convenience and access contracting before curative alternatives reach label.
Growth Catalysts
- Pediatric prophylaxis protocols:Hemophilia treatment centers in the United States now initiate prophylactic Factor IX in children under three, expanding the chronic patient base and lifetime value per individual.
- FDA accelerated approval pathways:Breakthrough therapy and orphan drug designations compress Phase III timelines for novel recombinant constructs, compressing capital-at-risk periods for developers.
- Extended half-life engineering:PEGylation and Fc-fusion technologies extend dosing intervals to fourteen days or longer, improving adherence and reducing breakthrough bleed rates in home-based settings.
Market Restraints
- Plasma supply concentration:Fractionators depend on captive collection networks in the United States and Germany, exposing plasma-derived supply to geographic sourcing risk and donor availability volatility.
- Gene therapy substitution threat:Single-dose investigational gene therapies promise functional cure, threatening to displace chronic replacement therapy in severe hemophilia B patients within the forecast window.
- Cold-chain infrastructure gaps:Emerging markets lack validated temperature-controlled distribution, limiting recombinant product penetration and preserving plasma-derived share despite inferior safety profiles.
Strategic Opportunities
- Subcutaneous delivery modes:Non-intravenous administration routes would eliminate venous access requirements and expand prophylaxis eligibility to patients with poor vein integrity.
- EMA priority medicines pathway:PRIME designation offers accelerated assessment and enhanced regulatory dialogue, enabling faster European market entry for novel constructs.
- Home infusion services:Specialty pharmacy networks can capture margin through nursing support and adherence monitoring, deepening patient lock-in beyond product supply alone.
Industry Challenges
- Comparability protocol execution:FDA current good manufacturing practice standards and EU MDR comparability requirements demand extensive analytical characterization, extending tech transfer timelines for new manufacturing sites.
- Biosimilar defense preparation:Reference product sponsors must construct patent thickets and real-world evidence programs before biosimilar entrants erode pricing power in recombinant segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coagulation Factor IX Market |
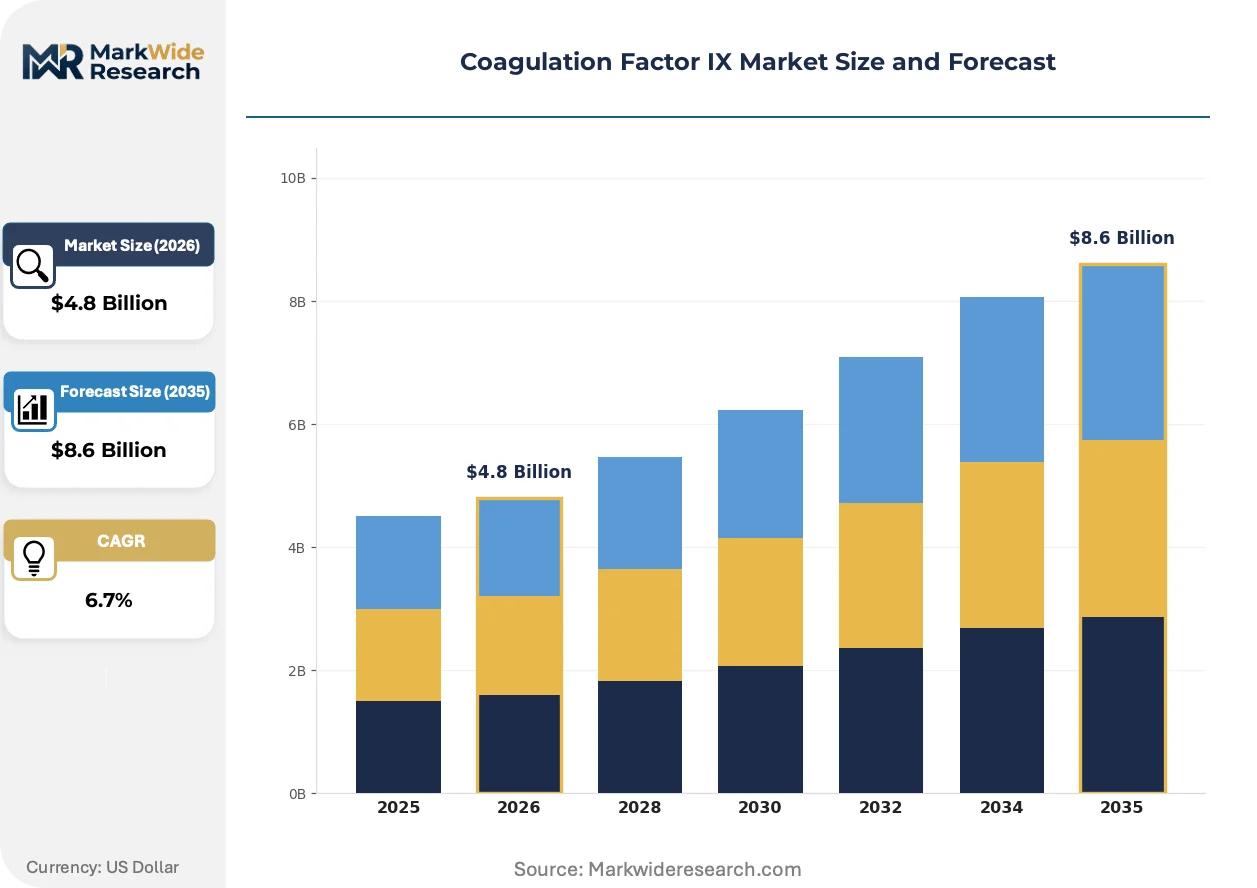
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Factor IX, Plasma-Derived Factor IX, Long-Acting Factor IX, Others Therapy Area: Hemophilia B, Surgical Bleeding, Acquired Coagulopathy, Others End User: Hospitals, Specialty Clinics, Home Care Settings, Blood Centers Delivery Mode: Intravenous, Subcutaneous, Continuous Infusion, Others |
| Companies Covered | Pfizer, CSL Behring, Grifols, Novo Nordisk, Takeda, Baxter, Bioverativ, Sanquin, Octapharma AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coagulation Factor IX Market Evolving Landscape
Bioconjugation chemistries and expression platform advances are compressing production costs while regulatory frameworks adapt to gene therapy convergence. Three developments are restructuring competitive positioning.
Site-specific PEGylation and albumin-binding domain fusions are rewriting dosing economics for prophylactic regimens. Pediatric hemophilia treatment centers in the United States and Germany are adopting fourteen-day interval products for naive patients, compressing annual infusion burdens from 104 to 26 events. This technology is rewriting adherence benchmarks and reducing central venous access device dependency in young patients.
The EU Medical Device Regulation and FDA's evolving gene therapy guidance are creating divergent approval pathways for curative versus replacement modalities. EMA's PRIME scheme now prioritizes hemophilia B gene therapy candidates, compressing assessment timelines while maintaining safety surveillance standards. Developers are responding with adaptive trial designs that bridge registrational requirements across both jurisdictions.
Comprehensive care models are unbundling product procurement from clinical services. Hemophilia treatment centers in the United States now contract separately for Factor IX supply, nursing infusion support, and outcomes monitoring, fragmenting purchasing authority across pharmacy directors and hematology chiefs. This shift is most visible in states with carve-out Medicaid managed care arrangements where pharmacy benefit managers intermediate access decisions.
Coagulation Factor IX Market Segmentation
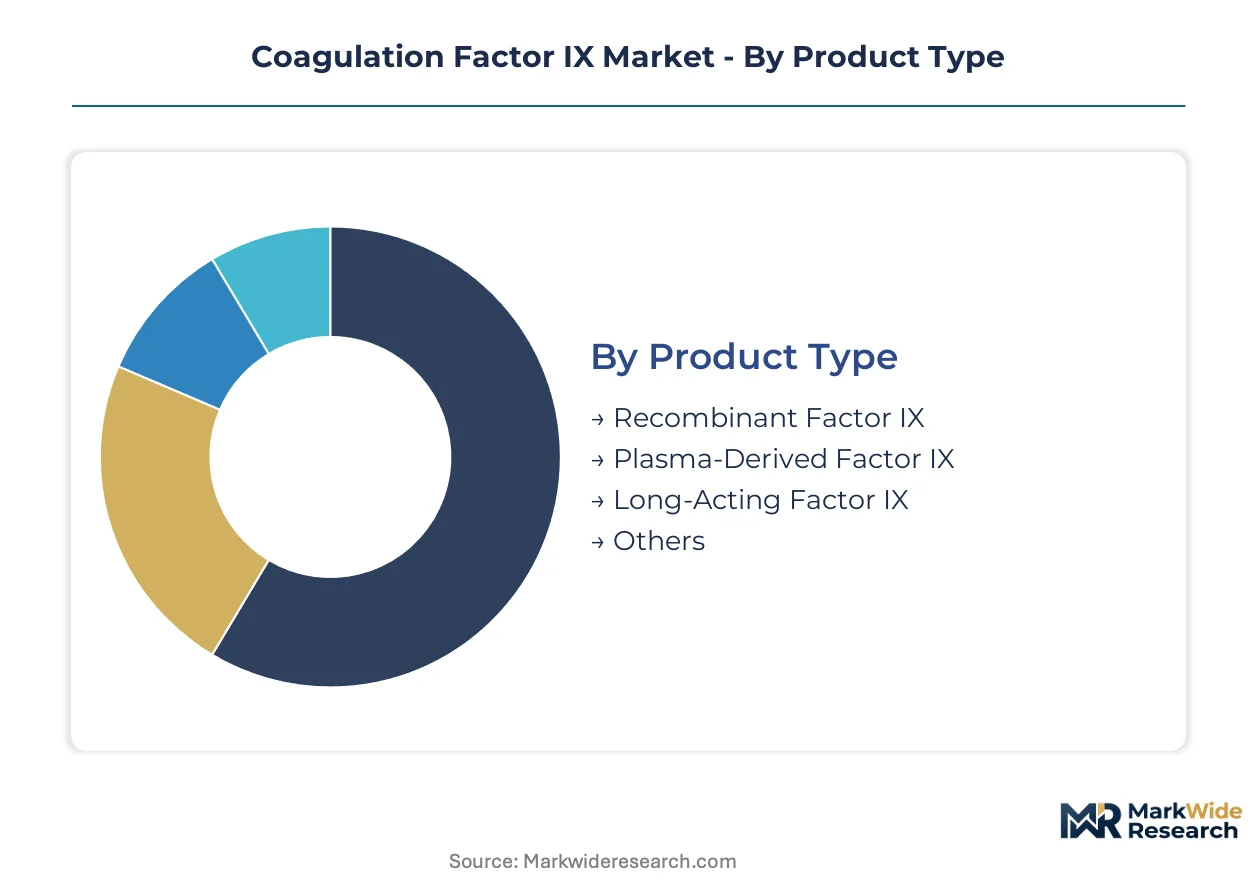
Coagulation Factor IX procurement patterns fragment across four critical dimensions: molecular origin dictates manufacturing scale and margin structure, clinical indication determines dosing intensity and reimbursement tier, care setting shapes cold-chain requirements, and administration route governs patient adherence and access barriers.
Product Type:
Supply concentration in recombinant manufacturing is compressing plasma-derived economics and accelerating bioconjugation investment.
- Recombinant Factor IX:Chinese hamster ovary cell lines produce high-purity zymogen with specific activity exceeding 200 IU per milligram. Demand concentrates in United States hemophilia treatment centers where FDA orphan drug exclusivity sustains premium positioning against biosimilar threat.
- Plasma-Derived Factor IX:Recovered from pooled human plasma through Cohn fractionation and viral inactivation protocols. Emerging markets in Brazil and India preserve this segment's relevance where cold-chain limitations and national blood service infrastructure favor established fractionation products.
- Long-Acting Factor IX:PEGylation and Fc-fusion technologies extend half-life to enable 14-day dosing intervals.
- Others:Includes investigational gene therapy adjuncts and novel fusion constructs in early clinical development.
Today's leader: Recombinant Factor IX. Tomorrow's challenger: Long-Acting Factor IX.
Therapy Area:
Cost tier stratification separates chronic prophylaxis regimens from acute intervention pricing.
- Hemophilia B:Congenital Factor IX deficiency requiring lifelong replacement therapy. Pediatric prophylaxis protocols in Germany and the United States now initiate treatment before age three, expanding the chronic patient base and lifetime therapy value.
- Surgical Bleeding:Perioperative hemostatic support for patients with mild hemophilia B or acquired coagulopathy. Orthopedic and cardiovascular surgical suites in tertiary hospitals drive intermittent high-volume demand.
- Acquired Coagulopathy:Factor IX depletion secondary to liver disease, vitamin K antagonism, or massive transfusion.
- Others:Rare indications including specific factor inhibitors and obstetric hemorrhage protocols.
Prophylaxis in hemophilia B commands the steepest expansion trajectory. Surgical applications face pricing pressure from bundled payment models.
End User:
Volume concentration is shifting from institutional procurement toward home-based distribution channels.
- Hospitals:Acute bleeding management and surgical prophylaxis in emergency departments and operating theaters. United States academic medical centers maintain centralized pharmacy control over high-cost clotting factor inventory.
- Specialty Clinics:Hemophilia treatment centers providing comprehensive care coordination and infusion training. German hemophilia centers integrate pharmacy dispensing with nursing support under single-roof reimbursement.
- Home Care Settings:Patient self-infusion and family-administered prophylaxis eliminating travel burden.
- Blood Centers:Plasma collection and fractionation facilities with captive product distribution.
Institutional buyers still anchor volume. Home care channels are climbing the fastest as prophylaxis protocols mature.
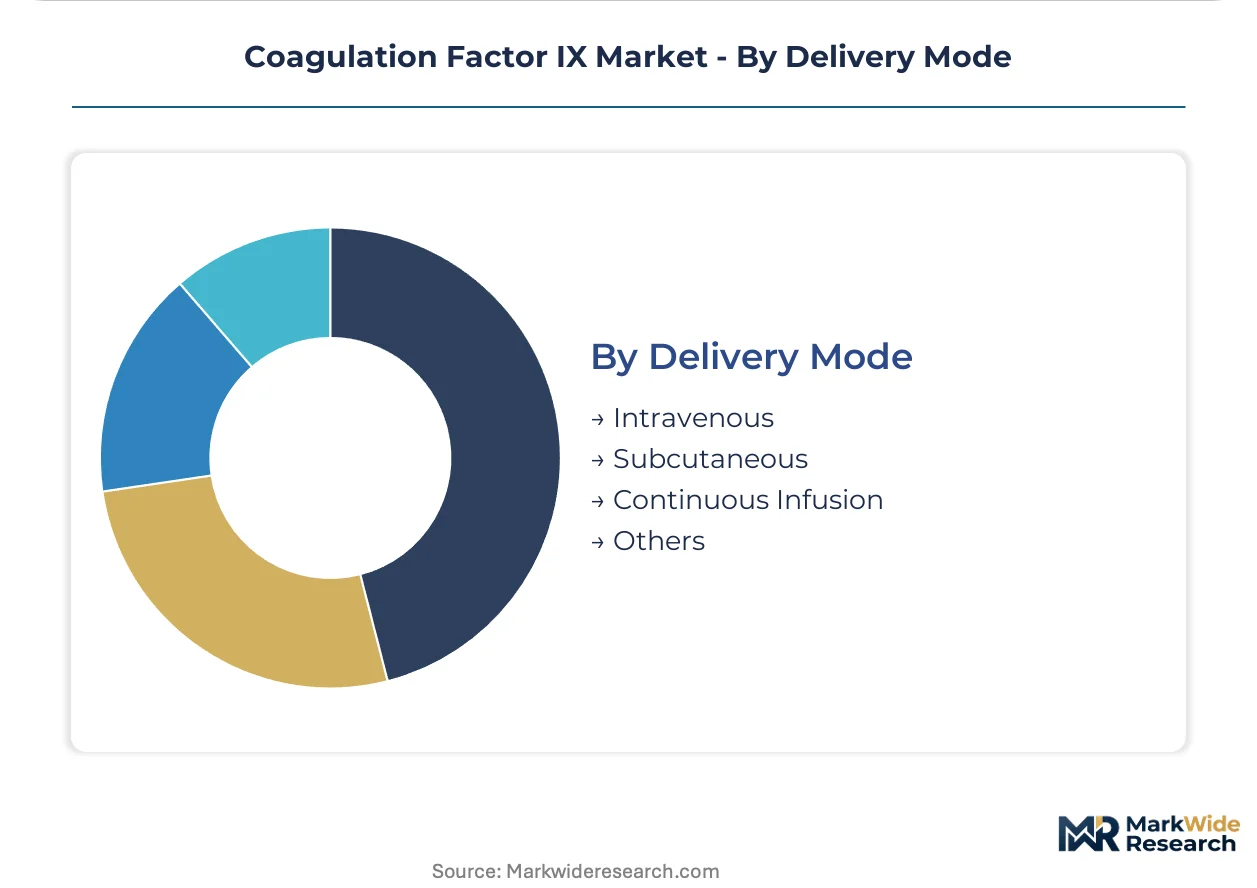
Delivery Mode:
Application requirements are forcing innovation beyond intravenous administration toward patient-centered alternatives.
- Intravenous:Standard peripheral or central venous access for bolus infusion. United States pediatric hematology practices report central venous access device dependency in 40% of severe hemophilia B patients under twelve.
- Subcutaneous:Investigational administration routes eliminating venous access requirements. Novo Nordisk and other developers are advancing subcutaneous formulations to expand prophylaxis eligibility for patients with poor vein integrity.
- Continuous Infusion:Postoperative and trauma settings requiring stable Factor IX levels.
- Others:Includes implantable pump systems and depot injection technologies in preclinical evaluation.
Intravenous delivery retains procedural dominance. Subcutaneous modes represent the most contested innovation frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hemophilia treatment centers in the United States anchor global Factor IX procurement volume through integrated specialty pharmacy networks and comprehensive care reimbursement models.
United States
FDA accelerated approval pathways and breakthrough therapy designations compress development timelines for novel recombinant constructs. Pediatric prophylaxis protocols now initiate treatment before age three, expanding the chronic patient base. The Greater Boston cluster concentrates gene therapy research and recombinant manufacturing investment.
Germany
EMA priority medicines pathways and integrated hemophilia treatment center reimbursement sustain market access for extended half-life products. National health insurance covers fourteen-day dosing intervals for naive patients. The Munich-Frankfurt corridor anchors plasma fractionation capacity and recombinant bioprocessing infrastructure.
Japan
PMDA orphan drug incentives and national hemophilia registry data accelerate post-market surveillance for novel therapies. Aging hemophilia populations drive demand for home infusion convenience. The Kansai region hosts plasma-derived manufacturing and distribution hubs serving East Asian markets.
United Kingdom
NHS England specialized commissioning frameworks and NICE technology appraisals govern access to premium-priced recombinant formulations. Gene therapy evaluation programs threaten chronic replacement volumes. The Oxford-Cambridge arc concentrates early-stage bioconjugation research and clinical trial networks.
Brazil
ANVISA regulatory pathways and national blood service infrastructure preserve plasma-derived product share against cold-chain limitations. Public procurement through the Ministry of Health dominates volume allocation. São Paulo state anchors fractionation partnerships and hemophilia treatment center density.
Coagulation Factor IX Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent manufacturers defend prophylaxis regimens against gene therapy substitution. The market structure concentrates around plasma fractionation conglomerates, recombinant bioprocessing specialists, and integrated rare disease commercializers. Three archetypes define positioning: captive plasma collectors sustaining cost advantages, half-life engineering specialists rewriting dosing economics, and gene therapy developers threatening replacement paradigms. M&A activity and strategic partnerships concentrate manufacturing scale and distribution access.
Among plasma-derived and recombinant incumbents, CSL Behring, Novo Nordisk, and Takeda occupy positions across the value chain. CSL Behring represents the captive plasma collection archetype with geographic sourcing networks. Novo Nordisk exemplifies half-life engineering specialization through bioconjugation platforms. Takeda anchors integrated rare disease commercial infrastructure spanning multiple hemophilia product generations.
| Leading Market Players |
|---|
| Pfizer |
| CSL Behring |
| Grifols |
| Novo Nordisk |
| Takeda |
| Baxter |
| Bioverativ |
| Sanquin |
| Octapharma AG |
| Others |
Value Network & Pricing Analysis
Bioprocessing engineer concentration in the Greater Boston corridor anchors labor-cost differentials that widen spreads between premium recombinant formulations and standard plasma-derived alternatives. Cold-chain logistics specialists command wage premiums that concentrate in United States and German distribution hubs, feeding into tiered procurement economics across hemophilia treatment centers.
Pricing Analysis
Input-cost pass-through from plasma collection economics and recombinant bioprocessing infrastructure shapes tiered pricing separates extended half-life constructs from standard replacement products. Price differentiation rests on FDA orphan drug exclusivity status and EMA PRIME designation tier, with certified cold-chain handling adding geographic delivery cost premiums. Cost compression in plasma-derived segments is intensifying because biosimilar filing activity accelerates, while recombinant premium tiers show pricing softness reflecting gene therapy substitution threat. Pediatric hemophilia treatment centers exhibit highest price sensitivity due to lifetime volume contracting, whereas academic medical centers with centralized pharmacy control demonstrate lowest sensitivity through bundled procurement authority.
Supply Chain Analysis
Single-source vulnerability sits with captive plasma collection networks concentrated in the United States and Germany, where CSL Behring and Grifols anchor fractionation capacity. Raw material dependencies include pooled human plasma, Chinese hamster ovary cell culture media, and PEGylation reagents for half-life extension engineering. Tariff exposure on bioprocessing equipment imports from Switzerland and Singapore threatens manufacturing scale-up timelines for new recombinant entrants. Distribution runs through specialty pharmacy networks in the United States and integrated hemophilia treatment center pharmacies in Germany, with home infusion services fragmenting last-mile delivery economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
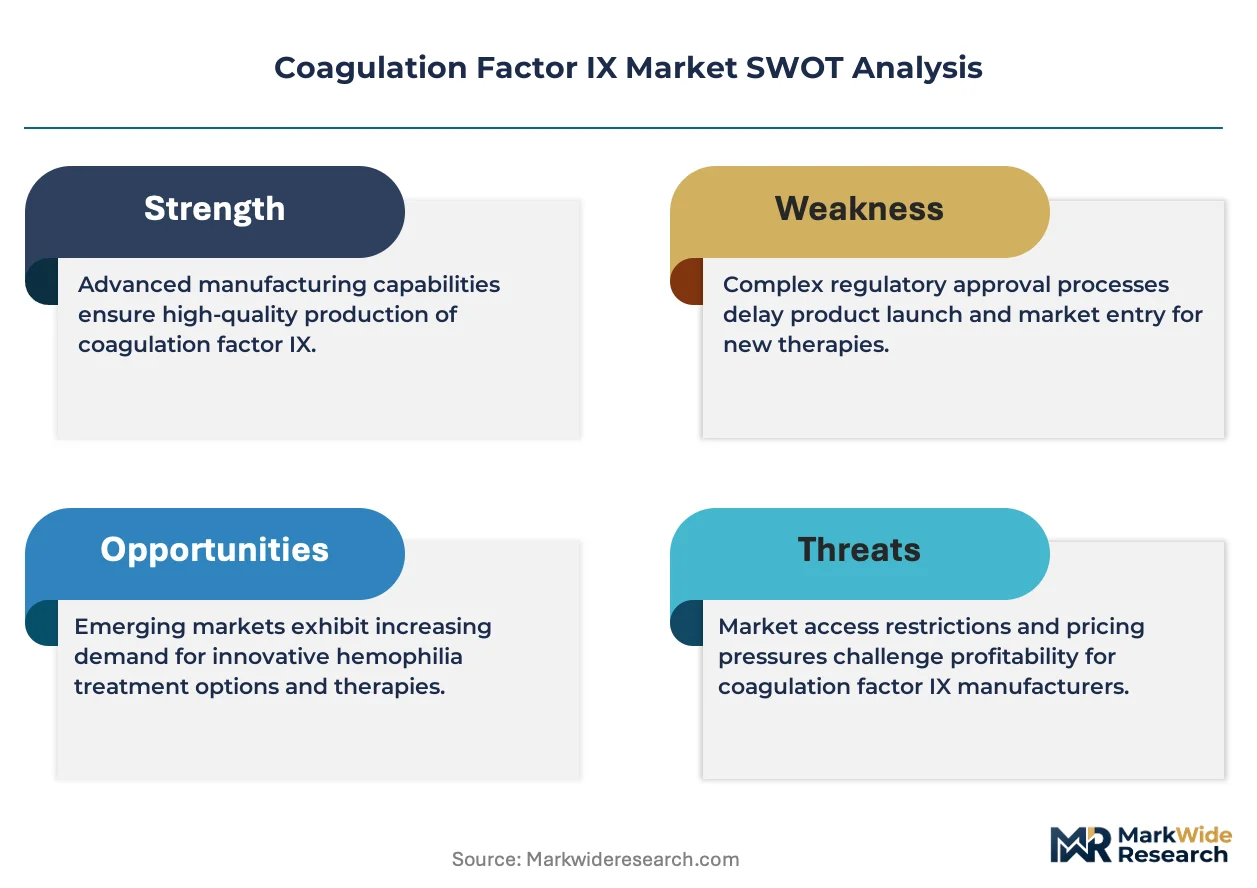
Margin expansion in Coagulation Factor IX procurement concentrates in extended half-life recombinant tiers, where PEGylation and Fc-fusion technologies compress annual infusion burdens and justify premium positioning against standard replacement products.
For Market Incumbents: To counter gene therapy substitution threat, CSL Behring and Takeda should deepen patient lock-in through home infusion service integration and outcomes-based contracting with United States hemophilia treatment centers. Patent thickets around bioconjugation chemistries and real-world evidence programs for pediatric prophylaxis adherence represent critical defensive levers before biosimilar entrants erode recombinant pricing power. For New Entrants and Emerging Players: Capture subcutaneous delivery white space in patients with poor vein integrity, where Novo Nordisk's investigational formulations have not yet secured regulatory exclusivity. Brazil and India offer the most penetrable geographies given cold-chain limitations that preserve plasma-derived share despite inferior safety profiles. A go-to-market angle through national blood service partnerships in emerging markets bypasses specialty pharmacy network gatekeeping. For Investors and Strategic Acquirers: Plasma fractionation conglomerates are the most active acquirer in this space, seeking recombinant bioprocessing capabilities to hedge gene therapy displacement risk. Five-to-ten year viability hinges on successful defense of prophylaxis regimens against curative alternatives. The signal to watch is FDA approval velocity for hemophilia B gene therapy candidates, which would compress addressable patient pools for chronic replacement therapy.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase III timelines for novel recombinant constructs. |
| Manufacturing Scale-Up | Chinese hamster ovary cell line expansion in Greater Boston anchors recombinant supply security. |
| Pipeline Diversification | Subcutaneous formulation advancement hedges against intravenous delivery commoditization. |
| Licensing Agreement | Albumin-binding domain fusion technology access extends half-life engineering capabilities. |
| Reimbursement Strategy | Medicaid carve-out contracting in United States states fragments purchasing authority favorably. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hemophilia treatment center directors, specialty pharmacy procurement managers, regulatory affairs leads at plasma fractionators, and payer access specialists with secondary validation against FDA orphan drug filings, EMA PRIME designations, ClinicalTrials.gov gene therapy readouts, and hemophilia patient registry data. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Comparable-period anchoring to historical prophylaxis adoption curves and gene therapy clinical milestone timelines structured the forecast framework across the projection horizon. Segmentation dimensions modeled include molecular origin, therapy area, care setting, and administration route, with regional regulatory cluster differentiation for United States, German, and Japanese market access patterns. CAGRs derived from dosing interval expansion rates and pediatric protocol penetration curves, incorporating bioconjugation technology adoption and cold-chain infrastructure development as industry-specific forecast inputs.
Gene therapy approval velocity, biosimilar launch timing, and plasma supply concentration shocks are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding prophylaxis protocol expansion and reimbursement tier stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Global Branded Generics Market